
 Pillow Market | 2026-2036
Pillow Market Size, Share, and Industry Trends Forecast 2026-2036
Pillow Market Outlook
Asset-light licensing and private-label manufacturing is tilting competitive dynamics toward brands that outsource production while retaining customer relationships. Serta Simmons Bedding LLC leverages its licensed factory network to sustain broad retail shelf presence without capital-heavy vertical assets. Tempur Sealy International anchors its position through proprietary memory foam formulations that command specialty-store placement. Bedgear competes on performance-driven product architecture, targeting athletic recovery positioning that differentiates its assortment from commodity alternatives.
A pillow is a cushioned support device, typically encased in woven textile covers and filled with materials such as viscoelastic polyurethane foam, natural latex, waterfowl down, or blown polyester fiber, engineered to maintain cervical alignment during sleep or rest. The product serves commercial purposes spanning residential sleep support, travel portability, interior design accentuation, and clinical therapeutic intervention. Memory foam and latex categories command premium price tiers due to density specifications and durability testing protocols, while polyester-filled units occupy mass-market volume leadership through lower unit economics. The hospitality customer segment generates concentrated bulk orders with standardized specifications, whereas healthcare facilities demand antimicrobial-treated covers and hypoallergenic fills that carry specialized certification burdens.
The United States Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1632 that govern residential bedding combustion resistance, while OEKO-TEX and CertiPUR-US operate as voluntary certification frameworks that shape commercial procurement eligibility across North American and European supply contracts. The European Union REACH regulation restricts chemical substances in textile treatments, compelling reformulation of flame retardants and dye processes for export-compliant production. Stakeholders must monitor how evolving state-level extended producer responsibility frameworks in California and New York reshape end-of-life collection obligations and material recovery economics.
Market Dynamics
Certification mandates from OEKO-TEX and CertiPUR-US are compressing supplier eligibility for hospitality and healthcare procurement, filtering uncertified manufacturers from commercial tenders while concentrating volume among compliant producers.
Growth Catalysts
- Hospitality bedding refresh cycles:North American hotel chains are compressing replacement timelines for premium sleep products, generating concentrated bulk orders with standardized specifications that favor certified suppliers.
- Memory foam density innovations:Viscoelastic polyurethane formulations with enhanced cervical alignment properties are commanding specialty retail placement and attach-rate economics with direct-to-consumer mattress brands.
- Extended producer responsibility frameworks:California and New York state-level regulations are mandating end-of-life collection obligations, creating compliant recycling infrastructure that unlocks circular material sourcing.
Market Restraints
- Down and feather input volatility:Waterfowl supply concentration in specific Eastern European and Asian sourcing regions creates price instability for natural fill categories.
- REACH chemical reformulation costs:The European Union's restriction on textile flame retardants and dye processes forces export-compliant production line changes that burden mid-tier manufacturers.
- Polyester fiber substitution pressure:Blown polyester fills occupy mass-market volume leadership, compressing margin structures for producers unable to differentiate on performance specifications.
Strategic Opportunities
- Athletic recovery positioning:Performance-driven product architecture targeting temperature regulation and moisture-wicking properties opens specialty sporting goods distribution.
- Antimicrobial healthcare specifications:Clinical therapeutic intervention applications demand hypoallergenic fills and treated covers with specialized certification burdens that premium suppliers can capture.
- Private-label manufacturing consolidation:Asset-light licensing models allow brands to outsource production while retaining customer relationships, creating white space for certified contract manufacturers.
Industry Challenges
- CertiPUR-US testing timeline compression:Voluntary certification frameworks require extended durability and emissions testing protocols that delay product launches and tie up working capital.
- Flammability standard reconciliation:The United States Consumer Product Safety Commission's 16 CFR Part 1632 combustion resistance requirements differ from EU textile safety frameworks, forcing dual compliance tracks for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pillow Market |
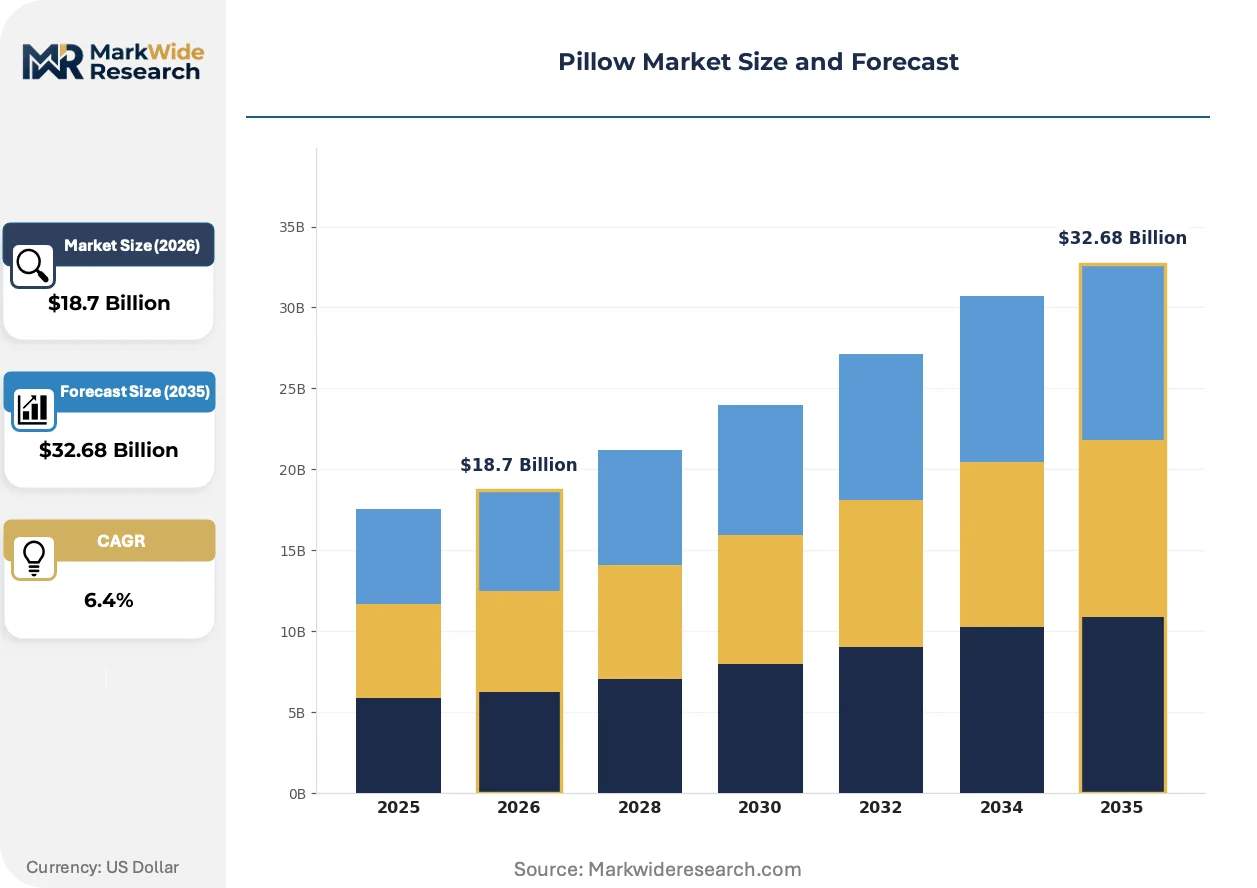
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Latex, Down, Polyester Use Case: Bed Pillows, Travel Pillows, Decorative Pillows, Therapeutic Pillows Customer Type: Retail Consumers, Hospitality Industry, Healthcare Facilities, Corporate Clients Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Serta Simmons Bedding LLC, Bedgear, Tempur Sealy International, Casper, Malouf, Purple Innovation LLC, MyPillow, Brooklinen, Sleep Number Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pillow Market Strategic Shifts
Sleep technology convergence with biometric monitoring and climate-responsive materials is redefining product architecture, while regulatory chemical restrictions and procurement centralization reshape competitive access.
Sensor-embedded pillows with pressure mapping and sleep stage detection capabilities are digitizing the residential sleep support category. Hospitality procurement teams at select North American hotel chains are piloting these units for guest wellness programming. This convergence of textile and electronics supply chains is compressing development timelines while raising firmware integration complexity for traditional foam converters.
REACH regulation amendments targeting persistent organic pollutants in textile treatments are compelling reformulation of flame retardant chemistries across EU-bound production. Manufacturers serving European hospitality contracts must validate alternative barrier technologies or face tender disqualification. Natural latex and wool fill categories gain relative positioning as inherently fire-resistant alternatives that reduce chemical dependency.
Direct procurement relationships between mattress brands and certified foam producers are disintermediating traditional wholesale distribution. Hospitality procurement teams now source standardized pillow specifications through consolidated national contracts rather than regional bedding distributors. This channel compression is most visible in United States markets where captive attach-rate economics dominate the premium residential segment.
Pillow Market Segmentation
Pillow procurement patterns diverge sharply across end-use contexts, with hospitality bulk contracts demanding standardized durability specifications while retail consumers prioritize ergonomic customization. Certification requirements and distribution economics create distinct competitive arenas that reshape supplier positioning.
Product Type:
Mature foam technologies anchor commercial volume while emerging natural alternatives capture premium positioning through sustainability credentials.
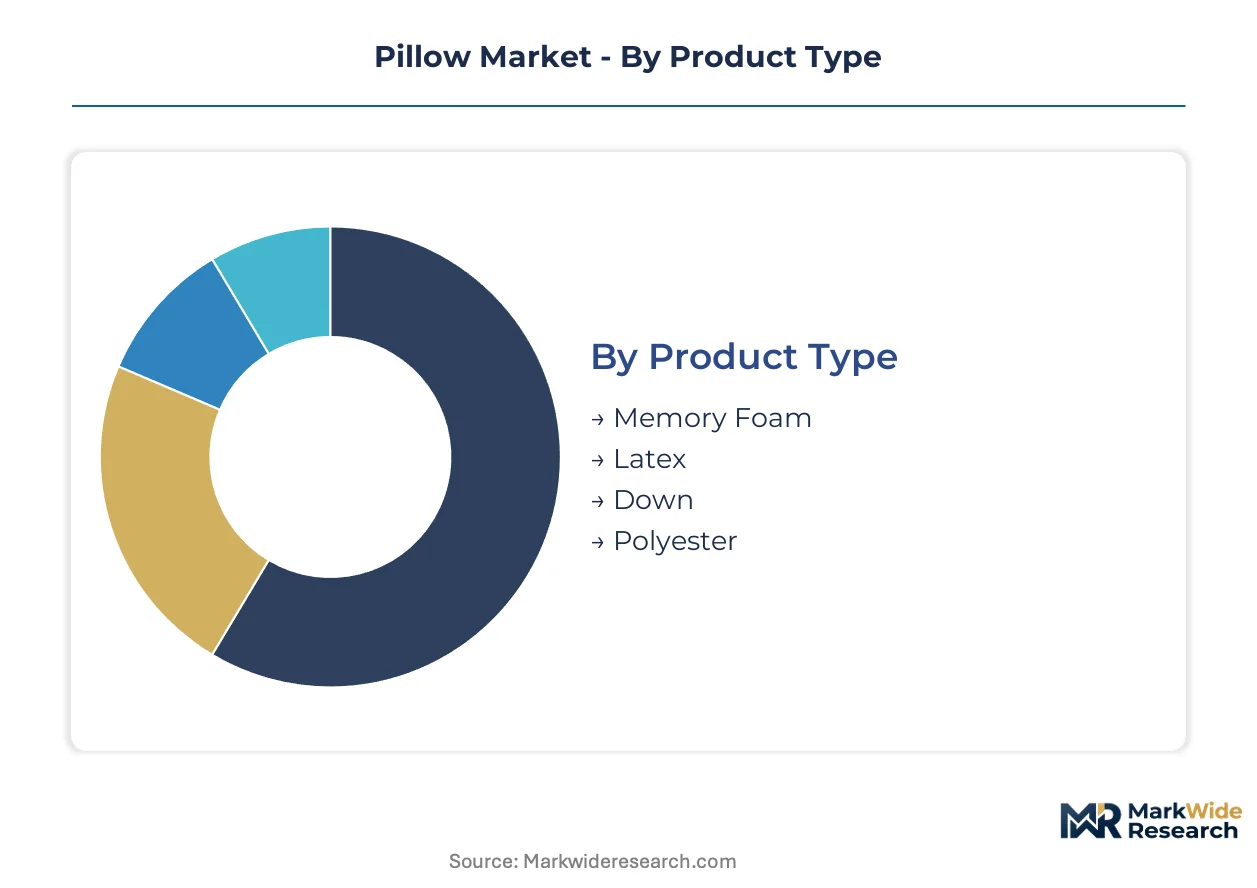
- Memory Foam:Viscoelastic polyurethane formulations with density specifications between 3-5 pounds per cubic foot dominate specialty retail and direct-to-consumer mattress attach-rate programs. United States hospitality procurement teams specify CertiPUR-US certified units for standardized refresh cycles across premium hotel chains.
- Latex:Natural rubber sap derivatives and synthetic styrene-butadiene blends offer inherent antimicrobial properties and fire resistance that reduce chemical treatment burdens under REACH regulation amendments. European hospitality contracts increasingly favor latex for EU Green Deal compliance positioning.
- Down:Waterfowl plumage fills command luxury residential price tiers despite sourcing concentration risks in Eastern European supply regions.
- Polyester:Blown polyethylene terephthalate fiber occupies mass-market volume leadership through lower unit economics and machine-washable durability.
Polyester retains volume leadership; memory foam holds the steepest expansion curve.
Use Case:
Application-driven specifications separate clinical therapeutic requirements from discretionary interior design purchases, creating tiered certification burdens.
- Bed Pillows:Standardized sleep support devices with cervical alignment engineering dominate residential and hospitality procurement. United States direct-to-consumer mattress brands drive attach-rate economics through bundled pillow-mattress offerings.
- Travel Pillows:Compact, compressible designs with neck stabilization architecture serve airline and rail passenger segments. Memory foam and inflatable hybrid constructions capture premium positioning in specialty sporting goods distribution.
- Decorative Pillows:Woven textile covers with aesthetic-focused fills serve interior design accentuation without ergonomic performance requirements.
- Therapeutic Pillows:Clinical-grade units with pressure redistribution and cervical traction specifications demand FDA registration for medical device claims in United States healthcare facilities.
Bed pillows retain volume leadership; therapeutic pillows hold the steepest expansion curve.
Customer Type:
Procurement centralization patterns concentrate volume among institutional buyers while fragmenting retail demand across channel-specific preferences.
- Retail Consumers:Individual purchasers selecting through e-commerce platforms, specialty sleep retailers, and mass merchandisers. Direct-to-consumer mattress brands have built captive pillow economics that reshape United States residential purchasing patterns.
- Hospitality Industry:North American hotel chains generate concentrated bulk orders with standardized specifications and compressed replacement timelines. Procurement teams require OEKO-TEX or CertiPUR-US certification as tender eligibility filters.
- Healthcare Facilities:Hospitals and long-term care centers demand antimicrobial-treated covers, hypoallergenic fills, and pressure-relief engineering that carry specialized regulatory burdens.
- Corporate Clients:Employee wellness programs and corporate gifting channels represent emerging volume with logo customization and bulk pricing requirements.
Retail consumers retain volume leadership; healthcare facilities hold the steepest expansion curve.
Distribution Channel:
Channel compression is disintermediating traditional wholesale relationships as direct procurement and digital platforms reshape supplier access.
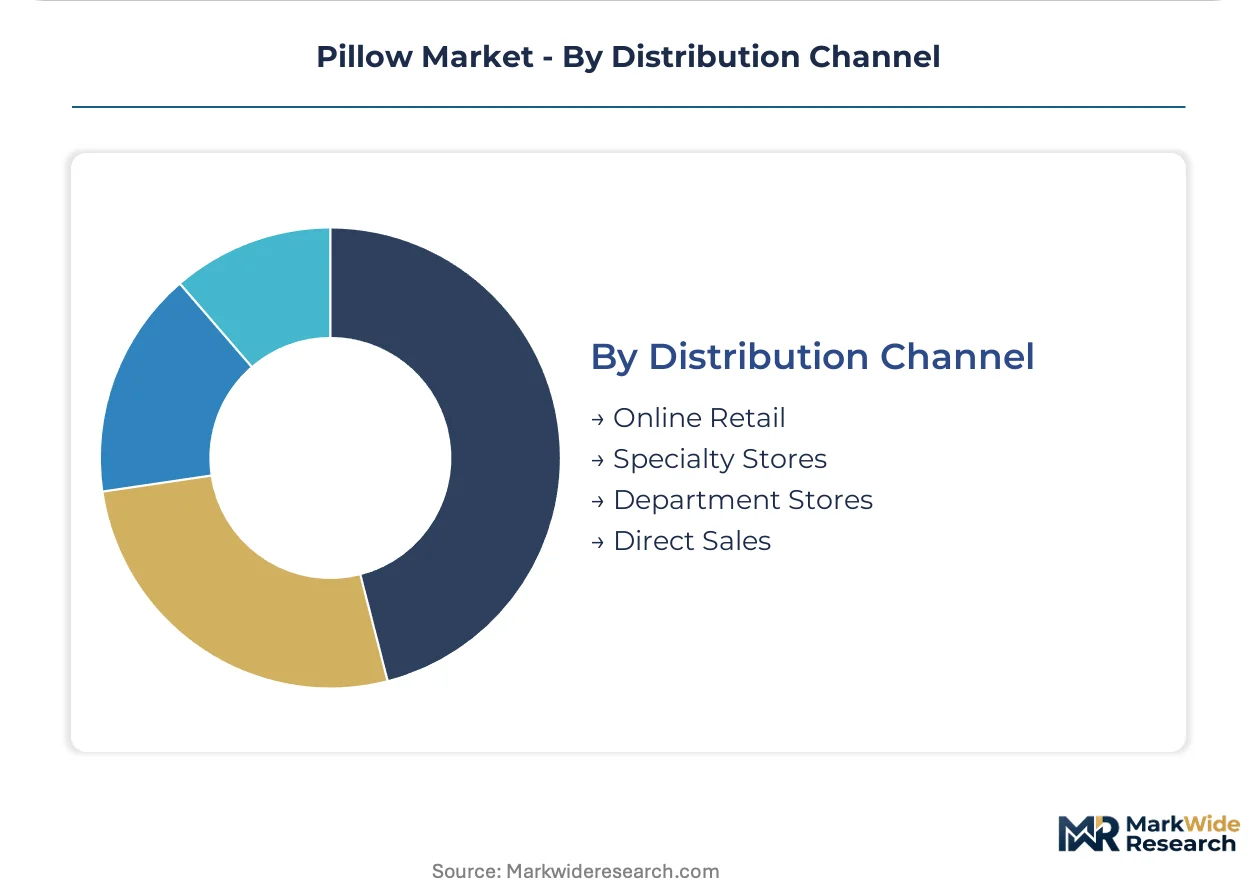
- Online Retail:E-commerce platforms and direct-to-consumer brand websites capture residential volume through mattress-pillow bundle economics and subscription replacement models. United States digital native brands dominate this channel through performance marketing and sleep trial guarantees.
- Specialty Stores:Sleep-focused retailers and furniture galleries provide tactile evaluation environments for premium foam and latex categories. Tempur Sealy International and comparable brands anchor shelf placement through proprietary formulation exclusivity.
- Department Stores:Multi-category retailers serve mass-market polyester and mid-tier memory foam demand through seasonal promotional calendars.
- Direct Sales:Hospitality and healthcare procurement teams increasingly source through manufacturer-direct national contracts, bypassing regional bedding distributors.
Online retail retains volume leadership; direct sales hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in China and Vietnam supply bulk contract orders to hospitality chains across North America and Europe, while domestic consumption in developed markets tilts toward premium certified products. Import dependency for natural fills creates sourcing vulnerabilities in Eastern European waterfowl supply regions.
United States
Direct-to-consumer mattress brands drive captive pillow attach-rate economics through bundled sleep system offerings. The Consumer Product Safety Commission enforces 16 CFR Part 1632 flammability standards that govern residential bedding combustion resistance. Manufacturing clusters in North Carolina and Georgia concentrate foam conversion capacity for hospitality contract fulfillment.
Germany
Specialty retailers anchor premium latex and memory foam distribution through tactile evaluation environments in urban centers. ECHA administers REACH regulation amendments that restrict persistent organic pollutants in textile flame retardant treatments. Industrial concentration in Baden-Württemberg houses precision foam fabricators serving EU hospitality procurement.
China
Private-label contract manufacturers supply standardized polyester and memory foam units to global hospitality chains at volume price points. MIIT oversees GB standards compliance for textile safety in domestic and export production. The Yangtze River Delta clustering around Shanghai integrates foam molding, textile finishing, and logistics infrastructure for consolidated export capacity.
India
Domestic hospitality expansion and rising residential disposable income expand addressable market for certified sleep products. BIS mandates product safety standards for textile and foam materials in consumer goods. Manufacturing activity in Gujarat and Tamil Nadu scales blown fiber and basic foam conversion for price-sensitive regional demand.
Vietnam
Textile and foam assembly operations capture contract manufacturing migration from higher-cost Asian supply bases. The Ministry of Industry and Trade coordinates export promotion programs for bedding and home textile categories. Industrial zones in Binh Duong and Dong Nai provinces concentrate cut-and-sew operations with Korean and Taiwanese invested foam supply chains.
Pillow Market Competitive Environment
On the supply side, the industry is bifurcated between asset-light brand licensors and vertically integrated foam compounders. Consolidation pressure concentrates volume among certified suppliers while fragmenting long-tail private-label capacity. Three archetypes dominate: licensed factory networks, proprietary formulation specialists, and direct-to-consumer digital natives. Competitive moves center on certification acquisition for hospitality eligibility and strategic partnerships with mattress brands for attach-rate economics.
Within the licensed manufacturing tier, Serta Simmons Bedding LLC represents the distributed factory model, while Tempur Sealy International exemplifies proprietary formulation anchoring. Among digital-native entrants, Casper occupies a position in direct-to-consumer bundle economics. These three anchors illustrate the structural divergence between capital-light brand management and integrated material science capabilities.
| Leading Market Players |
|---|
| Serta Simmons Bedding LLC |
| Bedgear |
| Tempur Sealy International |
| Casper |
| Malouf |
| Purple Innovation LLC |
| MyPillow |
| Brooklinen |
| Sleep Number Corporation |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta foam compounders and textile finishers anchor upstream supply concentration, translating into margin capture at the certified manufacturer tier where OEKO-TEX and CertiPUR-US eligibility gates commercial access.
Pricing Analysis
Hospitality procurement teams anchor contract-based long-term offtake structures that stratify across certification grade and volume scale. Three-tier pricing separates premium memory foam with CertiPUR-US validation from standard polyester fills and economy blended fiber alternatives. Cost compression in mass-market polyester tiers is intensifying because blown fiber substitution pressure erodes differentiation leverage. Individual retail consumers exhibit highest price sensitivity, while healthcare facilities demonstrate lowest sensitivity due to specialized antimicrobial specifications.
Supply Chain Analysis
Polyurethane feedstock and natural latex sap draw from concentrated petrochemical complexes in China, South Korea, and Thailand, with waterfowl down sourcing tethered to Eastern European and Asian agricultural regions. Viscoelastic foam formulations, woven textile covers, and antimicrobial treatment chemicals constitute critical component dependencies. Single-source vulnerability in waterfowl plumage supply creates input volatility for luxury fill categories. Distribution runs through direct national contracts with hospitality chains and direct-to-consumer digital platforms that disintermediate regional bedding distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pillow procurement is shifting toward subscription replacement models and sleep trial guarantees that attach recurring service revenue to hardware transactions, with mattress-pillow bundle economics expanding faster than standalone unit sales.
For Market Incumbents: Pre-empt certification displacement by accelerating CertiPUR-US and OEKO-TEX portfolio coverage before tender eligibility hardens, while consolidating regional foam conversion capacity in North Carolina and Georgia to defend against private-label contract manufacturer encroachment. For New Entrants and Emerging Players: Build out athletic recovery positioning through temperature-regulating product architecture that opens specialty sporting goods distribution, targeting the penetrable wellness-conscious residential segment with direct-to-consumer performance marketing and biometric-enabled sleep trial guarantees. For Investors and Strategic Acquirers: Capital is best deployed toward certified contract manufacturers with established hospitality procurement relationships and compliant recycling infrastructure for extended producer responsibility frameworks, with long-term viability hinging on circular material sourcing capabilities; monitor state-level collection mandate enforcement velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | CertiPUR-US and OEKO-TEX acquisition unlocks hospitality tender eligibility and filters uncertified competitors. |
| Direct-to-Consumer Platform Launch | Mattress-pillow bundle economics with sleep trial guarantees reshape United States residential purchasing patterns. |
| Circular Recycling Infrastructure Buildout | California and New York extended producer responsibility compliance creates compliant material recovery sourcing. |
| Athletic Recovery Product Line Extension | Temperature regulation and moisture-wicking specifications open specialty sporting goods distribution channels. |
| Healthcare Antimicrobial Specification Investment | Hypoallergenic fills and treated covers capture clinical therapeutic intervention procurement with premium pricing. |
Study Parameters
A spread of perspectives from hospitality procurement directors, foam conversion plant managers, textile finishing specialists, and direct-to-consumer brand executives converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC 10-K filings, and hospitality contract award databases. Bottom-up unit economics triangulated against top-down category spending estimates across the analysis window.
Demand-supply balance modeling anchored projections, with segmentation across product type, use case, customer archetype, and distribution channel informing elasticity assumptions. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and procurement centralization trends. Forecast inputs incorporated hospitality refresh cycle compression rates and certification adoption curves among contract manufacturers.
Practitioners should monitor REACH amendment enforcement, state-level extended producer responsibility rollout, and hospitality procurement consolidation velocity for early signals of forecast revision. Cross-checking against customs trade data and hospitality capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Stained Glass Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Removable Wallpaper Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
Pillow Cases Market