
 Mattress Topper Market | 2026-2036
Mattress Topper Market Size, Share, and Industry Trends Forecast 2026-2036
Mattress Topper Market Intelligence
Open-cell foam engineering with phase-change material integration is reconfiguring thermal regulation standards across the mattress topper category. Tempur-Pedic leverages proprietary viscoelastic formulations to sustain premium positioning in memory foam tiers. Saatva anchors its competitive stance through domestic manufacturing scale and direct-to-consumer channel control. Nolah differentiates via specialized pressure-relief architectures targeting side-sleeping demographics.
A mattress topper is a removable bedding layer, typically two to five inches thick, constructed from memory foam, latex, gel-infused polymers, or feather fill to modify mattress firmness, temperature, or support profiles. Manufacturers employ molded foam casting, Dunlop or Talalay latex processing, and quilted baffling to achieve density ratings between 2.5 and 5.5 pounds per cubic foot for durability and conformance. Memory foam variants command the largest revenue share due to established consumer recognition and lower production complexity, while latex segments capture disproportionate margin pools through certified organic supply chains and extended lifespan claims. The hospitality end-user segment shows the fastest structural expansion as hotel chains standardize sleep quality as a brand differentiator, with three-inch and four-inch thickness configurations dominating commercial procurement specifications.
The U.S. Consumer Product Safety Commission enforces 16 CFR Part 1633 open-flame mattress standards that extend to topper products, compelling foam suppliers to reformulate with intumescent barriers or inherent fire-resistant fibers. California's SB 1019 requires disclosure of flame retardant chemical content, directly steering R&D investment toward natural wool and silica-based alternatives. Stakeholders must monitor evolving state chemical restriction cascades and third-party certification fragmentation to avoid compliance cost asymmetries that could reshape sourcing geography and material cost structures.
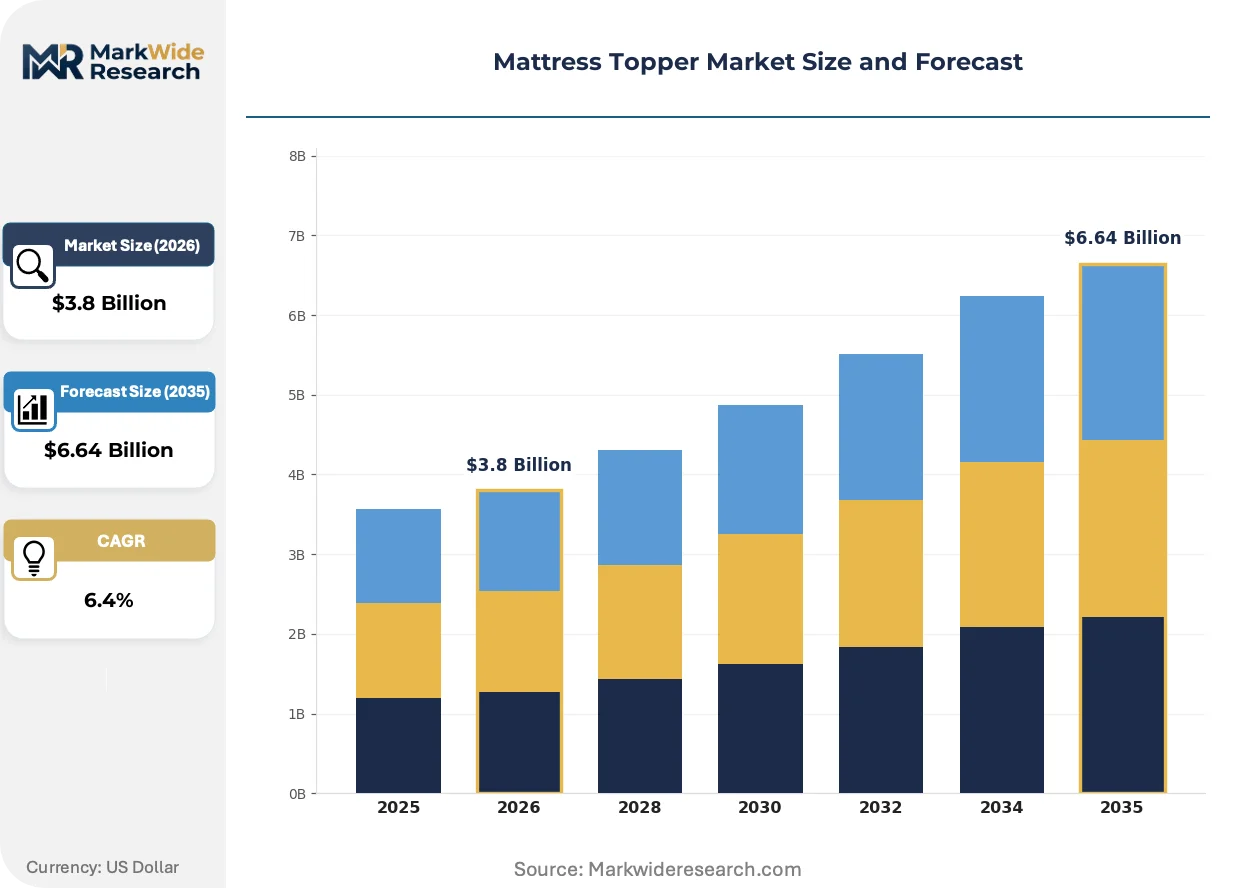
Market Dynamics
California's SB 1019 chemical disclosure mandate is compressing formulation cycles across the mattress topper supply base, forcing foam suppliers to abandon legacy flame retardant chemistries before adjacent states adopt parallel statutes.
Growth Catalysts
- California mattress recycling mandates:Extended producer responsibility laws in California divert end-of-life products from landfills, creating certified feedstock demand for recycled foam content in new topper production.
- Phase-change material integration:Open-cell foam engineering with thermal-regulating polymers addresses sleep-temperature complaints that drive product returns in warm-climate markets.
- Hospitality procurement standardization:Hotel chains operating 500+ properties now specify three-inch and four-inch thickness configurations as brand-defining sleep quality investments.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate price swings compress margin predictability for memory foam manufacturers operating on quarterly procurement contracts.
- Natural latex supply concentration:Plantation capacity constraints in Sri Lanka and Thailand limit certified organic latex availability below hospitality sector procurement timelines.
- 16 CFR Part 1633 compliance costs:Intumescent barrier integration adds material cost layers that price entry-tier products out of mass-market retail channels.
Strategic Opportunities
- Direct-to-consumer subscription models:Sleep trial programs with automated replacement cycles capture lifetime value from mattress topper buyers who historically treated purchases as one-time events.
- EU Ecodesign for Sustainable Products Regulation:Digital product passports for textile products create first-mover positioning for manufacturers with established recycled content documentation systems.
- Healthcare channel penetration:Pressure-relief specifications aligned with Medicare durable medical equipment reimbursement codes open institutional procurement pathways for therapeutic foam architectures.
Industry Challenges
- Certified organic supply chain verification:GOTS and GOLS audit backlogs extend certification timelines by 8-14 months, delaying product launches for latex-focused brands.
- Cross-border chemical restriction tracking:State-level disclosure laws fragmenting across Oregon, Vermont, and Maine require parallel formulation documentation systems that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mattress Topper Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Latex, Feather, Gel Thickness: 2 Inch, 3 Inch, 4 Inch, 5 Inch End User: Residential, Hospitality, Healthcare, RV Distribution Channel: Online, Offline, Retail, Direct Sales |
| Companies Covered | Nolah, Coop Sleep Goods, Tempur-Pedic, Saatva, Avocado, Helix, ViscoSoft, Lucid, Linenspa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mattress Topper Market Strategic Shifts & Innovations
Material science convergence with sleep-tracking hardware is redefining product value propositions beyond passive comfort layers toward biometric-responsive sleep environments.
Sensor-embedded foam toppers with pressure-mapping arrays and thermal feedback loops are digitizing sleep data collection for hospitality chains and wellness-focused consumers. Marriott International and Hyatt properties pilot these systems in premium suites to differentiate guest experiences through personalized climate adjustment. The technology is digitizing how mattress toppers function within broader smart bedroom ecosystems, compressing the boundary between furniture and health monitoring devices.
The U.S. Consumer Product Safety Commission's enforcement posture on 16 CFR Part 1633 open-flame standards is intensifying reformulation investments across foam suppliers serving the North American market. Manufacturers must now validate intumescent barrier performance through third-party testing protocols that add 6-8 weeks to product development cycles. California-based suppliers face the most acute compliance pressure as SB 1019 disclosure requirements layer onto federal flammability mandates.
Buyer concentration among online mattress retailers is consolidating procurement power and compressing supplier margins through exclusive private-label arrangements. Casper, Purple, and direct-to-consumer platforms now specify custom density profiles and branded packaging that lock out independent foam converters from premium tier placement. This channel consolidation is most visible in the United States, where e-commerce penetration in bedding exceeds 35% and continues displacing traditional furniture store distribution.
Mattress Topper Market Segmentation
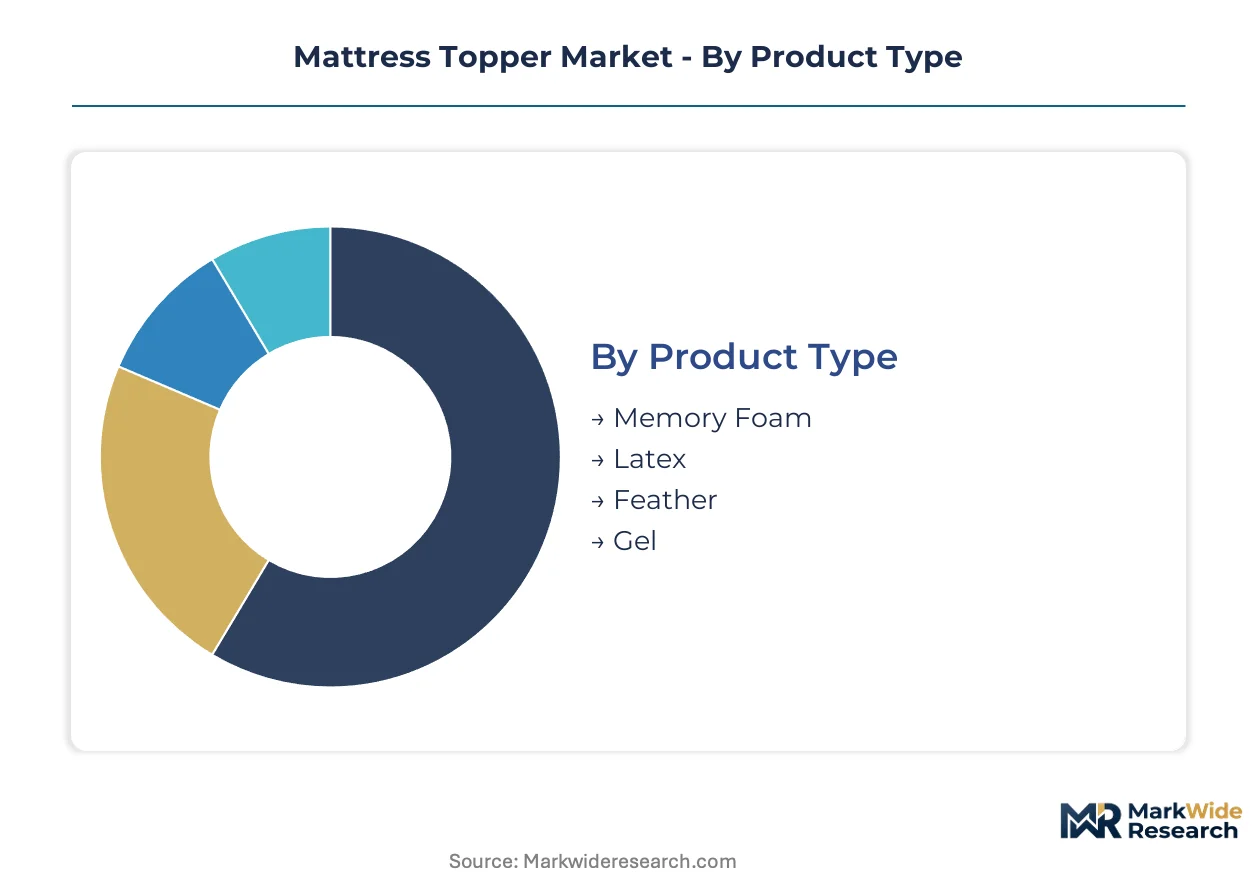
Mattress topper segmentation reveals how material science, dimensional specifications, and procurement channel choices create distinct margin architectures. Understanding these divisions exposes where formulation investments concentrate and which buyer categories drive pricing power.
Product Type:
Mature viscoelastic formulations dominate commercial throughput while emerging natural alternatives command premium positioning through certification scarcity.
- Memory Foam:Viscoelastic polyurethane formulations with density ratings between 2.5 and 5.5 pounds per cubic foot deliver pressure-point relief through temperature-responsive cell structure. Residential buyers in warm-climate U.S. states generate concentrated demand for open-cell variants with phase-change material integration. California's SB 1019 disclosure mandates accelerate reformulation timelines for flame-retardant compliance.
- Latex:Dunlop and Talalay processing methods yield distinct resilience profiles from rubber tree sap, with certified organic supply chains anchored in Sri Lankan and Thai plantation networks. Hospitality procurement teams in California prioritize GOLS-certified natural latex for extended-lifecycle properties aligned with sustainability mandates. Plantation capacity constraints limit availability below commercial procurement timelines.
- Feather:Down and feather fill from poultry processing byproducts delivers compressible loft through quilted baffling construction.
- Gel:Thermally conductive polymer beads or swirled gel layers integrated into foam matrices address heat retention complaints in memory foam alternatives.
Memory Foam handles the majority of throughput; Latex is the fastest mover on share.
Thickness:
Cost tier stratification separates entry-level comfort adjustments from structural support modifications that justify premium pricing.
- 2 Inch:Minimal profile toppers provide surface-level firmness modification for mattresses in satisfactory structural condition. Budget-conscious residential buyers in the United States select this specification for rental properties and guest room applications where capital investment is constrained.
- 3 Inch:Mid-profile construction balances conformance depth with fitted sheet compatibility, emerging as the hospitality industry standard for brand-differentiating sleep quality investments.
- 4 Inch:Substantial support layer effectively rehabilitates aging mattresses or substantially alters firmness profiles for therapeutic applications.
- 5 Inch:Maximum thickness approaches mattress replacement functionality, requiring deep-pocket sheet specifications and platform bed compatibility.
3 Inch configurations anchor hospitality procurement volume; 4 Inch specifications are climbing the fastest as therapeutic positioning expands.
End User:
Application-driven demand splits between replacement-cycle residential purchases and institutional procurement with standardized specifications.
- Residential:Individual consumers purchasing through retail or direct channels for personal sleep environment modification. California buyers demonstrate disproportionate preference for certified organic materials driven by mattress recycling mandates and chemical disclosure awareness.
- Hospitality:Hotel chains operating 500+ properties specify three-inch and four-inch configurations as brand-defining sleep quality investments, with procurement standardization compressing supplier margins through volume commitments.
- Healthcare:Pressure-relief specifications aligned with therapeutic outcomes serve institutional and home-care settings.
- RV:Compact dimensional requirements and weight constraints define specialized product development for recreational vehicle manufacturers and aftermarket suppliers.
Residential channels sustain baseline volume; Hospitality procurement is expanding most quickly on absolute dollar contribution.
Distribution Channel:
Customer type and geography concentration determine where margin capture concentrates versus where price transparency compresses profitability.
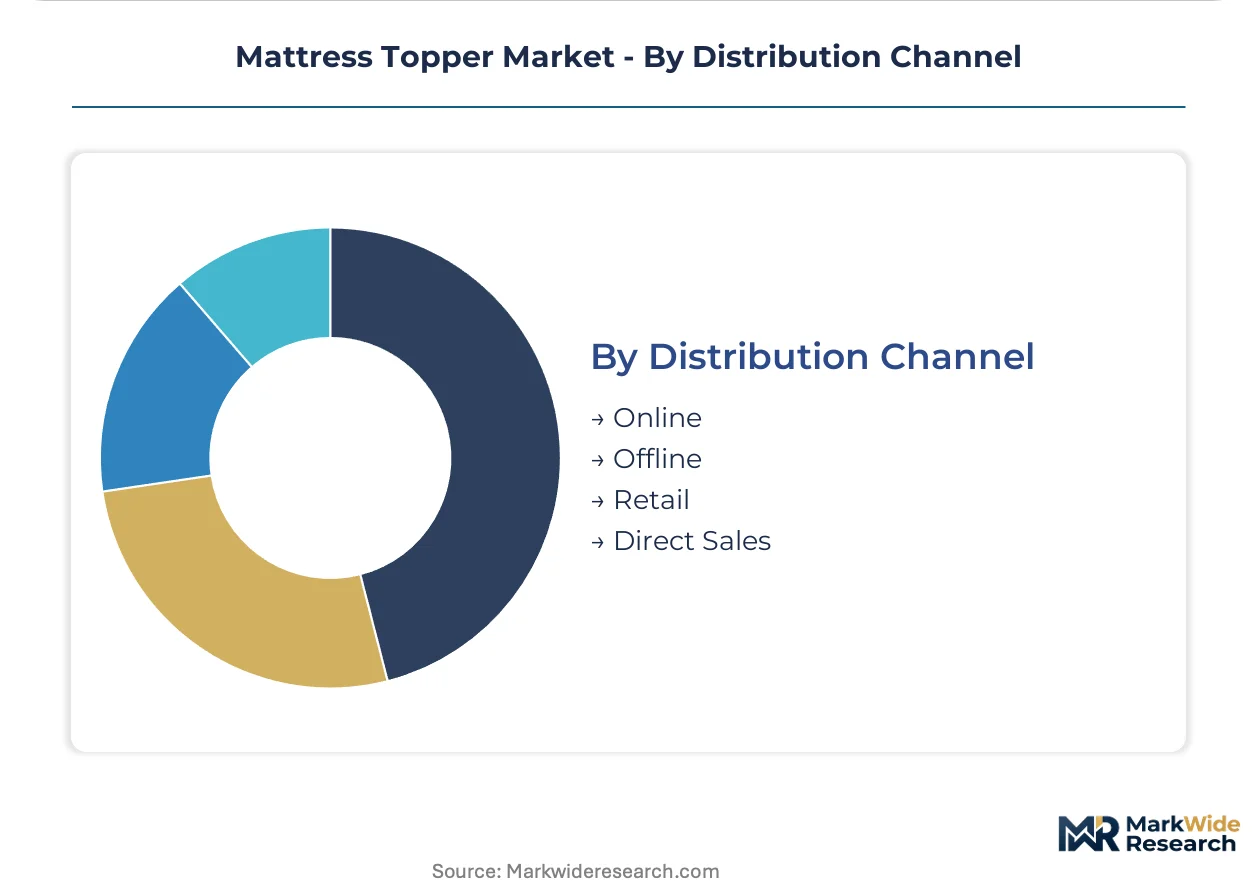
- Online:Direct-to-consumer platforms and marketplace aggregators disintermediate traditional retail markups while enabling sleep trial programs that extend customer lifetime value through automated replacement cycles.
- Offline:Brick-and-mortar furniture stores and bedding specialty retailers maintain tactile evaluation advantages for high-consideration purchases.
- Retail:Big-box and department store channels emphasize promotional pricing and seasonal inventory turnover.
- Direct Sales:Manufacturer-owned showrooms and white-glove delivery services capture full margin on premium-tier configurations.
Online channels command the steepest expansion trajectory; Offline retail retains importance for demographic segments requiring physical evaluation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Sri Lankan latex plantations supply certified organic feedstock to California hospitality chains and German eco-conscious retailers. Vietnam and China export processed foam components to North American direct-to-consumer brands. This trade-flow structure concentrates premium raw material sourcing in Southeast Asia while finished goods manufacturing clusters near major consumer markets.
United States
California hospitality chains drive certified organic latex procurement for guest satisfaction programs. The U.S. Consumer Product Safety Commission enforces 16 CFR Part 1633 open-flame standards that compel foam reformulation with intumescent barriers. Los Angeles and San Francisco anchor the nation's largest mattress recycling infrastructure under SB 1019 mandates.
Germany
EU Ecodesign for Sustainable Products Regulation drives digital product passport adoption among foam converters serving Central European retailers. ECHA REACH compliance requirements restrict legacy flame retardant chemistries in polyurethane formulations. Bavarian industrial clusters around Munich specialize in precision-molded viscoelastic components for automotive and bedding crossover applications.
China
Domestic mattress brands source polyol and isocyanate feedstocks from integrated petrochemical complexes in the Yangtze River Delta. MIIT industrial standards govern foam density specifications for export-bound production. Guangdong Province hosts the largest concentration of gel-infusion processing facilities serving Southeast Asian and Australian markets.
Vietnam
Rubber plantation expansion in the Central Highlands feeds natural latex processing for GOLS-certified export grades. The country's national industrial development framework prioritizes textile and foam sector foreign direct investment. Ho Chi Minh City anchors logistics corridors connecting plantation zones to Port of Cai Mep container terminals.
Thailand
World's largest natural latex exporter maintains plantation-to-processing vertical integration for certified organic supply chains. The country's national agricultural standards body oversees rubber quality grading for international certification compliance. Surat Thani Province concentrates Dunlop and Talalay processing facilities serving European and North American premium brands.
Mattress Topper Market Key Industry Players
On the supply side, the industry is bifurcated between mass-market foam converters and certified organic specialists competing for hospitality procurement contracts. Consolidation pressure concentrates among online mattress retailers specifying custom density profiles and branded packaging. Three archetypes dominate: domestic manufacturing scale players, direct-to-consumer platform operators, and certified organic supply chain integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as brands secure plantation relationships and recycling infrastructure access.
Within the certified organic tier, Avocado exemplifies supply chain integration from Sri Lankan plantation networks to California finishing facilities. Tempur-Pedic occupies a position as the archetypal proprietary formulation specialist leveraging viscoelastic chemistry investments. Saatva represents domestic manufacturing scale players controlling direct-to-consumer channel economics. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Nolah |
| Coop Sleep Goods |
| Tempur-Pedic |
| Saatva |
| Avocado |
| Helix |
| ViscoSoft |
| Lucid |
| Linenspa |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese polyol processing facilities is compressing raw material quotations while simultaneously eroding pricing power for North American foam converters locked into quarterly procurement contracts. This utilization imbalance forces suppliers to absorb margin compression or risk volume loss to vertically integrated competitors with captive feedstock access.
Pricing Analysis
Technology-generation pricing gaps separate legacy viscoelastic formulations from phase-change material integrated architectures and emerging sensor-embedded biometric-responsive systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal-regulation performance, with GOLS-certified organic latex commanding substantial premiums over conventional polyurethane. Pricing pressure stems from petrochemical feedstock volatility and buyer concentration among online mattress retailers specifying custom density profiles. Mass-market residential buyers exhibit highest price sensitivity, while hospitality procurement teams prioritize lifecycle cost over unit economics.
Supply Chain Analysis
Export-control regimes on advanced polymer processing equipment limit technology transfer to Vietnamese and Indonesian foam manufacturing investments, constraining regional capacity expansion. Raw material flows draw from Thai and Sri Lankan rubber plantations, Chinese Yangtze River Delta petrochemical complexes, and German Bavarian precision-molding clusters. Supply chain risk centers on single-source vulnerability for certified organic latex feedstock amid plantation capacity constraints. Distribution runs through direct-to-consumer platforms disintermediating traditional furniture retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mattress topper category is reconfiguring as a service-attach opportunity where automated replacement cycles and sleep trial subscriptions capture lifetime value exceeding hardware margins. Recurring revenue layers in subscription-based topper replacement programs are expanding faster than one-time transactional sales.
For Market Incumbents: Entrench market position through backward integration into Sri Lankan and Thai plantation networks securing GOLS-certified organic latex feedstock against supply concentration risks. Expand domestic finishing capacity in California to compress logistics costs and align with SB 1019 disclosure mandates. Prioritize phase-change material R&D investments to differentiate thermal-regulation performance as open-cell foam engineering becomes table stakes. For New Entrants and Emerging Players: Pursue white-space opportunities in healthcare channel penetration where pressure-relief specifications aligned with Medicare durable medical equipment reimbursement codes remain underdeveloped. Target the therapeutic application segment with 4-inch thickness configurations for aging mattress rehabilitation use cases. Deploy direct-to-consumer subscription models with automated replacement cycles to bypass established retail gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across direct-to-consumer platform operations as customer acquisition costs compress and lifetime value expands through subscription attach. Long-term viability favors acquirers of certified organic supply chain integrators with established plantation relationships and recycling infrastructure access. Monitor EU Ecodesign for Sustainable Products Regulation implementation timelines as inflection indicators for digital product passport competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Supply Chain Integration | GOLS and GOTS certification backlogs create scarcity value for verified plantation relationships. |
| Direct-to-Consumer Subscription Launch | Sleep trial programs with automated replacement cycles transform one-time purchases into recurring revenue streams. |
| Phase-Change Material R&D Investment | Thermal-regulation performance gaps separate premium architectures from commodity foam alternatives. |
| Healthcare Channel Partnership Development | Medicare reimbursement code alignment opens institutional procurement pathways for therapeutic specifications. |
| Recycling Infrastructure Access | California SB 1019 mandates and extended producer responsibility laws create certified feedstock competitive advantages. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, hospitality procurement databases, and California Department of Resources Recycling and Recovery mattress diversion reports. Primary interviews engaged foam manufacturing plant managers, hotel chain procurement directors, GOLS certification auditors, direct-to-consumer platform operations executives, and chemical compliance specialists. Secondary validation drew from U.S. Consumer Product Safety Commission enforcement disclosures, EU ECHA REACH restriction proposals, and SEC filings from publicly traded bedding companies. Bottom-up segment sizing triangulated against top-down market value estimates.
Forecast inputs incorporate material type segmentation, thickness configuration demand curves, end-user channel mix evolution, and distribution channel penetration rates across the analysis window. The analytical framework models density rating preferences, certification tier adoption patterns, and regional regulatory cluster impacts on formulation requirements. CAGRs derive from regression analysis of historical shipment volumes against petrochemical price indices and hospitality construction activity. Industry-specific inputs include phase-change material integration adoption curves and sensor-embedded topper pilot deployment timelines.
Sensitivities concentrate around petrochemical feedstock price volatility, state-level chemical restriction cascades beyond California, and plantation capacity expansion timelines in Southeast Asia. Forecasts reflect assumptions regarding regulatory enforcement continuity and certification audit backlog resolution. Material shifts in EU Ecodesign implementation scope or federal flammability standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
US Wallpaper Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Interior Design Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
Plantation Shutters Market