
 Door Stopper Market | 2026-2036
Door Stopper Market Size, Share, and Industry Trends Forecast 2026-2036
Door Stopper Market Analysis
Market Context
Vietnam's expanding hardware manufacturing corridor is reconfiguring supply dynamics for basic architectural fittings. Dorma Kaba leverages its European distribution network to sustain premium positioning in specification-grade magnetic stoppers. Spectrum Brands anchors North American retail channels through mass-market wedge and spring assortments. Stanley Black & Decker competes across commercial and residential tiers with broad material coverage.
Technical Definition and Segment Structure
A door stopper is a mechanical or magnetic device, typically fabricated from rubber compounds, zinc alloys, stainless steel, or engineered polymers, designed to arrest door swing, prevent wall impact damage, or hold doors in fixed open positions through friction, magnetic adhesion, or spring-loaded rebound mechanisms. Wedge and magnetic variants dominate residential volume, while heavy-duty metal spring configurations command industrial margins due to cycle-life specifications and floor-mounting requirements. Rubber and metal materials lead current production, though recycled-content plastics are gaining specification share in commercial green building projects where LEED and BREEAM compliance shapes procurement.
Regulatory Environment
OSHA workplace safety standards in the United States mandate hold-open devices in commercial egress paths, directly shaping industrial and commercial product demand. The EU REACH regulation and Ecodesign for Sustainable Products framework restrict certain phthalates in rubber compounds and establish recycled content thresholds for plastic variants sold within member states. China's GB standards for building hardware set dimensional and load-bearing benchmarks that export-oriented manufacturers must satisfy for market access. Stakeholders should monitor evolving extended producer responsibility schemes and material certification requirements as these frameworks tighten product composition rules across major supply destinations.
Market Dynamics
The EU Ecodesign for Sustainable Products Regulation is forcing virgin plastic phase-outs across door stopper supply chains, compressing margins for polymer-dependent producers while elevating certified metal and recycled rubber alternatives in specification channels.
Growth Catalysts
- Residential Retrofit Surge:North American homeowners are accelerating purchases of spring and magnetic variants during renovation cycles, with hardware retailers reporting concentrated demand spikes in suburban markets.
- REACH Compliance Migration:Manufacturers reformulating rubber compounds to eliminate restricted phthalates are capturing specification share in EU commercial projects where ECHA enforcement has tightened.
- Vietnam Manufacturing Scale:Export-oriented production clusters in Binh Duong and Dong Nai provinces are reducing unit costs for zinc alloy and stainless steel fabrications.
Market Restraints
- Recycled Rubber Input Volatility:Post-consumer tire crumb supply fluctuations are destabilizing cost structures for eco-certified door stopper lines dependent on circular feedstocks.
- Single-Source Magnet Dependency:Rare earth element concentration in Chinese processing facilities creates supply vulnerability for magnetic stopper manufacturers lacking diversified procurement.
- OSHA Egress Path Mandates:Hold-open device requirements in US commercial buildings create technical friction for simple friction-based products, limiting addressable market scope.
Strategic Opportunities
- German Renovation Subsidies:Federal funding for energy-efficient building upgrades is channeling specification demand toward certified metal stoppers that satisfy green building code thresholds.
- Smart Building Integration:Convergence of mechanical door control with IoT access systems is opening specification pathways for sensor-enabled magnetic holders in commercial security installations.
- Direct Contractor Platforms:B2B procurement marketplaces are disintermediating traditional distribution, enabling specialized manufacturers to capture margin previously allocated to wholesale tiers.
Industry Challenges
- GB Standard Certification Timelines:Chinese building hardware compliance testing creates extended market entry delays for exporters targeting domestic construction projects.
- Polymer Reformulation Capex:Transitioning virgin plastic production lines to recycled-content or bio-based alternatives demands significant retooling investment with uncertain payback periods.
- Cross-Material Quality Assurance:Maintaining consistent cycle-life performance across rubber, metal, and hybrid compositions strains quality control systems and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door Stopper Market |
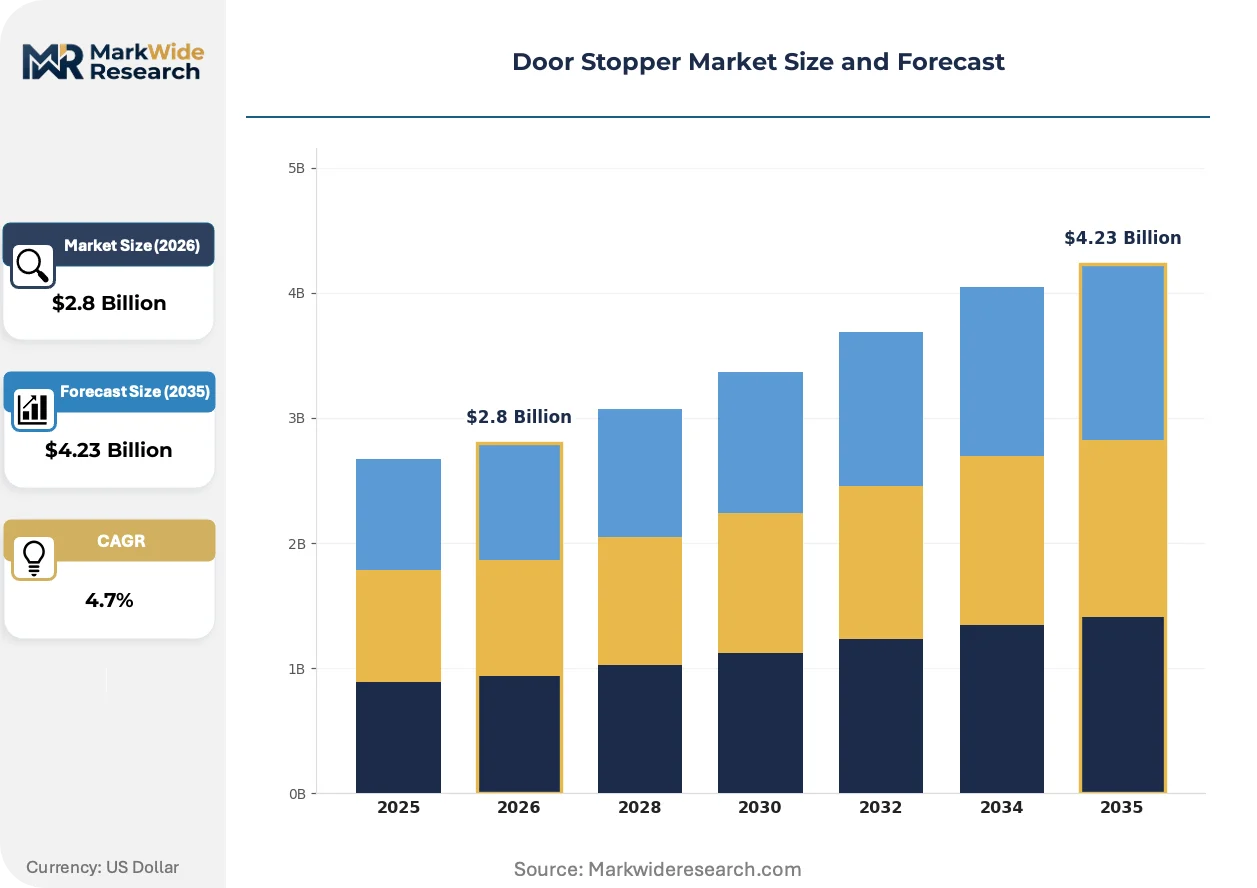
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wedge, Magnetic, Spring, Heavy-Duty Material: Rubber, Plastic, Metal, Wood Application: Residential, Commercial, Industrial, Outdoor Design: Traditional, Modern, Funky, Minimalist |
| Companies Covered | Dorma Kaba, Spectrum Brands, 3M, Hettich Australia Pty Ltd, Knape Vogt Manufacturing Company, Stanley Black & Decker, Allegion, Salice, Assa Abloy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door Stopper Market Emerging Trajectories
Material substitution and regulatory compliance are compressing traditional product lifecycles, with sustainability certification and smart building compatibility emerging as the primary axes of competitive differentiation.
Advanced magnetic assemblies utilizing neodymium-iron-boron configurations are rendering obsolete conventional spring-loaded mechanisms in high-traffic commercial environments. Facility managers in US healthcare and education verticals are specifying these variants for cycle-life reliability exceeding one million operations. The shift is compressing addressable demand for mechanical alternatives in premium specification tiers.
REACH Annex XVII restrictions on phthalate plasticizers are compelling rubber compound reformulation across EU-bound production. Manufacturers investing in bio-based alternatives derived from dandelion or guayule latex are securing BREEAM-compliant project specifications. German and Dutch construction consortia are now mandating material safety data sheet disclosure as a procurement gate.
Building automation procurement teams are unbundling door hardware from general contractor packages, creating direct specification relationships with specialized stopper manufacturers. This disintermediation is most visible in US commercial office retrofits where LEED v4.1 certification drives material transparency requirements. Distributors are responding with certified product segregation and digital documentation portals.
Door Stopper Market Segmentation
Door stopper procurement varies sharply by installation environment, with specification-grade products demanding intensive after-sales documentation for warranty compliance. Material and mechanism choices cascade through replacement cycles, maintenance protocols, and regulatory exposure. Understanding segment boundaries enables precise margin capture across divergent customer workflows.
Product Type:
After-sales service intensity peaks with spring-loaded and magnetic variants, where cycle-life warranties and field calibration requirements create recurring manufacturer touchpoints.
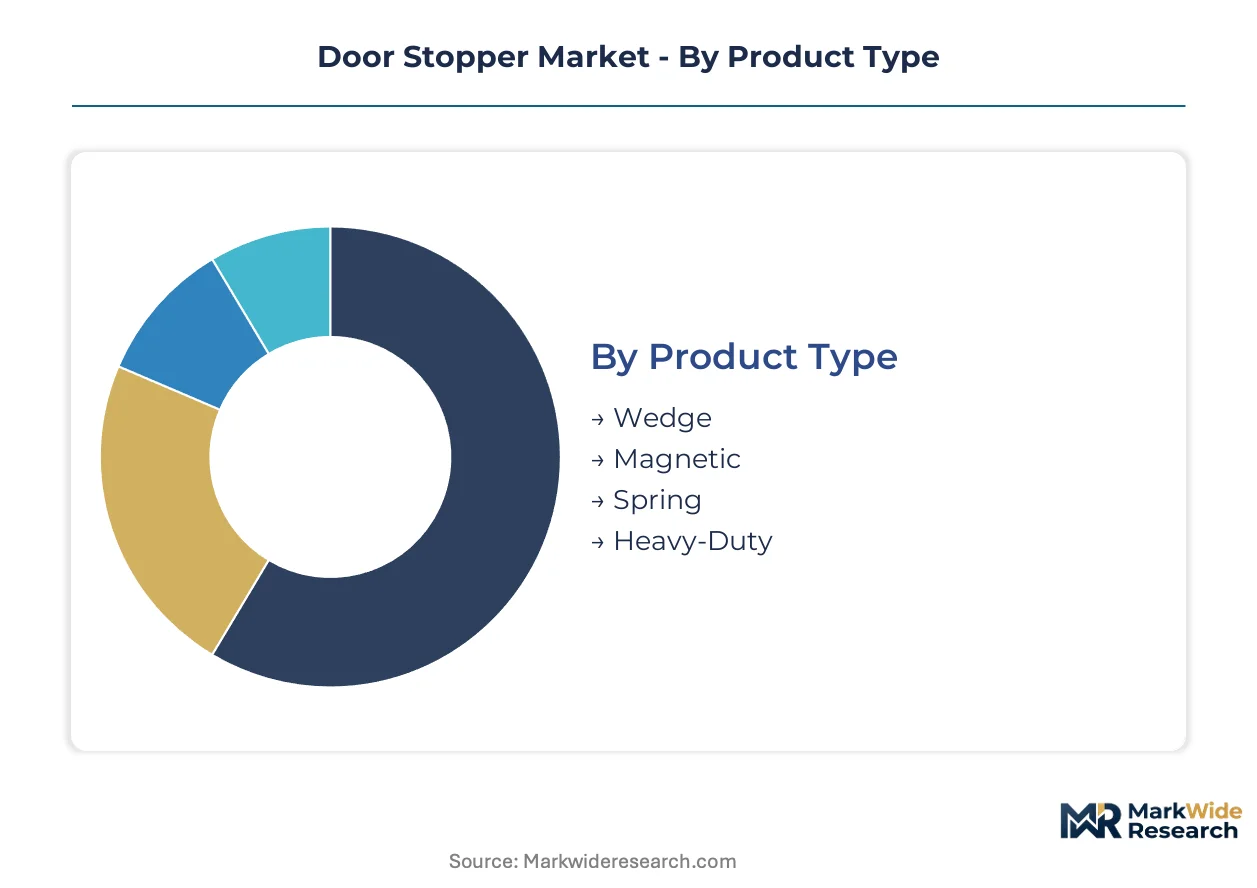
- Wedge:Fabricated from rubber compounds or dense polymers, these friction-dependent units arrest door swing through angular pressure against floor surfaces. Demand concentrates in North American residential retrofit channels, where homeowners prioritize low-cost installation without hardware mounting. By volume, wedge leads. By growth pace, magnetic is ahead.
- Magnetic:Neodymium-iron-boron assemblies generate holding force through ferrous plate adhesion, enabling clean wall-mounted installation without floor penetration. US healthcare and education verticals specify these for cycle-life reliability exceeding one million operations, displacing mechanical alternatives in premium tiers.
- Spring:Coiled steel mechanisms absorb impact kinetic energy through controlled rebound, suited for high-traffic commercial corridors with repetitive door cycles.
- Heavy-Duty:Reinforced metal castings with floor-anchor compatibility serve industrial environments subject to forklift impact and OSHA egress compliance mandates.
Specification complexity rises from wedge to heavy-duty, with magnetic variants commanding the steepest expansion trajectory in commercial retrofit.
Material:
Cost tier stratification separates commodity rubber and virgin plastic from certified recycled-content and precision metal grades.
- Rubber:Natural and synthetic elastomer compounds provide impact absorption and floor grip, with REACH Annex XVII compliance now mandatory for EU-bound shipments. German renovation subsidies channel specification demand toward certified recycled rubber products that satisfy green building code thresholds.
- Metal:Zinc alloy and stainless steel fabrications deliver structural integrity for high-cycle commercial applications, with Vietnam's Binh Duong manufacturing corridor reducing unit costs for export-oriented production. BREEAM-compliant project specifications increasingly mandate material safety data sheet disclosure as a procurement gate.
- Plastic:Virgin polymer injection molding dominates mass-market retail assortments, though EU Ecodesign regulations are forcing phase-out timelines across member states.
- Wood:Hardwood and composite timber variants serve aesthetic-driven residential segments, with limited penetration in commercial specification channels.
By installed base, rubber and metal dominate. By specification momentum, recycled-content metal is climbing fastest.
Application:
Customer type fragmentation separates price-sensitive residential purchasers from compliance-driven institutional buyers.
- Residential:Homeowners and rental property managers drive volume through hardware retail and direct contractor platform procurement, with suburban North American markets showing concentrated demand spikes during renovation cycles.
- Commercial:Office, retail, and hospitality facilities specify products meeting LEED v4.1 material transparency requirements, with US building automation teams unbundling door hardware from general contractor packages.
- Industrial:Manufacturing and logistics operations prioritize OSHA-compliant hold-open devices in egress paths, creating technical friction for simple friction-based alternatives.
- Outdoor:Weather-resistant metal and composite formulations serve marine, agricultural, and infrastructure applications with extended UV and moisture exposure profiles.
Residential channels move highest unit volumes. Commercial specification delivers steepest margin expansion.
Design:
Volume concentration sits with traditional and minimalist forms, while modern and funky aesthetics capture specification premiums in design-forward segments.
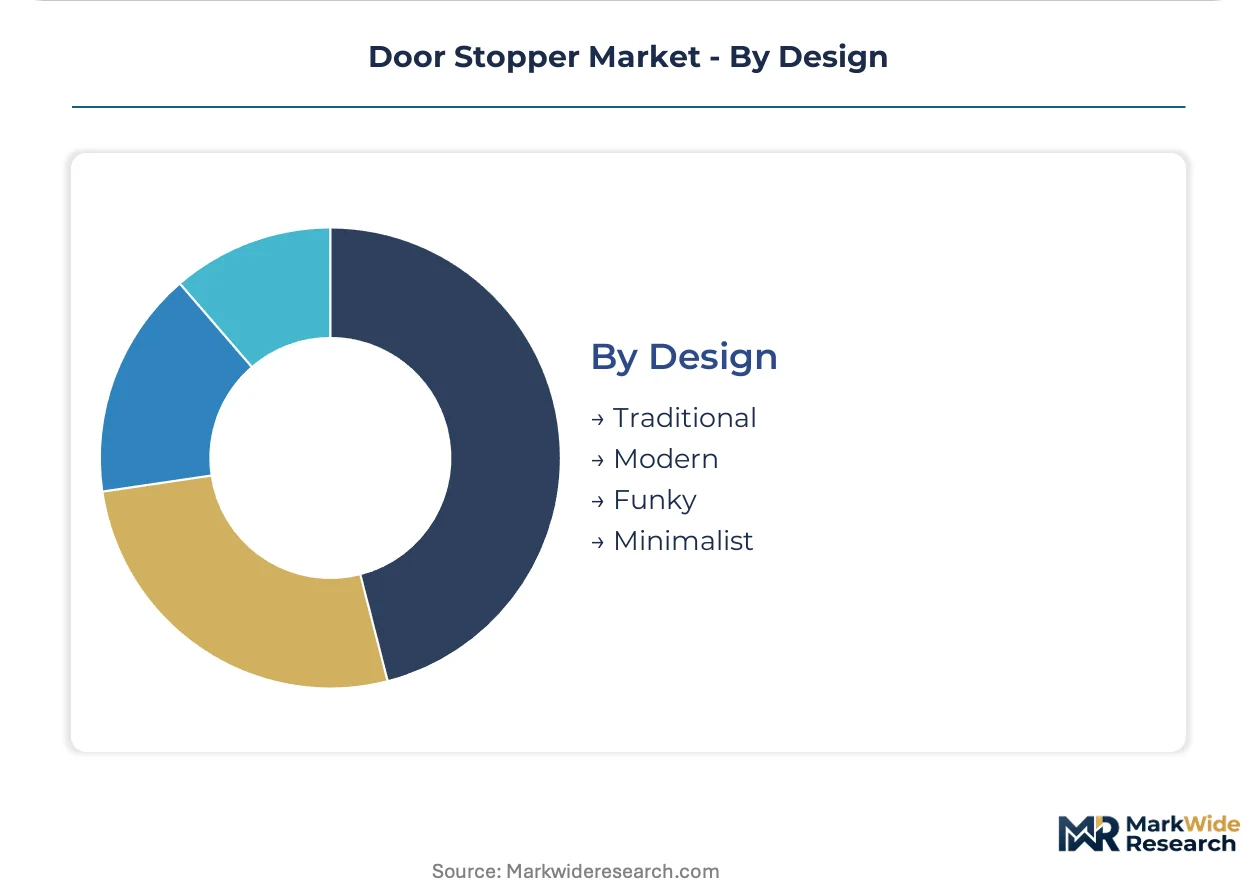
- Traditional:Domed rubber wedges and cast metal floor mounts align with established architectural vocabularies in heritage building maintenance and conservative commercial interiors.
- Modern:Geometric metal fabrications and concealed magnetic housings satisfy contemporary residential and workplace aesthetics, with direct-to-consumer channels expanding access.
- Funky:Novelty shapes and bright colorways target gift and children's room segments, with limited commercial specification relevance.
- Minimalist:Ultra-low-profile magnetic and flush-mount spring mechanisms integrate with invisible hardware trends in luxury residential and boutique hospitality.
Traditional forms retain volume leadership. Minimalist designs are gaining share fastest in premium specification tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety standards in the United States anchor the regulatory framework for commercial door hardware specifications. National renovation cycles and green building code adoption are redistributing procurement volumes across developed markets.
United States
Healthcare and education verticals specify neodymium-iron-boron magnetic assemblies for cycle-life reliability exceeding one million operations. OSHA mandates hold-open devices in commercial egress paths, creating technical friction for simple friction-based alternatives. Building automation teams in Chicago and Atlanta unbundle door hardware from general contractor packages to satisfy LEED v4.1 material transparency requirements.
Germany
Federal renovation subsidies channel specification demand toward certified metal stoppers that satisfy green building code thresholds. ECHA REACH Annex XVII enforcement tightens phthalate restrictions in rubber compounds bound for EU commercial projects. Manufacturing clusters in North Rhine-Westphalia reformulate bio-based alternatives derived from dandelion latex to secure BREEAM-compliant specifications.
Vietnam
Export-oriented production in Binh Duong and Dong Nai provinces reduces unit costs for zinc alloy and stainless steel fabrications. The country's national building hardware regulator maintains GB standard alignment for construction export certification. Ho Chi Minh City logistics corridors serve as transshipment nodes for ASEAN-bound architectural fittings.
China
Dual carbon goals and MIIT industrial policy accelerate recycled-content material transitions in polymer-dependent production lines. GB standards for building hardware set dimensional and load-bearing benchmarks that export-oriented manufacturers must satisfy. Yangtze River Delta fabrication clusters concentrate rare earth magnet processing for magnetic stopper assemblies.
United Kingdom
Heritage building maintenance sustains demand for traditional cast metal floor mounts and domed rubber wedges. CSRD disclosure requirements extend material traceability obligations to commercial construction supply chains. Midlands manufacturing bases supply specification-grade spring mechanisms for NHS facility refurbishment programs.
Door Stopper Market Vendor Landscape
Capability concentration sits with specification-grade specialists; scale advantage sits with mass-market distributors. The vendor base stratifies across three tiers: premium architectural hardware houses, mid-market building material conglomerates, and regional fabrication specialists. Strategic archetypes include European specification leaders, North American retail anchors, and Asian export manufacturers. Competitive moves center on polymer reformulation partnerships and direct contractor platform integration.
Among diversified industrial conglomerates, 3M and Stanley Black & Decker occupy positions spanning commercial and residential tiers with broad material coverage. Spectrum Brands exemplifies the mass-market retail anchor archetype, anchoring North American hardware channels through broad distribution reach. Dorma Kaba sits within the premium specification tier, sustaining positioning through European architectural specification networks. These three represent distinct competitive vectors rather than overlapping market contests.
| Leading Market Players |
|---|
| Dorma Kaba |
| Spectrum Brands |
| 3M |
| Hettich Australia Pty Ltd |
| Knape Vogt Manufacturing Company |
| Stanley Black & Decker |
| Allegion |
| Salice |
| Assa Abloy |
| Others |
Supply Flow & Price Mechanics
Binh Duong province's zinc alloy and stainless steel fabrication clusters are expanding capacity faster than downstream demand absorption, compressing export pricing power for mass-market wedge and spring variants while elevating margins for specification-grade magnetic assemblies with certified cycle-life warranties.
Pricing Analysis
Unit price spreads between Vietnam-exported metal fabrications and EU-certified recycled rubber products now exceed three-to-one, with premium-mid-economy pricing differentiation anchored by BREEAM compliance tiers and after-sales documentation bundles. Cost compression in virgin polymer lines is intensifying because EU Ecodesign phase-out mandates are forcing distressed inventory liquidation. Residential retrofit purchasers through hardware retail channels exhibit highest price sensitivity, while German commercial consortia purchasing for renovation subsidy programs demonstrate lowest sensitivity due to green building code threshold requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for ASEAN-based fabricators supplying North American distributors, with supply-chain finance facilities increasingly bridging working capital gaps for tier-two manufacturers. Production gravity centers on Vietnam, China, and Germany, with rare earth magnet processing concentrated in the Yangtze River Delta and precision metal casting in North Rhine-Westphalia. Raw material flows draw from post-consumer tire crumb for recycled rubber compounds, neodymium-iron-boron alloys for magnetic assemblies, and zinc ingots for die-cast hardware. Single-source dependency on Chinese rare earth processing creates structural vulnerability for magnetic stopper procurement. Distribution runs through specification-grade architectural hardware houses in Europe, mass-market retail anchors in North America, and direct contractor platforms emerging in both regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The door stopper market functions as a regulatory entrenchment story, where REACH Annex XVII compliance and Ecodesign certification create switching costs that lock institutional buyers into validated supplier relationships and deter opportunistic price competition.
For Market Incumbents: Harden specification-grade positioning by deepening backward integration into certified recycled rubber compounding and neodymium magnet assembly, neutralizing the threat of Vietnamese cost competitors lacking BREEAM documentation capabilities. Prioritize capacity addition in North Rhine-Westphalia to capture German federal renovation subsidy flows with localized green building code compliance. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with unbundled procurement from general contractor packages creating direct specification access for sensor-enabled magnetic holders. US healthcare facility retrofit programs offer secondary white-space, with cycle-life reliability requirements exceeding one million operations filtering out established mechanical competitors. A go-to-market angle through B2B procurement marketplaces enables margin capture previously allocated to wholesale distribution tiers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specification-grade specialists with embedded regulatory compliance capabilities over mass-market scale players facing polymer reformulation capex burdens. Long-term viability over a five-to-ten year horizon rests on material substitution agility and smart building integration pathways rather than manufacturing scale alone. Acquisition targets should demonstrate EU Ecodesign pre-certification and IoT access system partnerships. The signal to watch is consolidation in Vietnamese export manufacturing, where distressed asset availability may accelerate if EU recycled-content mandates tighten faster than reformulation timelines allow.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Rubber Compound Certification | REACH Annex XVII pre-certification secures BREEAM-compliant project specifications in German renovation subsidy channels. |
| Neodymium Magnet Supply Diversification | Dual-sourcing from Yangtze River Delta and alternative processing jurisdictions reduces rare earth concentration risk. |
| Smart Building Integration Partnership | IoT access system convergence opens specification pathways for sensor-enabled magnetic holders in commercial security installations. |
| Direct Contractor Platform Integration | B2B procurement marketplace disintermediation captures margin previously allocated to wholesale distribution tiers. |
| Vietnam Manufacturing Scale Expansion | Binh Duong capacity addition reduces unit costs for zinc alloy and stainless steel fabrications serving export markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with facility managers in US healthcare and education verticals, German construction consortium procurement leads, and Vietnamese export manufacturing plant heads providing operational validation. Secondary sources included ECHA REACH regulatory filings, EU Ecodesign implementation guidance, German federal renovation subsidy program documentation, and customs trade data for architectural hardware flows. Bottom-up segment sizing triangulated against top-down macroeconomic anchors ensured methodological consistency.
Calibration against historical volume trajectories and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, application environment, and design aesthetic, with regional regulatory cluster differentiation as an industry-specific overlay. CAGRs were derived from fitted growth curves adjusted for policy-driven demand step-changes. Forecast inputs incorporated polymer reformulation capex schedules, rare earth magnet price volatility bands, and green building code adoption curves.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, renovation subsidy funding levels, or trade policy stringency would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pacing and material substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Interior Design Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Window Covering Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Flush Door Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Wall Decor Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Japan Sustainable Home Decor Market