
 Middle East and Africa Christmas Tree Market | 2026-2036
Middle East and Africa Christmas Tree Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Christmas Tree Market Foresight
Saudi Arabia is rewriting the supply map for Middle East and Africa Christmas Tree Market sourcing as domestic warehousing and seasonal distribution hubs multiply around Jeddah and Riyadh. TechnipFMC Plc leverages its industrial project logistics network to anchor bulk artificial tree shipments into Gulf Cooperation Council markets. Baker Hughes Company competes through channel control of polyethylene-based inventory destined for commercial end users. National Tree Company specializes in pre-lit and tabletop configurations calibrated to regional voltage standards and climate conditions.
The Middle East and Africa Christmas Tree comprises decorated evergreen structures—natural or synthetic—engineered for seasonal display, with artificial variants typically employing PVC or polyethylene needle systems attached to hinged metal frames and pre-wired with low-voltage LED strings rated for dry and damp locations. Artificial Christmas Trees occupy the dominant volume position across the region given import reliability and multi-season reuse economics, while Pre-lit Trees capture expanding margin pools as Gulf hotels and shopping malls prioritize labor-minimized installation. Polyethylene material grades increasingly displace basic PVC in premium tier positioning due to superior needle realism and flame-retardant compliance profiles.
South Africa's National Regulator for Compulsory Specifications enforces electrical safety and flammability testing on all imported pre-lit tree assemblies, while the UAE's Emirates Authority for Standardization and Metrology governs product labeling and energy efficiency declarations for seasonal lighting accessories. Saudi Standards, Metrology and Quality Organization requirements for chemical content in plastics directly shape supplier material selections and factory audit protocols. Stakeholders must monitor evolving Gulf customs tariff schedules and local content incentives that could reroute procurement away from traditional Far East manufacturing clusters toward regional assembly or near-shoring alternatives.
Market Dynamics
Warehousing expansion across Saudi Arabia and the UAE is compressing lead times for artificial tree imports, while South Africa's NRCS enforcement and Gulf voltage standardization are fragmenting supplier compliance requirements across the region.
Growth Catalysts
- Commercial hospitality procurement:Dubai and Riyadh hotels are scaling seasonal décor budgets to capture year-end tourism flows. Mall operators in Abu Dhabi and Doha follow similar patterns.
- Pre-lit LED technology:Low-voltage, climate-rated lighting systems reduce on-site installation labor for Gulf commercial buyers. This specification now dominates procurement tenders.
- SFDA material standards:Saudi Arabia's chemical content rules for plastics are accelerating factory audits and material traceability investments by Far East manufacturers.
Market Restraints
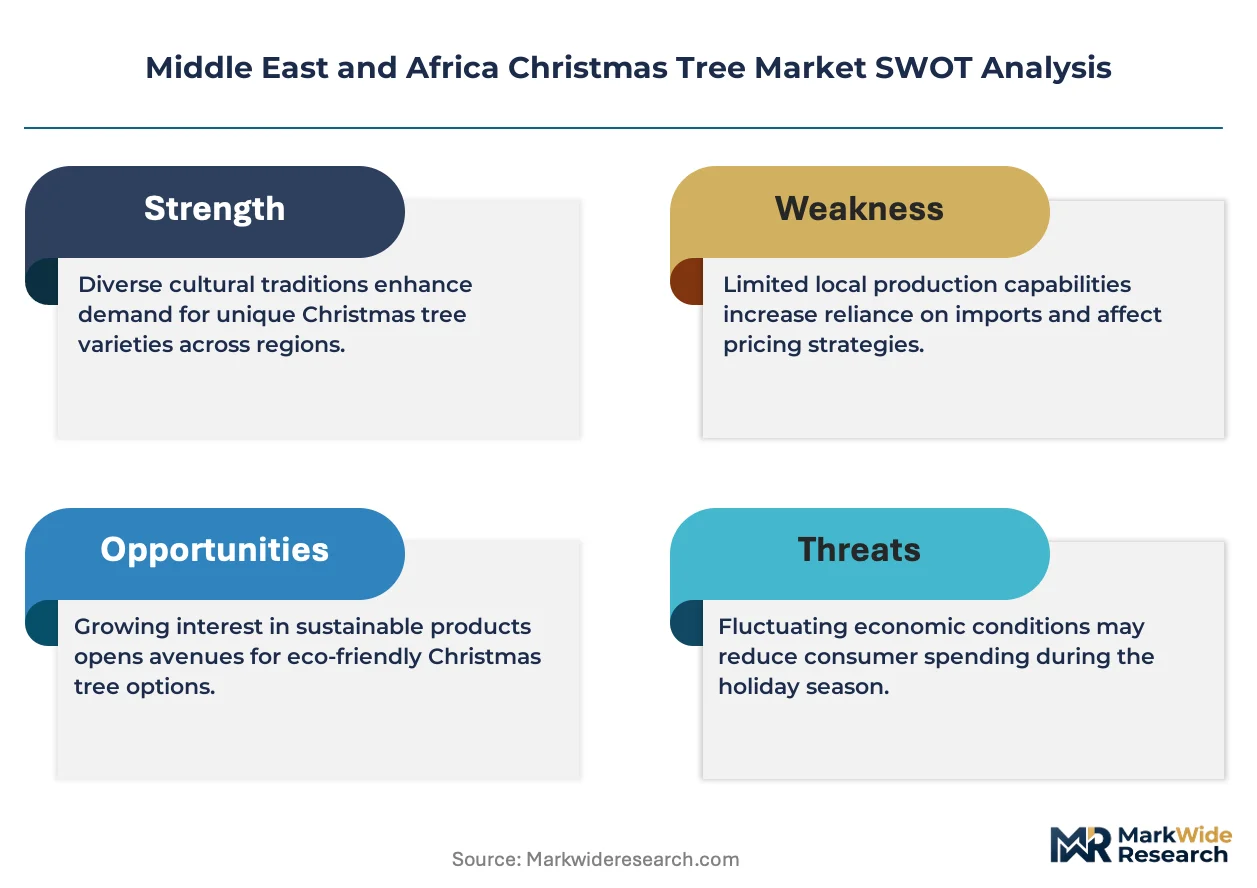
- Input cost volatility:Polyethylene resin prices fluctuate with crude oil benchmarks, squeezing margin predictability for premium-tier artificial tree production.
- Supply concentration risk:Bulk manufacturing clusters in Guangdong and Zhejiang provinces create single-source vulnerability for Middle East and Africa importers.
- NRCS testing timelines:South Africa's electrical safety and flammability certification delays product launches by 8-14 weeks during peak ordering seasons.
Strategic Opportunities
- Nigeria urban retail:Lagos and Abuja shopping districts show underpenetrated demand for compact tabletop and pre-lit varieties suited to apartment living.
- Regional assembly incentives:Saudi Arabia's local content requirements and customs tariff structures favor establishing Jeddah or Riyadh-based finishing facilities.
- Smart lighting convergence:Integration of app-controlled RGB LED systems with artificial tree frames opens premium positioning for tech-forward hospitality buyers.
Industry Challenges
- Certification fragmentation:Divergent voltage, flammability, and chemical standards across Saudi SFDA, UAE ESMA, and South Africa NRCS multiply SKU complexity for suppliers.
- Seasonal demand compression:Narrow Q3-Q4 ordering windows strain working capital and inventory forecasting for distributors serving the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Christmas Tree Market |
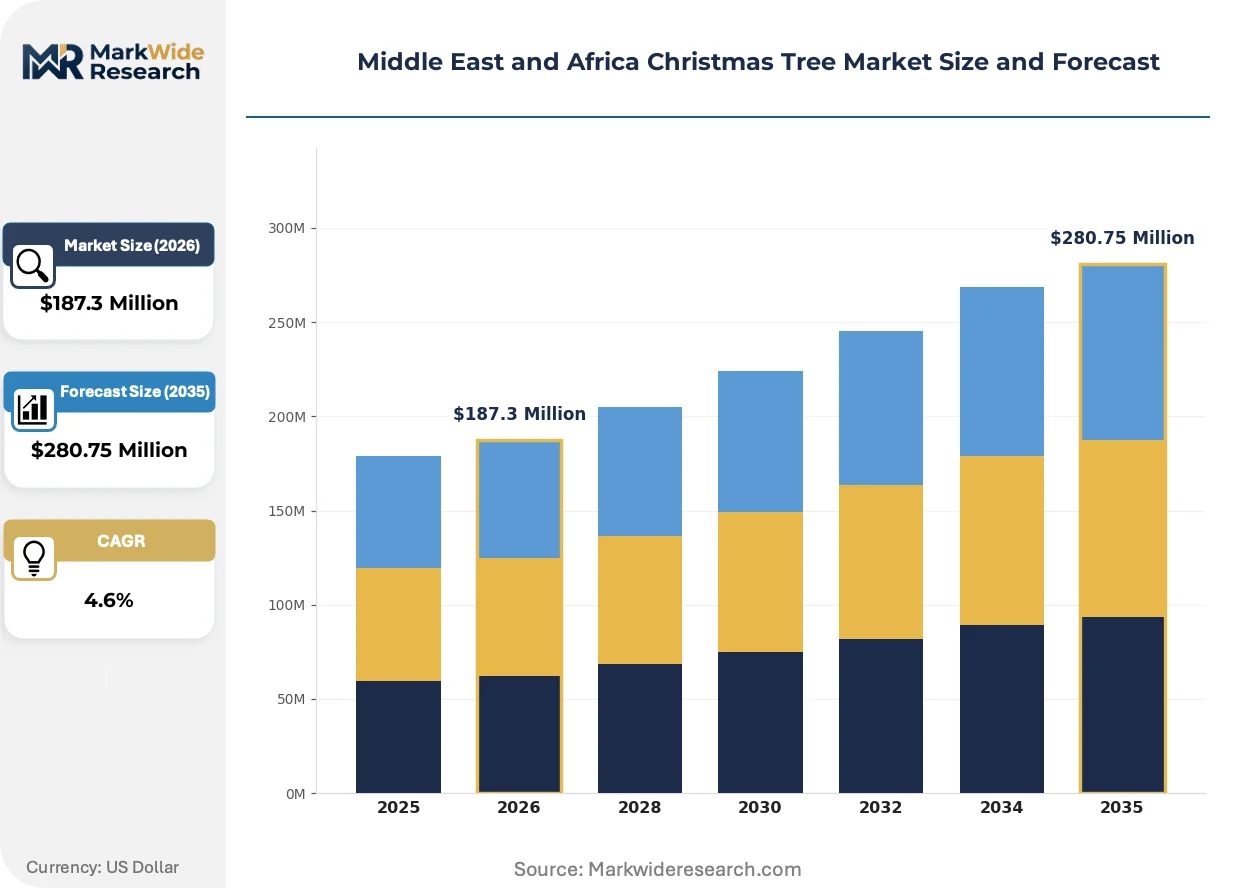
| Market Size in 2026 | $187.3 Million |
| Market Size in 2035 | $280.75 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tree Type: Real Christmas Trees, Artificial Christmas Trees, Pre-lit Trees, Tabletop Trees Material: Polyethylene, PVC, Metal, Wood Distribution Channel: Online Retail, Supermarkets, Garden Centers, Specialty Stores End User: Households, Businesses, Schools, Religious Organizations |
| Companies Covered | TechnipFMC Plc, Baker Hughes Company, Schlumberger Limited, Aker Solutions ASA, Drill-Quip Inc., National Tree Company, Balsam Hill, Fraserdale Ltd, Puleo International, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Christmas Tree Market Shifts & Advancements
Material science advances and Gulf regulatory harmonization are reshaping product specifications, while procurement digitization and channel consolidation are altering how commercial buyers source seasonal décor.
Polyethylene needle systems are digitizing the premium artificial tree segment by enabling photorealistic branch structures that integrate with automated quality inspection systems. Saudi hotel procurement teams specify these grades for lobby installations. The technology is digitizing supplier factory workflows and compressing defect rates in pre-lit assembly lines.
SFDA chemical content regulations and UAE ESMA labeling mandates are forcing material substitutions across PVC and polyethylene grades. Factory audit protocols now require documented flame-retardant additive chains. Commercial hospitality buyers in Dubai and Riyadh prioritize suppliers with dual-certification readiness.
Direct-to-hotel procurement platforms are consolidating what was previously fragmented distributor networks across the Gulf. Procurement teams at Riyadh and Jeddah hospitality groups now source through centralized digital tenders. This pattern is most visible in Saudi Arabia's luxury hotel segment, where volume commitments override traditional seasonal distributor relationships.
Middle East and Africa Christmas Tree Market Segmentation
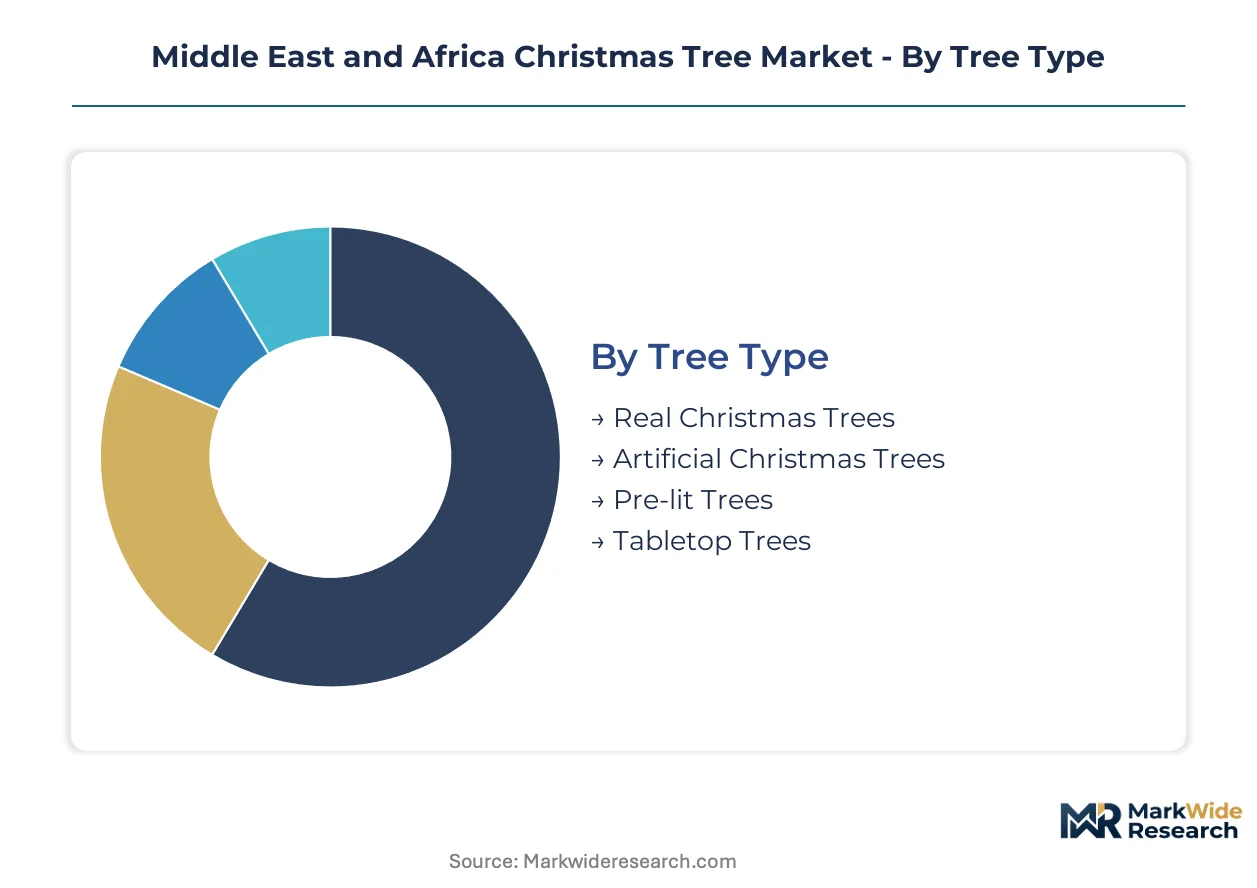
Segmentation in the Middle East and Africa Christmas Tree Market reveals divergent procurement rhythms across tree types and materials. Commercial buyers in Dubai and Riyadh rotate stock on compressed cycles compared to household purchasers in Lagos or Cape Town.
Tree Type:
Replacement cycles vary dramatically across this category, with commercial hospitality venues refreshing displays annually while residential buyers extend useful life across multiple seasons.
- Real Christmas Trees:Fresh-cut evergreens require cold-chain logistics and perish within weeks of display. Demand concentrates in South Africa's Cape region where pine plantations serve local retail, constrained by import phytosanitary barriers and narrow harvest windows.
- Artificial Christmas Trees:PVC and polyethylene needle systems mounted on hinged metal frames dominate import volumes into Gulf Cooperation Council markets. Dubai hotels specify these for multi-season reuse economics and fire-safety compliance.
- Pre-lit Trees:Factory-integrated LED wiring reduces on-site installation labor for Abu Dhabi mall operators. Saudi Standards, Metrology and Quality Organization electrical certifications govern voltage and flammability specifications.
- Tabletop Trees:Compact configurations suit Nigeria's urban apartment density and Lagos retail space constraints. Pre-lit variants command premium positioning in Abuja shopping districts.
Artificial Christmas Trees anchors the volume base while Pre-lit Trees gains share at the steepest rate.
Material:
Cost tiers separate commodity-grade inputs from premium specifications, with regulatory compliance costs widening the spread between base and advanced grades.
- Polyethylene:Injection-molded needle tips replicate photorealistic branch structures. Saudi hotel procurement teams specify these grades for lobby installations where visual authenticity justifies price premiums.
- PVC:Extruded flat-needle construction dominates economy-tier artificial trees. South Africa's National Regulator for Compulsory Specifications enforces flammability testing on all PVC assemblies with electrical components.
- Metal:Steel and aluminum framing systems provide structural backbone for hinged artificial tree assemblies. Hinge mechanisms undergo fatigue testing for Gulf climate humidity exposure.
- Wood:Natural trunk inserts and base structures serve premium artisanal segments. Limited commercial scale due to moisture sensitivity in coastal UAE and Saudi environments.
Polyethylene commands the highest unit margins while PVC retains the broadest household penetration.
Distribution Channel:
Channel concentration reflects urban retail infrastructure maturity, with digital penetration diverging sharply between Gulf cities and sub-Saharan markets.
- Online Retail:Direct-to-hotel procurement platforms consolidate previously fragmented distributor networks across Saudi Arabia. Centralized digital tenders now dominate Riyadh luxury hospitality seasonal sourcing.
- Supermarkets:Mass-market artificial trees and tabletop varieties stock seasonal aisles in Lagos and Abuja urban retail chains. Pre-lit configurations accelerate inventory turns.
- Garden Centers:Real Christmas Trees and premium artificial specimens concentrate in South Africa's Western Cape nursery retail. Cold-chain proximity determines viable catchment radius.
- Specialty Stores:Curated polyethylene needle systems and custom lighting configurations serve Dubai design-conscious residential buyers. Staff-assisted specification dominates purchase process.
Supermarkets move the highest unit volumes while Online Retail expands most quickly in Gulf commercial segments.
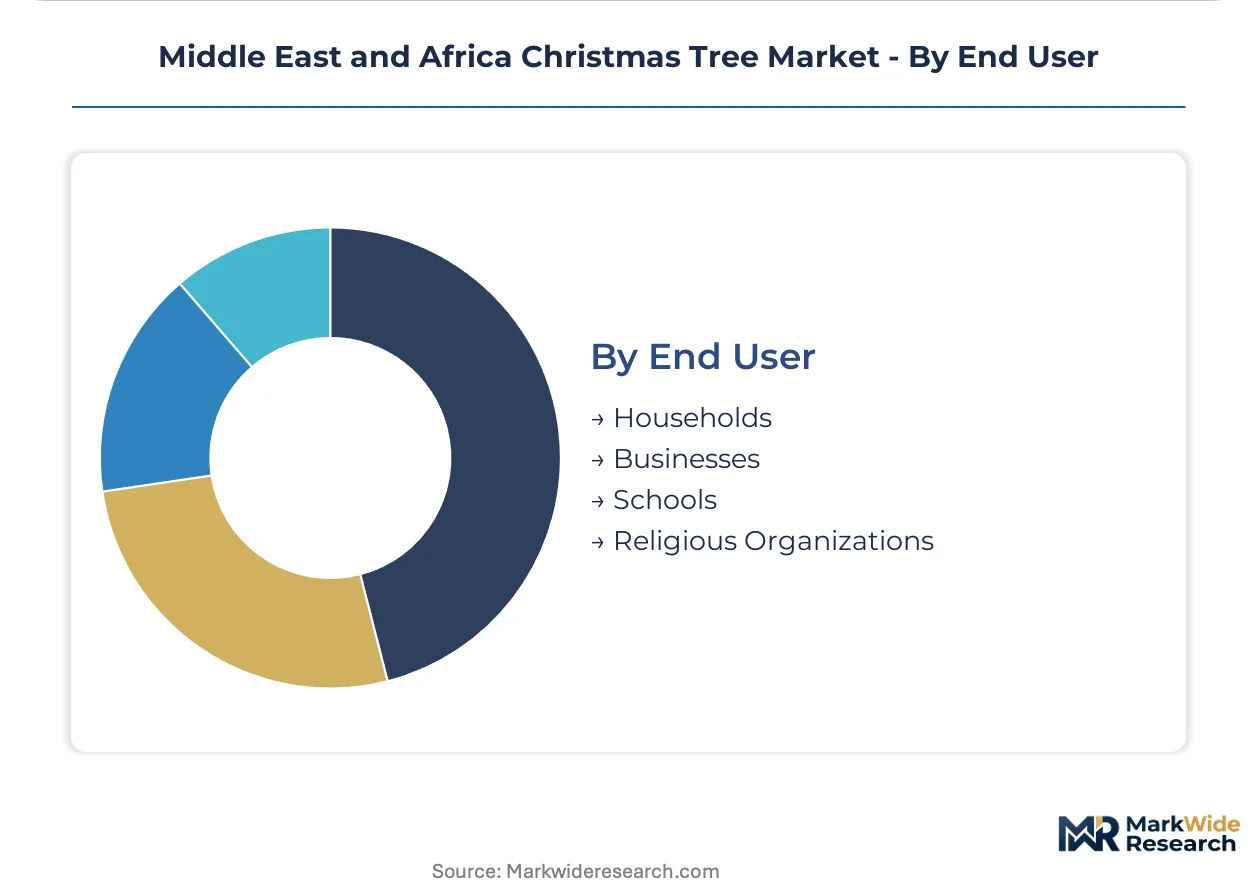
End User:
Application requirements fragment procurement specifications, with commercial buyers prioritizing labor minimization and regulatory documentation over household price sensitivity.
- Households:Compact tabletop and mid-size artificial trees dominate Lagos and Abuja apartment living. Pre-lit configurations reduce storage and setup friction for urban Nigerian buyers.
- Businesses:Hotels and shopping malls in Dubai and Riyadh drive demand for large-format polyethylene trees with integrated LED systems. Emirates Authority for Standardization and Metrology labeling mandates govern accessory procurement.
- Schools:Budget-constrained institutions in South Africa prioritize PVC artificial trees with basic lighting. NRCS electrical safety certification delays create procurement planning constraints.
- Religious Organizations:Community-scale displays in Saudi Arabia and UAE require commercial-grade installation support. Seasonal rental models emerge for one-time liturgical events.
Businesses anchor procurement value while Households represent the deepest volume reservoir across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Standards, Metrology and Quality Organization (SFDA) chemical content rules anchor compliance architecture across the dominant Gulf geography, while South Africa's National Regulator for Compulsory Specifications fragments electrical safety requirements for pre-lit assemblies.
Saudi Arabia
Riyadh and Jeddah hospitality groups drive bulk procurement of large-format polyethylene trees with integrated LED systems. SFDA mandates documented flame-retardant additive chains and factory audit protocols for all plastic imports. Eastern Province warehousing clusters now host seasonal distribution hubs compressing lead times for Red Sea port arrivals.
United Arab Emirates
Dubai hotel operators and Abu Dhabi mall managers rotate seasonal décor stock on compressed annual cycles favoring labor-minimized pre-lit configurations. Emirates Authority for Standardization and Metrology governs energy efficiency declarations for lighting accessories. Sharjah-based finishing facilities are emerging as Gulf assembly alternatives to direct Far East imports.
South Africa
Cape region pine plantations serve localized real Christmas Tree demand constrained by import phytosanitary barriers. National Regulator for Compulsory Specifications enforces 8-14 week electrical safety and flammability certification delays. Western Cape nursery retail concentrates premium artificial specimen distribution within cold-chain proximity catchments.
Nigeria
Lagos and Abuja urban retail chains show accelerating inventory turns for compact tabletop and pre-lit varieties suited to apartment living. The country's national standards body influences product safety documentation for electrical seasonal goods. Lagos shopping districts concentrate demand for pre-lit configurations reducing storage friction for dense urban households.
Qatar
Doha mall operators and luxury hospitality venues specify commercial-grade polyethylene needle systems for lobby installations. The country's national metrology authority aligns with Gulf Cooperation Council labeling harmonization initiatives. Doha procurement teams participate in centralized digital tenders consolidating previously fragmented distributor relationships.
Middle East and Africa Christmas Tree Market Competitive Landscape
Capability concentration sits with specialized seasonal décor manufacturers; scale advantage sits with diversified industrial conglomerates leveraging logistics networks. The vendor base separates into three functional tiers: dedicated artificial tree fabricators with material science expertise, energy-sector industrial players repurposing project logistics for seasonal cargo, and hospitality-focused procurement platforms consolidating distributor relationships. Dominant competitive moves include backward integration into polyethylene resin sourcing and establishment of regional finishing facilities to capture Saudi local content incentives.
Among industrial-logistics players, TechnipFMC Plc and Baker Hughes Company exemplify scale-driven entry into seasonal cargo routing through existing Gulf project infrastructure. National Tree Company occupies a position within the dedicated fabricator tier, representing specialization in pre-lit and tabletop configurations calibrated to regional voltage standards. These three anchors illustrate divergent pathways: industrial conglomerates leveraging supply chain assets versus pure-play specialists investing in compliance-ready product lines.
| Leading Market Players |
|---|
| TechnipFMC Plc |
| Baker Hughes Company |
| Schlumberger Limited |
| Aker Solutions ASA |
| Drill-Quip Inc. |
| National Tree Company |
| Balsam Hill |
| Fraserdale Ltd |
| Puleo International |
| Others |
Supply & Pricing Matrix
Guangdong province manufacturing clusters dictate polyethylene resin conversion economics that cascade through Middle East and Africa importer pricing power. Dubai hotel procurement teams leverage volume commitments to compress supplier margins on pre-lit configurations, while Lagos retail distributors absorb freight cost volatility on compact tabletop varieties. Saudi Arabia's SFDA chemical content mandates add compliance premiums that widen spreads between certified and uncertified product tiers.
Pricing Analysis
Price spreads between Gulf commercial buyers and sub-Saharan retail channels reflect divergent service bundling and certification requirements. Three-tier pricing structure across premium polyethylene, standard PVC, and economy flat-needle configurations separates hospitality-grade specifications from household budget tiers. Pricing pressure stems from polyethylene resin cost volatility tracking crude benchmarks, squeezing margin predictability for premium artificial tree assemblers. Household purchasers in Nigeria and South Africa exhibit highest price sensitivity, while Riyadh luxury hotel groups prioritize labor-minimized installation over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with dedicated seasonal décor fabricators in Zhejiang and Guangdong provinces, supplemented by industrial-logistics players repurposing Gulf project infrastructure. Raw material flows draw from Saudi petrochemical feedstocks for polyethylene resin, Chinese PVC extrusion facilities, and Taiwanese LED component suppliers. Single-source vulnerability runs through Guangdong bulk manufacturing clusters, exposing Middle East importers to concentrated disruption risk. Distribution runs through Jeddah and Riyadh warehousing hubs for Gulf markets, with Lagos and Abuja retail chains serving Nigerian urban demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory audit readiness and dual-certification capability separate viable suppliers from margin-compressed commodity players in this compliance-fragmented market. Material traceability documentation and regional voltage standardization expertise constitute scarce assets that concentrate pricing power.
For Market Incumbents: Pre-empt emerging procurement platform consolidation by anchoring direct-to-hotel relationships through multi-season volume contracts with Riyadh and Dubai hospitality groups. Defend margin position against industrial-logistics entrants by deepening captive supply of polyethylene needle systems and accelerating factory audit investments for SFDA compliance readiness.
For New Entrants and Emerging Players: Build out Nigeria's underpenetrated urban retail corridor with compact pre-lit configurations calibrated to Lagos apartment density and voltage standards. Target Abuja shopping district distributors with tabletop varieties reducing storage friction for dense urban households, leveraging supermarket channel relationships as primary go-to-market pathway.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergent Gulf and sub-Saharan certification requirements create persistent capability premiums for dual-standard suppliers. Acquisition focus should center on dedicated fabricators with documented flame-retardant additive chains and existing NRCS testing relationships. Quarterly review of Saudi local content incentive revisions and UAE ESMA labeling harmonization progress is advised to detect inflection toward regional assembly models.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Resin | Captive supply secures margin stability against crude-linked input volatility for Gulf-facing production. |
| Regional Finishing Facility Establishment | Jeddah or Riyadh assembly captures Saudi local content incentives and compresses customs tariff exposure. |
| Dual-Certification Product Line Investment | SFDA and NRCS readiness opens simultaneous access to Gulf hospitality and South African retail channels. |
| Direct-to-Hotel Procurement Platform Launch | Digital tender consolidation displaces fragmented distributor networks in Saudi luxury hospitality segment. |
| Smart Lighting Convergence Development | App-controlled RGB LED integration commands premium positioning from tech-forward Dubai hotel buyers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs import records, hospitality procurement databases, and national standards body filings across Saudi Arabia, UAE, South Africa, and Nigeria. Primary interviews engaged seasonal décor procurement managers at Dubai and Riyadh hotel groups, Lagos retail chain category buyers, polyethylene resin sourcing directors at artificial tree fabricators, and compliance officers navigating SFDA and NRCS certification protocols. Secondary validation drew from Emirates Authority for Standardization and Metrology labeling directives, South Africa National Regulator for Compulsory Specifications testing timelines, and Saudi Standards, Metrology and Quality Organization chemical content regulations. Bottom-up shipment volume analysis triangulates against top-down hospitality seasonal décor budget disclosures.
Forecast inputs incorporate tree type substitution rates, material grade penetration curves, and channel shift dynamics across the projection horizon. Segmentation modeling spans tree type, material composition, distribution channel, and end-user application, with voltage standard and climate rating specifications as industry-specific overlay dimensions. CAGRs derive from regression against historical import volume trajectories and hospitality sector capital expenditure patterns, with Saudi warehousing expansion and Nigeria urban retail infrastructure buildout as key demand-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by industrial-logistics conglomerates or Gulf sovereign wealth-backed procurement platforms would shift outcomes beyond modeled ranges. Quarterly review of Saudi customs tariff schedule revisions, UAE ESMA labeling harmonization announcements, and South Africa NRCS testing backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Window Covering Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
Pillow Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Wall Covering Market