
 US Daybeds Market | 2026-2036
US Daybeds Market Size, Share, and Industry Trends Forecast 2026-2036
US Daybeds Market Insights
The US daybed category is recalibrating around a widening split between heirloom-grade hardwood frames with certified upholstery and flat-pack metal units priced for rental turnover. Ashley Furniture Industries Inc. leverages its vertical manufacturing network to control costs across wood and upholstered lines. Williams-Sonoma Inc. anchors the premium tier through design-forward collections sold via owned channels. West Elm differentiates with sustainably sourced materials that appeal to urban residential buyers.
A daybed is a dual-purpose furniture piece combining a seating surface with a sleep platform, typically built with slatted wood or welded steel frames and foam or spring-supported cushions measuring 75 to 80 inches in length. Manufacturers employ mortise-and-tenon joinery or powder-coated tubular construction to meet residential and commercial load standards. Upholstered daybeds command the strongest margin pools as fabric upgrades and custom sizing drive average order values upward. Metal frames lead unit volumes in the hospitality end user segment due to durability requirements and faster replacement cycles. Wood daybeds sustain steady demand in residential settings where aesthetic longevity influences purchase decisions.
The Consumer Product Safety Commission governs structural stability and entrapment risks for convertible sleep furniture, while the EPA enforces TSCA Title VI limits on composite wood formaldehyde emissions that affect domestic panel sourcing. California's Proposition 65 labeling requirements add compliance layers for upholstered components containing flame retardants or vinyl. Stakeholders must monitor evolving state-level chemical disclosure rules and decide whether to standardize formulations nationally or maintain regional SKU differentiation.
Market Dynamics
The US daybeds market is bifurcating around EPA TSCA Title VI compliance costs, which favor vertically integrated manufacturers with captive panel supply while squeezing import-dependent assemblers into lower-margin metal-frame commoditization.
Growth Catalysts
- Vacation rental platform procurement:Airbnb and Vrbo hosts in Florida and Arizona are outfitting outdoor lounging spaces with weather-resistant daybeds, creating steady replacement demand for hospitality-grade upholstery and powder-coated frames.
- CARB Phase II alignment:California's extended formaldehyde emission rules are accelerating certified wood panel adoption, rewarding domestic manufacturers with compliant supply chains and penalizing non-conforming imports.
- Modular outdoor living:Deck and patio contractors are specifying daybeds with interchangeable cushion systems and configurable backrest angles, driving upgrade cycles in residential renovation projects.
Market Restraints
- Hardwood lumber cost volatility:White oak and walnut price swings from Great Lakes sawmill disruptions compress margin predictability for heirloom-grade frame producers.
- Asia-Pacific panel concentration:Dependence on Vietnamese and Malaysian composite wood suppliers exposes US assemblers to shipping rate spikes and customs inspection backlogs at Long Beach and Savannah ports.
- Flame retardant chemistry restrictions:California Proposition 65 disclosure mandates on upholstered components containing TDCPP or TCEP create SKU proliferation costs for multi-state retailers.
Strategic Opportunities
- Texas second-home corridor:Hill Country and Gulf Coast vacation property investments are outpacing national averages, creating underserved demand for transitional-style daybeds suited to indoor-outdoor flexibility.
- IRA residential energy credits:Homeowners claiming efficiency rebates are redirecting savings toward furniture upgrades, positioning daybeds as complementary purchases in whole-home renovation financing.
- Direct-to-builder channel:Custom home developers in Colorado and Utah are bypassing retail markup by sourcing daybeds through regional millwork distributors, opening B2B volume contracts.
Industry Challenges
- Upholstery craft labor scarcity:Sewing and tufting specialists with foam-cutting certification are retiring faster than trade programs in North Carolina and Mississippi can replenish the pipeline.
- TSCA Title VI audit timelines:Third-party certifier backlogs are extending product launch windows by four to six months for manufacturers sourcing non-certified particleboard.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Daybeds Market |
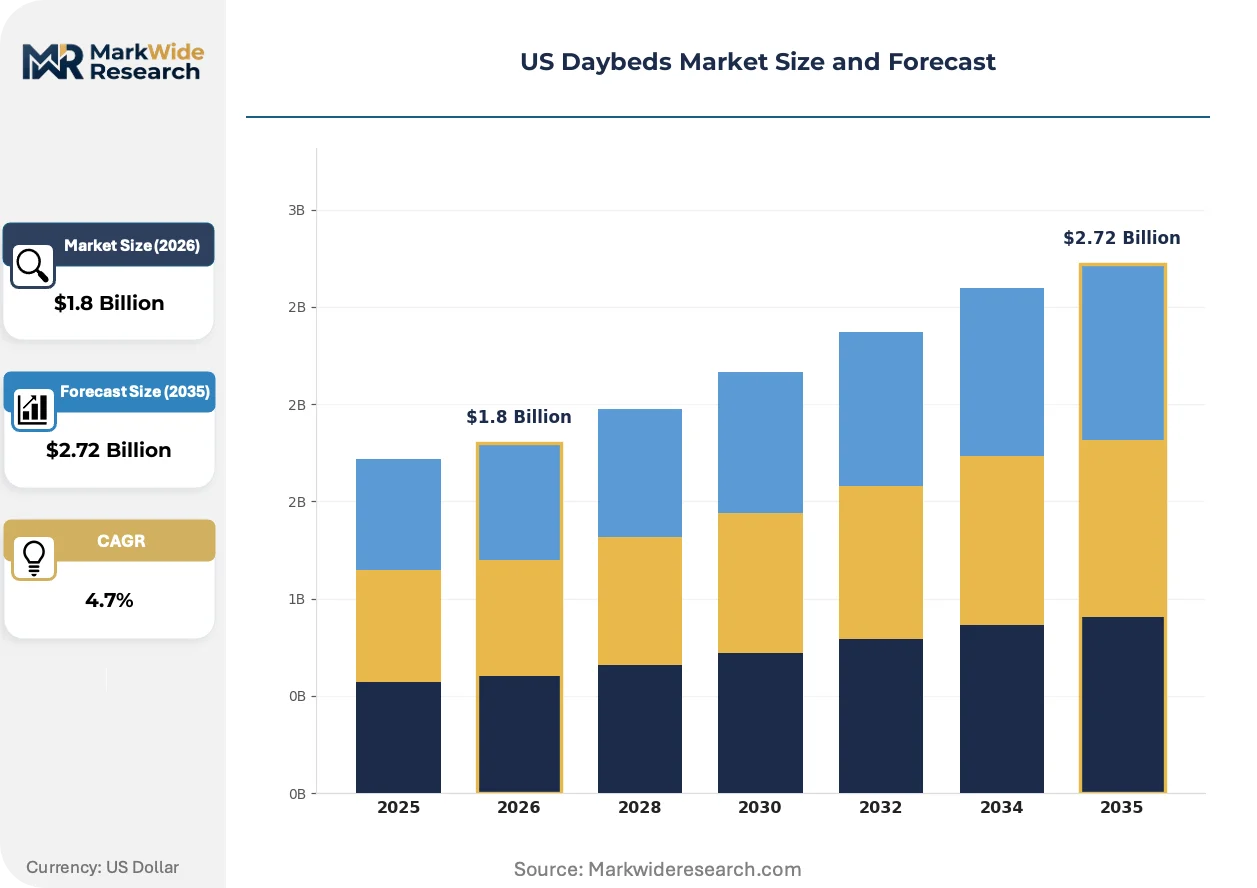
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Metal, Upholstered, Futon End User: Residential, Hospitality, Healthcare, Educational Size: Single, Twin, Full, Queen Distribution Channel: Online, Retail, Specialty Stores, Direct Sales |
| Companies Covered | Ashley Furniture Industries Inc., Brown Jordan Inc., Inter IKEA Systems BV, Home Depot Product Authority LLC, Century Furniture LLC, Herman Miller Inc., Lowe's Companies Inc., Williams-Sonoma Inc., West Elm, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Daybeds Market Trends and Innovations
Frame construction and distribution models are converging around sustainability verification and channel compression, with regulatory pressure and buyer sophistication accelerating technical and commercial innovation cycles.
Knockdown steel tube framing with tool-free assembly hardware is modularizing logistics for e-commerce fulfillment. Online furniture retailers are specifying these systems to reduce damage rates and return processing costs. The shift is compressing traditional wholesale distribution tiers and forcing regional warehouse operators to add final-mile white-glove services.
EPA enforcement of TSCA Title VI composite wood formaldehyde limits is restructuring panel sourcing decisions. Domestic mills with CARB Phase II certification are capturing share from import-reliant competitors. Upholstered daybed producers in California and the Northeast are reformulating adhesives and facing materials to maintain single-SKU national distribution.
Buyers are consolidating purchases through interior design subscription platforms that bundle furniture selection with spatial planning software. These channels are displacing traditional furniture gallery traffic in metropolitan markets. The pattern is most pronounced in Seattle and Austin, where tech-sector households favor curated procurement over showroom browsing.
US Daybeds Market Segmentation
Daybed procurement patterns diverge sharply between residential buyers prioritizing aesthetic longevity and commercial operators optimizing for replacement cycles. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume flows.
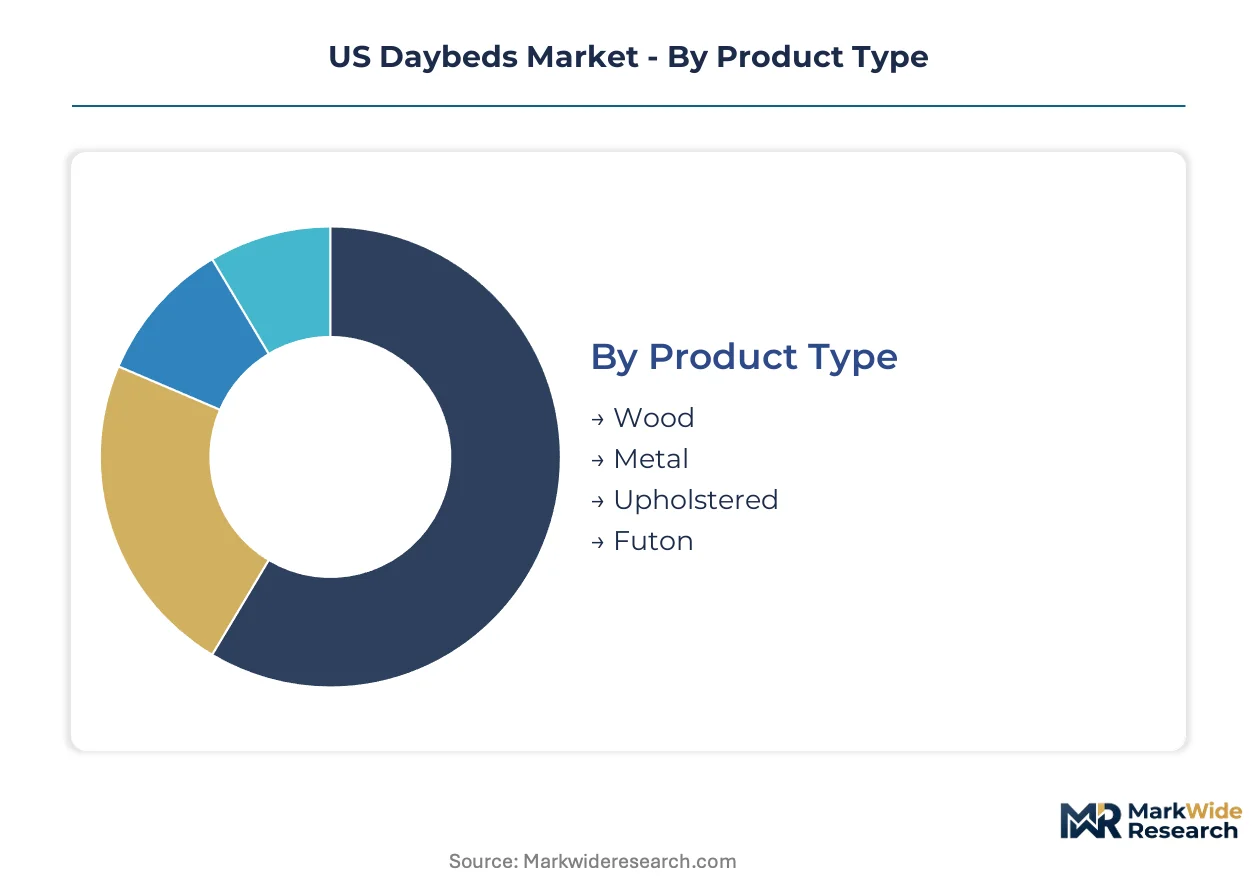
Product Type:
Frame construction technology determines durability certification, upholstery compatibility, and compliance pathway under EPA TSCA Title VI.
- Upholstered:Fabric-wrapped foam or spring-supported platforms with customizable sizing drive the highest average order values. California and Florida vacation rental operators specify marine-grade upholstery for outdoor lounge concepts, creating steady replacement demand.
- Wood:Slatted hardwood or composite panel frames employing mortise-and-tenon joinery serve residential buyers in Texas Hill Country and Colorado mountain towns where heirloom-grade aesthetics influence purchase decisions. White oak and walnut price volatility from Great Lakes sawmill disruptions compress margin predictability.
- Metal:Powder-coated tubular steel construction dominates hospitality procurement for durability and faster replacement cycles. Tool-free knockdown assembly hardware reduces damage rates in e-commerce fulfillment.
- Futon:Convertible bi-fold frames with cotton or foam mattresses occupy entry-level residential positioning. Arizona and Nevada multi-family housing developers specify these for furnished rental units.
Upholstered leads on scale; metal leads on momentum.
End User:
Application context dictates load standards, warranty terms, and procurement channel preferences across distinct operational environments.
- Residential:Individual households purchasing through retail or online channels prioritize design coherence with existing furniture. Seattle and Austin tech-sector buyers favor curated interior design subscription platforms over showroom browsing.
- Hospitality:Hotels, resorts, and Airbnb hosts in Florida and Arizona source weather-resistant outdoor daybeds through direct-to-builder channels. Powder-coated frames and hospitality-grade upholstery withstand high-turnover usage.
- Healthcare:Assisted living facilities and rehabilitation centers specify institutional-grade frames meeting CPSC structural stability standards. Medicare reimbursement patterns influence capital equipment budgeting cycles.
- Educational:University housing offices and dormitory contractors procure durable, low-maintenance units for student common areas. California public institutions add Proposition 65 compliance layers to upholstered component specifications.
Hospitality leads on scale; residential leads on momentum.
Size:
Dimensional standards align with mattress industry conventions while accommodating space constraints in urban and vacation property markets.
- Twin:Approximately 75-inch length serves children's rooms, guest nooks, and compact urban apartments. New York and San Francisco micro-unit developers specify these for convertible living-sleeping zones.
- Full:Wider sleep surface accommodates adult guests and couples in second-home settings. Gulf Coast vacation rental platforms in Texas prioritize full-size daybeds for indoor-outdoor flexibility.
- Queen:Maximum residential dimension supports primary sleep use in studio apartments and guest suites. Premium upholstery upgrades drive margin expansion in this segment.
- Single:Narrowest profile suits narrow corridors and institutional hallway seating. Healthcare facilities specify these for waiting area configurations.
Twin leads on scale; full leads on momentum.
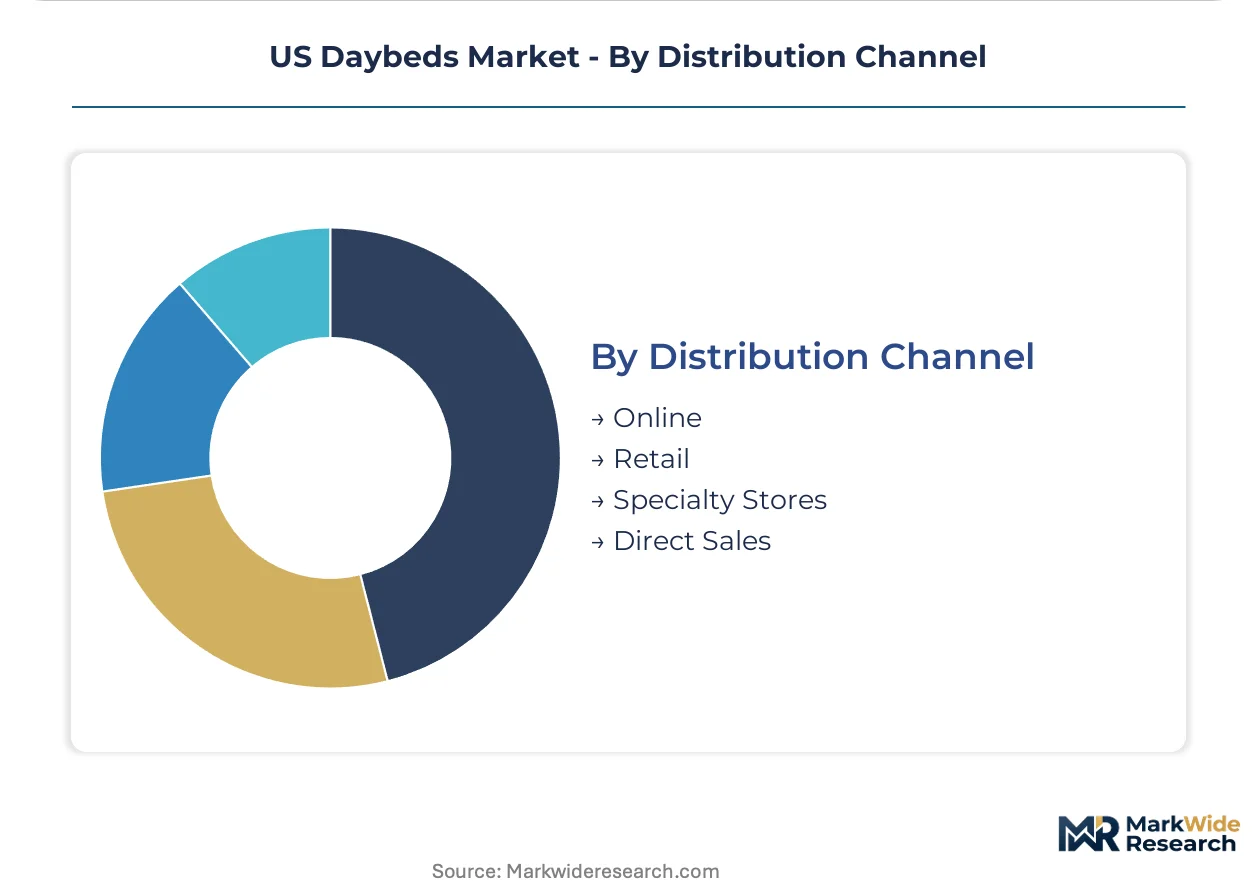
Distribution Channel:
Channel structure determines price realization, customer acquisition cost, and final-mile service obligations.
- Online:E-commerce retailers specify knockdown steel framing to reduce return processing costs. The shift compresses traditional wholesale distribution tiers and forces regional warehouse operators to add white-glove assembly services.
- Retail:Furniture galleries and big-box stores maintain tactile evaluation advantages for upholstered products. Foot traffic displacement in metropolitan markets pressures this channel's relevance.
- Specialty Stores:Design-focused boutiques in coastal California and Florida cater to vacation rental investors seeking curated outdoor lounge collections. Higher service intensity supports premium pricing.
- Direct Sales:Custom home developers in Colorado and Utah bypass retail markup by sourcing through regional millwork distributors. B2B volume contracts lock in multi-project pricing.
Online leads on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High Point, North Carolina anchors the nation's upholstered furniture workforce, with generations of sewing and tufting specialists concentrated in the Piedmont Triad. This labor pool underpins domestic production capacity for premium daybed lines. Regional demand patterns diverge sharply between coastal vacation property markets and inland residential renovation corridors.
California
Vacation rental investors in Los Angeles and Palm Springs drive outdoor lounge daybed procurement with marine-grade upholstery specifications. The California Air Resources Board enforces CARB Phase II formaldehyde emission standards that exceed federal TSCA Title VI baselines, compelling manufacturers to reformulate composite wood components. Bay Area interior design subscription platforms are displacing traditional furniture gallery traffic through curated procurement bundles.
Florida
Airbnb and Vrbo hosts across Miami-Dade and Orlando metro areas source weather-resistant powder-coated frames for high-turnover poolside installations. The state's building code amendments for hurricane-resistant outdoor structures influence frame engineering specifications. Tampa Bay contractors specify configurable daybed systems for residential deck renovation projects tied to second-home investments.
Texas
Hill Country and Gulf Coast vacation property development outpaces national averages, creating demand for transitional-style daybeds suited to indoor-outdoor flexibility. Texas state tax incentives for residential construction equipment indirectly support furniture upgrade cycles in new-build vacation rentals. Austin tech-sector households favor curated procurement platforms over traditional showroom browsing, compressing retail channel relevance.
Colorado
Custom home developers in Denver and Boulder metro areas bypass retail markup by sourcing daybeds through regional millwork distributors. The Colorado Department of Public Health and Environment maintains aligned formaldehyde emission monitoring that facilitates compliant wood panel sourcing from domestic mills. Mountain town residential buyers prioritize heirloom-grade hardwood aesthetics that withstand altitude-driven wood movement.
New York
Micro-unit developers in Manhattan and Brooklyn specify twin-size daybeds for convertible living-sleeping zones in sub-400-square-foot apartments. New York State's extended producer responsibility frameworks for furniture waste influence end-of-life design considerations. Hudson Valley second-home owners drive full-size daybed demand for guest suite configurations in renovated barn and carriage house properties.
US Daybeds Market Competitive Landscape
Top-tier vendors anchor the premium design tier, while mass-market assemblers compete on fulfillment speed and price accessibility. The vendor base stratifies across three functional tiers: vertically integrated manufacturers with captive wood panel supply, import-dependent assemblers sourcing knockdown metal frames, and curated lifestyle brands selling through owned direct channels. Dominant competitive moves include backward integration into certified composite wood production and expansion of white-glove final-mile assembly networks.
Within the mass-market tier, Ashley Furniture Industries Inc. and Inter IKEA Systems BV exemplify scale-driven operational models. Among design-forward specialists, Williams-Sonoma Inc. and West Elm occupy positions emphasizing sustainably sourced materials and owned-channel distribution. Brown Jordan Inc. represents the outdoor hospitality specialist archetype, with Century Furniture LLC anchoring heirloom-grade residential positioning.
| Leading Market Players |
|---|
| Ashley Furniture Industries Inc. |
| Brown Jordan Inc. |
| Inter IKEA Systems BV |
| Home Depot Product Authority LLC |
| Century Furniture LLC |
| Herman Miller Inc. |
| Lowe's Companies Inc. |
| Williams-Sonoma Inc. |
| West Elm |
| Others |
Pricing and Supply Chain Analysis
White oak lumber price volatility from Great Lakes sawmill disruptions cascades through three distinct pricing tiers, compressing margin pools for heirloom-grade wood frames while accelerating commoditization in powder-coated metal units sourced through Vietnam and Malaysia.
Pricing Analysis
The bundled-versus-unbundled service split separates premium upholstery lines with white-glove assembly from knockdown metal frames sold through self-serve e-commerce channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under EPA TSCA Title VI and customization depth. Price differentiation hinges on CARB Phase II compliance status and after-sales service bundling. Pricing pressure stems from hardwood input cost swings, with hospitality buyers in Florida and Arizona exhibiting highest price sensitivity while Colorado custom home developers tolerate premium positioning for heirloom aesthetics.
Supply Chain Analysis
Domestic-content mandates under EPA TSCA Title VI are reshaping sourcing decisions, rewarding captive panel supply from certified Great Lakes mills while penalizing import-reliant assemblers. Manufacturing concentrates in Vietnam, Malaysia, and domestic Piedmont Triad upholstery clusters. Raw material dependencies span white oak and walnut lumber, CARB-certified composite panels, and marine-grade upholstery textiles. Supply chain risk centers on customs inspection backlogs at Long Beach and Savannah ports. Distribution runs through compressed e-commerce fulfillment networks with regional white-glove final-mile augmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA TSCA Title VI enforcement creates durable competitive moats for compliant domestic manufacturers.
For Market Incumbents: To counter import-dependent assembler price erosion, secure captive supply of CARB Phase II certified composite panels and expand white-glove final-mile assembly networks in Texas Hill Country and Colorado mountain corridors. Backward integration into certified wood production anchors margin defense against Vietnamese panel cost volatility. For New Entrants and Emerging Players: Direct-to-builder digital channels unlock B2B volume contracts with Colorado and Utah custom home developers bypassing retail markup. Target Texas Gulf Coast vacation rental platforms for transitional-style indoor-outdoor daybed procurement. White-space concentration sits in hospitality-grade upholstery with marine certification for Florida poolside installations. For Investors and Strategic Acquirers: Consolidation pressure builds where upholstery craft labor scarcity in North Carolina and Mississippi outpaces trade program replenishment. Long-term viability favors vertically integrated manufacturers with captive panel mills and certified supply chains. Watch EPA certifier backlog durations as inflection signal for product launch velocity differentials.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Panel Production | Captive CARB Phase II supply locks in margin predictability against import volatility. |
| White-Glove Final-Mile Network Expansion | Differentiated service tier captures premium pricing from Colorado custom home developers. |
| Direct-to-Builder Channel Development | Bypassing retail markup secures multi-project B2B volume contracts in Utah and Colorado. |
| Marine-Grade Upholstery Certification Investment | Florida and Arizona hospitality procurement specifications mandate weather-resistant fabric tiers. |
| Upholstery Craft Workforce Pipeline Development | North Carolina and Mississippi training partnerships address retiring specialist scarcity. |
Research Methodology
Direct dialogue with upholstery manufacturing executives, hospitality procurement directors, custom home developers, and EPA compliance officers grounded qualitative findings in operational reality. Secondary validation drew from EPA TSCA Title VI certification databases, CARB Phase II compliance registries, customs import records, and furniture industry trade association filings. Bottom-up and top-down triangulation cross-checked manufacturer capacity estimates against end-user demand signals.
Bottom-up modeling aggregated individual product line forecasts across frame construction technology, end-user segment, and regional demand cluster dimensions. Top-down validation referenced macroeconomic indicators for residential construction and vacation rental investment activity. CAGRs derived from segment-level volume and value build-ups across the projection horizon. Industry-specific inputs included hardwood lumber price indices, EPA certifier backlog durations, and hospitality replacement cycle frequencies.
The model assumes a particular technology adoption path; alternative pathways for knockdown steel tube framing with tool-free assembly would alter the outlook if e-commerce damage rates fall faster than projected. Forecasts reflect assumptions regarding regulatory enforcement intensity, trade route stability, and upholstery labor pipeline replenishment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Global Mattress Market
Bedroom Furniture
Heated Bedding Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Bunk Beds Market
Bedroom Furniture
US Wall Beds Market