
 Indonesia Home Furniture Market | 2026-2036
Indonesia Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Home Furniture Market Foresight
Digital design-to-manufacture integration is fragmenting traditional furniture production workflows across Indonesia. PT Integra Indocabinet leverages automated CNC routing to sustain precision output at scale for export-grade cabinetry. IKEA Indonesia anchors its competitive position through centralized distribution control and flat-pack logistics expertise. PT Chitose Internasional Tbk differentiates via specialized metal-frame seating lines targeting hospitality procurement channels.
Indonesia home furniture encompasses movable household fixtures constructed from wood, metal, plastic, or glass composites, typically finished with lacquers, veneers, or powder coatings to meet dimensional stability and surface durability specifications; these products serve residential, hospitality, commercial, and educational environments by providing functional spatial organization and ergonomic support. Wood material segments dominate volume due to Indonesia's tropical hardwood access and established Jepara carving craftsmanship clusters, though metal frames are gaining traction in hospitality fit-outs requiring fire-resistance compliance. Seating and storage categories lead residential demand as apartment dwellers in Jakarta prioritize space-efficient configurations, while e-commerce distribution channels are expanding fastest among urban millennials seeking direct-to-home assembly services.
Indonesia's National Standardization Agency (BIS equivalent functional descriptor: BSN/SNI framework) mandates SNI certification for wood furniture safety and formaldehyde emission limits, compelling domestic mills to upgrade finishing processes or lose retail access. The Ministry of Environment and Forestry enforces timber legality verification through SVLK certification, which shapes export eligibility to European markets operating under EUDR due diligence requirements. Stakeholders must monitor evolving SNI test protocol expansions into metal and plastic furniture categories, as regulatory scope broadening would force material diversification investments ahead of compliance deadlines.
Market Dynamics
Indonesia's SNI mandatory certification for wood products is compressing supply-side capacity as domestic mills absorb capital costs for finishing-line upgrades and formaldehyde testing infrastructure. This regulatory compression is redistributing volume toward certified producers with verified SVLK timber chains.
Growth Catalysts
- SVLK Certification Alignment:The Ministry of Environment and Forestry timber legality verification unlocks European market access under EUDR due diligence requirements, pulling export-grade production toward verified sustainable sourcing.
- Modular Storage Demand:Apartment dwellers in Greater Jakarta and Surabaya are prioritizing space-efficient configurations as middle-class housing stock expands fastest in Java's urban corridor.
- CNC Routing Automation:Automated manufacturing is enabling precision output at scale for cabinetry segments, collapsing batch-size minimums that previously constrained custom furniture production.
Market Restraints
- Tropical Hardwood Supply Concentration:Jepara carving clusters and Kalimantan mills dominate certified timber access, creating bottleneck risk for non-integrated furniture producers lacking captive plantation supply.
- SNI Compliance Capital Intensity:Mandatory certification for formaldehyde emission limits forces domestic mills to upgrade finishing processes or forfeit retail distribution channels entirely.
- Metal-Frame Substitution Threat:Hospitality fit-outs are pivoting toward fire-resistant metal seating lines, eroding wood's traditional dominance in commercial procurement specifications.
Strategic Opportunities
- E-Commerce Direct Assembly:Urban millennials across Bandung and Jakarta are bypassing traditional retail for direct-to-home furniture with bundled assembly services, opening channel margin capture for digital-native brands.
- Metal and Plastic SNI Expansion:BSN protocol broadening into non-wood categories creates first-mover advantage for diversified material producers ahead of compliance deadlines.
- Hospitality Procurement Specialization:Fire-resistance-compliant metal-frame seating lines target hotel and restaurant fit-out channels underserved by traditional wood-centric domestic suppliers.
Industry Challenges
- Digital Design-Manufacture Integration:Traditional furniture workflows fragment as CAD-to-CNC pipelines require retraining of Jepara artisan clusters accustomed to manual pattern replication.
- Certification Timeline Compression:SVLK and SNI parallel audit requirements strain quality-control staffing at mid-cap mills lacking dedicated compliance departments.
- Flat-Pack Logistics Expertise Gap:Domestic producers struggle to match centralized distribution control and packaging optimization standards set by international retailers operating in Indonesian urban markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Home Furniture Market |
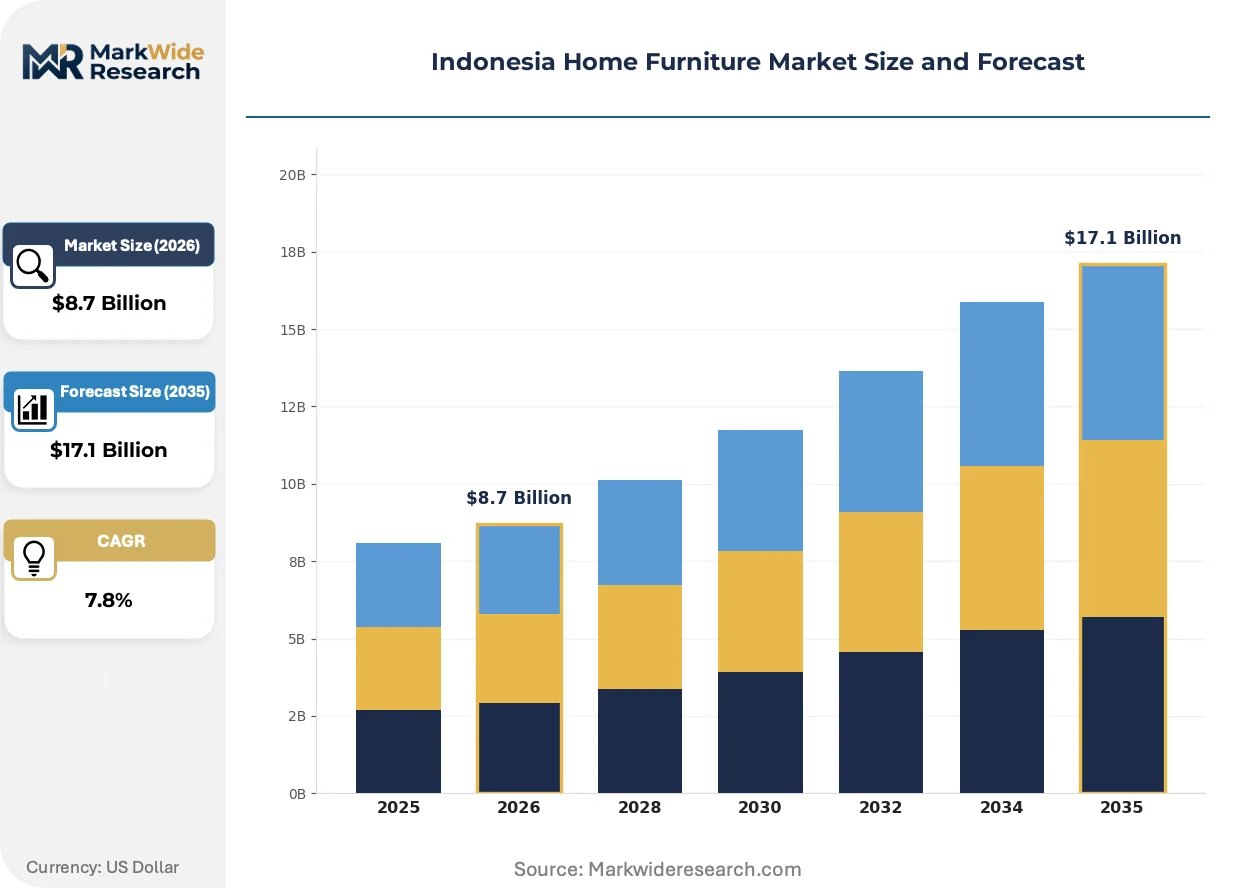
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Tables, Storage, Beds Material: Wood, Metal, Plastic, Glass End User: Residential, Hospitality, Commercial, Educational Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | PT Panca Anugrah Wisesa, PT Surya Pertiwi, Raisa House of Excellence, PT Chitose Internasional Tbk, PT Boston Furniture Industries, IKEA Indonesia, PT Integra Indocabinet, PT Dewata Furniture, Daya Intiguna Yasa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Home Furniture Market Shifts & Advancements
Digital fabrication tools and regulatory material mandates are actively restructuring how Indonesian furniture moves from design to household installation. Three converging developments are compressing traditional production timelines and redistributing competitive advantage across the value chain.
Parametric design software paired with automated CNC routing is collapsing the gap between custom specifications and mass-production economics. Residential buyers in Jakarta's apartment sector are specifying modular dimensions through online configurators. This capability compression is eroding the historical trade-off between artisan customization and factory throughput.
BSN's expansion of SNI test protocols into metal and plastic furniture categories is forcing material diversification investments ahead of formal compliance deadlines. Domestic mills with captive timber certification face parallel capital allocation decisions for non-wood production lines. Metal-frame seating producers targeting hospitality channels are accelerating laboratory testing partnerships to secure preemptive certification.
Millennial households in Surabaya and Bandung are unbundling furniture purchase from retail showroom visits, completing entire transactions through mobile-optimized platforms with embedded assembly scheduling. Traditional distributor networks in Java's urban corridor are responding with localized last-mile partnerships or ceding share to vertically integrated digital entrants. This channel compression is most visible in seating and storage categories where dimensional standardization supports remote purchase confidence.
Indonesia Home Furniture Market Segmentation
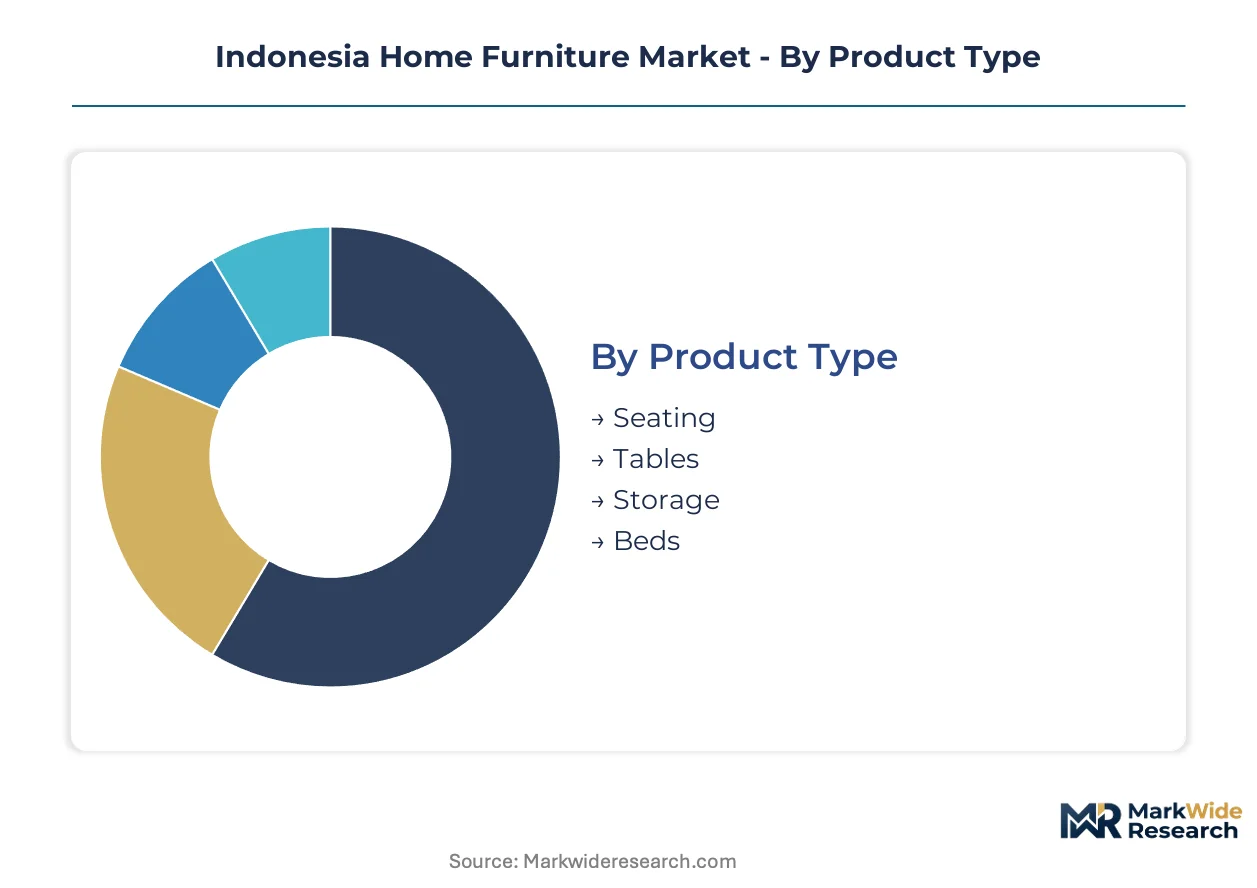
Segmentation reveals how Indonesia's home furniture market fragments across material sourcing constraints, urban housing formats, and channel migration patterns. Each dimension exposes distinct margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Use-case spectrum spans compact apartment living to hospitality fit-outs, with dimensional constraints and fire-safety specifications driving category divergence.
- Seating:Upholstered and frame-based configurations dominate residential procurement in Greater Jakarta, where apartment dwellers prioritize ergonomic support within space-limited floor plans. Metal-frame variants with fire-resistance certification are displacing wood in Surabaya hotel procurement channels.
- Storage:Modular systems with configurable dimensions capture apartment renovation demand across Java's urban corridor, collapsing the historical trade-off between custom carpentry and factory throughput. CNC routing automation enables precision output at batch sizes previously uneconomical for domestic mills.
- Tables:Dining and work-surface configurations serve hybrid home-office arrangements expanding in Bandung's middle-class housing stock.
- Beds:Platform and storage-integrated frames address space efficiency priorities in Jakarta's high-density residential towers.
The dominant share belongs to Seating, while Storage is closing the gap fastest.
Material:
Cost tier stratification separates certified sustainable timber from synthetic alternatives, with regulatory compliance costs redistributing volume toward integrated producers.
- Wood:Tropical hardwood access through Jepara carving clusters and Kalimantan mills underpins volume leadership, though SVLK certification requirements and SNI formaldehyde testing compress supply-side capacity. Certified producers with verified timber chains capture retail distribution channels forfeited by non-compliant competitors.
- Metal:Powder-coated steel and aluminum frames satisfy hospitality fire-resistance specifications eroding wood's commercial procurement dominance. PT Chitose Internasional Tbk anchors specialized production lines targeting hotel and restaurant fit-out channels.
- Plastic:Injection-molded components serve cost-sensitive residential segments and educational institutional procurement with lower durability requirements.
- Glass:Tempered surface elements integrate into premium table and storage configurations for urban millennial households seeking aesthetic differentiation.
Wood retains volume leadership, though Metal is gaining share fastest in commercial applications.
End User:
Customer type determines specification intensity, with hospitality and commercial buyers imposing certification burdens that residential purchasers rarely demand.
- Residential:Apartment dwellers in Greater Jakarta and Surabaya drive modular storage and space-efficient seating demand as middle-class housing stock expands. E-commerce direct-to-home assembly services are displacing traditional retail showroom visits among urban millennials.
- Hospitality:Hotel and restaurant fit-outs in Java's urban corridor specify fire-resistant metal-frame seating lines with SVLK-aligned timber legality verification for European export eligibility under EUDR due diligence requirements.
- Commercial:Office and co-working space operators in Bandung prioritize ergonomic seating configurations with rapid procurement turnaround.
- Educational:Institutional buyers emphasize durability and cost containment over aesthetic specifications, sourcing through consolidated wholesale channels.
Residential commands absolute volume, yet Hospitality is expanding most quickly as tourism infrastructure investment accelerates.
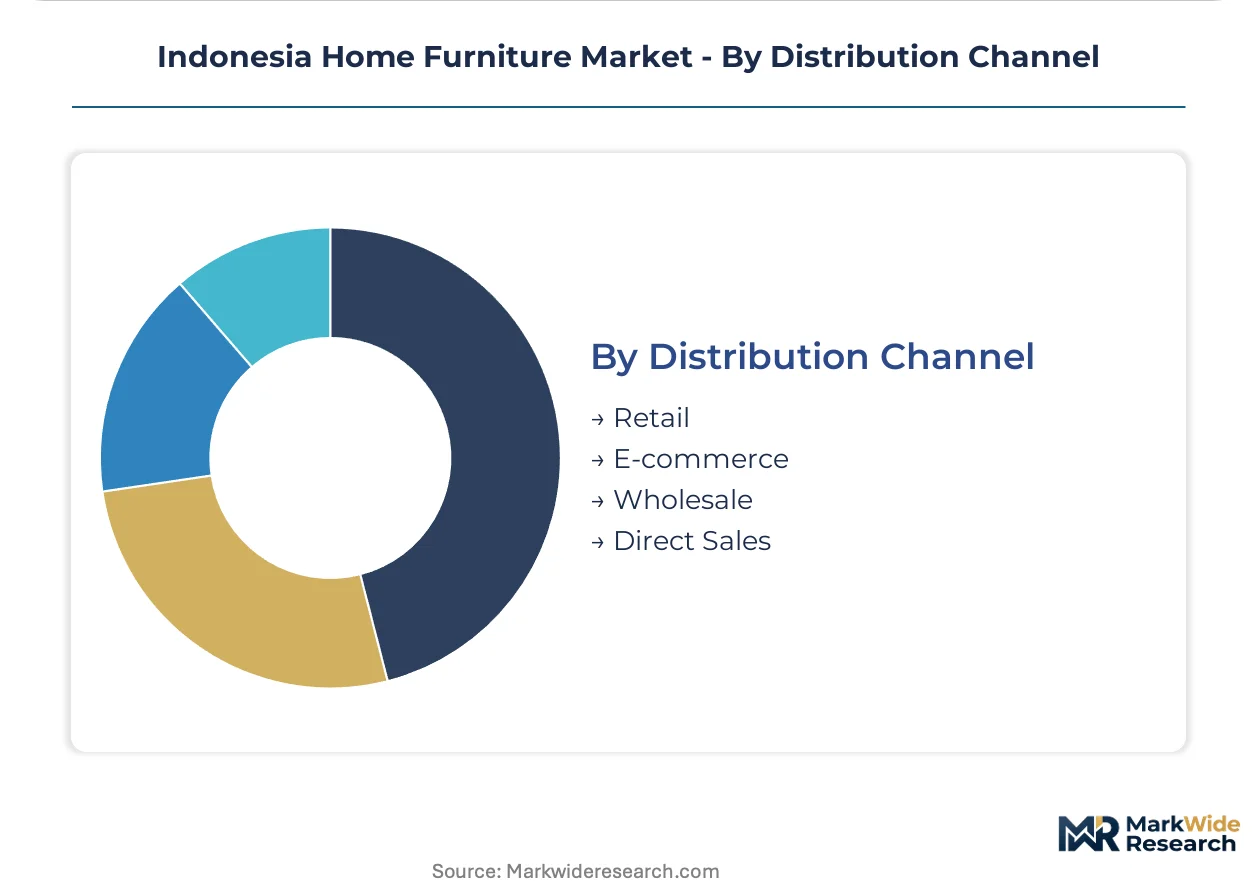
Distribution Channel:
Supply concentration in Java's urban corridor shapes channel economics, with last-mile logistics capabilities determining reach into apartment-dense districts.
- E-commerce:Mobile-optimized platforms with embedded assembly scheduling capture urban millennial transactions across Jakarta, Surabaya, and Bandung. Vertically integrated digital entrants bypass traditional distributor networks through localized last-mile partnerships.
- Retail:Showroom-based purchasing persists among older demographics and high-consideration custom orders requiring tactile evaluation, particularly in Jepara carving cluster proximity.
- Wholesale:Consolidated procurement channels serve educational and commercial institutional buyers with volume pricing and standardized specifications.
- Direct Sales:Manufacturer-to-project relationships dominate hospitality fit-outs requiring specification customization and compliance documentation.
E-commerce is climbing the fastest, while Retail retains the largest transaction value per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in Greater Jakarta and Surabaya concentrate absolute demand, with middle-class housing expansion across Java's urban corridor driving modular storage and space-efficient seating procurement.
Greater Jakarta
Apartment dwellers in Jakarta's high-density residential towers prioritize platform beds with integrated storage and configurable modular systems. BSN's SNI mandatory certification for formaldehyde emission limits forces finishing-line upgrades among Bekasi and Tangerang mills. The Cikarang industrial zone hosts automated CNC routing facilities supplying precision cabinetry to urban renovation contractors.
Surabaya
East Java's hospitality infrastructure investment accelerates fire-resistant metal-frame seating procurement for hotel fit-outs. SVLK timber legality verification administered by the Ministry of Environment and Forestry shapes export eligibility to European markets under EUDR due diligence. Gresik and Sidoarjo manufacturing clusters specialize in powder-coated steel frames targeting commercial procurement channels.
Bandung
Middle-class housing stock expansion in West Java's capital drives hybrid home-office furniture demand among remote-work professionals. Local government industrial zone incentives support furniture manufacturing relocation from saturated Jakarta corridors. The Cimahi sub-district concentrates upholstery workshops serving e-commerce direct-to-home assembly platforms.
Jepara
Traditional carving craftsmanship clusters face workflow fragmentation as CAD-to-CNC pipelines displace manual pattern replication. BSN protocol expansions into metal and plastic furniture categories threaten wood-centric producers lacking material diversification capacity. The Jepara furniture district maintains tropical hardwood access through Kalimantan supply chains, though SVLK certification compresses uncertified mill capacity.
Bali
Tourism-driven hospitality procurement specifies aesthetic differentiation through premium table and storage configurations for villa developments. The provincial government enforces building code alignment with national SNI safety standards for commercial installations. Denpasar and Badung regency manufacturing units serve boutique hotel chains requiring custom specification turnaround.
Indonesia Home Furniture Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Indonesia's home furniture market, creating a tiered structure where scale-driven distributors and material-specific fabricators occupy distinct margin positions. Consolidation pressure concentrates around certified producers with verified SVLK timber chains and SNI-compliant finishing infrastructure. Three archetypes dominate: automated precision manufacturers, hospitality-specialized metal-frame producers, and vertically integrated digital-native brands. Competitive moves center on e-commerce last-mile partnership formation and preemptive laboratory testing for expanded SNI protocol compliance.
Among Indonesia-based fabricators, PT Integra Indocabinet and PT Chitose Internasional Tbk exemplify divergent specialization strategies within the competitive landscape. PT Integra Indocabinet occupies a position representing automated manufacturing archetypes, while PT Chitose Internasional Tbk anchors the metal-frame hospitality specialization tier. IKEA Indonesia represents the channel-control archetype through centralized distribution infrastructure. These three entities collectively illustrate how certification compliance, material diversification, and logistics integration separate viable competitors from capacity-constrained peers.
| Leading Market Players |
|---|
| PT Panca Anugrah Wisesa |
| PT Surya Pertiwi |
| Raisa House of Excellence |
| PT Chitose Internasional Tbk |
| PT Boston Furniture Industries |
| IKEA Indonesia |
| PT Integra Indocabinet |
| PT Dewata Furniture |
| Daya Intiguna Yasa |
| Others |
Supply & Pricing Matrix
The Tanjung Priok port corridor's container handling cost dynamics compress margins for Java-based manufacturers while amplifying price differentiation between SNI-certified exporters and uncertified domestic suppliers. This freight chokepoint concentrates supply-side power among integrated producers with captive finishing infrastructure, forcing price stratification across certification tiers.
Pricing Analysis
Cost-plus contracts with quarterly tropical hardwood indexation dominate procurement between Kalimantan mills and Jakarta distributors. Price differentiation separates SVLK-certified premium grades from standard domestic tiers, with formaldehyde compliance testing adding measurable overhead. Pricing pressure intensifies in metal-frame categories as hospitality buyers consolidate procurement around fire-resistance specifications. Residential purchasers in Surabaya exhibit highest price sensitivity, while hospitality procurement teams prioritize certification documentation over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among Jepara carving clusters, Bekasi CNC facilities, and Gresik powder-coating specialists serving distinct material segments. Raw material flows draw from Kalimantan certified timber plantations, imported steel coil through Tanjung Perak, and regional foam upholstery suppliers. Single-source vulnerability runs through SVLK audit bottleneck capacity at mid-tier mills lacking dedicated compliance departments. Distribution runs through vertically integrated e-commerce platforms, traditional showroom networks in urban corridors, and project-direct channels for hospitality fit-outs.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's home furniture market operates as a service-attach opportunity where bundled assembly and after-sales maintenance contracts expand faster than standalone product sales. Direct-to-home installation services capture margin premiums that hardware transactions alone cannot sustain.
For Market Incumbents: Insulate certified production capacity through preemptive SNI protocol expansion into metal and plastic categories before BSN mandates formal compliance deadlines. Deepen backward integration into Kalimantan plantation supply to secure SVLK-verified timber chains against audit bottleneck risks from competing mills. For New Entrants and Emerging Players: Pursue hospitality procurement white space in Surabaya and Bali where fire-resistant metal-frame specifications outpace domestic supplier capability. Target e-commerce direct assembly in Bandung's remote-work professional segment with mobile-optimized configurators and localized last-mile partnerships. For Investors and Strategic Acquirers: BSN's SNI expansion into non-wood categories reshapes the acquisition landscape toward diversified material producers with laboratory testing partnerships already established. Long-term viability favors automated CNC facilities with CAD-to-manufacture pipelines over traditional Jepara artisan clusters facing workflow fragmentation. Monitor SVLK audit queue lengths at Ministry of Environment and Forestry offices as inflection indicator for supply-side capacity compression.| Strategic Initiative | Industry Significance |
|---|---|
| Automated CNC Routing Deployment | PT Integra Indocabinet leverages precision output at scale for export-grade cabinetry segments. |
| SVLK Certification Preemption | Early audit completion secures European market access under EUDR due diligence requirements. |
| Metal-Frame Production Line Diversification | PT Chitose Internasional Tbk targets hospitality fire-resistance specifications eroding wood dominance. |
| E-Commerce Last-Mile Partnership Formation | Urban millennial demand in Jakarta shifts procurement toward direct-to-home assembly services. |
| SNI Protocol Expansion Preparation | Laboratory testing partnerships for metal and plastic categories create first-mover compliance advantage. |
Research Methodology
The analysis maps seating, storage, tables, and beds segments, each validated through manufacturing plant managers, retail category buyers, hospitality procurement directors, and e-commerce logistics specialists. Primary fieldwork combined structured interviews with secondary triangulation across BSN SNI protocol documentation, Ministry of Environment and Forestry SVLK audit records, customs export filings, and urban housing development permits. Bottom-up production capacity assessments and top-down demand modeling from residential and commercial construction data converge in volume estimates.
Assumptions held SNI certification timeline and EUDR enforcement intensity within observed regulatory patterns while varying urban middle-class housing expansion rates across Java's corridor. The forecast framework segments by material certification grade, end-use procurement channel, and regional manufacturing hub concentration. CAGRs derive from production capacity utilization trends and channel migration velocity. Industry-specific inputs include CNC automation adoption curves and hospitality infrastructure investment pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive certification acceleration by Bekasi and Tangerang mills would shift competitive outcomes beyond modeled parameters. Quarterly review of BSN protocol expansion announcements, SVLK audit queue durations, and e-commerce platform furniture category growth rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
US Contract Furniture and Furnishing Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
GCC Furniture Market
Furniture
France Furniture Market
Furniture
North America School Furniture Market
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Italy Furniture Market
Furniture
Spain Furniture Market
Furniture
Lecterns Market
Furniture
GCC Luxury Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
Global Furniture Market
Furniture
Indonesia Furniture Market
Furniture
Europe Sustainable Office Furniture Market