
 Asia-Pacific Mattress Market | 2026-2036
Asia-Pacific Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Mattress Market Analysis
Smart foam formulation with embedded pressure-mapping sensors is rewriting how manufacturers engineer personalized sleep surfaces. Paramount Bed Holdings leverages its hospital-grade expertise to dominate Japan's therapeutic mattress segment. Kurlon Enterprise Limited anchors South India's dense retail network with localized latex sourcing. Suibao Group competes through vertical manufacturing control across Guangdong's chemical and textile belt.
Asia-Pacific mattresses comprise layered comfort systems—typically polyurethane foam, pocketed coils, or natural latex cores encased in quilted ticking—engineered to distribute body weight across sleep surfaces and regulate thermal transfer. The residential end-user segment leads absolute volume as urban household formation accelerates across Indonesia and Vietnam, while the hospitality segment captures premium margin pools through bulk procurement contracts with international hotel operators. Memory foam product types command pricing premiums in Australia's replacement cycle, whereas innerspring units sustain mass-market penetration in price-sensitive South Asian markets.
Japan's Ministry of Economy, Trade and Industry (METI) enforces stringent flammability standards under JIS regulations, compelling exporters to reformulate foam chemistry for market access. China's State Administration for Market Regulation (SAMR) implements GB standards for mattress labeling and durability disclosure, reshaping how domestic brands communicate product longevity. India's Bureau of Indian Standards (BIS) mandates density and resilience testing, filtering substandard imports from regional trade corridors. Stakeholders must monitor diverging national certification timelines to synchronize production planning with compliance windows.
Market Dynamics
China's tier-one housing renovation cycles and India's BIS certification mandates are compressing product lifecycles while elevating technical entry barriers across the Asia-Pacific mattress supply base.
Growth Catalysts
- Urban household formation:Indonesia and Vietnam are adding residential units at pace, driving replacement mattress demand through first-time buyer channels and bulk developer procurement.
- Hospitality infrastructure investment:Southeast Asian hotel chains are upgrading sleep infrastructure, creating premium contract manufacturing opportunities for foam and hybrid systems.
- India's BIS density mandates:The Bureau of Indian Standards certification for foam resilience is filtering substandard imports and consolidating domestic manufacturing quality tiers.
Market Restraints
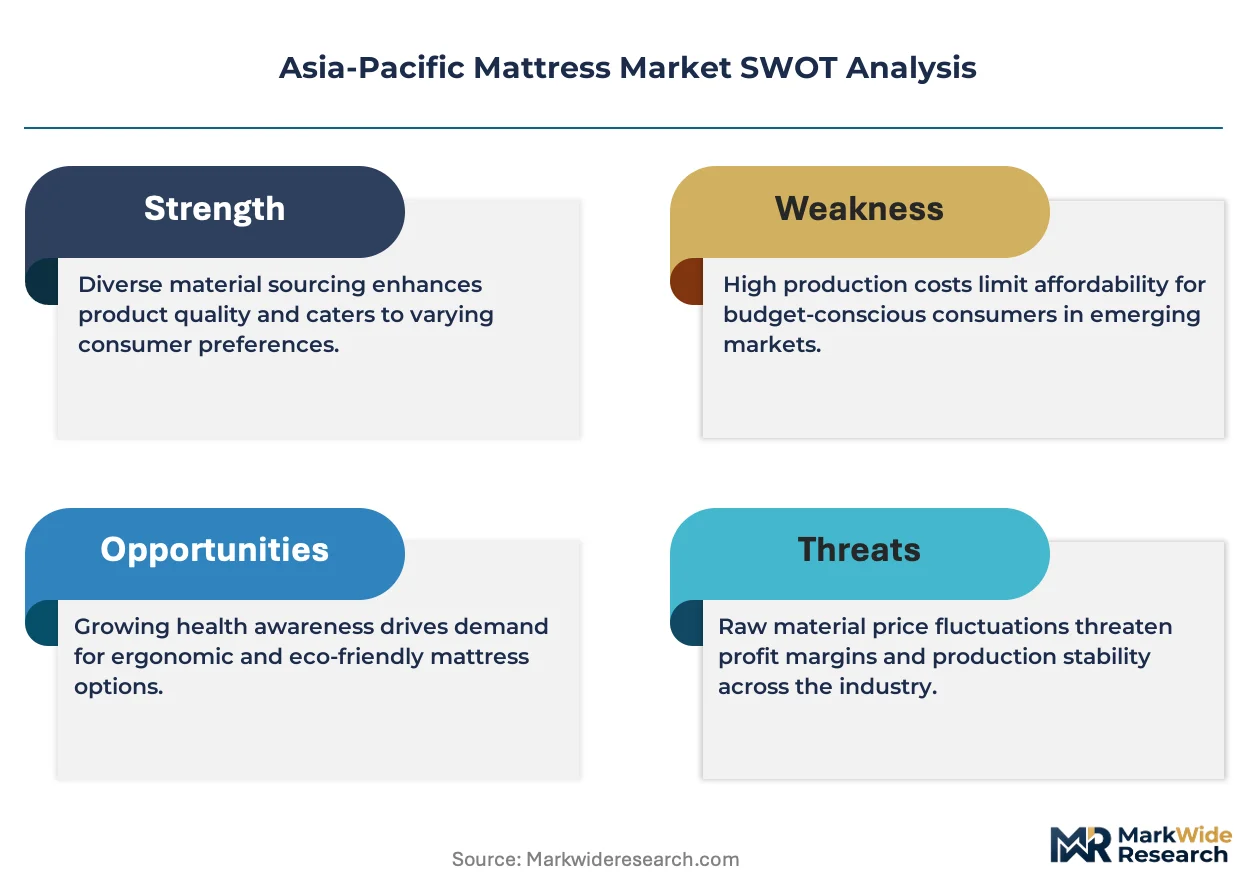
- Polyol and TDI feedstock volatility:Petrochemical input costs for polyurethane foam production swing with crude oil benchmarks, compressing margin visibility for mid-tier manufacturers.
- Guangdong chemical belt concentration:Vertical manufacturing control by Suibao Group and similar integrated players limits component sourcing flexibility for smaller assemblers.
- JIS flammability compliance costs:Japan's METI reformulation requirements for foam chemistry add R&D overhead that deters price-competitive exporters from market entry.
Strategic Opportunities
- Vietnam's underpenetrated premium segment:Natural latex and hybrid coil systems remain nascent in this market, offering first-mover positioning ahead of supply chain maturation.
- Pressure-mapping sensor convergence:Smart foam formulation integrating textile sensors with adjustable base systems is digitizing sleep surface customization for therapeutic applications.
- Australia's compressed replacement cycles:Memory foam product types command pricing premiums as consumers shorten mattress ownership duration, opening direct-to-consumer channel expansion.
Industry Challenges
- Fire safety certification timelines:Diverging national flammability standards across Japan, China, and India require parallel testing protocols that delay regional product launches.
- Skilled foam chemist scarcity:Formulation expertise for open-cell and gel-infused systems concentrates with senior technicians at established Japanese and South Korean manufacturers.
- Legacy innerspring retooling costs:Mass-market South Asian producers face capital intensity when pivoting production lines to pocketed coil or hybrid configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Mattress Market |
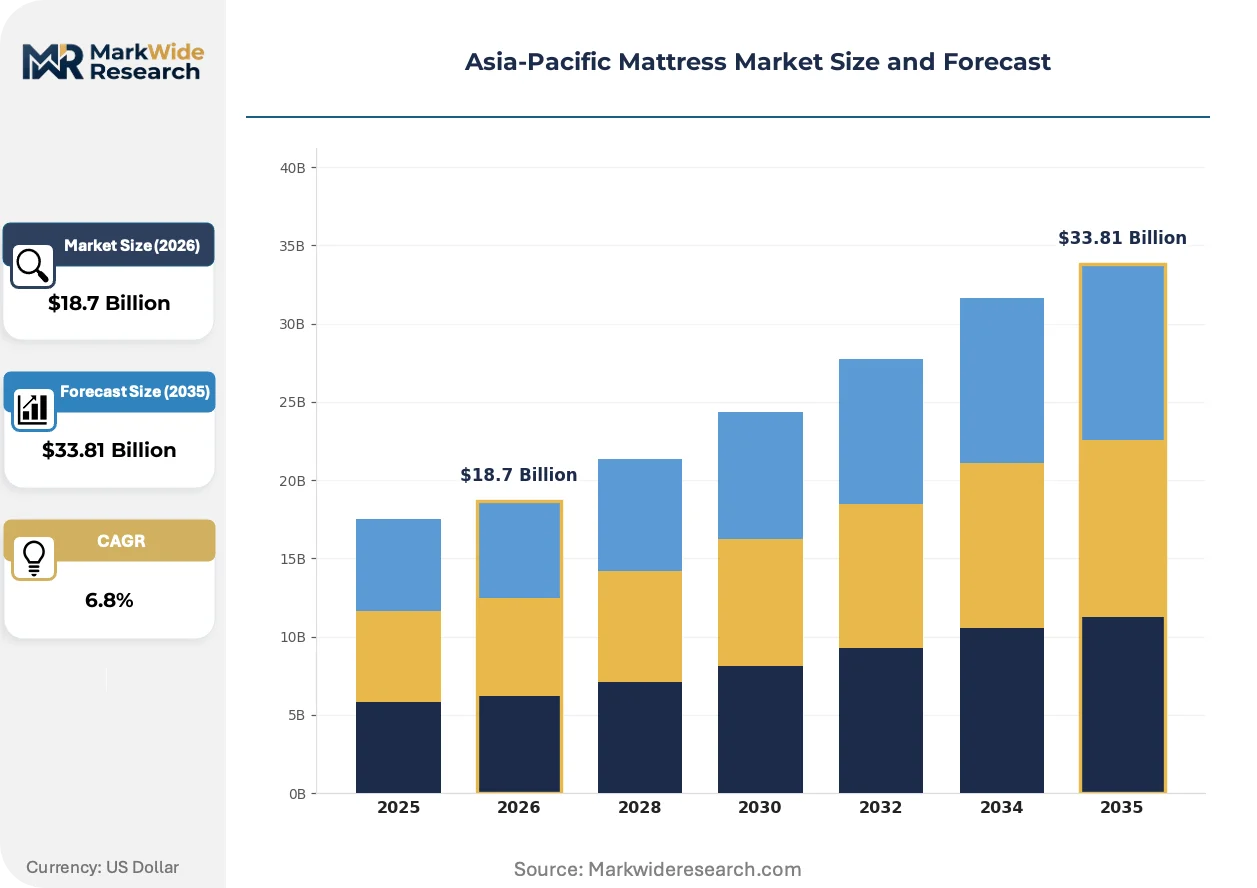
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid End User: Residential, Hospitality, Healthcare, Institutions Size: Twin, Queen, King, California King Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Tempur-Pedic International Inc., Kingsdown Inc., Paramount Bed Holdings Co. Ltd, Select Comfort, Serta Inc., KING KOIL Inc., Kurlon Enterprise Limited, Suibao Group, Sealy Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Mattress Market Emerging Trajectories
Sensor-embedded sleep surfaces and regulatory disclosure mandates are rewriting how manufacturers engineer, label, and distribute mattresses across the Asia-Pacific region.
Smart foam formulation with embedded pressure-mapping sensors is digitizing how manufacturers engineer personalized sleep surfaces. Hospital chains and premium hospitality buyers are adopting these systems fastest, demanding real-time sleep data integration. This compression of customization timelines is forcing mid-tier assemblers to license sensor technology or exit the therapeutic segment entirely.
China's State Administration for Market Regulation has implemented GB standards for mattress labeling and durability disclosure. Manufacturers must now communicate product longevity through standardized testing protocols that reshape domestic brand positioning. Exporters targeting China are reformulating tickings and core densities to meet these documentation requirements ahead of enforcement windows.
Direct-to-consumer channel disintermediation is fragmenting traditional retail dependence across Australia's replacement market. Online mattress-in-a-box brands are capturing urban millennials through compressed delivery logistics and trial-period guarantees. This shift is most visible in Sydney and Melbourne, where showroom traffic has declined while digital-native brands scale warehousing and reverse logistics networks.
Asia-Pacific Mattress Market Segmentation
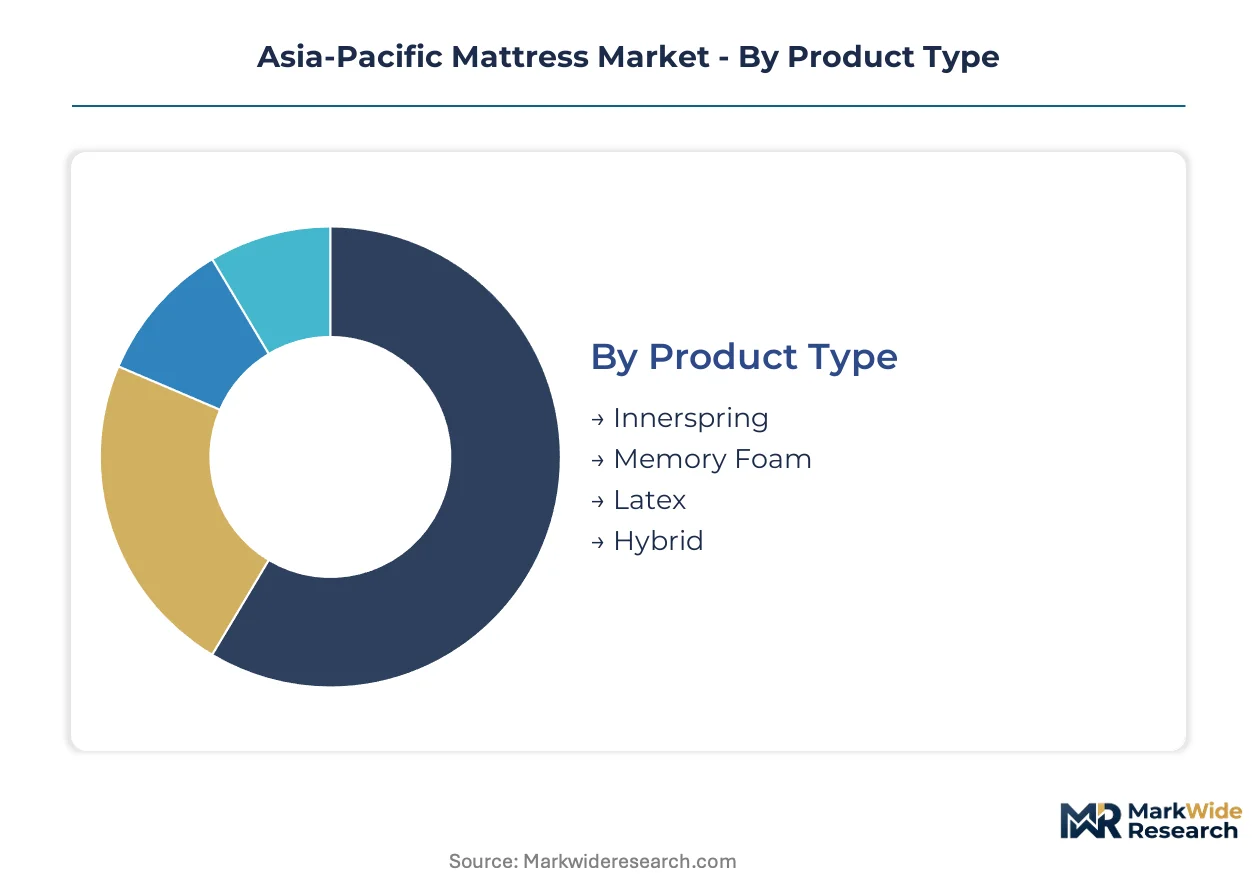
Segmentation in the Asia-Pacific mattress market reveals how product architecture, procurement patterns, and channel economics diverge across consumer and institutional buyers. Understanding these fault lines exposes where margin pools concentrate and where supply chain investments yield defensive positioning.
Product Type:
The use-case spectrum spans mass-market affordability through therapeutic precision, with material science investments determining competitive durability.
- Innerspring:Steel coil support systems with fabric-encased springs deliver familiar bounce and airflow. Price-sensitive South Asian households in India and Indonesia sustain volume through replacement cycles tied to urban household formation.
- Memory Foam:Viscoelastic polyurethane formulations contour to body weight distribution while retaining shape memory. Australia's compressed replacement cycles and premium positioning in Sydney and Melbourne drive margin capture for direct-to-consumer brands.
- Latex:Natural rubber sap or synthetic polymer cores offer resilient support with inherent antimicrobial properties. Kurlon Enterprise Limited anchors South India's supply through localized Kerala rubber sourcing.
- Hybrid:Pocketed coil bases layered with foam or latex comfort zones combine structural support with pressure relief. Southeast Asian hospitality procurement favors these systems for durability under high-occupancy hotel use.
Established volume favors Innerspring; emerging adoption favors Hybrid.
End User:
Procurement scale and specification rigor separate fragmented consumer demand from concentrated institutional contracts.
- Residential:Individual household purchases across first-time buyer and replacement channels. China's tier-one housing renovation cycles accelerate mattress turnover in Beijing and Shanghai.
- Hospitality:Bulk procurement contracts with international hotel operators and regional chains. Southeast Asian destinations from Bangkok to Bali drive premium foam and hybrid specifications for guest sleep infrastructure upgrades.
- Healthcare:Therapeutic surfaces for patient pressure ulcer prevention and recovery positioning. Japan's METI flammability standards and hospital-grade requirements filter supplier eligibility to specialized manufacturers like Paramount Bed Holdings.
- Institutions:Dormitory, military, and correctional facility procurement with durability-focused specifications. India's BIS density mandates reshape competitive eligibility for domestic contract awards.
Residential channels dominate absolute unit throughput; Healthcare commands the steepest expansion trajectory as aging demographics and hospital infrastructure investments converge.
Size:
Spatial economics and household composition dictate dimensional preferences across urban housing stock.
- Twin:Compact single-sleeper dimensions suited to dormitory, children's, and guest room applications. Institutional procurement in Japan and South Korea sustains baseline production runs.
- Queen:Mid-scale dimensions balancing couple accommodation with spatial efficiency. Australian apartment dwellers and Southeast Asian middle-class households favor this configuration.
- King:Expanded width for premium residential and hospitality applications. China's tier-one city renovations and luxury hotel upgrades in Singapore and Hong Kong concentrate demand.
- California King:Extended length for taller sleepers with narrower width than standard King. Niche positioning in Australia's premium replacement market and expatriate-heavy Southeast Asian developments.
Queen dimensions anchor mass-market production planning; King specifications gain share fastest through hospitality premiumization.
Distribution Channel:
Channel selection determines working capital intensity, return logistics burden, and customer acquisition economics.
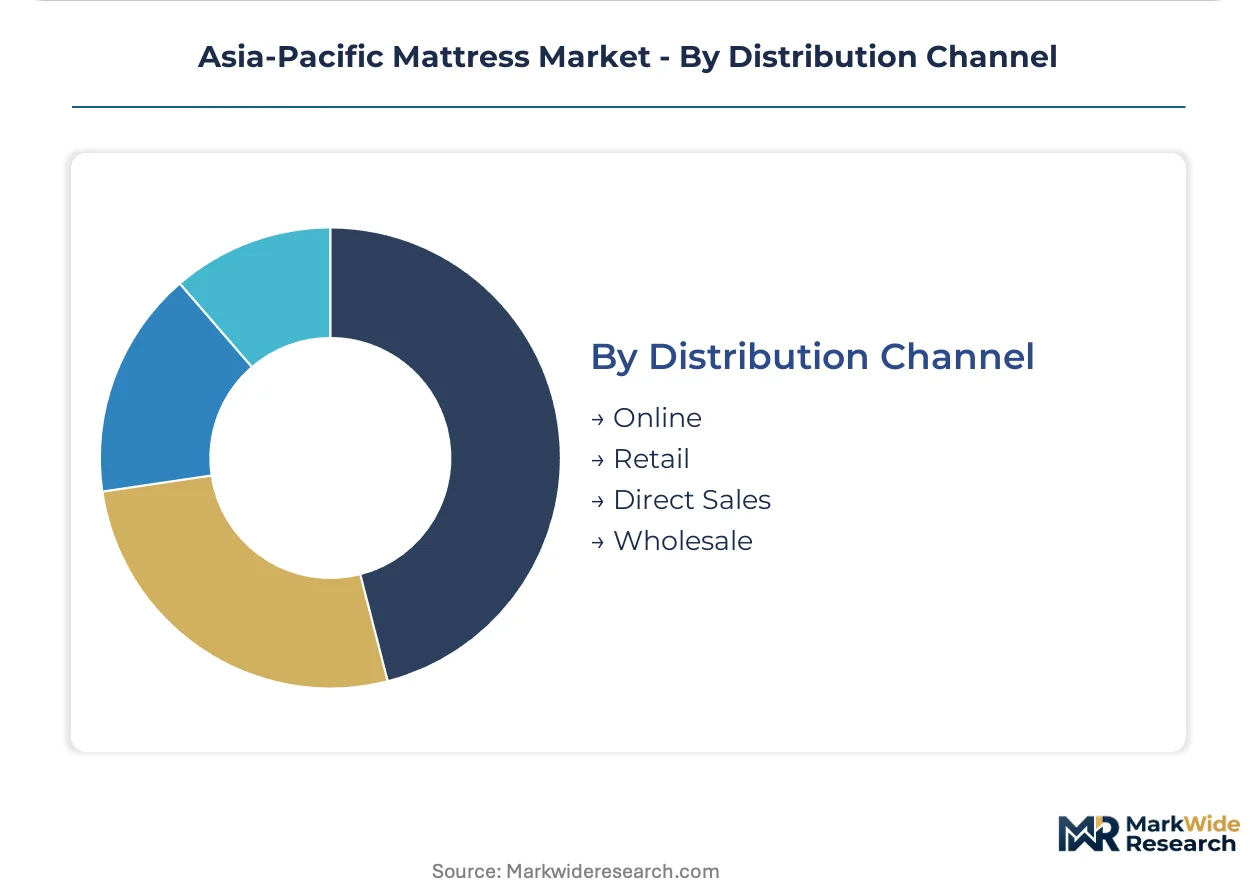
- Online:Mattress-in-a-box compressed delivery with trial-period guarantees. Sydney and Melbourne urban millennials drive Australia's digital-native brand scaling.
- Retail:Physical showroom networks with tactile evaluation and immediate delivery. South India's dense traditional trade sustains Kurlon Enterprise Limited's storefront penetration.
- Direct Sales:Manufacturer-owned channels bypassing wholesale markups. Suibao Group's vertical manufacturing control across Guangdong enables this route for institutional buyers.
- Wholesale:Bulk supply to furniture retailers and hospitality procurement aggregators. Indonesia and Vietnam developer channels for new residential construction rely on this pathway.
Retail maintains defensive positioning in tactile-dependent segments; Online is climbing the fastest as reverse logistics networks mature and trial-period economics stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate around hospitality procurement clusters in Southeast Asia, residential renovation cycles in China's tier-one cities, and therapeutic-grade institutional demand in Japan's hospital networks.
China
Urban housing renovation cycles in Beijing and Shanghai accelerate mattress replacement purchases among middle-class households. SAMR's GB standards for labeling and durability disclosure force domestic brands to reformulate tickings and document product longevity. Guangdong's chemical and textile belt hosts vertically integrated manufacturers controlling foam chemistry through captive polyol supply.
Japan
Hospital chains and aged-care facilities drive therapeutic mattress specifications for pressure ulcer prevention. METI enforces stringent JIS flammability standards that compel foam chemistry reformulation for market access. Osaka and Nagoya industrial corridors concentrate specialized manufacturers with hospital-grade certification expertise.
India
Urban household formation across Mumbai and Delhi-NCR sustains innerspring volume through first-time buyer channels. BIS mandates for foam density and resilience testing filter substandard imports from regional trade corridors. Kerala's rubber belt anchors natural latex sourcing for South Indian manufacturers with localized raw material control.
Australia
Compressed replacement cycles among Sydney and Melbourne urban millennials favor memory foam premium positioning. TGA-equivalent consumer safety frameworks govern product claims without blocking direct-to-consumer channel entry. Melbourne's warehousing and reverse logistics networks enable mattress-in-a-box brands to scale trial-period economics.
Vietnam
Underpenetrated premium segments in Ho Chi Minh City and Hanoi create first-mover openings for natural latex and hybrid systems. Developer procurement for new residential construction runs through wholesale furniture channels rather than retail showrooms. Northern industrial zones near Hai Phong attract foam component suppliers serving regional export markets.
Asia-Pacific Mattress Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented national markets where scale advantages remain geographically bounded. The structure tiers into three archetypes: vertically integrated chemical-textile conglomerates, hospital-grade therapeutic specialists, and digital-native direct-to-consumer brands. Dominant competitive moves include backward integration into polyol and textile supply, plus technology licensing for sensor-embedded smart foam systems.
Among Japan-based therapeutic specialists, Paramount Bed Holdings Co. Ltd exemplifies hospital-grade certification expertise. Within China's vertically integrated tier, Suibao Group occupies a position anchored in Guangdong's chemical belt control. South India's dense retail network representation sits with Kurlon Enterprise Limited, which exemplifies localized latex sourcing archetypes.
| Leading Market Players |
|---|
| Tempur-Pedic International Inc. |
| Kingsdown Inc. |
| Paramount Bed Holdings Co. Ltd |
| Select Comfort |
| Serta Inc. |
| KING KOIL Inc. |
| Kurlon Enterprise Limited |
| Suibao Group |
| Sealy Corporation |
| Others |
Supply Flow & Price Mechanics
Polyol and TDI feedstock volatility tied to crude oil benchmarks compresses margin visibility for mid-tier manufacturers while simultaneously widening spreads between economy innerspring units and premium memory foam systems across the Asia-Pacific mattress supply base.
Pricing Analysis
Cost-plus contracts with polyol indexation dominate bulk hospitality procurement across Southeast Asian hotel chains. Price differentiation hinges on foam density certification tier and geographic delivery cost from Guangdong chemical belt concentration. Pricing pressure intensifies in South Asian mass-market tiers as petrochemical input swings compress assembler margins. Residential replacement buyers in Australia's urban centers exhibit lowest price sensitivity, while Indonesia's first-time household formation channels sustain economy innerspring volume.
Supply Chain Analysis
Export-control restrictions on advanced pressure-sensor technology limit smart foam formulation flows to Japanese therapeutic specialists. Manufacturing gravity centers on China's Guangdong province, South Korea's chemical corridor, and Thailand's natural latex belt. Raw material dependencies include petroleum-derived polyols, TDI isocyanates, and Kerala rubber sap. Single-source vulnerability concentrates in Guangdong's vertically integrated chemical-textile conglomerates. Distribution runs through wholesale furniture channels for Indonesia and Vietnam developer procurement, direct sales for institutional buyers, and compressed logistics for Australia's mattress-in-a-box brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific mattress demand sits in early-cycle expansion as smart foam sensor convergence accelerates therapeutic and hospitality adoption ahead of supply chain maturation.
For Market Incumbents: Build certification moats around BIS density compliance and METI flammability standards to filter price-competitive exporters from India and Japan procurement channels. Deepen captive polyol supply control across Guangdong chemical belt assets. Accelerate sensor-embedded sleep surface R&D to defend therapeutic segment positioning against mid-tier assemblers.
For New Entrants and Emerging Players: Pursue Vietnam's underpenetrated premium segment for natural latex and hybrid coil first-mover positioning ahead of wholesale channel maturation in Ho Chi Minh City and Hanoi. Target Australia's direct-to-consumer mattress-in-a-box channel through Melbourne warehousing partnerships and trial-period guarantee structuring.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated chemical-textile specialists with hospital-grade certification expertise. Five-to-ten year viability hinges on backward integration depth and regulatory compliance infrastructure. Monitor BIS enforcement windows and METI reformulation timelines as inflection signals for competitive eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Foam Sensor Integration | Paramount Bed Holdings leverages hospital-grade expertise to digitize therapeutic sleep surfaces for METI-regulated institutions. |
| Backward Integration into Polyol Supply | Suibao Group's captive chemical production across Guangdong insulates margin visibility from crude oil benchmark swings. |
| BIS Certification Investment | Kurlon Enterprise Limited anchors South India retail density through compliant foam density and Kerala latex sourcing. |
| Direct-to-Consumer Channel Launch | Australian mattress-in-a-box brands scale Melbourne warehousing to capture compressed replacement cycles among urban millennials. |
| Natural Latex Supply Agreement | Vietnam's nascent premium segment attracts first-movers through Ho Chi Minh City developer procurement relationships. |
Methodological Framework
Cross-validation between primary interviews with foam chemists, hospitality procurement managers, and retail channel heads and secondary sources including BIS certification databases, METI JIS standards filings, and customs trade data anchors the qualitative findings. Bottom-up triangulation across product type, end-user segment, and distribution channel dimensions synthesizes with top-down macroeconomic calibration.
Calibration against historical replacement cycle patterns and regulatory enforcement timelines shapes the analytical framework across the projection horizon. Segmentation modeling spans product architecture, procurement scale, channel economics, and regional certification clusters. CAGRs derive from elasticity-adjusted demand curves incorporating urban household formation rates and hospitality infrastructure investment pipelines.
Sensitivities concentrate around polyol price volatility, BIS enforcement acceleration, and METI flammability standard revisions. Forecasts reflect documented assumptions on feedstock cost trajectories and regulatory compliance windows. Material shifts in crude oil benchmarks or certification timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Latin America Mattress Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Home Bedding Market