
 Pillow Cases Market | 2026-2036
Pillow Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Pillow Cases Market Analytics
Subscription-based bedding refresh programs is broadening how pillow cases move from factory to bedroom. American Textile Company leverages its domestic manufacturing footprint to serve hotel chains with rapid replenishment cycles. Brooklinen anchors its direct-to-consumer model through fabric innovation and limited-edition drops. Welspun Group extends its reach via private-label partnerships with mass retailers across North America and Europe.
A pillow case is a removable textile enclosure, typically woven from cotton, linen, microfiber, or satin in thread counts ranging from 200 to 800, designed to shield pillows from soil, moisture, and allergen accumulation while providing a hygienic sleep surface. Cotton dominates unit volume due to breathability and cost accessibility, though satin commands premium positioning in beauty-focused segments marketed for hair and skin benefits. Closure type introduces meaningful operational complexity: envelope styles reduce hardware failure rates in institutional laundering, while zipper configurations appeal to consumers seeking enclosed allergen barriers.
The U.S. Consumer Product Safety Commission and EPA regulate flammability standards and antimicrobial claims in treated textiles, compelling manufacturers to substantiate performance marketing. The EU REACH framework restricts azo dyes and formaldehyde-based finishing agents, elevating compliance costs for exporters serving European hospitality buyers. Stakeholders must monitor evolving state-level chemical disclosure laws and third-party certification proliferation as dual gatekeepers to shelf access and contract eligibility.
Market Dynamics
REACH chemical restrictions and OEKO-TEX certification mandates are forcing textile suppliers to reformulate finishing agents and rebuild dye-house processes, compressing margins for non-compliant manufacturers while rewarding certified producers with hospitality contract eligibility.
Growth Catalysts
- Antimicrobial fabric treatments:EPA-registered silver-ion and copper-infused finishes are gaining traction in healthcare and hospitality procurement specifications, driven by infection-control protocols.
- EU REACH compliance:European hospitality buyers now require full chemical disclosure documentation, creating competitive separation for suppliers with certified supply chains.
- Zhejiang manufacturing cluster:Concentrated dyeing and weaving capabilities in Shaoxing and Ningbo enable rapid sample-to-production turnaround for bulk institutional orders.
Market Restraints
- Cotton price volatility:Raw fiber costs fluctuate with Indian monsoon patterns and Texas drought cycles, squeezing contract manufacturers on fixed-price hospitality agreements.
- Tamil Nadu supplier concentration:Tiruppur's knitted fabric dominance creates single-point vulnerability for buyers dependent on South Indian organic cotton certification.
- Formaldehyde-free finishing:Cross-linking alternatives for wrinkle resistance deliver inferior wash durability, forcing trade-offs between compliance and product lifespan.
Strategic Opportunities
- Saudi hospitality expansion:Giga-project developments under Vision 2030 are generating institutional linen procurement at scale unmatched elsewhere in the Middle East.
- Subscription refresh models:Direct-to-consumer bedding services create recurring revenue streams and predictable demand forecasting for woven cotton suppliers.
- California Proposition 65:State-level chemical labeling requirements are accelerating third-party testing adoption, opening advisory service revenue for certification laboratories.
Industry Challenges
- Dye-house chemist scarcity:Formulation expertise for low-impact reactive dyes is concentrated among aging technicians in European and Japanese technical textile centers.
- Certification timeline compression:OEKO-TEX Standard 100 renewal cycles and REACH SVHC list updates demand continuous compliance monitoring and documentation refresh.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pillow Cases Market |
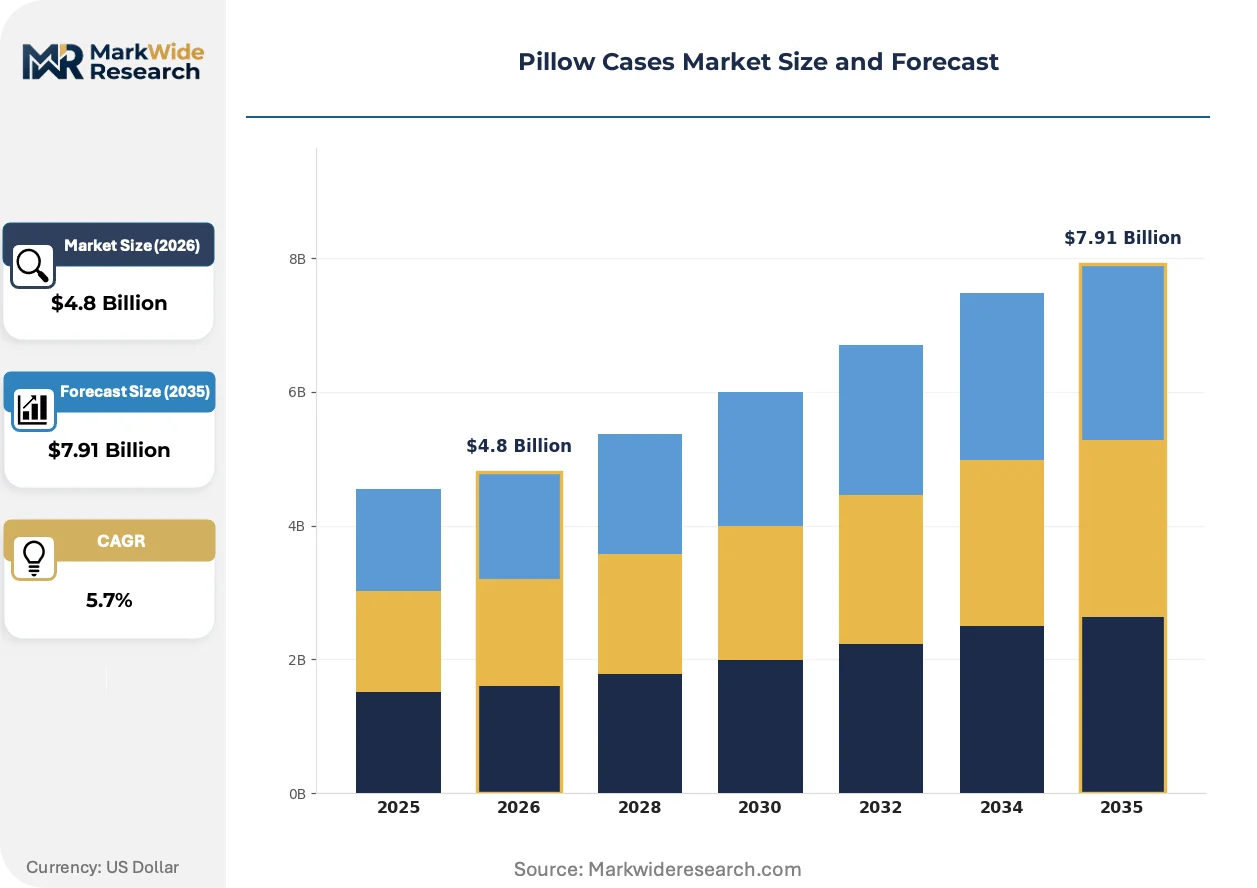
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cotton, Linen, Microfiber, Satin Design Type: Solid, Patterned, Printed, Textured Size: Standard, Queen, King, Body Closure Type: Zipper, Envelope, Button, Velcro |
| Companies Covered | American Textile Company, DZEE Textiles, Welspun Group, Cozy Earth, Brooklinen, Wendre Group, Thomaston Mills, Blissy, Hollander Sleep Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pillow Cases Market Evolving Landscape
Material science breakthroughs and procurement digitization are restructuring how pillow case specifications travel from brand headquarters to factory floor, collapsing traditional sampling timelines and redefining quality assurance checkpoints.
Tencel lyocell fiber is overtaking conventional cotton in premium hospitality sourcing due to superior moisture management and closed-loop solvent recovery credentials. Marriott International and Hyatt procurement teams have elevated lyocell blends to preferred status in 300-thread-count minimum specifications. This shift is compressing demand for long-staple Egyptian cotton while rewarding Austrian and Czech fiber producers with multi-year supply agreements.
REACH Annex XVII restrictions on azo dyes and nickel-releasing fasteners are compelling Asian exporters to maintain dual inventory streams for European and non-European markets. The regulation's 2023 update added four new restricted substances, forcing reformulation of navy and black colorways prevalent in hotel uniform and linen coordination. Tamil Nadu exporters now operate separate dye-house shifts to prevent cross-contamination between compliant and non-compliant batches.
Hotel asset-light management contracts are fragmenting linen procurement authority away from corporate headquarters toward individual property general managers. This decentralization favors regional textile distributors with same-day delivery capability over national contract holders. The pattern is most visible in the United States extended-stay segment, where property-level P&L accountability drives thread-count downgrades and shortened replacement cycles.
Pillow Cases Market Segmentation
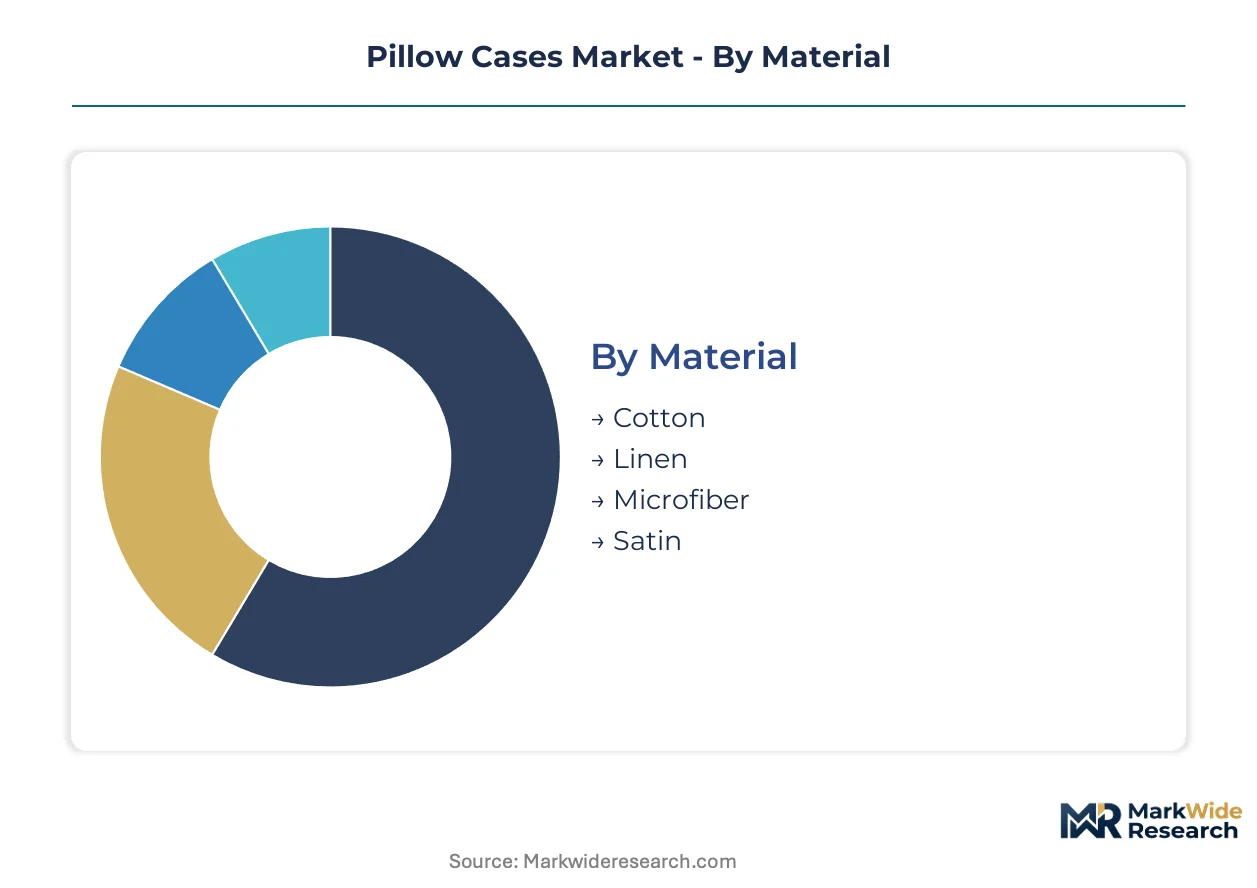
Pillow case procurement specifications diverge sharply between institutional hospitality buyers and direct-to-consumer channels, with material composition and closure mechanics serving as primary qualification filters. Thread count tolerances, laundering durability, and chemical certification status create tiered sourcing requirements that reshape supplier competitiveness across each segment boundary.
Material:
Standalone bedding purchases favor natural fiber transparency and wash-cycle longevity, while embedded hospitality procurement prioritizes bulk uniformity and rapid inventory turns.
- Cotton:Woven from staple fibers in 200-800 thread count ranges, cotton pillow cases dominate institutional procurement due to breathability and cost accessibility. Hospitality buyers in China's Zhejiang province specify long-staple varieties for 150+ wash-cycle durability under commercial laundering protocols.
- Linen:Derived from flax bast fibers with inherent moisture-wicking properties, linen commands premium positioning in boutique hotel portfolios and direct-to-consumer wellness brands. French and Belgian spinning mills control quality-tier supply, constraining volume scalability for mass-market penetration.
- Microfiber:Polyester micro-denier constructions offer synthetic durability at entry price points, capturing value-tier retail and healthcare institutional demand where stain resistance outweighs breathability priorities.
- Satin:Warp-faced weave structures in silk or polyester filament produce low-friction surfaces marketed for hair and skin benefits, anchoring beauty-focused direct-to-consumer segments with limited hospitality adoption.
Cotton leads volumes today; linen is gaining share fastest among premium hospitality repositioning initiatives.
Design Type:
Cost tier stratification separates commodity bulk procurement from brand-differentiated retail positioning, with print complexity directly correlating to margin structure and minimum order thresholds.
- Solid:Undyed or piece-dyed constructions in white, ivory, and institutional neutrals constitute the baseline hospitality specification, minimizing SKU complexity and enabling rapid replacement sourcing across multi-property portfolios.
- Patterned:Woven-in dobby or jacquard structures add tactile differentiation without surface pigment, serving mid-tier retail and select boutique hotel segments where visual coordination justifies 15-25% price premiums over solid equivalents.
- Printed:Rotary or digital pigment application enables seasonal design refreshes and limited-edition drops, concentrating demand in direct-to-consumer channels with compressed production timelines and higher per-unit margins.
- Textured:Seersucker, waffle weave, or garment-washed finishes create tactile differentiation for wellness and lifestyle positioning, with Portuguese and Turkish mills dominating quality-tier supply.
Solid colorways dominate hospitality procurement volumes; printed designs expand most quickly in subscription-based bedding services.
Size:
Application-driven dimensionality aligns with mattress platform standardization in North American and European markets, with regional sizing conventions creating inventory fragmentation for global suppliers.
- Standard:20x26 inch dimensions serve twin and full mattress platforms, capturing entry-level retail and extended-stay hospitality segments where space constraints limit bedding footprint.
- Queen:20x30 inch specifications align with the dominant North American residential mattress size, concentrating direct-to-consumer volume and driving pattern inventory depth for retail assortments.
- King:20x36 inch or 20x40 inch variants address master bedroom and luxury hospitality specifications, with California King dimensions creating additional SKU complexity for West Coast distribution.
- Body:20x54 inch elongated constructions serve maternity, therapeutic, and specialty sleep positioning markets, representing niche volume with concentrated sourcing from orthopedic textile specialists.
Queen sizing anchors North American retail volume; King specifications are climbing the fastest in Saudi hospitality giga-project procurement.
Closure Type:
Customer type and end-use durability requirements dictate hardware selection, with institutional laundering protocols favoring failure-resistant mechanics over consumer-preferred enclosure security.
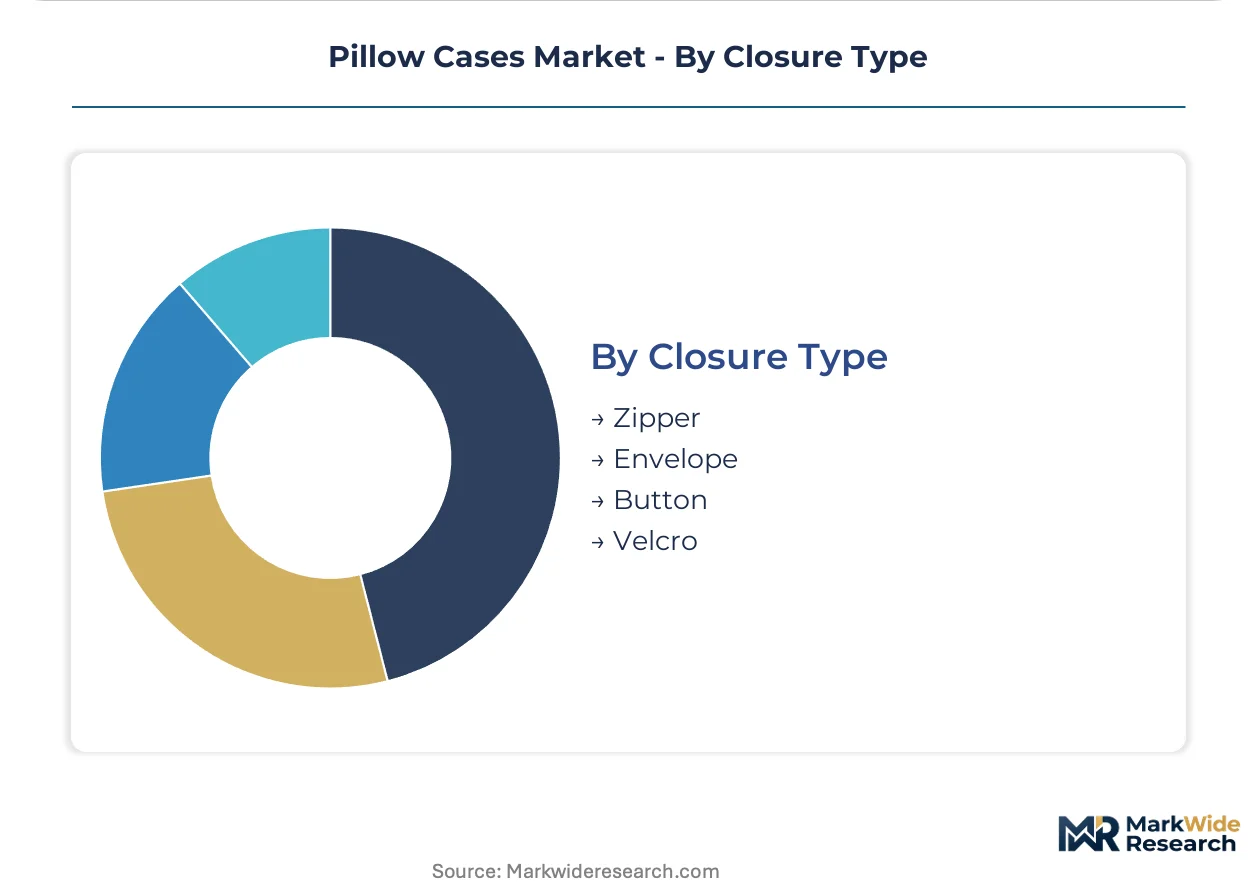
- Zipper:Nylon coil or metal slider configurations provide complete enclosure for allergen barrier applications, dominating healthcare and allergy-sensitive consumer segments despite hardware replacement costs in commercial laundering environments.
- Envelope:Fold-over flap constructions eliminate hardware failure points, capturing hospitality procurement preference for 200+ wash-cycle longevity without zipper maintenance or replacement requirements.
- Button:Mother-of-pearl or corozo fastenings add decorative positioning for premium retail and boutique hospitality, with natural material sourcing constraints limiting volume scalability.
- Velcro:Hook-and-loop fastening serves adaptive and accessibility-focused applications, with limited adoption in mainstream bedding due to fiber entanglement and laundering degradation.
Envelope closures dominate institutional procurement volumes; zipper configurations are gaining share fastest in healthcare and wellness-focused direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Zhejiang province and India's Tamil Nadu belt generate contrasting procurement patterns, with Shaoxing dye-houses serving bulk hospitality contracts while Tiruppur knitters specialize in organic cotton certification for European buyers.
United States
Extended-stay hotel chains and direct-to-consumer subscription services drive cotton and microfiber demand. The EPA regulates antimicrobial claims under FIFRA, compelling silver-ion finish substantiation. Thomaston Mills anchors domestic manufacturing in Georgia, supplying rapid-replenishment cycles for hospitality procurement teams.
China
Zhejiang's Shaoxing and Ningbo clusters command institutional linen production with 150-plus wash-cycle durability specifications. GB standards and MEE environmental enforcement govern dye-house wastewater discharge. The province's concentrated weaving capabilities enable sample-to-production turnaround measured in days for Saudi giga-project orders.
India
Tiruppur's knitted fabric dominance creates single-point vulnerability for organic cotton certification dependent buyers. BIS textile labeling rules and DGFT export incentives shape supplier economics. Tamil Nadu exporters now operate separate dye-house shifts to prevent REACH-compliant batch contamination.
Germany
European hospitality headquarters procurement prioritizes OEKO-TEX Standard 100 and full REACH Annex XVII chemical disclosure. ECHA enforcement of azo dye and formaldehyde restrictions elevates compliance costs for Asian exporters. Importers in Hamburg and Bremen maintain dual inventory streams for compliant and non-compliant European markets.
Saudi Arabia
Vision 2030 giga-projects generate institutional linen procurement at unmatched Middle East scale. SFDA textile safety standards and SASO conformity requirements apply to hospitality imports. NEOM and Red Sea Project developments are contracting multi-year supply agreements directly with Zhejiang manufacturers.
Pillow Cases Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer players capturing premium pricing through fabric innovation while OEM suppliers compete on bulk uniformity and laundering durability. The vendor base concentrates among three strategic archetypes: domestic hospitality contract holders, vertically integrated South Asian textile conglomerates, and digitally native bedding brands. M&A activity targets certification-compliant manufacturing assets, while capacity expansion focuses on lyocell fiber integration and antimicrobial finishing lines.
Among India-based fabricators, Welspun Group occupies a position exemplifying private-label scale, supplying mass retailers across North America and Europe through captive spinning and weaving operations. American Textile Company and Brooklinen represent contrasting archetypes: the former anchors domestic manufacturing for rapid hospitality replenishment, while the latter exemplifies direct-to-consumer model innovation through limited-edition drops and subscription refresh programs. These three entities collectively illustrate the competitive tension between scale efficiency and brand differentiation in procurement channel segmentation.
| Leading Market Players |
|---|
| American Textile Company |
| DZEE Textiles |
| Welspun Group |
| Cozy Earth |
| Brooklinen |
| Wendre Group |
| Thomaston Mills |
| Blissy |
| Hollander Sleep Products |
| Others |
Value Network & Pricing Analysis
Hospitality procurement mandates for OEKO-TEX Standard 100 certification and antimicrobial finishing are compressing supplier margins and forcing dye-house reconfiguration, which elevates price floors for compliant inventory while creating dual-track sourcing complexity for exporters.
Pricing Analysis
Capacity additions in China's Zhejiang province are reshaping price floors for institutional-grade cotton pillow cases. Three-tier pricing structure across premium, standard, and economy levels separates Tencel lyocell blends from long-staple Egyptian cotton and entry-level microfiber. Price differentiation hinges on certification grade and wash-cycle durability specifications. Cost compression in standard-tier cotton contracts is intensifying because of fixed-price hospitality agreements confronting raw fiber volatility. Extended-stay hotel chains exhibit highest price sensitivity; boutique wellness properties show least.
Supply Chain Analysis
Container freight rate volatility between Shanghai and Los Angeles is altering landed cost calculations for Tamil Nadu exporters serving North American retail. Supply concentrates in China's Zhejiang province and India's Tamil Nadu belt, with Portuguese and Turkish mills anchoring premium textured finishes. Raw material flows draw from Texas upland cotton, Indian organic certification clusters, and Austrian lyocell fiber producers. Single-source vulnerability pervades Tiruppur's knitted fabric dominance for European organic cotton buyers. Distribution runs through hospitality contract holders, mass retail private-label programs, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pillow cases function as a stable compounder anchored by recurring institutional replacement cycles and subscription refresh models that generate predictable demand forecasting for woven cotton suppliers.
For Market Incumbents: Deepen backward integration into captive spinning operations to offset margin compression from REACH compliance costs. Secure multi-year lyocell fiber supply agreements with Austrian producers before hospitality procurement specifications fully pivot. Certify additional dye-house capacity for OEKO-TEX Standard 100 to defend contract eligibility against emerging South Asian competitors. For New Entrants and Emerging Players: Regional textile distributors serving decentralized extended-stay property managers represent an underserved buyer archetype bypassed by national contract holders. Saudi giga-project procurement under Vision 2030 offers the most penetrable geography with unmatched institutional volume. Lead with same-day delivery capability and property-level P&L accountability rather than corporate headquarters relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with certification-compliant manufacturing assets in South Asia that can pivot between European REACH and non-European markets. The five-to-ten year viability window favors dye-house operations with demonstrated azo dye reformulation expertise and separate batch management systems. Watch for OEKO-TEX Standard 100 renewal cycle backlogs as an inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Finishing Line Investment | EPA-registered silver-ion capacity unlocks healthcare and hospitality procurement specifications previously closed to untreated suppliers. |
| Direct-to-Consumer Subscription Launch | Limited-edition drops and refresh programs generate recurring revenue streams with superior demand predictability versus wholesale channels. |
| Lyocell Fiber Supply Agreement | Marriott and Hyatt procurement teams have elevated Tencel blends to preferred status, compressing long-staple cotton contract volumes. |
| Dual-Inventory Dye-House Configuration | Separate REACH-compliant and non-compliant batch streams prevent cross-contamination and enable simultaneous European and non-European market service. |
| Saudi Hospitality Contract Pursuit | NEOM and Red Sea Project developments are contracting multi-year supply agreements directly with Zhejiang manufacturers at unmatched Middle East scale. |
Research Methodology
Multiple input streams — hospitality procurement director interviews, textile mill operational assessments, and regulatory filing analysis — were reconciled to construct demand and supply estimates. Primary conversations captured specification evolution from hotel chain headquarters and extended-stay property managers. Secondary validation drew from EPA FIFRA registrations, ECHA REACH Annex XVII updates, OEKO-TEX certification databases, and customs trade records. Bottom-up volume modeling and top-down market sizing were cross-referenced for convergence.
Data-stream reconciliation across material segmentation, closure type mechanics, and regional procurement patterns anchored the analytical framework over the projection horizon. Modeled dimensions span cotton/linen/microfiber/satin composition, solid/patterned/printed/textured design tiers, and hospitality versus direct-to-consumer channel economics. CAGRs were derived from wash-cycle replacement frequency analysis and institutional contract renewal timelines. Saudi giga-project procurement velocity and subscription service adoption curves served as industry-specific demand inputs.
Inputs from hospitality procurement databases and textile certification registries were available through the study window; gaps in property-level P&L data and informal spot-market pricing introduce uncertainty bands around extended-stay segment estimates. Forecasts reflect assumptions regarding REACH SVHC list evolution and EPA antimicrobial claim enforcement posture. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Stained Glass Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
Door Handles Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Wall Decor Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Flush Door Market
Homecare and Decor
Wall Covering and Wall Decor Market