
 Closets, Nightstands, and Dressers Market | 2026-2036
Closets, Nightstands, and Dressers Market Size, Share, and Industry Trends Forecast 2026-2036
Closets, Nightstands, and Dressers Market Insights
Modular bundling of closets, nightstands, and dressers into coordinated bedroom systems is broadening buyer choice beyond standalone purchases. IKEA leverages flat-pack logistics to dominate entry-level modular configurations across multiple continents. Williams-Sonoma Inc. anchors premium positioned built-in closet systems through design-forward retail channels. Ashley Furniture Industries, Inc. competes on manufacturing scale in traditional wood dresser segments with broad North American distribution.
Closets, nightstands, and dressers comprise fixed and movable storage furniture designed for garment organization, bedside utility, and clothing containment, typically constructed from engineered wood, solid timber, metal framing, or laminated composites with functional parameters spanning load capacity, drawer slide extension, and dimensional modularity to fit standard residential room footprints. The residential end user segment leads volume absorption due to persistent new household formation and replacement cycles in owner-occupied housing. Modular product types are capturing disproportionate growth as urban dwellers prioritize reconfigurable layouts in smaller footprint apartments. Wood materials sustain margin concentration at the premium tier despite laminates penetrating mass-market channels aggressively.
EPA formaldehyde emission standards under TSCA Title VI shape composite wood panel sourcing for domestic manufacturers, while CARB ATCM Phase 2 requirements in California extend compliance obligations to imported finished goods. The EU Ecolabel and FSC chain-of-custody certification increasingly filter market access for European-bound exports from Asian production bases. Stakeholders must monitor evolving state-level chemical disclosure mandates and circular economy packaging requirements that will reshape supplier qualification criteria and finished goods distribution economics across primary demand centers.
Market Dynamics
California's Title 24 building efficiency standards are forcing residential developers to specify storage systems with embedded energy performance metrics, compressing supplier qualification timelines and reshaping procurement criteria across multi-family construction corridors.
Growth Catalysts
- Sun Belt housing inventory expansion:Metropolitan areas in Texas, Florida, and Arizona are absorbing prefabricated closet systems at volumes that justify dedicated regional distribution centers.
- EPA TSCA Title VI compliance infrastructure:Domestic panel manufacturers have invested in certified composite wood sourcing that now accelerates specification wins against non-compliant imports.
- Modular reconfiguration demand:Urban apartment dwellers in dense coastal markets prioritize reconfigurable nightstand and dresser systems that adapt to lease-term room layout changes.
Market Restraints
- Engineered wood input cost volatility:Resin and fiber supply fluctuations compress margins for laminate-dependent producers serving mass-market channels.
- Asian production base concentration risk:Finished goods and component sourcing clusters in Vietnam and Malaysia expose brands to shipping rate spikes and port congestion.
- CARB ATCM Phase 2 enforcement friction:California's extended compliance obligations to imported finished goods create documentation bottlenecks that delay customs clearance.
Strategic Opportunities
- FSC chain-of-custody certification penetration:Premium wood dresser segments in European markets reward verified sustainable sourcing with shelf placement preference.
- EU Ecolabel qualification:Asian exporters who achieve this designation unlock preferential access to Scandinavian retail channels with stringent chemical disclosure requirements.
- Built-in closet system convergence:Integration of LED lighting and smart home connectivity is expanding into new construction specifications previously served by standalone wardrobes.
Industry Challenges
- Composite panel certification timeline compression:Third-party laboratory testing queues for formaldehyde emission verification are extending supplier onboarding cycles.
- Flat-pack assembly skill scarcity:Retailers face customer service burden from improperly assembled modular systems that damage brand perception.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Closets, Nightstands, and Dressers Market |
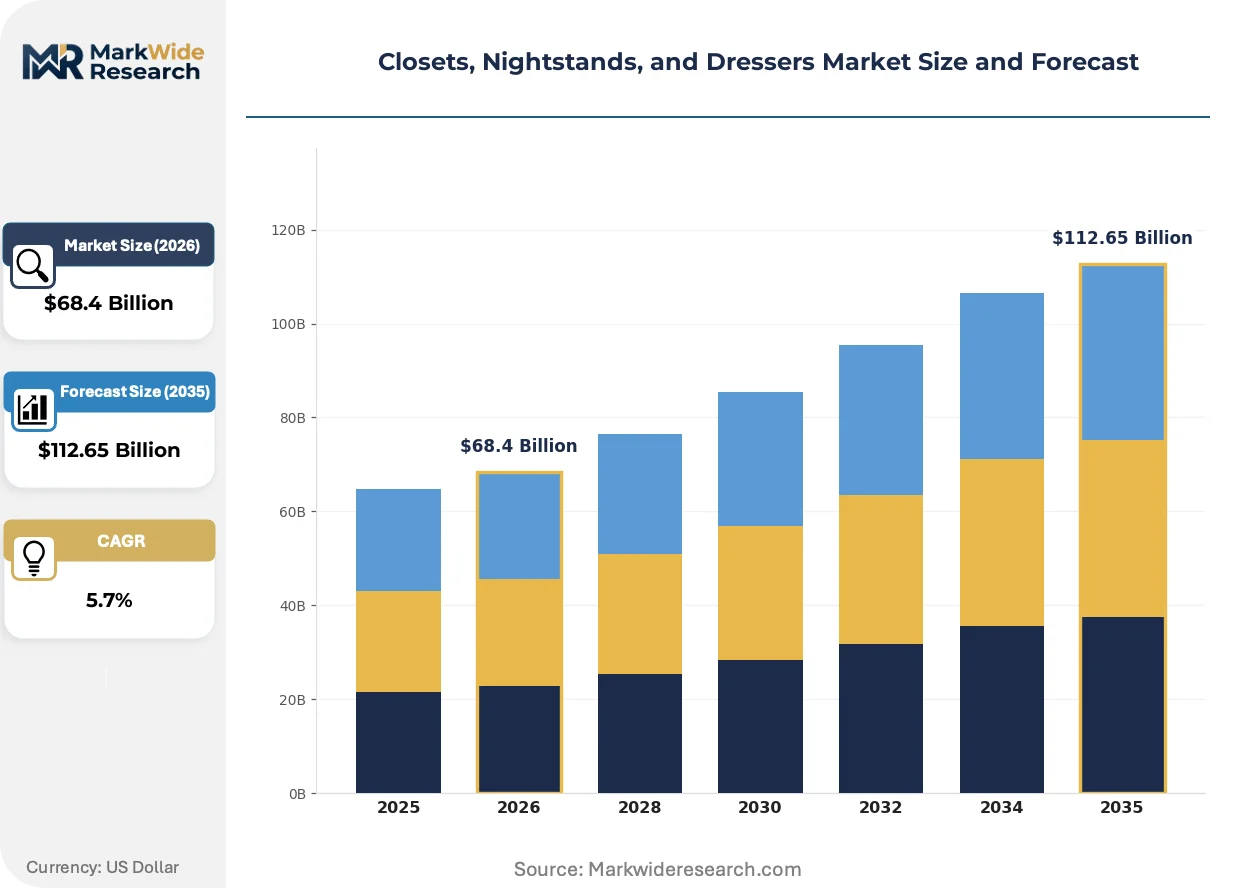
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Modular, Wall-mounted Material: Wood, Metal, Laminates, Glass Design Style: Modern, Traditional, Industrial, Rustic End User: Residential, Hospitality, Retail, Commercial |
| Companies Covered | IKEA, Wayfair Inc., Williams-Sonoma Inc., Ashley Furniture Industries, Inc., Bed Bath & Beyond Inc., Target Corporation, The Home Depot Inc., Crate and Barrel, Rooms to Go, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Closets, Nightstands, and Dressers Market Trends and Innovations
Material science advances and regulatory disclosure mandates are converging to reshape how bedroom storage systems are specified, manufactured, and distributed across residential construction channels.
Cross-laminated timber and mass plywood panel construction is expanding into premium built-in closet applications previously dominated by particleboard substrates. Custom home builders in Pacific Northwest markets specify these engineered wood products for load-bearing wardrobe structures. The shift is compressing traditional lumber supply relationships while opening specification pathways for certified sustainable forestry operations.
REACH chemical registration requirements in the European Union are forcing reformulation of adhesives and surface finishes used in nightstand and dresser production. Manufacturers serving EU-bound exports must maintain substance volume tracking across complex Asian supply chains. The regulatory burden falls heaviest on small-to-mid-scale producers lacking dedicated compliance infrastructure.
Direct-to-installer procurement platforms are fragmenting traditional distributor relationships in the multi-family construction segment. Property developers in Texas and Florida now source coordinated bedroom systems through digital marketplaces that bypass legacy furniture dealer networks. This channel shift concentrates purchasing power with national developers while compressing regional distributor margins.
Closets, Nightstands, and Dressers Market Segmentation
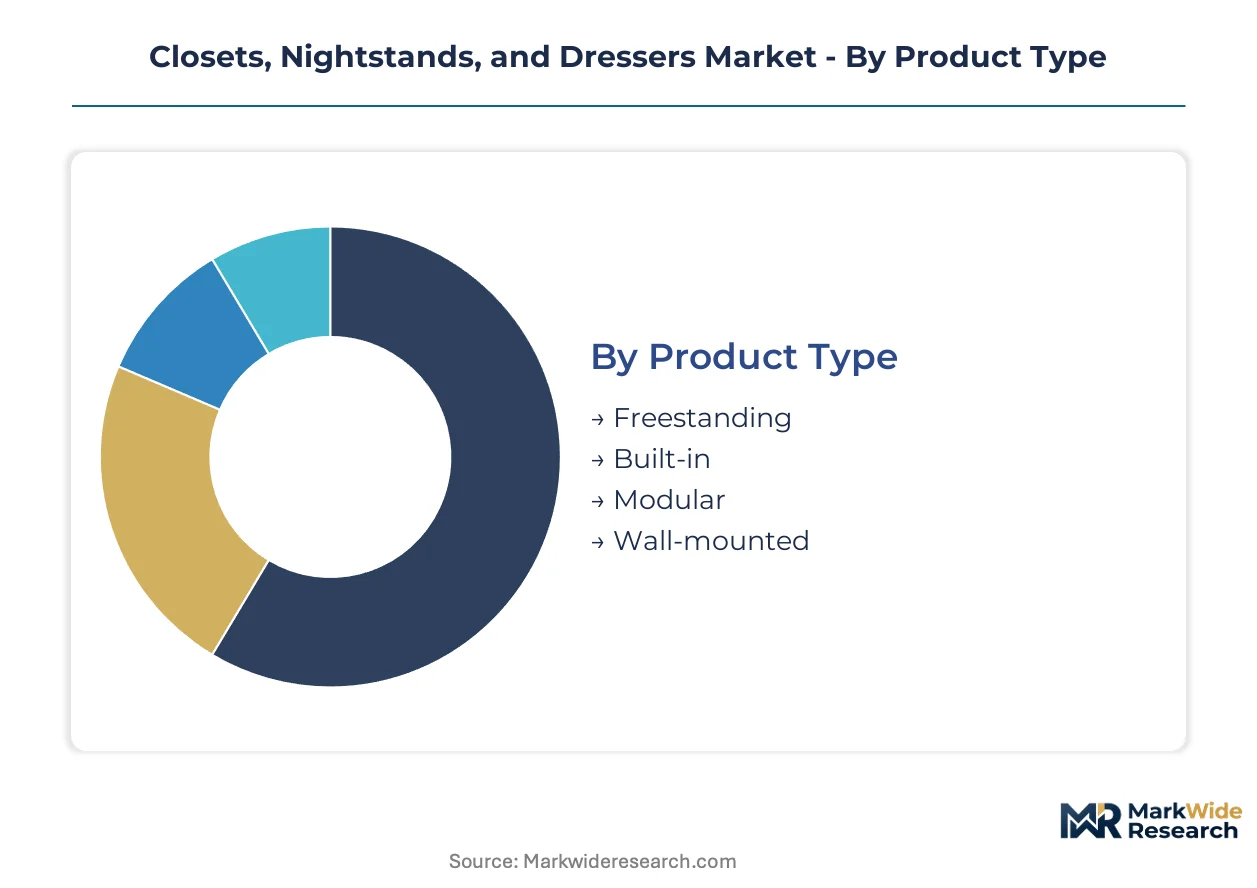
Segmentation in the Closets, Nightstands, and Dressers Market reveals how regulatory compliance burdens, material sourcing constraints, and installation complexity create divergent margin profiles across product configurations. Understanding these divisions helps suppliers align certification investments with addressable revenue pools.
Product Type:
EPA TSCA Title VI certification requirements apply differentially across product types, with built-in systems facing extended third-party laboratory verification timelines compared to freestanding alternatives that rely on component-level compliance documentation.
- Freestanding:Self-contained units requiring no wall anchoring or structural integration. Demand concentrates in single-family residential replacements and rental property turnovers across Sun Belt metropolitan areas, where mobility and ease of installation outweigh built-in permanence.
- Built-in:Custom-fitted systems integrated with wall structures and architectural millwork. California Title 24 multi-family construction specifications increasingly mandate these configurations with embedded LED lighting and energy performance metrics, compressing supplier qualification windows.
- Modular:Reconfigurable component systems designed for flat-pack distribution and user assembly. Urban apartment dwellers in dense coastal markets prioritize these for lease-term adaptability.
- Wall-mounted:Floating configurations anchored to vertical surfaces without floor contact. Space-constrained micro-units in high-density housing corridors absorb these for footprint efficiency.
Leading the category by volume: Freestanding. Growing fastest: Modular.
Material:
Cost tier stratification separates premium solid timber offerings from mass-market laminate penetration, with certification burden intensity inversely correlating with price positioning.
- Wood:Solid timber and engineered wood products commanding margin concentration at premium tiers. FSC chain-of-custody certification unlocks preferential shelf placement in European retail channels with stringent disclosure requirements.
- Metal:Steel and aluminum framing systems dominating commercial and hospitality specifications for durability and load capacity. Industrial-style residential applications in urban loft conversions absorb growing volumes.
- Laminates:Particleboard and MDF substrates with decorative surface films penetrating mass-market channels aggressively. CARB ATCM Phase 2 documentation bottlenecks delay customs clearance for Asian-sourced finished goods.
- Glass:Tempered and laminated glass elements integrated as accent surfaces or full paneling. Niche positioning in high-design hospitality and luxury residential segments limits volume scale.
Dominating by revenue: Wood. Expanding most quickly: Laminates.
Design Style:
Application context determines style specification, with hospitality and multi-family developers favoring neutral modern configurations while custom residential channels sustain traditional and rustic alternatives.
- Modern:Clean lines, minimal ornamentation, and neutral palettes aligning with contemporary architectural specifications. Multi-family developers in Texas and Florida standardize these for broad tenant appeal.
- Traditional:Ornate detailing, raised paneling, and classic hardware finishes. Custom home builders in established Northeast and Midwest markets specify these for owner-occupied new construction.
- Industrial:Exposed metal framing, reclaimed wood accents, and utilitarian hardware. Urban adaptive reuse projects and loft conversions drive specification in dense metropolitan cores.
- Rustic:Distressed finishes, natural edge details, and farmhouse-inspired proportions. Secondary home and vacation property markets in mountain and coastal regions sustain demand.
Highest volume: Modern. Steepest expansion trajectory: Industrial.
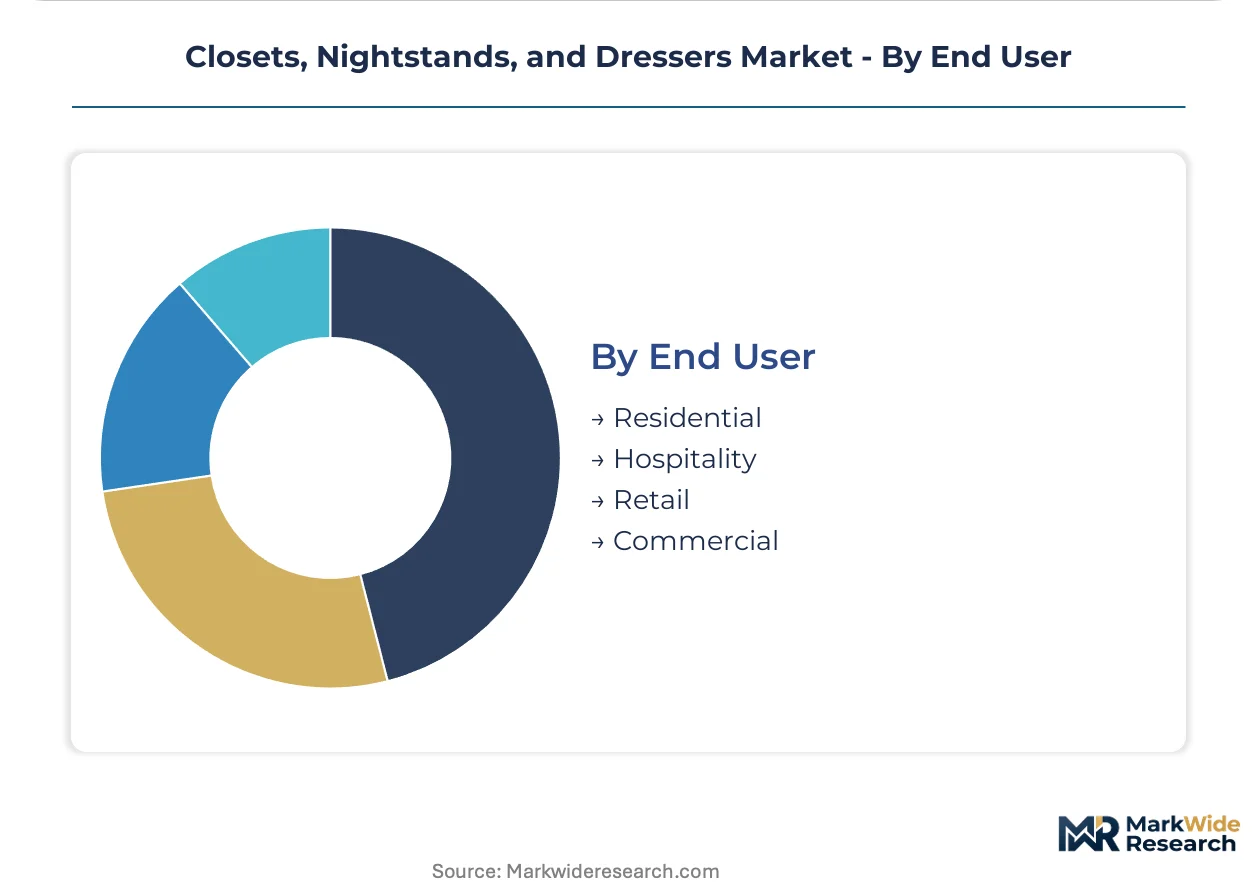
End User:
Customer type segmentation reveals divergent procurement pathways, with residential absorption leading volume while hospitality and commercial segments concentrate purchasing power through direct-to-installer digital platforms.
- Residential:Owner-occupied and rental housing units driving replacement cycles and new household formation. Persistent housing inventory expansion in Sun Belt metropolitan areas sustains volume leadership.
- Hospitality:Hotels, resorts, and extended-stay properties specifying coordinated bedroom systems for guest room standardization. Direct-to-installer procurement platforms are fragmenting traditional distributor relationships in this segment.
- Retail:Furniture showrooms and design centers requiring display fixtures and merchandising systems. Cyclical exposure to consumer discretionary spending compresses order predictability.
- Commercial:Corporate housing, student dormitories, and senior living facilities with institutional procurement protocols. Extended sales cycles and specification requirements limit supplier participation.
Leading by volume: Residential. Gaining share fastest: Hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Sun Belt metropolitan corridors are concentrating residential construction activity and storage system procurement. California's Title 24 building efficiency standards now extend compliance obligations to imported finished goods. Vietnam and Malaysia production bases face documentation bottlenecks under CARB ATCM Phase 2 enforcement.
United States
Texas, Florida, and Arizona metropolitan areas absorb prefabricated closet systems at volumes justifying dedicated regional distribution centers. EPA TSCA Title VI certification infrastructure accelerates specification wins for domestic panel manufacturers against non-compliant imports. Houston and Dallas-Fort Worth clusters concentrate multi-family construction procurement through direct-to-installer digital platforms.
Germany
REACH chemical registration requirements force adhesive and surface finish reformulation for nightstand and dresser production bound for EU markets. ECHA substance volume tracking mandates burden small-to-mid-scale producers lacking dedicated compliance infrastructure. Bavaria and Baden-Württemberg industrial zones anchor premium wood dresser manufacturing with FSC chain-of-custody certification penetration.
China
GB standards for formaldehyde emission in composite wood products shape export-oriented manufacturing configurations. MIIT industrial policy directs capacity consolidation in engineered wood panel production. Pearl River Delta and Yangtze River Delta manufacturing clusters supply modular flat-pack systems to North American and European retail channels under OEM arrangements.
Vietnam
Shipping rate spikes and port congestion expose finished goods sourcing clusters to supply chain disruption risk. CARB ATCM Phase 2 documentation requirements create customs clearance delays for California-bound exports. Ho Chi Minh City and Binh Duong industrial zones concentrate laminate-dependent production serving mass-market channels with compressed margin profiles.
Sweden
EU Ecolabel qualification unlocks preferential access to Scandinavian retail channels with stringent chemical disclosure requirements. FSC chain-of-custody certification rewards verified sustainable sourcing with shelf placement preference in premium segments. Stockholm and Gothenburg design-forward retail channels anchor built-in closet system specification for new construction.
Closets, Nightstands, and Dressers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: flat-pack logistics operators, premium design-forward retailers, and manufacturing-scale traditional wood producers. Consolidation pressure concentrates in mid-market laminate segments while premium wood tiers sustain fragmentation. M&A activity targets regional distribution capabilities in Sun Belt corridors. Strategic partnerships link Asian production bases with North American specification channels.
Within the flat-pack logistics archetype, IKEA exemplifies entry-level modular configuration dominance across multiple continents. Williams-Sonoma Inc. occupies a position in the premium built-in closet system segment through design-forward retail channels. Ashley Furniture Industries, Inc. anchors the manufacturing-scale traditional wood dresser archetype with broad North American distribution infrastructure. These three players represent divergent competitive vectors: logistics efficiency, design premiumization, and production scale.
| Leading Market Players |
|---|
| IKEA |
| Wayfair Inc. |
| Williams-Sonoma Inc. |
| Ashley Furniture Industries, Inc. |
| Bed Bath & Beyond Inc. |
| Target Corporation |
| The Home Depot Inc. |
| Crate and Barrel |
| Rooms to Go |
| Others |
Pricing and Supply Chain Analysis
Multi-family property developers in Texas and Florida corridors concentrate procurement volumes through direct-to-installer digital platforms, compressing distributor margins and forcing transactional pricing models over relationship-based contracts.
Pricing Analysis
Short lead-time premiums command substantial markups in built-in closet segments where California Title 24 compliance documentation extends supplier qualification windows. Pricing stratifies across premium, standard, and economy tiers based on FSC certification status and EPA TSCA Title VI compliance grade. Cost compression in laminate-dependent mass-market channels intensifies as resin and fiber input volatility squeezes producer margins. Hospitality procurement teams demonstrate lowest price sensitivity due to specification standardization requirements, while individual residential buyers in Sun Belt replacement cycles drive hardest bargain hunting.
Supply Chain Analysis
Reverse-logistics flows for flat-pack modular systems create customer service burdens as improperly assembled nightstands and dressers generate return volumes that damage brand perception. Manufacturing concentrates in Vietnam, Malaysia, and China, with Pearl River Delta and Yangtze River Delta clusters supplying OEM arrangements for North American retail channels. Resin adhesives, decorative surface films, and engineered wood panels constitute critical input dependencies. Single-source vulnerability in Vietnam shipping corridors exposes brands to rate spikes and port congestion. Distribution runs through regional furniture dealer networks fragmenting under digital marketplace pressure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-laminated timber and mass plywood panel construction is displacing particleboard substrates in premium built-in applications, compressing traditional lumber supply relationships while opening specification pathways for certified sustainable forestry operations.
For Market Incumbents: Deploy FSC chain-of-custody certification as a defensive moat against laminate competitors facing CARB ATCM Phase 2 documentation bottlenecks. Deepen backward integration into engineered wood panel production to secure EPA TSCA Title VI compliant supply against Asian import delays. Control specification channels in California Title 24 multi-family construction through embedded LED lighting integration partnerships. For New Entrants and Emerging Players: The mid-market price-point gap between IKEA flat-pack economy and Williams-Sonoma premium built-in systems offers white-space opportunity in reconfigurable modular nightstands for urban apartment dwellers. Target hospitality procurement platforms in Texas and Florida corridors where direct-to-installer digital marketplaces fragment legacy distributor relationships. Pursue EU Ecolabel qualification as a go-to-market angle for Scandinavian retail channel access. For Investors and Strategic Acquirers: The window for entry favors regional distribution capabilities in Sun Belt metropolitan corridors where housing inventory expansion justifies dedicated logistics infrastructure. Long-term viability hinges on compliance infrastructure investments that accelerate supplier qualification timelines against non-compliant competitors. Monitor EPA formaldehyde emission standard enforcement intensity as an inflection indicator for domestic panel manufacturer margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | EPA TSCA Title VI compliance accelerates specification wins against delayed Asian imports. |
| Regional Distribution Expansion | Dedicated Sun Belt logistics hubs capture multi-family construction procurement concentration. |
| Smart Home Integration Partnership | LED lighting and connectivity convergence penetrates California Title 24 new construction specifications. |
| Sustainable Sourcing Repositioning | FSC chain-of-custody certification unlocks preferential European retail shelf placement. |
| Direct-to-Installer Platform Launch | Digital procurement bypass fragments legacy furniture dealer networks in hospitality segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with multi-family property developers, furniture procurement managers at hospitality chains, regional distribution channel heads, and compliance officers at engineered wood panel manufacturers. EPA TSCA Title VI certification databases, CARB ATCM Phase 2 compliance registries, and FSC chain-of-custody tracking systems provided structured secondary validation. Bottom-up volume builds across product type, material, and end-use segments triangulated against top-down construction spending and housing formation data.
Reconciliation of shipment volumes, import customs records, and retail point-of-sale data streams informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, material grade tier, design style category, and end-use vertical with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to normalized baseline data. Housing inventory expansion rates in Sun Belt metropolitan areas and compliance timeline compression under California Title 24 standards served as industry-specific forecast inputs.
Inputs from EPA certification databases and EU Ecolabel registries were available through the study window; gaps in real-time Asian production capacity utilization introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and shipping rate normalization. Practitioners should monitor CARB ATCM Phase 2 customs clearance delays and resin input cost volatility for early signals of margin pressure redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Children Mattress Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Global Cervical Pillows Market