
 Global Cervical Pillows Market | 2026-2036
Global Cervical Pillows Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cervical Pillows Market Foresight
Multi-source sourcing of viscoelastic foam and natural latex is hardening across the supply base as manufacturers diversify away from single-origin dependencies. PharMeDoc leverages its direct-to-consumer channel infrastructure to sustain price competitiveness in the home care segment. Coop Home Goods anchors its position through in-house production of shredded memory foam blends that differentiate against commodity alternatives.
Cervical pillows are ergonomically contoured sleep supports designed to maintain neutral cervical spine alignment during rest, typically manufactured with density ratings between 40D and 100D for viscoelastic formulations and incorporating cervical rolls measuring 4 to 6 inches in height to provide targeted lordotic support. Their primary commercial purpose centers on reducing neck pain, improving sleep quality, and supporting post-surgical recovery protocols prescribed by physiotherapy professionals. Memory foam formulations dominate volume production due to established molding infrastructure and consumer familiarity, while gel-infused foam variants capture expanding margin pools in the luxury hotel and wellness center channels where cooling performance commands premium positioning. Orthopedic therapy applications lead absolute demand from physiotherapy clinics, whereas sleep apnea relief represents the fastest-growing application segment as clinicians integrate cervical positioning into multi-modal airway management protocols.
The FDA's Class I medical device framework in the United States and the EU Medical Device Regulation in Europe impose biocompatibility and labeling requirements that filter substandard imports and elevate compliance costs for new entrants. Japan's Ministry of Economy, Trade and Industry enforces JIS standards for polyurethane foam density and durability that constrain formulation flexibility but protect domestic manufacturers from low-cost displacement. Stakeholders must monitor evolving reimbursement criteria from national health systems that increasingly influence whether cervical pillows are classified as durable medical equipment or discretionary wellness purchases.
Market Dynamics
Home care patients now drive cervical pillow demand as aging populations reject institutional recovery settings, forcing manufacturers to redesign distribution infrastructure for direct-to-consumer fulfillment while maintaining clinical credibility with physiotherapy gatekeepers.
Growth Catalysts
- EU Medical Device Regulation compliance:Biocompatibility and labeling requirements filter substandard imports from Asian manufacturers, elevating entry barriers that protect incumbent European producers.
- Physiotherapy clinic prescribing protocols:Post-surgical recovery applications expand as orthopedic professionals integrate cervical positioning into standard rehabilitation regimens across Germany and France.
- Memory foam molding infrastructure:Established capital equipment for viscoelastic production enables rapid SKU proliferation without new tooling investments, accelerating product line extensions.
Market Restraints
- Natural latex price volatility:Rubber plantation yields in Southeast Asia fluctuate with climate patterns, compressing margins for premium positioning strategies.
- Single-origin foam concentration:Viscoelastic chemical precursors cluster in Chinese petrochemical corridors, creating geopolitical exposure for Western manufacturers.
- JIS density standards rigidity:Japan's Ministry of Economy, Trade and Industry enforces polyurethane formulation constraints that limit product differentiation for domestic producers.
Strategic Opportunities
- Indian home care expansion:Underpenetrated domestic physiotherapy infrastructure creates first-mover advantage for certified medical device positioning ahead of BIS standardization.
- Sleep apnea multi-modal protocols:Clinicians integrate cervical pillows with CPAP compliance programs, opening reimbursement pathways through durable medical equipment classification.
- Gel-infused foam convergence:Cooling performance technology crosses from luxury hospitality into wellness center channels, commanding premium positioning.
Industry Challenges
- FDA 510(k) documentation timelines:Class I medical device reclassification creates administrative bottlenecks for novel material introductions.
- ISO 10993 biocompatibility testing costs:Small manufacturers face capital constraints for comprehensive cytotoxicity and sensitization validation.
- Legacy distributor inventory systems:Wholesale channels lack real-time demand signaling, causing forecast mismatches against direct-to-consumer velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cervical Pillows Market |
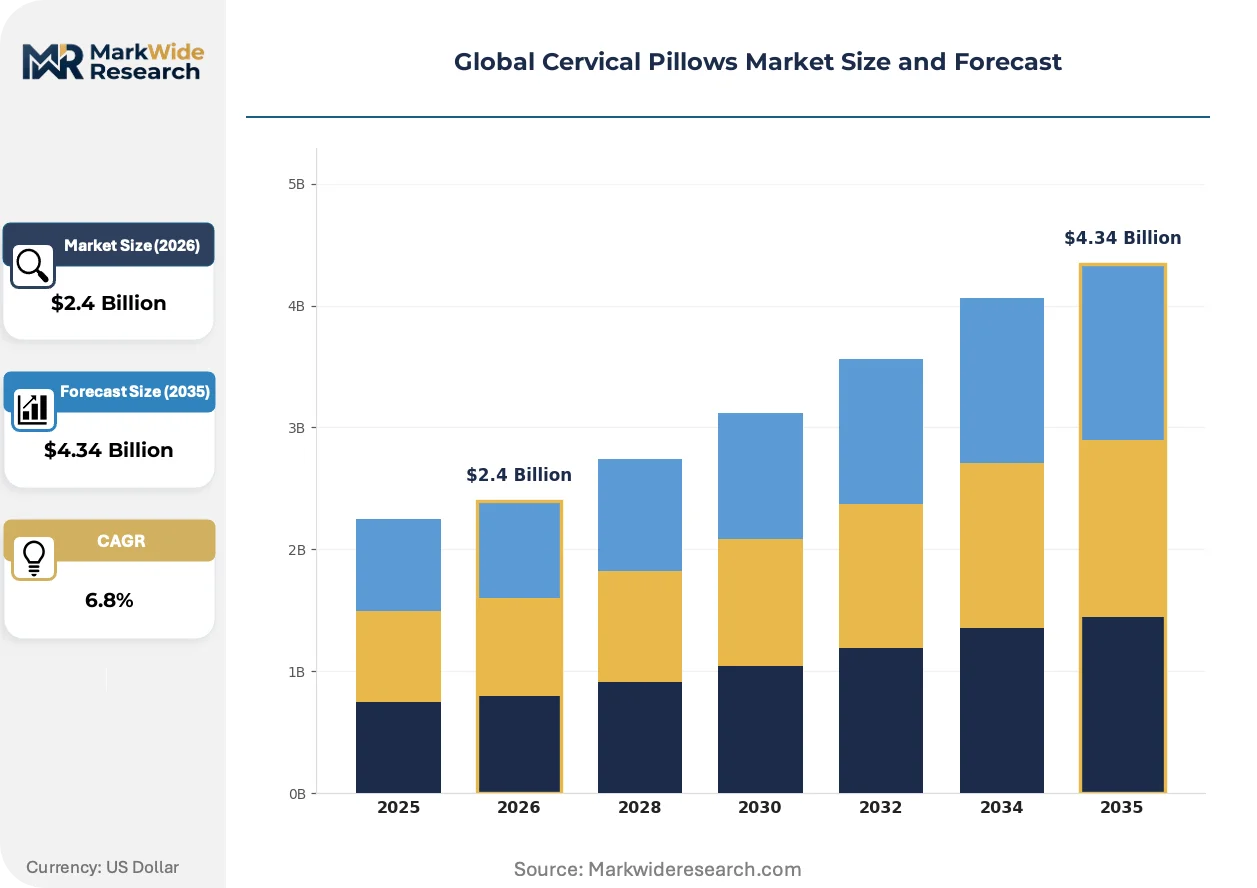
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Latex, Water, Fiber, Buckwheat Material: Viscoelastic Foam, Natural Latex, Gel-Infused Foam, Polyurethane Foam, Bamboo Fiber Application: Orthopedic Therapy, Sleep Apnea Relief, Post-Surgery Recovery, General Neck Support, Snoring Prevention End User: Home Care Patients, Wellness Centers, Physiotherapy Clinics, Luxury Hotels, Senior Care Facilities |
| Companies Covered | PharMeDoc, Coop Home Goods, Malouf, Innocor Inc., Mediflow USA, Snuggle-Pedic, DJO Global Inc., Tempur-Pedic, Custom Craftworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cervical Pillows Market Shifts & Advancements
Material science advances and regulatory recalibration are compressing product development cycles while fragmenting buyer access points across clinical and consumer domains.
Shredded memory foam blends with adjustable loft mechanics is overtaking molded contour designs in the home care segment. Consumers with variable sleep positions reject fixed cervical rolls, driving adoption of zippered fill systems that enable height customization. This flexibility is overtaking physician-prescribed rigidity as the dominant purchase criterion, forcing physiotherapy clinics to stock multiple configurations or risk patient non-compliance.
REACH chemical substance restrictions on isocyanates in polyurethane production are compelling reformulation investments across European manufacturing facilities. The regulation compresses allowable volatile organic compound thresholds, requiring water-based blowing agent transitions. German producers absorb compliance costs through wellness center premium channels, while import-dependent distributors face margin compression from rejected shipments.
Subscription-based pillow replacement programs are displacing single-transaction retail in direct-to-consumer channels. Sleep wellness apps partner with manufacturers to deliver scheduled replacements based on foam degradation algorithms, capturing lifetime value from previously anonymous buyers. This model concentrates in United States metropolitan markets where mattress-in-a-box infrastructure provides last-mile fulfillment templates.
Global Cervical Pillows Market Segmentation
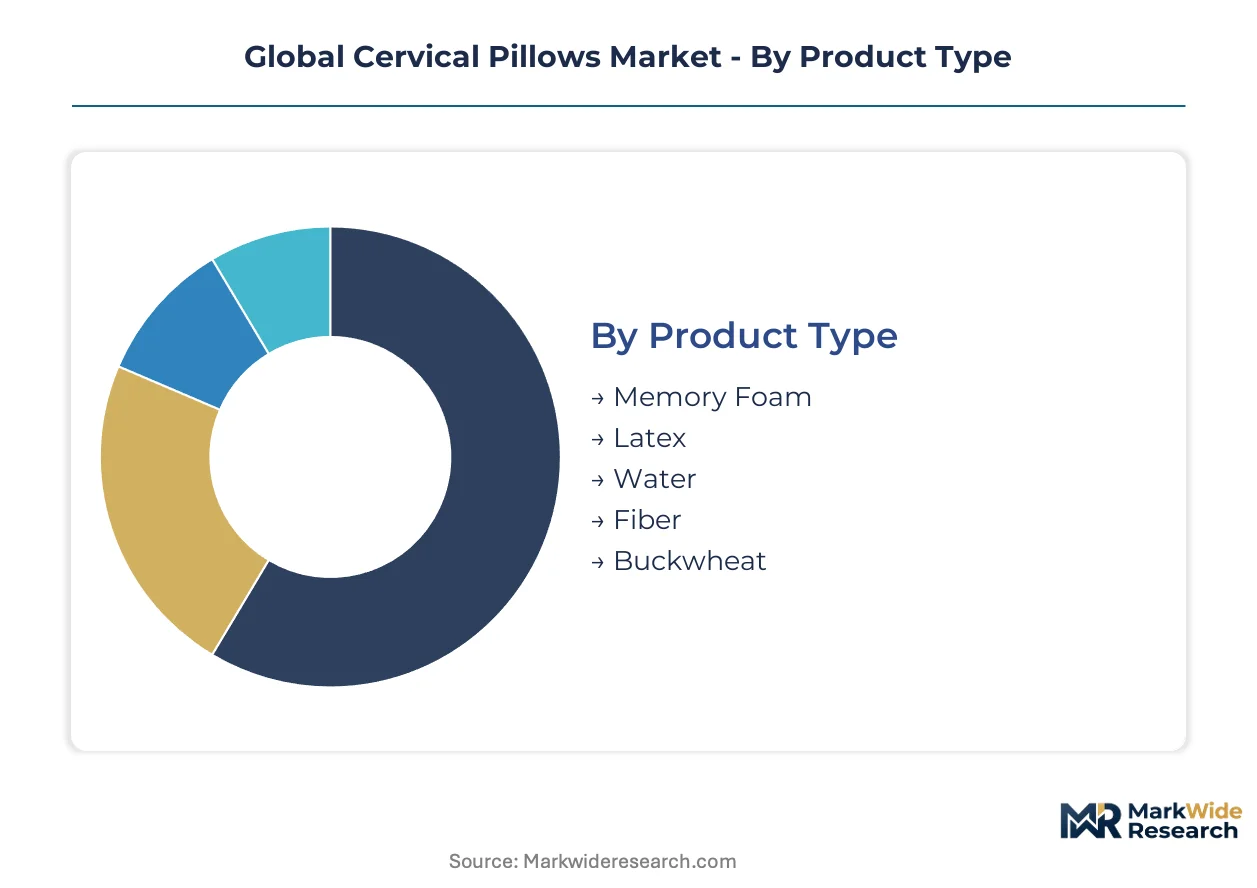
Cervical pillow manufacturers align formulation chemistry with specific therapeutic protocols and distribution channels. Material specifications determine reimbursement eligibility, while end-user targeting shapes margin architecture across clinical and consumer domains.
Product Type:
Density ratings and contour geometry differentiate performance across sleep position requirements.
- Memory Foam:Viscoelastic formulations between 40D and 100D density enable precise cervical roll molding at 4 to 6 inch heights. Demand concentrates in German physiotherapy clinics where post-surgical recovery protocols require consistent lordotic support.
- Latex:Natural rubber derivatives offer resilient support with faster rebound than viscoelastic alternatives. Malaysian and Thai plantation supply volatility compresses margins for premium wellness center positioning in France and Switzerland.
- Water:Adjustable fluid chambers enable height customization for variable sleep positions. Home care patients in the United States favor these for travel portability.
- Fiber:Polyester or down-alternative fills provide economical entry points. Senior care facilities in Japan specify these for bulk procurement under JIS durability standards.
- Buckwheat:Organic hull construction delivers firm, breathable support. Niche adoption persists in Korean and Taiwanese wellness markets.
Mature deployment sits with memory foam. Newer deployment is concentrated in water-based adjustable systems.
Material:
Raw material sourcing geography and chemical compliance burden determine competitive positioning.
- Viscoelastic Foam:Established molding infrastructure dominates volume production. REACH isocyanate restrictions force water-based blowing agent transitions at European facilities.
- Natural Latex:Southeast Asian plantation dependency creates price volatility. German manufacturers absorb cost spikes through wellness center premium channels.
- Gel-Infused Foam:Phase-change materials command luxury hotel and wellness center placement. Cooling performance justifies 40-60% price premiums over standard viscoelastic in Dubai and Singapore hospitality markets.
- Polyurethane Foam:Commodity formulations serve economy-tier home care segments. Chinese petrochemical corridor concentration creates geopolitical exposure for Western distributors.
- Bamboo Fiber:Sustainable positioning targets environmentally conscious direct-to-consumer buyers. Limited structural support restricts clinical applications.
Volume leadership belongs to viscoelastic foam. Margin expansion concentrates in gel-infused variants.
Application:
Clinical validation requirements and reimbursement pathways fragment demand by therapeutic use case.
- Orthopedic Therapy:Physician-prescribed protocols for cervical spine alignment drive physiotherapy clinic procurement. German statutory health insurance covers these as durable medical equipment.
- Sleep Apnea Relief:Multi-modal airway management integration with CPAP compliance programs opens reimbursement pathways. United States Medicare classification debates determine patient out-of-pocket exposure.
- Post-Surgery Recovery:Cervical fusion and disc replacement protocols specify contour pillows for 6-12 week rehabilitation periods. French hospital discharge planners coordinate home delivery logistics.
- General Neck Support:Discretionary wellness purchases dominate e-commerce velocity. Subscription replacement programs capture lifetime value in US metropolitan markets.
- Snoring Prevention:Positional therapy adjuncts claim limited clinical evidence. Direct-to-consumer marketing avoids regulatory scrutiny.
Absolute demand volume sits with orthopedic therapy. Steepest expansion trajectory belongs to sleep apnea relief applications.
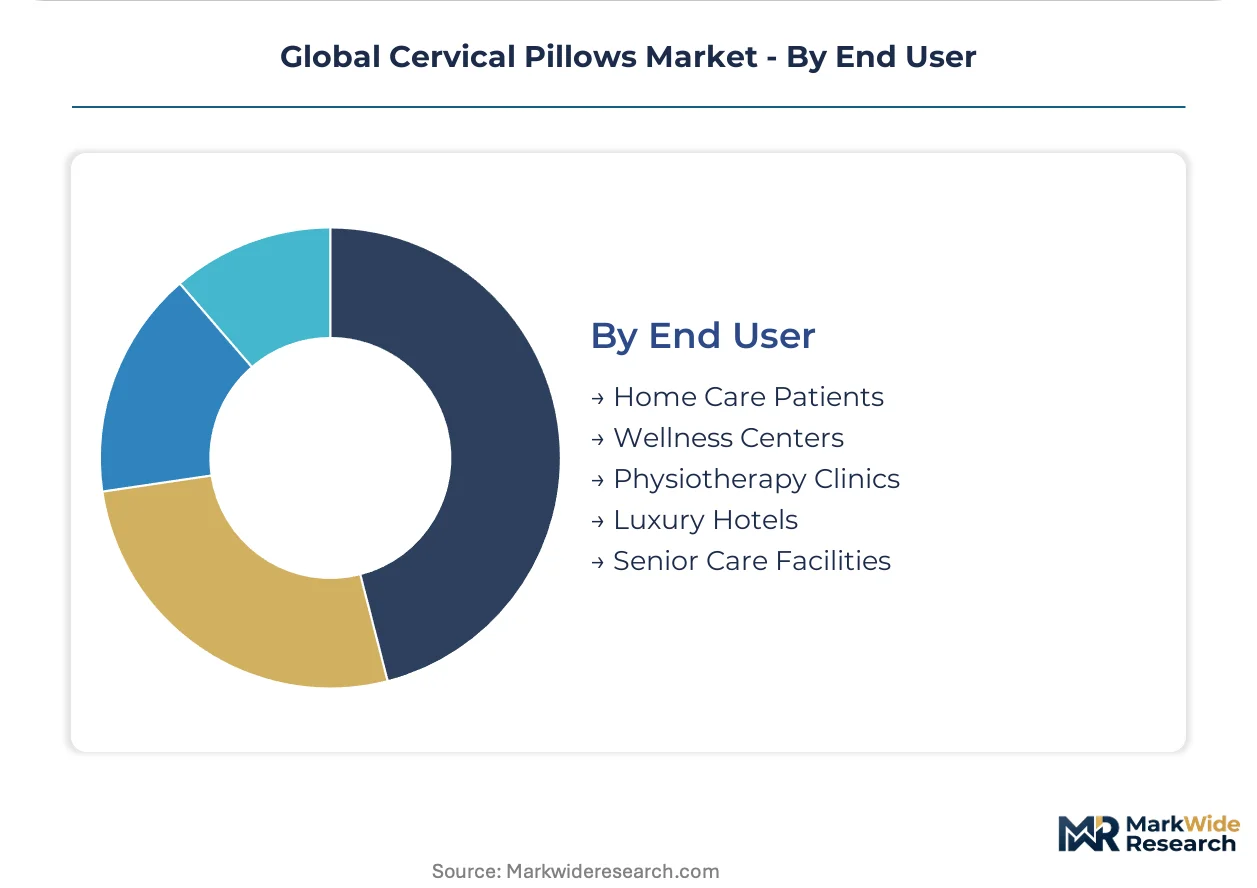
End User:
Channel structure and purchase authority determine pricing architecture and compliance burden.
- Home Care Patients:Aging populations rejecting institutional recovery settings force direct-to-consumer fulfillment redesign. FDA Class I medical device classification maintains clinical credibility with prescribing gatekeepers.
- Wellness Centers:Premium positioning for memory foam and latex variants concentrates in German-speaking markets. METI JIS standards constrain Japanese domestic producer differentiation.
- Physiotherapy Clinics:Post-surgical prescribing protocols in Germany and France drive certified medical device procurement. Inventory systems lack real-time demand signaling against direct-to-consumer velocity.
- Luxury Hotels:Gel-infused cooling performance commands amenity program placement. Dubai and Singapore hospitality procurement favors suppliers with ISO 10993 biocompatibility documentation.
- Senior Care Facilities:Bulk procurement under cost constraints favors fiber fills. BIS standardization lag in India creates first-mover opportunity for certified positioning.
Procurement maturity sits with physiotherapy clinics. Volume growth concentrates in home care patient channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese petrochemical corridors anchor viscoelastic foam precursor supply for cervical pillow manufacturing, while German physiotherapy infrastructure and United States direct-to-consumer channels shape demand-side monetization patterns across three continents.
United States
Home care patients rejecting institutional recovery settings drive direct-to-consumer velocity through mattress-in-a-box fulfillment infrastructure. FDA Class I medical device classification maintains clinical credibility with physiotherapy gatekeepers while enabling e-commerce penetration. Austin and Denver metropolitan clusters host subscription-based pillow replacement program operators partnering with sleep wellness apps.
Germany
Physiotherapy clinics and wellness centers concentrate demand for memory foam and latex variants under statutory health insurance durable medical equipment coverage. EU Medical Device Regulation biocompatibility requirements filter substandard imports from Asian manufacturers. Bavarian manufacturing facilities absorb REACH isocyanate compliance costs through wellness center premium channel pricing.
Japan
METI JIS standards for polyurethane foam density and durability constrain formulation flexibility for domestic producers while protecting against low-cost displacement. Senior care facilities specify fiber fills for bulk procurement under cost constraints. Osaka-based distributors face margin compression from rigid certification timelines for novel material introductions.
India
Underpenetrated domestic physiotherapy infrastructure creates first-mover advantage for certified medical device positioning ahead of BIS standardization. Home care expansion accelerates as aging populations reject institutional settings. Maharashtra and Karnataka clusters attract contract manufacturing investment from brands seeking to diversify single-origin foam dependencies.
United Arab Emirates
Dubai and Singapore hospitality procurement favors gel-infused cooling performance for luxury hotel amenity programs with ISO 10993 biocompatibility documentation requirements. Wellness center channels command 40-60% price premiums over standard viscoelastic formulations. MOHAP medical device registration pathways remain underdeveloped for cervical pillow classification.
Global Cervical Pillows Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to diversify raw material sourcing away from Chinese petrochemical corridor concentration. The vendor base organizes around three tiers: integrated foam compounders with captive molding infrastructure, direct-to-consumer specialists leveraging mattress-in-a-box fulfillment templates, and clinical-channel incumbents maintaining physiotherapy clinic relationships. Two competitive moves define current positioning: backward integration into shredded memory foam blending operations, and subscription-based replacement programs capturing lifetime value from previously anonymous buyers.
Among United States-based operators, PharMeDoc exemplifies direct-to-consumer channel infrastructure deployment for home care segment price competitiveness, while Coop Home Goods anchors the in-house production archetype through captive shredded memory foam blending operations that differentiate against commodity alternatives. Tempur-Pedic occupies the premium-tier position associated with established viscoelastic molding infrastructure and hospitality channel penetration.
| Leading Market Players |
|---|
| PharMeDoc |
| Coop Home Goods |
| Malouf |
| Innocor Inc. |
| Mediflow USA |
| Snuggle-Pedic |
| DJO Global Inc. |
| Tempur-Pedic |
| Custom Craftworks |
| Others |
Supply & Pricing Matrix
REACH chemical substance restrictions on isocyanates in polyurethane production gate qualified supply access for European manufacturers while compressing margins for import-dependent distributors unable to absorb water-based blowing agent transition costs. This regulatory filter stratifies the market into wellness center premium channels that pass compliance costs to buyers versus economy-tier home care segments facing price erosion from rejected shipments.
Pricing Analysis
Warranty and replacement program bundling separates subscription-based operators from transactional retailers, with sleep wellness apps partnering manufacturers to deliver scheduled foam replacements based on degradation algorithms. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility certification status and gel-infused cooling performance specifications. Cost compression in the natural latex tier is intensifying because Malaysian and Thai plantation yield volatility feeds through to raw material input costs. Home care patients in the United States demonstrate highest price sensitivity, while Dubai and Singapore luxury hotel procurement teams show lowest sensitivity to 40-60% premiums for phase-change cooling technology.
Supply Chain Analysis
Direct-to-consumer channels handle home care patient demand through mattress-in-a-box fulfillment infrastructure, while physiotherapy clinic procurement runs through legacy wholesale distributors lacking real-time demand signaling. Viscoelastic foam precursor production concentrates in Chinese petrochemical corridors, with secondary sourcing emerging from Maharashtra and Karnataka manufacturing clusters in India. Natural latex supply draws from Southeast Asian plantations, with shredded memory foam blends increasingly produced through captive in-house operations. Single-origin chemical precursor concentration creates geopolitical exposure for Western manufacturers dependent on cross-border petrochemical feedstock flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable operators as REACH isocyanate restrictions and FDA Class I medical device documentation timelines force capital-constrained manufacturers toward exit or acquisition.
For Market Incumbents: Hedge against Southeast Asian latex price volatility through backward integration into shredded memory foam blending operations that reduce plantation dependency. Secure wellness center premium channel positioning by absorbing REACH compliance costs through pricing power rather than margin sacrifice. Defensive patent filings around adjustable loft mechanics protect against direct-to-consumer specialists eroding physiotherapy clinic relationships.
For New Entrants and Emerging Players: AI-driven foam degradation algorithms for subscription replacement programs offer a technology-first wedge into the United States metropolitan home care segment ahead of incumbent software partnerships. Target Indian domestic physiotherapy infrastructure before BIS standardization formalizes certification requirements for certified medical device positioning. Go-to-market through sleep wellness app partnerships captures lifetime value from previously anonymous buyers without legacy distributor inventory system constraints.
For Investors and Strategic Acquirers: FDA 510(k) clearance for novel gel-infused foam formulations is the leading indicator that a target possesses regulatory navigation capabilities transferable across product line extensions. The five-to-ten year viability window favors operators with established ISO 10993 biocompatibility testing infrastructure and direct-to-consumer fulfillment templates. Acquisition target archetype: mid-cap manufacturers with captive shredded memory foam production and pending Medicare durable medical equipment classification for sleep apnea relief applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shredded Foam Blending | Captive production of adjustable loft materials reduces Southeast Asian latex dependency for Coop Home Goods-type operators. |
| Subscription Replacement Program Launch | Sleep wellness app partnerships capture lifetime value through mattress-in-a-box fulfillment infrastructure in Austin and Denver clusters. |
| ISO 10993 Biocompatibility Certification | Dubai and Singapore hospitality procurement mandates documentation for gel-infused cooling performance premium placement. |
| REACH Water-Based Blowing Agent Transition | German Bavarian facilities absorb compliance costs through wellness center channel pricing power against import-dependent competitors. |
| Medicare Durable Medical Equipment Classification | Reimbursement pathway opening for sleep apnea relief applications reduces patient out-of-pocket exposure in United States home care segment. |
Research Methodology
Independent corroboration across physiotherapy clinic prescribing protocols, foam manufacturing technical specifications, and hospitality procurement databases underwrites the qualitative findings in this study. Primary interviews with orthopedic surgeons, biomedical engineers at German statutory health insurance funds, GPO contracts managers, and direct-to-consumer channel operators combined with secondary validation from FDA 510(k) filings, EU Medical Device Regulation technical documentation, JIS standard density specifications, and customs trade data for viscoelastic foam precursors. Bottom-up demand modeling from end-user segments triangulated against top-down supply capacity assessments across Chinese petrochemical corridors and Indian contract manufacturing clusters.
Comparable historical reference periods anchored the projection framework against post-surgical recovery protocol adoption curves and CPAP compliance program integration timelines across the analysis window. Segmentation dimensions modeled include material chemistry tiers, therapeutic application categories, distribution channel structures, and regional regulatory cluster classifications. CAGRs were derived from elasticity-adjusted demand curves incorporating aging population demographic shifts and reimbursement policy evolution. Industry-specific forecast inputs captured REACH isocyanate restriction implementation phasing and BIS standardization progression for Indian medical device classification.
Several conditions sit outside the modeled scope, including unforeseen rubber plantation climate disruptions, sudden FDA reclassification of cervical pillows to Class II medical devices, and geopolitical trade restriction impacts on Chinese petrochemical feedstock flows. Forecasts reflect assumptions about statutory health insurance durable medical equipment coverage continuity and sleep wellness app partnership expansion velocity. Periodic stress-testing of base assumptions is recommended against Medicare classification debate outcomes and METI JIS standard revision timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
US Wall Beds Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
US Daybeds Market