
 Teen Room Décor Market | 2026-2036
Teen Room Décor Market Size, Share, and Industry Trends Forecast 2026-2036
Teen Room Décor Market Analytics
Subscription-based room refresh services is pivoting how retailers monetize teen spaces beyond one-time purchases. Pottery Barn Teen leverages its catalog heritage to sustain premium positioning among affluent suburban households. IKEA anchors volume through flat-pack logistics and democratic design pricing across its global store network. Urban Outfitters, Inc. differentiates via curated aesthetics that merge streetwear culture with interior styling for older teens.
Teen room décor encompasses furnishings, textiles, wall treatments, and accessories designed to personalize residential spaces occupied by adolescents aged 12 to 19, typically incorporating modular components that accommodate frequent style shifts during developmental transitions. Products range from peel-and-stick vinyl wall coverings rated for clean removal to upholstered platform beds with integrated USB charging ports and storage-optimized footprints. Wall Art and Bedding command the largest current revenue pools due to lower price points and shorter replacement cycles, while Furniture captures disproportionate margin through customization upsells and delivery service bundling. The 15-17 Years target age group represents the fastest-expanding segment as these consumers gain independent purchasing influence through part-time employment and digital payment access.
The US Consumer Product Safety Commission governs furniture stability and flammability standards for residential youth products, while the EU REACH regulation restricts hazardous substances in textiles and surface coatings sold to European teens. California's Proposition 65 labeling requirements create de facto national compliance obligations for US-distributed décor containing listed chemicals. Stakeholders must monitor evolving extended producer responsibility frameworks for furniture recycling that could reshape material selection and end-of-life cost structures.
Market Dynamics
Digital printing technology has compressed production lead times from weeks to days, enabling mass customization at scale economics that reshape inventory models and consumer expectations across teen room décor.
Growth Catalysts
- REACH substance restrictions:EU chemical regulations on textiles and coatings accelerate demand for certified low-VOC wall coverings and organic bedding materials among European households.
- Gen Z purchasing autonomy:Part-time employment and digital payment access among 15-17 year olds create independent buyer segments with distinct aesthetic preferences and replacement cycles.
- On-demand manufacturing platforms:Cloud-based design-to-fulfillment systems enable retailers to offer personalized wall art and textiles without holding finished goods inventory.
Market Restraints
- Cotton and polyester price volatility:Raw material input swings compress margin on bedding and textile categories where price elasticity limits pass-through capability.
- Chinese manufacturing concentration:Heavy reliance on Zhejiang and Guangdong province suppliers creates geopolitical and logistics vulnerability for flat-pack furniture and printed accessories.
- California Proposition 65:Warning label requirements for listed chemicals create compliance friction and product reformulation costs that effectively become national standards.
Strategic Opportunities
- Subscription refresh services:Recurring revenue models for seasonal textile and accessory swaps capture lifetime value beyond single-transaction economics.
- Augmented reality visualization:Smartphone-based room preview tools reduce return rates and accelerate purchase confidence for online furniture buyers.
- Extended producer responsibility frameworks:Emerging EU furniture recycling mandates create first-mover advantage for circular material sourcing and take-back program infrastructure.
Industry Challenges
- Digital-native design talent scarcity:Shortage of professionals combining interior styling expertise with platform-native content creation skills limits brand social media effectiveness.
- Multi-channel inventory synchronization:Real-time stock visibility across DTC websites, marketplaces, and physical showrooms demands capital-intensive systems integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teen Room Décor Market |
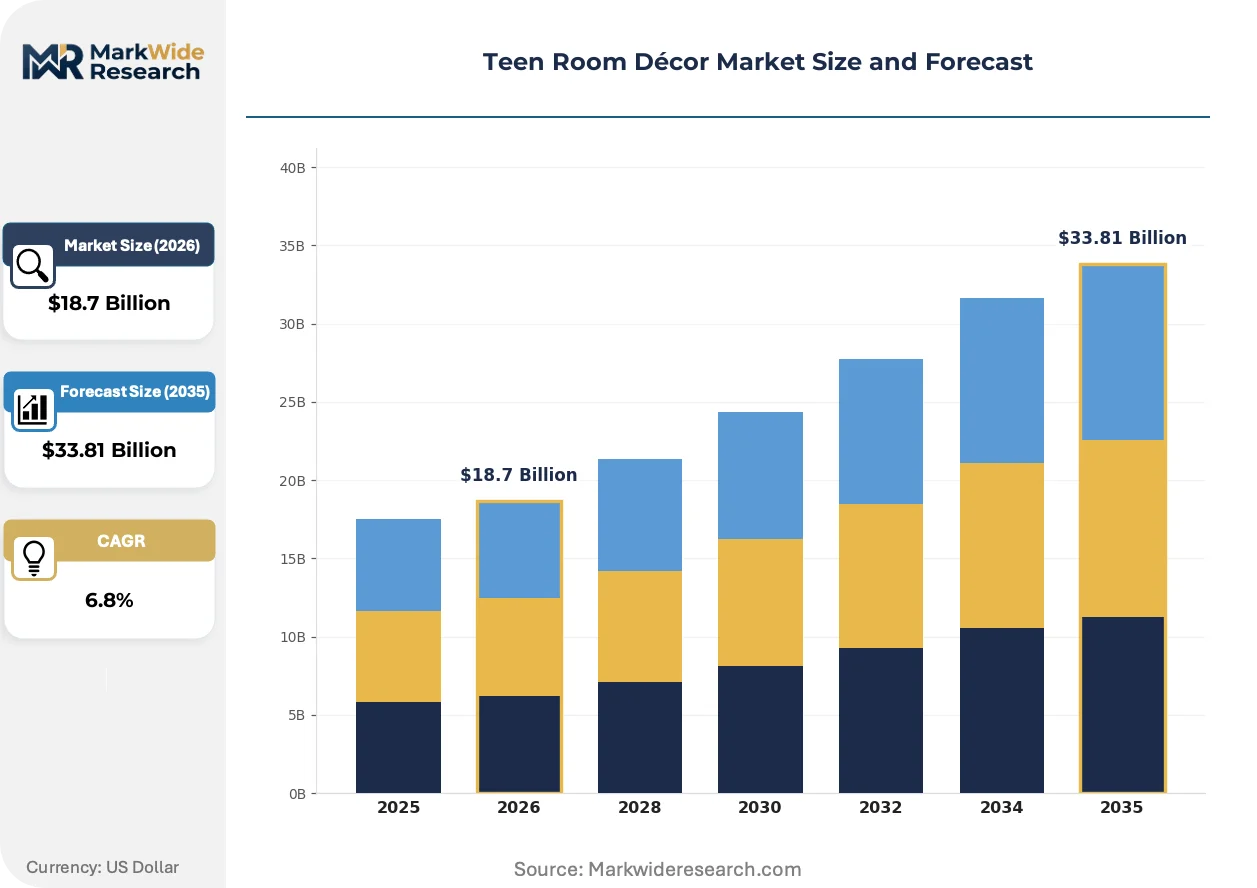
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Art, Bedding, Furniture, Lighting Style: Modern, Vintage, Bohemian, Minimalist Material: Wood, Fabric, Metal, Plastic Target Age Group: 12-14 Years, 15-17 Years, 18-19 Years, Others |
| Companies Covered | Pottery Barn Teen, IKEA, Urban Outfitters, Inc., Spoonflower, West Elm, Bed Bath and Beyond Inc., Etsy, Ban.do, Dormify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teen Room Décor Market Evolving Landscape
Three converging forces are restructuring how teen room décor reaches buyers: manufacturing technology enabling personalization at scale, regulatory pressure on material safety, and shifting purchase authority toward adolescents themselves.
Peel-and-stick vinyl wall coverings rated for clean removal are overtaking traditional painted and permanent wallpaper installations in the 12-19 age segment. Landlords and parents in rental-heavy urban markets favor damage-free alternatives. This technology is compressing the redecorating cycle from years to semesters and enabling seasonal aesthetic shifts without contractor costs.
EU REACH regulation continues tightening restrictions on hazardous substances in textiles and surface coatings sold to European teens. Manufacturers reformulate adhesives and flame retardants to maintain market access. Germany, France, and the Netherlands show strongest compliance-driven demand for certified organic and OEKO-TEX Standard 100 labeled products.
Part-time employment and digital payment access among 15-17 year olds concentrates independent purchasing influence in this age bracket. Parents increasingly delegate accessory and textile decisions while retaining furniture approval authority. This bifurcation is most pronounced in United States suburban markets where teen employment rates exceed 35 percent.
Teen Room Décor Market Segmentation
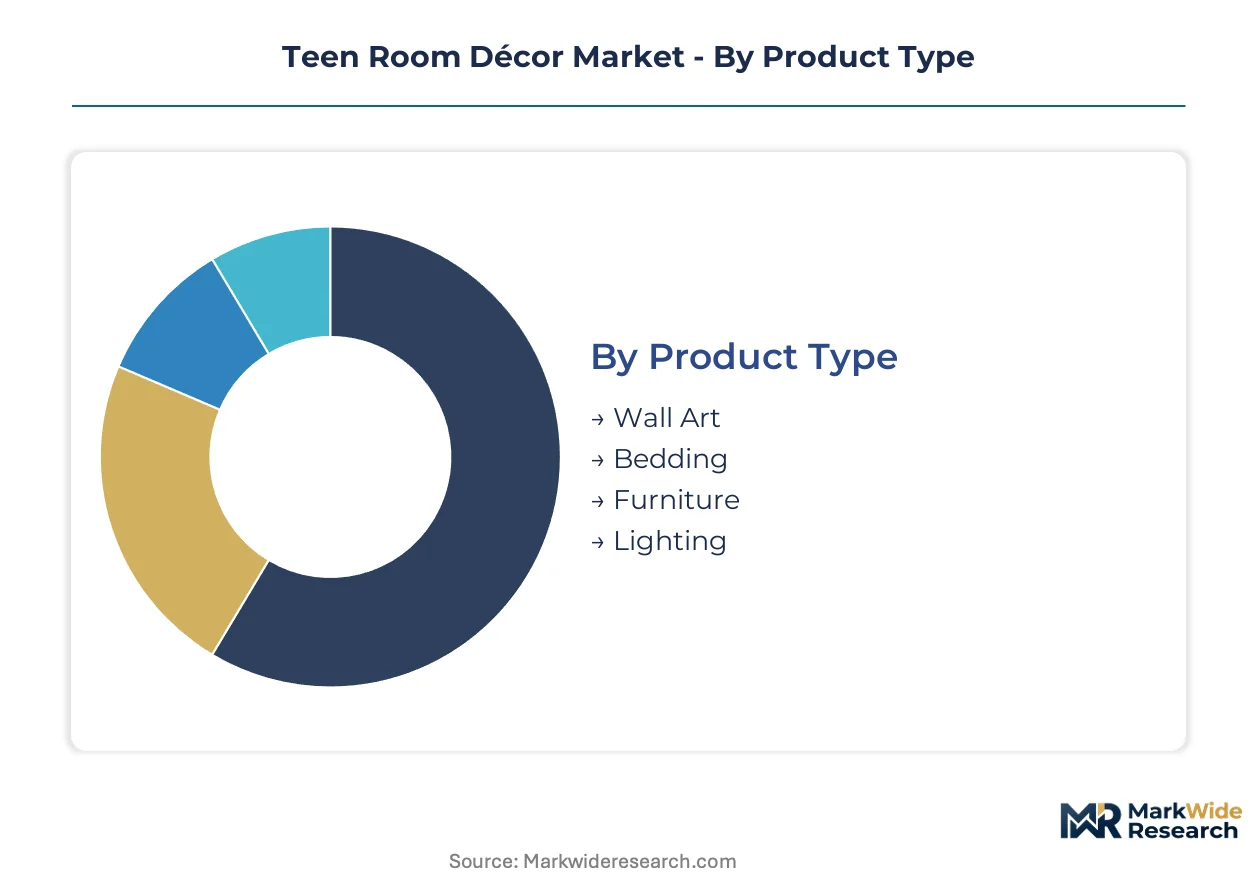
Segmentation in teen room décor reveals how purchasing authority, material preferences, and aesthetic cycles create distinct commercial pockets. Manufacturers configure supply chains differently for each axis, from fast-turn printed textiles to durable furniture with extended production horizons.
Product Type:
Supply concentration varies sharply across product categories, with manufacturing clusters in Zhejiang province dominating printed accessories while European woodworkers capture premium furniture assembly.
- Wall Art:Digital printing platforms enable same-week fulfillment of canvas wraps, peel-and-stick murals, and framed prints. Demand clusters among 15-17 year olds in United States suburban markets where seasonal redecorating cycles compress to semester intervals. Peel-and-stick vinyl formulations rated for clean removal now command preference in rental-heavy urban corridors.
- Bedding:Comforter sets, sheet collections, and decorative pillows rotate on shorter replacement cycles than furniture. Organic cotton and OEKO-TEX Standard 100 certified textiles concentrate demand in Germany, France, and Netherlands households responding to REACH substance restrictions. Dye-sublimation printing allows custom designs without minimum order thresholds.
- Furniture:Platform beds, storage ottomans, and modular shelving systems carry higher average transaction values and longer decision horizons. Flat-pack logistics from Guangdong province suppliers enable volume penetration, though tariff exposure and shipping cost volatility create margin pressure.
- Lighting:LED string installations, desk lamps with integrated charging ports, and pendant fixtures complete room transformations. USB-C compatibility and app-controlled color temperature now serve as baseline specifications rather than premium differentiators.
Furniture absorbs the bulk of installed capacity; Wall Art is expanding most quickly.
Style:
Cost tier stratification maps cleanly onto aesthetic categories, with Bohemian and Vintage styles commanding material premiums while Minimalist and Modern lines optimize for production efficiency.
- Modern:Clean lines, neutral palettes, and geometric forms characterize this segment. United States coastal metropolitan markets show concentration, with parents and teens splitting purchase authority—parents approving furniture frames, teens selecting textile colors.
- Vintage:Distressed finishes, antique reproduction hardware, and curated patina effects require specialized finishing capabilities. European craft workshops in Portugal and Romania supply distressed wood treatments, creating supply bottlenecks during peak back-to-school seasons.
- Bohemian:Macramé textiles, rattan accents, and layered pattern mixing define this aesthetic. Higher material and labor intensity compress margins relative to simpler styles, though price inelasticity among affluent households sustains viability.
- Minimalist:Reduced SKU complexity and standardized dimensions enable inventory efficiency. IKEA's democratic design approach anchors volume here, with flat-pack logistics supporting global store network replenishment.
Modern styling holds the largest share of current production; Bohemian is climbing the fastest among independent teen purchasers.
Material:
Volume concentration in Asian manufacturing clusters shapes material selection, with proximity to processing infrastructure determining cost competitiveness across wood, fabric, metal, and plastic categories.
- Wood:Solid hardwood and engineered particleboard serve distinct price tiers. Malaysian and Indonesian rubberwood plantations supply mid-market furniture frames, while European oak and walnut concentrate in premium German and French retail channels.
- Fabric:Polyester, cotton, and blended textiles dominate bedding and upholstery. REACH-compliant dye houses in Turkey and Portugal capture European demand for low-VOC certification, adding lead time and cost relative to conventional Asian suppliers.
- Metal:Powder-coated steel frames and aluminum hardware provide structural durability for desks and shelving. Chinese foundries in Guangdong province supply the majority of global volume, though quality variance creates segmentation between mass-market and contract-grade specifications.
- Plastic:Injection-molded polypropylene and acrylic accessories occupy entry price points. Recycled content mandates in California and European Union jurisdictions are forcing reformulation of conventional petroleum-based resins.
Fabric commands the greatest production volume; Wood is gaining share fastest in sustainability-positioned product lines.
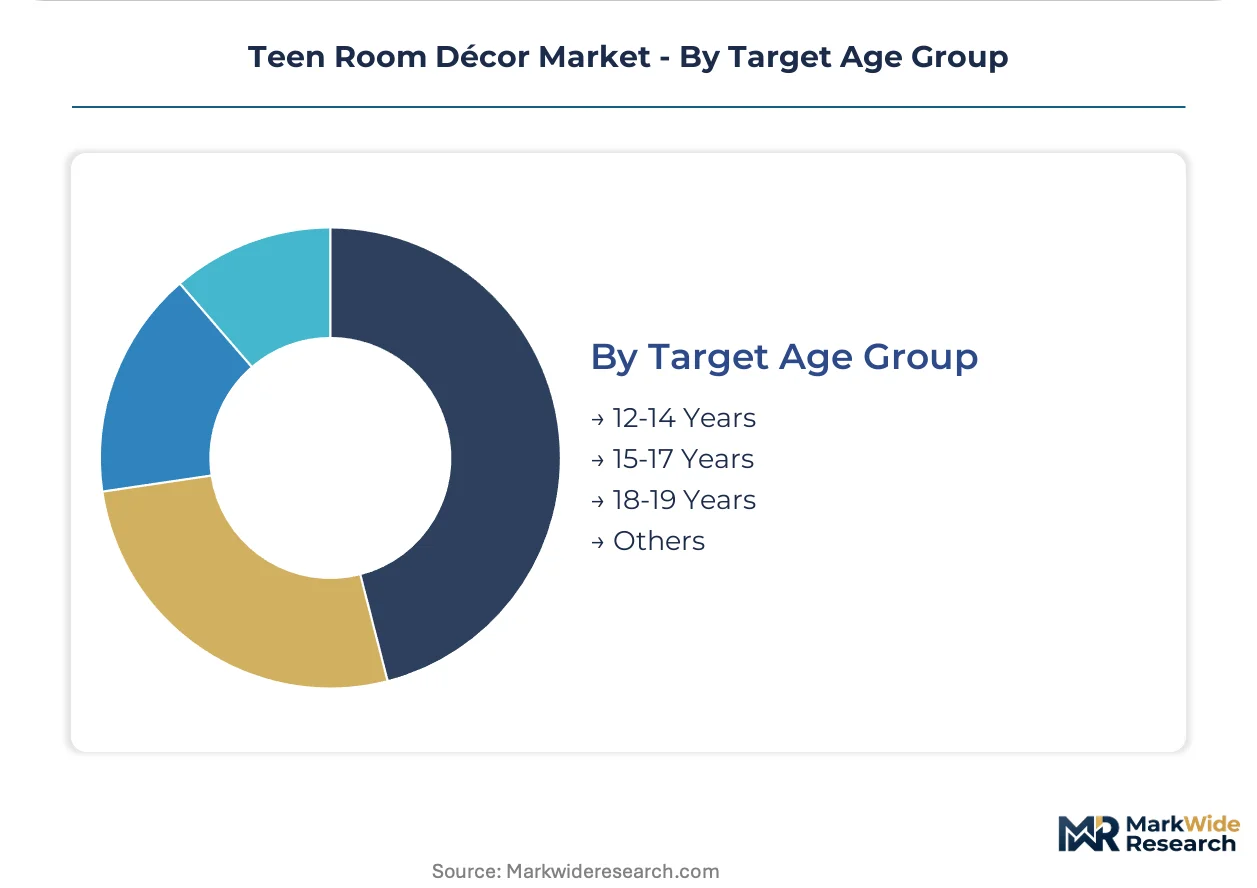
Target Age Group:
Purchasing autonomy escalates dramatically across the teen developmental arc, with employment status and digital payment access creating independent buyer segments in older brackets.
- 12-14 Years:Parent-driven decisions dominate, with durability and safety certifications outweighing aesthetic preferences. CPSC furniture stability standards and California Proposition 65 compliance requirements filter product availability for this segment.
- 15-17 Years:Part-time employment and digital payment platforms enable independent accessory and textile purchases. United States suburban markets show teen employment rates exceeding 35 percent, concentrating discretionary spending power in this bracket. Parents retain furniture approval authority while delegating wall art and bedding selections.
- 18-19 Years:College transition and first independent housing drive furniture investment. Dormitory-compatible dimensions and flat-pack portability become critical specifications, with Urban Outfitters and direct-to-consumer brands capturing this mobility-oriented demand.
- Others:Gift purchases and transitional spaces for blended families create occasional demand outside core age brackets. Seasonal promotional calendars target grandparents and extended family during holiday periods.
12-14 Years represents the largest addressable population base; 15-17 Years shows the steepest expansion trajectory as independent purchasing influence compounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in Zhejiang and Guangdong provinces supply the majority of flat-pack furniture and printed accessories, while consumption concentrates in affluent suburban households across the United States, Germany, and coastal China.
United States
Teen employment rates exceeding 35 percent in suburban markets drive independent purchasing power among 15-17 year olds. The US Consumer Product Safety Commission enforces furniture stability standards that filter product availability for younger age brackets. California's Proposition 65 labeling requirements create de facto national compliance obligations for décor containing listed chemicals.
Germany
REACH substance restrictions accelerate demand for certified low-VOC wall coverings and OEKO-TEX Standard 100 labeled textiles among safety-conscious households. The country's national chemical regulator maintains strict enforcement of hazardous substance limits in surface coatings sold to adolescents. Craft workshops in Bavaria supply distressed wood treatments for vintage-styled furniture lines.
China
Rapid urbanization and rising disposable incomes in coastal metropolitan markets expand the addressable middle-class teen population. The Ministry of Ecology and Environment implements dual carbon goals that pressure manufacturers toward sustainable material sourcing. Manufacturing clusters in Hangzhou and Shenzhen dominate digital printing platforms for personalized wall art.
France
Urban rental markets favor damage-free peel-and-stick vinyl wall coverings rated for clean removal. The national health and safety regulator enforces REACH-aligned substance restrictions through ANSM oversight of consumer product safety. Parisian design studios curate Bohemian aesthetic collections that merge macramé textiles with rattan accents.
Netherlands
Compact living spaces in Amsterdam and Rotterdam drive demand for modular, storage-optimized furniture footprints. Extended producer responsibility frameworks for furniture recycling reshape material selection and end-of-life cost structures. Rotterdam logistics hubs facilitate flat-pack distribution across Northern European retail channels.
Teen Room Décor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. The market exhibits tiered consolidation, with mass-market volume players anchoring global scale while curated specialty retailers capture premium positioning. Three archetypes dominate: catalog-heritage premium brands, democratic-design volume leaders, and platform-native customization specialists. Competitive moves center on subscription refresh services and augmented reality visualization tools that reduce return rates.
Among catalog-heritage retailers, Pottery Barn Teen exemplifies premium suburban positioning through sustained affluent household penetration. IKEA occupies the democratic-design tier, leveraging flat-pack logistics and standardized dimensions for global store network replenishment. Urban Outfitters, Inc. sits within the curated aesthetic vector, merging streetwear culture with interior styling for older teen demographics transitioning to independent housing.
| Leading Market Players |
|---|
| Pottery Barn Teen |
| IKEA |
| Urban Outfitters, Inc. |
| Spoonflower |
| West Elm |
| Bed Bath and Beyond Inc. |
| Etsy |
| Ban.do |
| Dormify |
| Others |
Value Network & Pricing Analysis
Premium-to-commodity bifurcation between catalog-heritage brands and flat-pack volume players manifests in divergent margin structures and sourcing footprints across the teen room décor market. Certification ladders—OEKO-TEX Standard 100, REACH compliance, California Proposition 65—separate price tiers while driving supply chain reconfiguration toward Turkish dye houses and European craft workshops.
Pricing Analysis
Margin tightening in textile categories reflects cotton and polyester price volatility that limits pass-through to price-elastic bedding buyers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and customization depth. Cost-down pressure on printed accessories accelerates as digital-native teens demand same-week fulfillment without premium surcharges. Independent 15-17 year old purchasers show highest price sensitivity on wall art and textiles, while affluent suburban parents absorb furniture premiums.
Supply Chain Analysis
Direct-to-retailer channels from Zhejiang and Guangdong province suppliers dominate flat-pack furniture and printed accessory flows. Manufacturing draws from Malaysian rubberwood plantations, Turkish REACH-compliant dye houses, and Chinese Guangdong foundries. Tariff exposure on Chinese-origin goods creates structural vulnerability for volume players dependent on Zhejiang printing platforms. Distribution runs through Rotterdam logistics hubs for Northern European retail channels and direct container routes to US West Coast ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as players pursue captive control over digital printing platforms to compress fulfillment lead times and capture customization premiums.
For Market Incumbents: Lock in exclusive capacity at Hangzhou and Shenzhen digital printing clusters before platform-native competitors scale. Secure OEKO-TEX Standard 100 certification across bedding lines to defend margin position against REACH-compliant European entrants. Channel control through subscription refresh services creates switching costs that protect against direct-to-consumer disintermediation.
For New Entrants and Emerging Players: College-transition 18-19 year olds seeking dormitory-compatible flat-pack furniture represent the most penetrable white-space segment. Augmented reality visualization tools reduce return rates for online-first buyers underserved by incumbent showroom networks. Partner with peel-and-stick vinyl formulators to bypass capital-intensive furniture manufacturing entirely.
For Investors and Strategic Acquirers: Re-rating potential sits with platform-native customization specialists given on-demand manufacturing technology maturation and Gen Z purchasing autonomy expansion. Five-to-ten year viability hinges on circular material sourcing infrastructure ahead of EU extended producer responsibility mandates. Monitor EU furniture recycling framework implementation timelines as inflection signal for circular economy positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Refresh Service Launch | Recurring revenue models capture lifetime value beyond single-transaction economics in seasonal textile categories. |
| Augmented Reality Visualization Deployment | Smartphone-based room preview tools reduce return rates for online furniture buyers lacking physical showroom access. |
| REACH-Compliant Supply Chain Reconfiguration | Turkish and Portuguese dye house partnerships maintain European market access under tightening substance restrictions. |
| Digital Printing Platform Integration | Cloud-based design-to-fulfillment systems enable mass customization without finished goods inventory holding costs. |
| Circular Material Sourcing Program | Take-back program infrastructure creates first-mover advantage ahead of EU extended producer responsibility enforcement. |
Research Methodology
Trade association filings, customs import records, and retail point-of-sale databases formed the secondary backbone for demand quantification and competitive positioning assessment. Primary interviews with category buyers at major retailers, brand managers at teen-focused décor companies, supply chain directors at flat-pack furniture manufacturers, and digital printing platform operators provided forward-looking demand signals. Bottom-up and top-down triangulation validated volume estimates across product categories and regional markets.
Bottom-up modeling aggregated unit economics across wall art, bedding, furniture, and lighting segments while top-down cross-checks applied demographic and spending penetration rates. Segmentation dimensions included product type, style aesthetic, material composition, and target age group purchasing authority throughout the projection horizon. CAGRs derived from historical growth pattern analysis adjusted for technology adoption curves and regulatory implementation schedules. Forecast inputs incorporated teen employment rate trajectories and digital payment platform penetration metrics.
Revisions become necessary when REACH substance restriction amendments, Chinese tariff schedule changes, or cotton futures volatility materialize beyond baseline assumptions. Practitioners should monitor EU extended producer responsibility framework rollouts and Gen Z digital payment adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
US Wall Beds Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Bunk Beds Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Heated Bedding Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Germany Mattress Market