
 Back Table and Cart Covers Market | 2026-2036
Back Table and Cart Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Back Table and Cart Covers Market Analysis
Consolidation among ambulatory surgery center chains is repositioning procurement leverage toward group purchasing organizations. Cardinal Health leverages its distribution infrastructure to sustain contract penetration across integrated delivery networks. Medline Industries, Inc. anchors private-label volume through direct sales teams embedded in hospital supply committees. Mölnlycke Health Care differentiates via proprietary fabric technologies that compete on validated microbial barrier performance.
Back table and cart covers are sterile or non-sterile textile barriers engineered to shield surgical equipment surfaces from particulate and microbial contamination, typically constructed from spunbond-meltblown-spunbond polypropylene laminates or fluid-resistant polyester blends with sealed seams. Their primary purpose is maintaining aseptic fields during operative procedures while enabling rapid turnover between cases. The disposable product type dominates hospital purchasing due to eliminated reprocessing labor and laundry compliance costs, whereas reusable covers retain margin pools in catering and event applications where sterilization protocols are less stringent. Polyester material grades command preference in medical settings for combined durability and low-linting characteristics, while vinyl alternatives occupy price-sensitive segments.
FDA 510(k) clearance requirements for surgical accessories and EPA antimicrobial coating registrations shape product development cycles and label claims in the United States. The Joint Commission's infection control standards and OSHA bloodborne pathogen regulations further constrain material selection and disposal workflows. Stakeholders must monitor evolving single-use plastic restrictions at state levels and validate that barrier test methodologies align with AAMI PB70 classifications before committing to capacity expansion.
Market Dynamics
Hospital outpatient surgical departments are expanding procurement of disposable covers to reduce cross-contamination risks. The FDA's updated medical device cleanliness standards are compelling manufacturers to validate barrier performance claims. Demand is concentrating in the United States as health systems standardize perioperative supply contracts.
Growth Catalysts
- AAMI PB70 Classifications:The FDA's updated medical device cleanliness standards compel manufacturers to validate barrier performance claims through standardized testing protocols.
- Spunbond-Meltblown-Spunbond Laminates:Advanced polypropylene fabric technologies deliver superior microbial barrier performance that hospital infection control committees now mandate.
- Ambulatory Surgery Centers:Rapid expansion of outpatient surgical facilities in the United States drives volume procurement of single-use sterile barriers.
Market Restraints
- Polypropylene Feedstock Volatility:Crude oil price fluctuations directly compress margins on SMS laminate production.
- Single-Use Plastic Restrictions:State-level environmental regulations in California and New York threaten disposable cover market access.
- Reusable Polyester Alternatives:Launderable barrier systems retain footholds in veterinary and dental settings where sterilization protocols are less stringent.
Strategic Opportunities
- EPA Antimicrobial Coating Registrations:Validated antimicrobial surface treatments open premium pricing tiers for barrier products in orthopedic and neurosurgical suites.
- Integrated Delivery Networks:Consolidated health systems in Texas and Florida present concentrated contract opportunities for standardized cover specifications.
- Sealed Seam Technologies:Heat-sealed construction methods eliminate particle shedding that stitched alternatives permit, creating differentiation in critical care applications.
Industry Challenges
- 510(k) Clearance Timelines:FDA surgical accessory review cycles extend 12-18 months for novel barrier materials, delaying revenue recognition.
- Legacy Inventory Systems:Hospital ERP platforms lack granular tracking of cover consumption patterns, obscuring demand signals for suppliers.
- OSHA Bloodborne Pathogen Compliance:Disposal workflow redesigns require capital investment in sealed containment systems for contaminated barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back Table and Cart Covers Market |
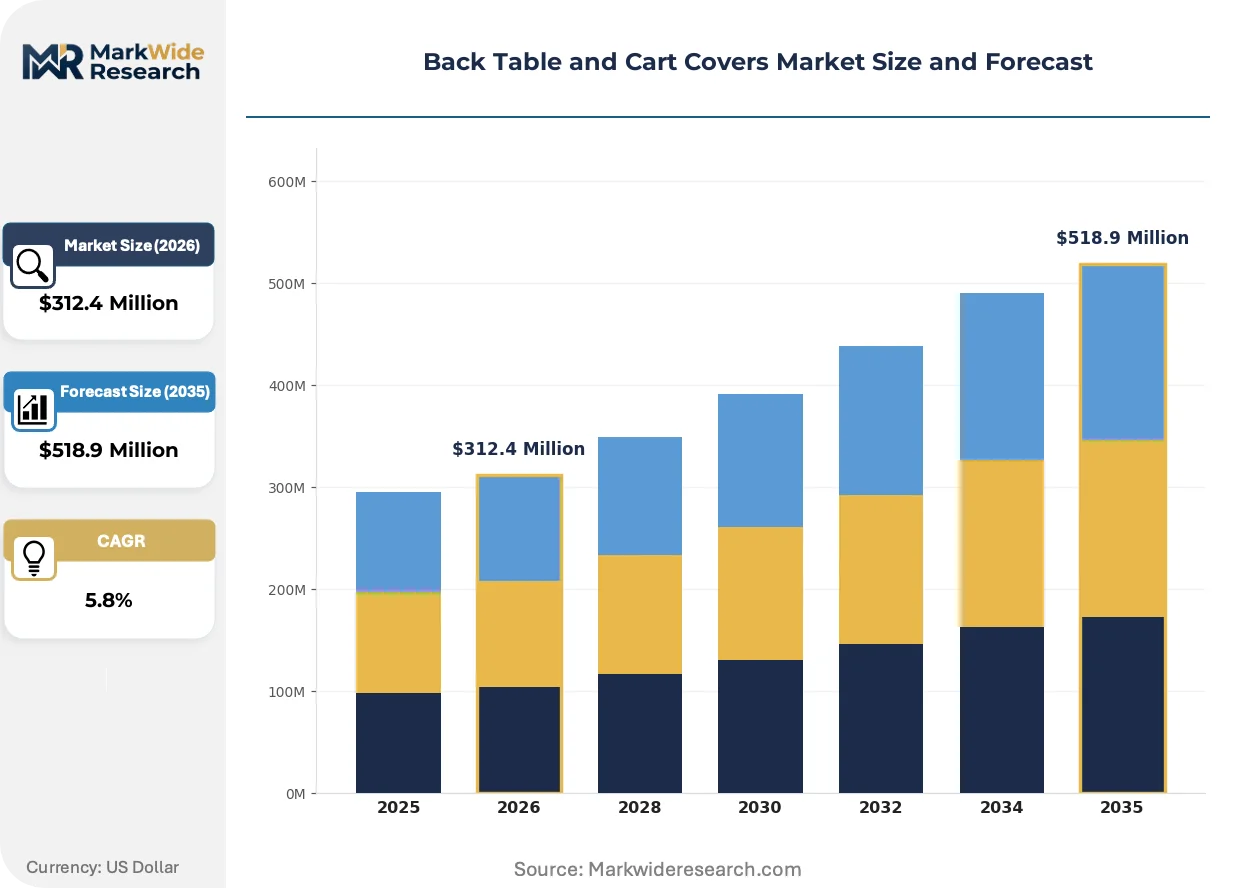
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Customizable, Standard Material: Polyester, Vinyl, Cotton, Nylon Usage: Medical, Catering, Events, Household Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | 3M, Cardinal Health, Medline Industries, Inc., Halyard Health, SW Med-Source, David Scott Company, TIDI Products, LLC, Ansell Healthcare LLC, Mölnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back Table and Cart Covers Market Emerging Trajectories
Barrier material science is advancing faster than sterilization protocol updates can absorb. Manufacturers now compete on validated microbial performance rather than commodity pricing.
Antimicrobial-coated spunbond-meltblown-spunbond laminates is electrifying the premium segment of surgical barrier products. Hospital infection control committees in academic medical centers are mandating these enhanced fabrics for orthopedic and cardiovascular procedures. The technology is compressing market share for untreated polypropylene alternatives that lack validated kill-rate documentation.
EPA antimicrobial coating registrations are reshaping product development cycles and label claims in the United States. Manufacturers must submit efficacy data against specific pathogen panels before marketing treated barriers. Ambulatory surgery centers in the Southeast are prioritizing EPA-registered products in perioperative supply contracts to preempt Joint Commission scrutiny.
Group purchasing organization consolidation is concentrating procurement leverage among fewer decision-makers. Integrated delivery networks in California and Texas are standardizing cover specifications across 20-plus facility footprints. This behavioral shift is most visible in the Southwest, where Catholic Health Initiatives and HCA Healthcare have consolidated vendor panels to three approved suppliers per product category.
Back Table and Cart Covers Market Segmentation
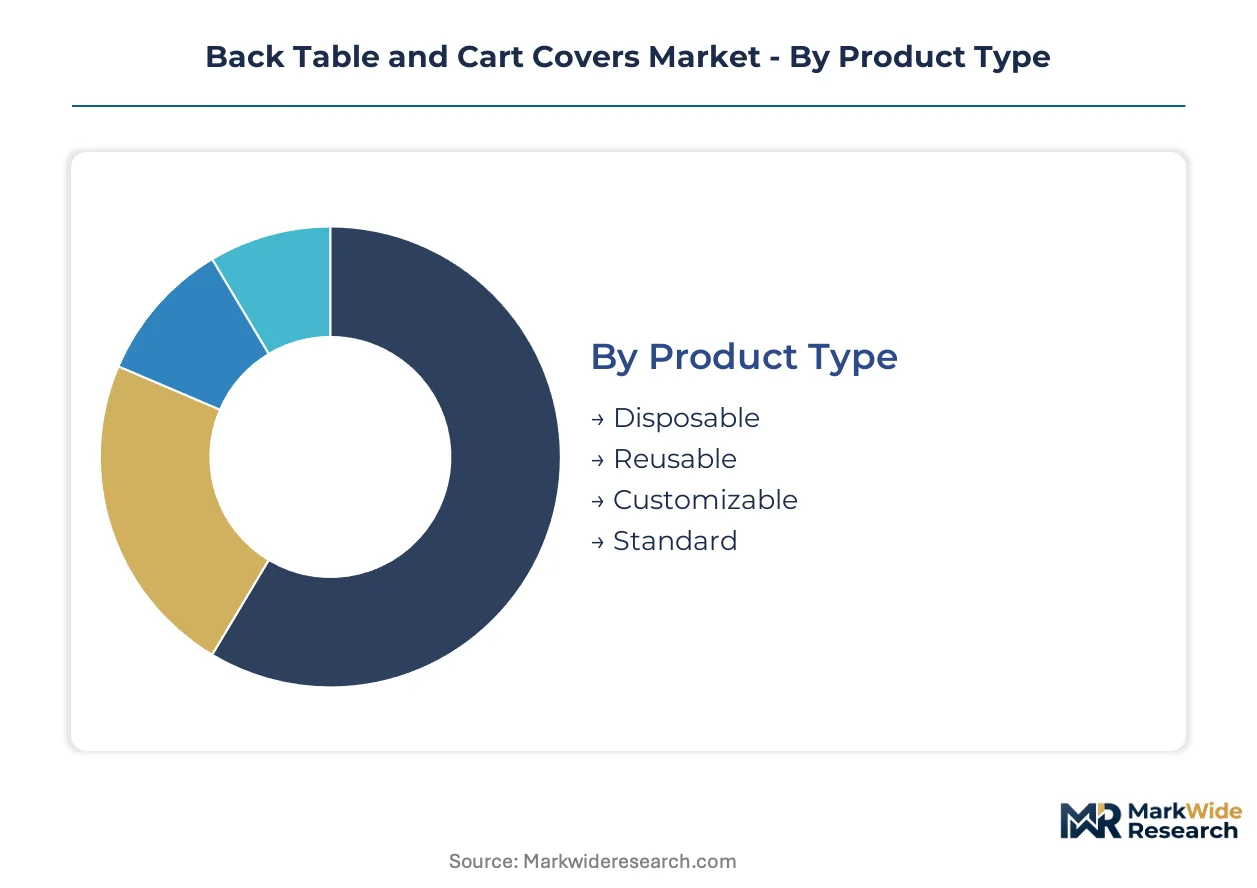
Segmentation in the back table and cart covers market exposes divergent margin structures across sterilization protocols and procurement channels. Disposable barriers command hospital purchasing budgets while reusable alternatives retain footholds in cost-sensitive verticals. Material selection and distribution access determine competitive positioning more than brand recognition.
Product Type:
Disposable covers dominate hospital volume procurement while reusable systems compete on total cost of ownership in veterinary and dental settings.
- Disposable:Spunbond-meltblown-spunbond polypropylene laminates eliminate reprocessing labor and laundry compliance costs. Hospital outpatient surgical departments in the United States prioritize single-use barriers to reduce cross-contamination risks per FDA cleanliness standards.
- Reusable:Fluid-resistant polyester blends withstand 75-100 industrial laundering cycles. Veterinary clinics and ambulatory surgery centers in Florida and Texas select launderable options where sterilization protocols are less stringent than academic medical centers.
- Customizable:Dimension-specific covers fit proprietary equipment configurations. Original equipment manufacturers embed these in surgical table and cart purchase agreements.
- Standard:Universal sizing reduces inventory complexity for distributors. Group purchasing organizations favor standardized specifications across integrated delivery network footprints.
Today's leader: Disposable. Tomorrow's challenger: Customizable.
Material:
Polyester grades anchor medical applications through combined durability and low-linting characteristics while vinyl alternatives occupy price-sensitive segments.
- Polyester:Sealed-seam construction eliminates particle shedding that stitched alternatives permit. Hospital infection control committees mandate polyester for orthopedic and cardiovascular procedures where AAMI PB70 barrier performance is non-negotiable.
- Vinyl:Thermoplastic formulations offer fluid resistance at lower unit cost. Catering and event applications in California select vinyl where single-use plastic restrictions have not yet prohibited disposal.
- Cotton:Natural fiber barriers retain legacy usage in non-sterile equipment protection. Some ambulatory surgery centers specify cotton for non-critical surface coverage.
- Nylon:High tensile strength supports heavy-duty reusable applications. Veterinary surgical suites specify nylon for equipment covers subject to repeated sterilization cycles.
Polyester holds current volume leadership. Nylon is gaining share fastest in specialized reusable segments.
Usage:
Medical applications concentrate demand in sterile barrier procurement while catering and events drive reusable cover volume.
- Medical:Aseptic field maintenance during operative procedures requires validated microbial barrier performance. The Joint Commission's infection control standards and OSHA bloodborne pathogen regulations constrain material selection and disposal workflows.
- Catering:Food service equipment protection prioritizes cost efficiency over sterilization validation. Reusable polyester covers dominate this segment through laundry service integration.
- Events:Temporary equipment shielding for conference and exhibition infrastructure. Rental companies stock standardized sizes for rapid deployment.
- Household:Consumer-grade protection for home medical equipment and mobility aids. Online direct-to-consumer channels serve this fragmented demand.
Medical commands premium pricing power. Catering delivers volume scale through reusable economics.
Distribution Channel:
Direct sales teams embedded in hospital supply committees capture integrated delivery network contracts while distributors serve fragmented ambulatory surgery center demand.
- Online:E-commerce platforms enable small-facility procurement without sales representative overhead. Ambulatory surgery centers in the Southeast utilize online channels for standardized cover replenishment.
- Retail:Medical supply stores serve veterinary clinics and dental practices with immediate availability requirements. Regional chains in Texas and Florida stock polyester grades for walk-in purchase.
- Direct Sales:Manufacturer representatives participate in value analysis committees for contract specification. Cardinal Health and Medline Industries leverage embedded teams across Catholic Health Initiatives and HCA Healthcare systems.
- Distributors:Independent distributors aggregate demand from smaller facilities lacking procurement infrastructure. Group purchasing organization consolidation is concentrating leverage toward fewer distribution partners.
Direct sales controls strategic accounts. Online channels are climbing the fastest in ambulatory surgery center procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates surgical barrier procurement through standardized perioperative supply contracts, while Germany anchors European demand through stringent MDR compliance requirements for sterile medical textiles.
United States
Hospital outpatient surgical departments in Texas and Florida are expanding disposable cover procurement to reduce cross-contamination risks. The FDA's updated medical device cleanliness standards compel manufacturers to validate barrier performance claims through AAMI PB70 testing protocols. Integrated delivery networks in the Southwest, including Catholic Health Initiatives and HCA Healthcare facilities, have consolidated vendor panels to three approved suppliers per product category.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia mandate validated microbial barrier performance for orthopedic and cardiovascular procedures. The EU MDR requires enhanced technical documentation for surgical accessories, extending product registration timelines. Industrial clusters around Stuttgart and Munich host specialized textile manufacturers developing sealed-seam polyester technologies for critical care applications.
United Kingdom
NHS trusts in London and the Southeast are standardizing cover specifications across hospital networks to reduce procurement complexity. The UK Health Security Agency's infection prevention guidelines influence material selection for sterile barriers. Manufacturing facilities in the Midlands supply private-label volumes to group purchasing organizations serving ambulatory surgery centers.
China
Domestic hospital construction in the Yangtze River Delta and Pearl River Delta is driving procurement of single-use sterile barriers. The NMPA's medical device classification system requires registration for surgical accessory imports. Local manufacturers in Zhejiang and Guangdong provinces are expanding spunbond-meltblown-spunbond laminate capacity to serve regional health system demand.
Japan
Metropolitan hospitals in Tokyo and Osaka prioritize low-linting polyester grades for aseptic field maintenance during operative procedures. METI's quality infrastructure framework supports domestic textile innovation for medical applications. Specialized fabricators in the Chubu region around Nagoya supply customized dimension-specific covers for proprietary surgical equipment configurations.
Back Table and Cart Covers Market Vendor Landscape
United States producers anchor one tier through embedded direct sales teams and distribution infrastructure; European specialists hold differentiated positions via proprietary fabric technologies and regulatory compliance capabilities. The market structure concentrates around three to five dominant suppliers with integrated delivery network contracts, while mid-tier players compete through private-label volume and regional distribution partnerships. Strategic archetypes include distribution-leveraged conglomerates, technology-differentiated specialists, and private-label manufacturers. Competitive moves center on group purchasing organization consolidation and antimicrobial coating registrations that enable premium pricing tiers.
Among United States-based suppliers, Cardinal Health and Medline Industries exemplify the distribution-leveraged archetype through embedded sales participation in hospital value analysis committees. Mölnlycke Health Care represents the technology-differentiated specialist tier, occupying a position anchored by proprietary barrier fabric development and validated microbial performance claims. These three companies collectively illustrate how competitive positioning in surgical barriers depends on channel access, regulatory validation depth, and material science differentiation rather than commodity manufacturing scale.
| Leading Market Players |
|---|
| 3M |
| Cardinal Health |
| Medline Industries, Inc. |
| Halyard Health |
| SW Med-Source |
| David Scott Company |
| TIDI Products, LLC |
| Ansell Healthcare LLC |
| Mölnlycke Health Care |
| Others |
Supply Flow & Price Mechanics
Polypropylene resin feedstock costs cascade through spunbond-meltblown-spunbond laminate production, compressing margins at converters serving price-sensitive ambulatory surgery centers while enabling premium capture for EPA-registered antimicrobial variants sold to academic medical centers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard polypropylene barriers, intensifying competition in economy-tier segments. Pricing stratifies across premium, standard, and economy tiers based on AAMI PB70 certification level and antimicrobial coating validation. Cost compression in standard-grade laminates is intensifying because of feedstock volatility and Asian import competition. Ambulatory surgery centers in the Southeast exhibit highest price sensitivity, while orthopedic and neurosurgical suites at academic medical centers demonstrate lowest sensitivity due to infection control committee mandates.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand, while distributor networks aggregate fragmented ambulatory surgery center procurement. Manufacturing concentrates in the United States, China, and Germany, with Zhejiang and Guangdong provinces expanding SMS laminate capacity. Supply chains draw from polypropylene resin, meltblown fabric, and antimicrobial coating chemical inputs. Single-source vulnerability in specialized meltblown equipment creates bottleneck risk for barrier performance upgrades. Distribution runs through Cardinal Health and Medline Industries for national hospital contracts, supplemented by regional distributors serving smaller facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The back table and cart covers market functions as a stable compounder, with outpatient surgical volume expansion providing durable demand tailwinds through health system consolidation and infection control protocol tightening.
For Market Incumbents: Extend proprietary fabric technology portfolios through sealed-seam polyester innovations that exceed AAMI PB70 benchmarks, defending against commodity import pressure from Chinese converters. Deepen embedded sales team presence in Texas and Florida integrated delivery networks to preempt vendor panel consolidation. Anchor contract renewals through antimicrobial coating registrations that create switching costs for hospital infection control committees.
For New Entrants and Emerging Players: E-commerce direct procurement routes offer lowest-friction entry for standardized disposable covers targeting independent ambulatory surgery centers in the Southeast. Veterinary and dental settings present underpenetrated reusable cover demand with less stringent sterilization validation requirements. Private-label partnerships with regional distributors in California and New York circumvent direct sales team infrastructure gaps.
For Investors and Strategic Acquirers: Consolidation pressure builds where group purchasing organization leverage concentrates procurement among three to five approved suppliers per category. The five-to-ten year viability window favors technology-differentiated specialists with validated microbial barrier claims over commodity converters. Monitor EPA antimicrobial coating registration timelines as inflection signals for premium pricing power expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA Antimicrobial Coating Registration | Validated efficacy claims enable premium pricing in orthopedic and neurosurgical suites. |
| Sealed-Seam Technology Investment | Heat-sealed construction eliminates particle shedding for critical care applications. |
| Integrated Delivery Network Partnership | Multi-facility contracts with Catholic Health Initiatives and HCA Healthcare secure volume. |
| Private-Label Manufacturing Scale-Up | Direct sales team embedding in hospital supply committees captures GPO consolidation. |
| Alternative Material R&D Program | Biodegradable barrier development preempts California and New York single-use plastic restrictions. |
Methodological Framework
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each market through interviews with hospital purchasing committee members, group purchasing organization contracts managers, biomedical engineers, and sterile processing department directors. Secondary validation draws from FDA 510(k) filings, EPA antimicrobial product registrations, hospital procurement databases, and AAMI technical documents. Bottom-up facility-level demand modeling triangulates against top-down health system expenditure analysis.
Segmentation granularity operates at product type, material grade, usage setting, and distribution channel levels across the projection horizon. CAGRs derive from surgical procedure volume trajectories, health system consolidation patterns, and regulatory compliance cost pass-through assumptions. Forecast inputs incorporate AAMI PB70 adoption curves, ambulatory surgery center construction pipelines, and state-level single-use plastic restriction implementation timelines.
The model assumes a particular technology adoption path for antimicrobial-coated barriers; alternative pathways for biodegradable material substitution would alter the outlook. Forecasts reflect assumptions about FDA review cycle durations, feedstock price stability, and GPO consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Interactive Tables Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Accent Tables Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Oman Kitchen Hood Market