
 Bed Wedge Market | 2026-2036
Bed Wedge Market Size, Share, and Industry Trends Forecast 2026-2036
Bed Wedge Market Analytics
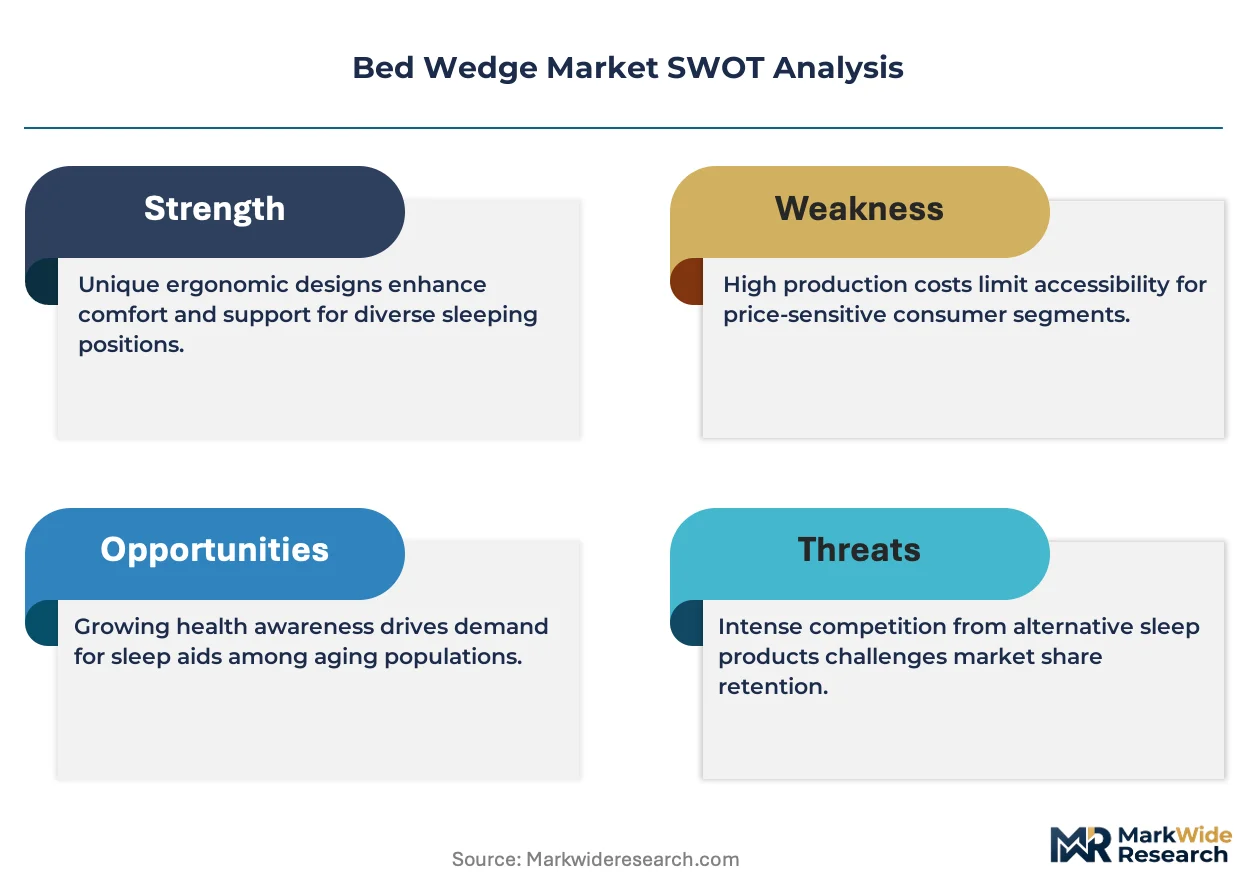
Direct-to-consumer mattress channels is narrowing as legacy sleep brands and specialty orthopedic suppliers consolidate digital shelf space. MedCline Inc. leverages clinical positioning around acid reflux and sleep apnea to sustain premium pricing in physician-adjacent channels. Brentwood Home LLC anchors its wedge assortment within a broader foam mattress ecosystem, competing on material transparency and domestic manufacturing. Contour Products specializes in multi-position adjustable designs, occupying a mid-market tier between basic foam wedges and motorized hospital alternatives.
A bed wedge is an inclined positioning device, typically constructed from polyurethane or viscoelastic foam at angles between 30 and 45 degrees, engineered to elevate the upper torso for therapeutic or comfort purposes. The product serves commercial and residential markets by mitigating symptoms of gastroesophageal reflux disease, obstructive sleep apnea, and postoperative edema without pharmaceutical or surgical intervention. Memory foam wedges command margin concentration due to material cost premiums and consumer willingness to pay for pressure redistribution, while adjustable wedges represent the fastest-growing product configuration as users seek customizable elevation control. Acid reflux applications dominate volume throughput, though post-surgery recovery segments in hospital and rehabilitation channels carry higher per-unit pricing and institutional procurement standards.
FDA Class I device classifications govern labeling and manufacturing quality in the United States, while ISO 13485 certification requirements shape supplier eligibility for European hospital tenders and institutional procurement frameworks. The EU Medical Device Regulation imposes stricter post-market surveillance obligations on wedge products marketed with therapeutic claims, compressing compliance timelines for smaller foam converters. Stakeholders must monitor how reimbursement policy evolution for home sleep therapy equipment alters consumer out-of-pocket exposure and channel economics across direct-to-consumer and durable medical equipment pathways.
Market Dynamics
Direct-to-consumer mattress brands and specialty orthopedic suppliers are consolidating digital shelf space, compressing margins for standalone wedge manufacturers while elevating clinical positioning as the primary differentiation vector.
Growth Catalysts
- FDA Class I pathway:Streamlined device classification in the United States reduces regulatory friction for foam converters entering therapeutic positioning markets, accelerating time-to-revenue for new entrants.
- GERD prevalence:Elevated diagnosis rates among aging populations in Germany and Japan sustain physician recommendation volumes for non-pharmaceutical reflux management interventions.
- Polyurethane foam innovation:Viscoelastic formulations with enhanced pressure redistribution properties command consumer willingness to pay premium price points in home care channels.
Market Restraints
- Petrochemical input volatility:Polyether polyol and TDI price swings compress foam converter margins, forcing inventory risk absorption or pass-through pricing conflicts with retail partners.
- Single-source foam supply:Domestic U.S. viscoelastic production concentrates among three major chemical conglomerates, creating vulnerability to force majeure disruptions.
- Adjustable bed substitution:Motorized hospital-grade and consumer adjustable bases capture elevation-seeking demand with programmable positioning, eroding wedge volume in premium segments.
Strategic Opportunities
- Post-surgical rehabilitation:Hospital discharge protocols in France and Italy increasingly specify home-based elevation therapy, opening institutional procurement pathways for certified wedge suppliers.
- EU MDR compliance arbitrage:Stricter post-market surveillance obligations under the Medical Device Regulation compress timelines for smaller competitors, creating acquisition targets for scaled foam converters with ISO 13485 certification.
- Telehealth integration:Remote patient monitoring platforms are incorporating sleep positioning data, enabling wedge manufacturers to embed sensors and capture recurring revenue through digital health subscriptions.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and skin sensitization studies face laboratory capacity constraints, extending product launch timelines by four to six months for novel foam formulations.
- Legacy DME channel conflict:Direct-to-consumer growth alienates durable medical equipment distributors who control Medicare reimbursement pathways, requiring parallel channel architecture investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed Wedge Market |
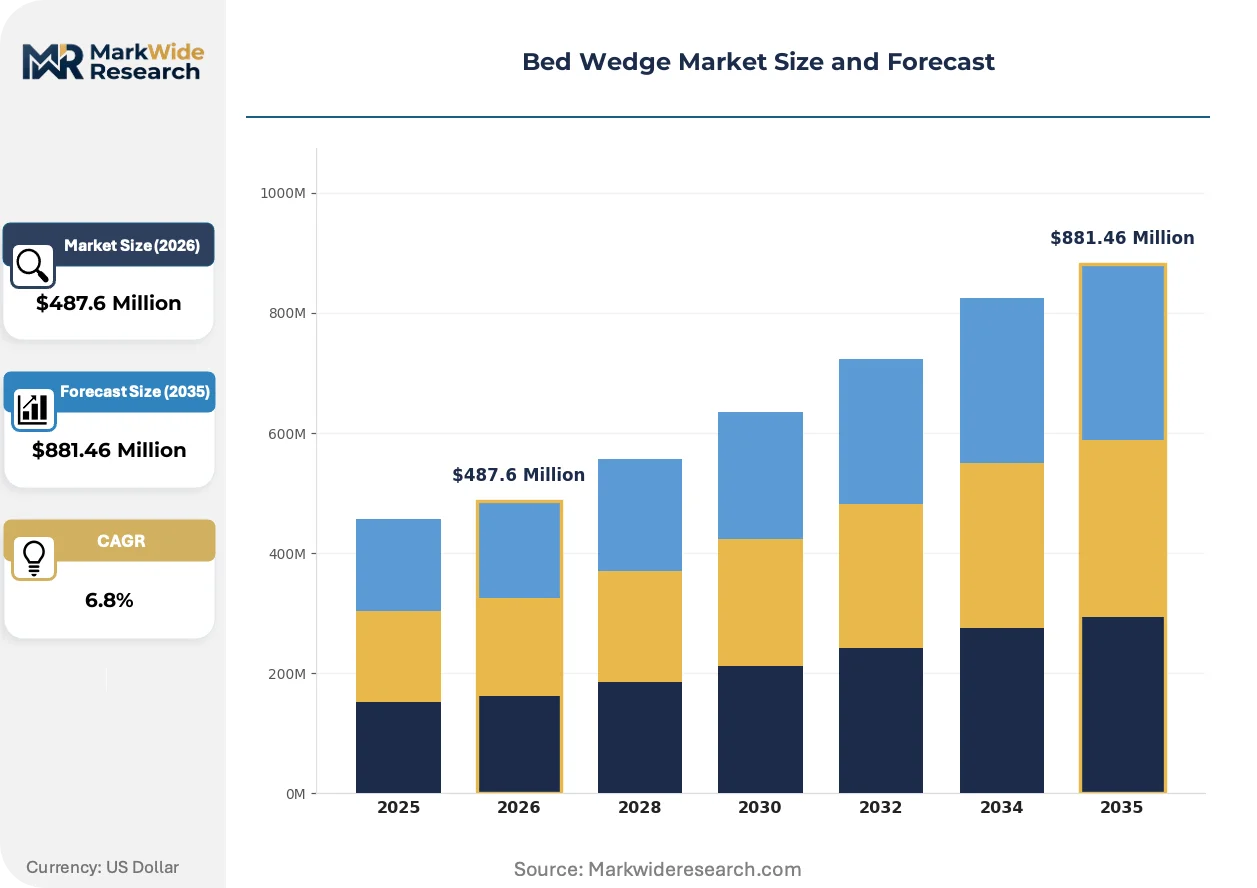
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wedge, Memory Foam Wedge, Adjustable Wedge, Inflatable Wedge Material: Polyester, Cotton, Latex, Gel End User: Hospitals, Home Care, Rehabilitation Centers, Elderly Care Facilities Application: Acid Reflux, Sleep Apnea, Post-Surgery Recovery, Snoring Relief |
| Companies Covered | MedCline Inc., Brentwood Home LLC, Contour Products, Avana Comfort, Alex Orthopedic, Inc., OneUp Innovations, Inc., Inventive Sleep, Inc., MedSlant LLC, Brooklyn Bedding, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed Wedge Market Evolving Landscape
Material science convergence and regulatory digitization are reconfiguring competitive advantage away from pure foam sourcing toward integrated clinical validation and connected health ecosystems.
Memory foam is hybridizing with gel-infusion and phase-change materials to address thermal retention complaints that historically limited wedge adoption among hot sleepers. Sleep clinics and post-acute care facilities are specifying these temperature-neutral configurations for patient compliance protocols. The technology is hybridizing cost structures, forcing mid-market suppliers to abandon basic polyurethane offerings or exit the therapeutic positioning category entirely.
The EU Medical Device Regulation's Unique Device Identification mandate is imposing serialization and traceability requirements on wedge products marketed with therapeutic claims. Foam converters must now maintain electronic quality management systems and post-market surveillance documentation previously exempt for general wellness positioning devices. European hospital tenders increasingly exclude suppliers lacking MDR technical documentation, concentrating procurement among ISO 13485-certified manufacturers.
Consumers are unbundling wedge purchases from mattress replacement cycles, treating elevation devices as discrete sleep therapy investments rather than accessory add-ons. Direct-to-consumer brands with clinical content strategies are capturing this intent-driven traffic, while legacy mattress retailers lose attachment-rate leverage. The shift is most pronounced in the United States, where GERD-diagnosed households research physician-recommended positioning solutions independently of bedding replacement schedules.
Bed Wedge Market Segmentation
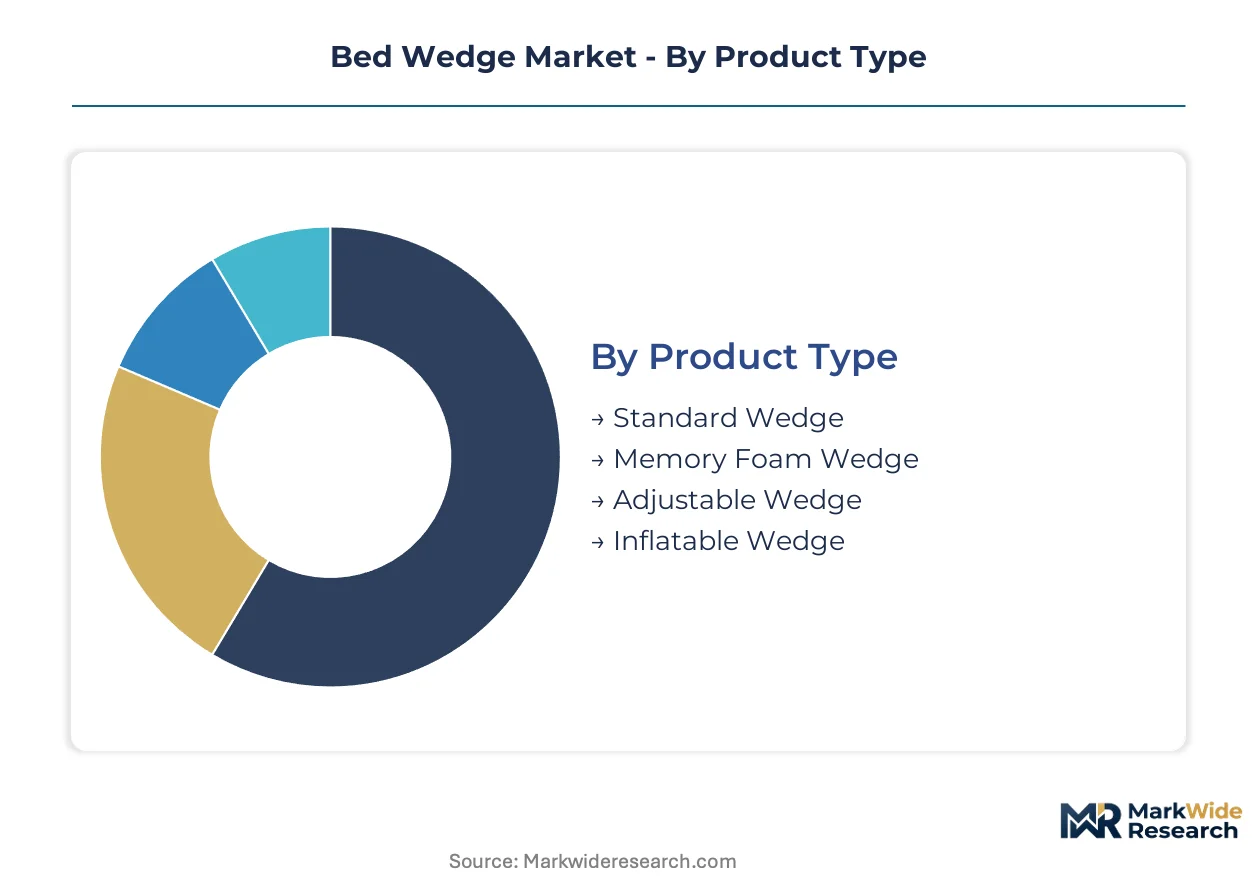
Bed wedge manufacturers configure product portfolios across four intersecting dimensions. Material selection determines margin structure and regulatory pathway, while end-user concentration shapes channel economics and certification requirements.
Product Type:
Cost tier differentiation separates commodity foam converters from clinically positioned suppliers with programmable elevation systems.
- Standard Wedge:Basic polyurethane foam construction at fixed 30-45 degree angles serves price-sensitive GERD management in mass retail channels. Demand concentrates in US drugstore chains and supermarket pharmacy sections where physician recommendations convert to immediate purchase without clinical consultation.
- Memory Foam Wedge:Viscoelastic formulations with density ratings between 3-5 pounds per cubic foot command premium positioning through pressure redistribution claims. Hospital discharge planners in Germany and Japan specify these configurations for postoperative edema protocols, sustaining wholesale pricing power against adjustable bed substitution.
- Adjustable Wedge:Modular stacking systems or mechanical ratchet mechanisms enable user-customized elevation angles. The steepest expansion runs through this segment as telehealth platforms integrate positioning data capture.
- Inflatable Wedge:PVC or TPU bladder construction with electric pumps targets travel and temporary rehabilitation scenarios. Travel retail and orthopedic equipment rental networks in France and Italy drive volume for this portable configuration.
Standard wedges command the established base. The steepest expansion runs through adjustable configurations with sensor integration potential.
Material:
Application requirements and thermal regulation performance dictate material selection across home care and institutional procurement channels.
- Polyester:Synthetic fiber fill with hypoallergenic treatments occupies entry-level price bands. Budget-conscious elderly care facilities in Spain and Portugal specify polyester constructions for bulk purchasing agreements.
- Cotton:Natural fiber covers with organic certification appeal to chemical-sensitive consumers in direct-to-consumer channels. US mattress subscription services bundle cotton-covered wedges with latex mattress purchases.
- Latex:Natural rubber foam derived from Hevea brasiliensis offers inherent antimicrobial properties without synthetic additives. The steepest expansion runs through this segment as EU MDR biocompatibility requirements tighten.
- Gel:Phase-change material infusions with thermal conductivity ratings address heat retention complaints in memory foam systems. Sleep clinics in Australia and South Korea specify gel-hybrid wedges for patient compliance protocols in warm climates.
Polyester constructions command the established base. The steepest expansion runs through gel-infused configurations addressing thermal comfort gaps.
End User:
Customer type determines regulatory burden, procurement pathway, and pricing elasticity across institutional and residential markets.
- Hospitals:Acute care facilities require ISO 13485-certified supply chains with lot traceability and sterilization compatibility. Tender specifications in Italy and France increasingly mandate MDR technical documentation for elevation devices used in post-surgical protocols.
- Home Care:Direct-to-consumer and durable medical equipment channels serve GERD-diagnosed households with physician recommendations. Medicare reimbursement pathways in the United States create channel conflict as DME distributors compete with mattress brand direct sales.
- Rehabilitation Centers:Post-acute facilities specify wedges for lymphedema and orthopaedic recovery with documented patient outcomes. The steepest expansion runs through this segment as hospital-at-home protocols expand across European health systems.
- Elderly Care Facilities:Nursing homes and assisted living communities prioritize durability and infection control over premium comfort features. Bulk procurement contracts in Japan's aged care sector concentrate volume among domestic foam converters with established institutional relationships.
Home care channels command the established base. The steepest expansion runs through rehabilitation centers as discharge planning shifts toward home-based elevation therapy.
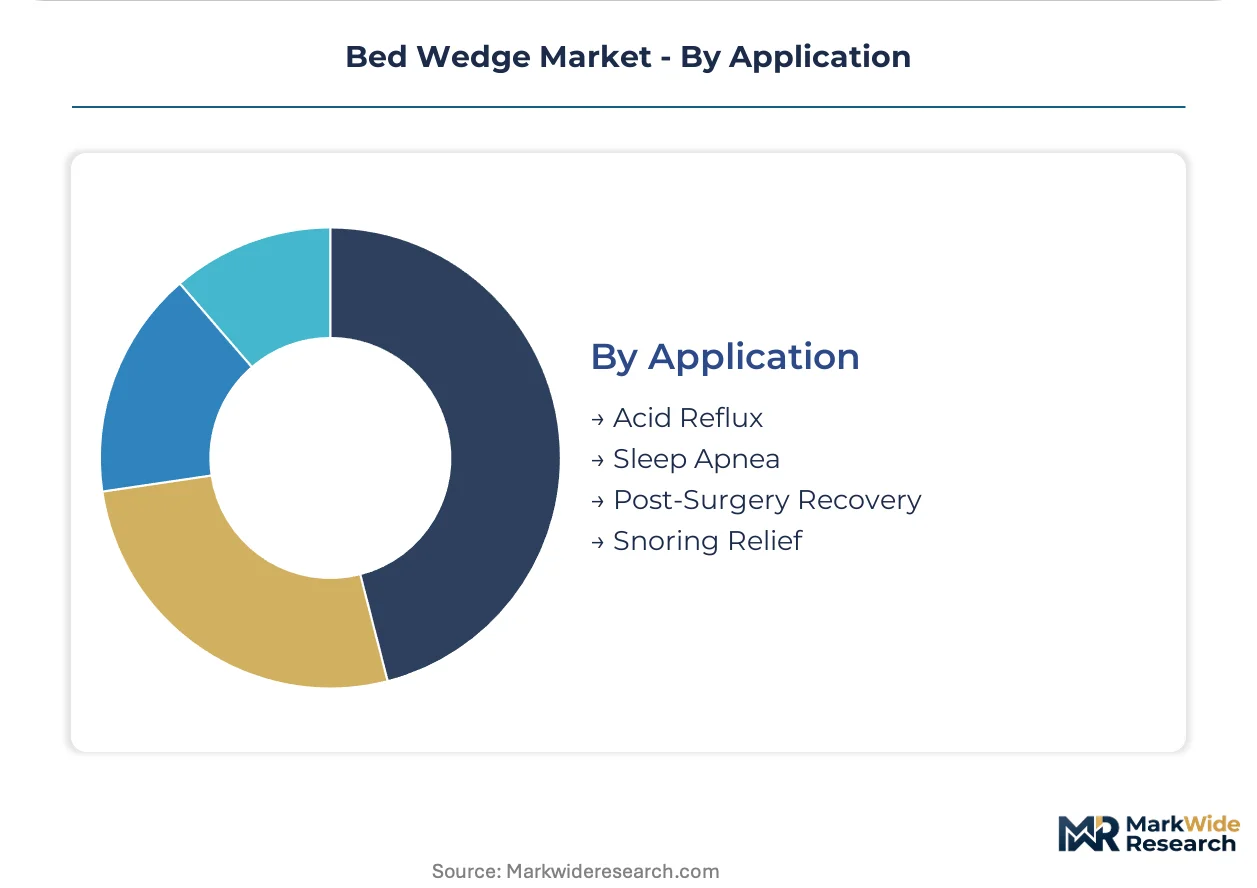
Application:
Clinical indication severity and reimbursement eligibility shape product specification and channel strategy for therapeutic positioning claims.
- Acid Reflux:GERD symptom management represents the highest volume application with physician recommendation driving purchase intent. US gastroenterology practices maintain sample programs with MedCline and similar clinically positioned brands.
- Sleep Apnea:Adjunct positioning therapy for CPAP-intolerant patients requires steeper elevation angles and cervical support integration. Sleep medicine clinics in Germany and Australia specify wedges as conservative intervention before mandibular advancement devices.
- Post-Surgery Recovery:Orthopaedic and cardiac procedures generate institutional procurement with higher per-unit pricing and documentation requirements. The steepest expansion runs through this segment as enhanced recovery after surgery protocols standardize home elevation.
- Snoring Relief:Positional therapy for primary snoring occupies wellness positioning with lighter regulatory scrutiny. Direct-to-consumer marketing in the United Kingdom and Canada emphasizes partner sleep quality rather than clinical outcomes.
Acid reflux applications command the established base. The steepest expansion runs through post-surgery recovery as hospital discharge protocols formalize home-based elevation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where clinical positioning commands premium multiples, while Japanese and Australian markets absorb higher landed costs through aged-care procurement subsidies.
United States
FDA Class I device classification streamlines market entry for foam converters, while Medicare reimbursement pathways through durable medical equipment distributors sustain institutional volume. GERD prevalence among aging populations drives physician recommendation networks, with gastroenterology practices in the Northeast and California maintaining active sample programs for therapeutic positioning brands.
Germany
Hospital discharge planners specify ISO 13485-certified wedges for postoperative edema protocols, creating procurement concentration among certified foam converters. The EU Medical Device Regulation's technical documentation requirements filter tender eligibility, with Baden-Württemberg and Bavaria hosting the dominant medical device manufacturing clusters for foam-based positioning equipment.
Japan
Domestic foam converters with established institutional relationships capture bulk procurement contracts in the aged-care sector. METI standards for medical device quality management shape supplier certification requirements, with manufacturing concentration in the Kanto region around Tokyo and Osaka-Kobe corridor serving rehabilitation facility networks.
Australia
Sleep clinics in New South Wales and Victoria specify temperature-neutral gel-hybrid configurations for patient compliance protocols in warm climates. TGA therapeutic goods registration creates a compliance threshold that favors scaled suppliers with existing ISO 13485 certification, compressing market access for smaller regional foam converters.
United Kingdom
Direct-to-consumer brands with clinical content strategies capture intent-driven traffic from GERD-diagnosed households researching physician-recommended solutions. The Medicines and Healthcare products Regulatory Agency oversees device safety standards, while London and Southeast England concentrate digital health platform development for sleep positioning integration.
Bed Wedge Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying foam formulations and adjustable mechanisms to branded assemblers. Market structure tilts toward consolidation as direct-to-consumer mattress brands and specialty orthopedic suppliers compress digital shelf space for standalone wedge manufacturers. Three archetypes dominate: clinically positioned premium brands, foam-mattress ecosystem players, and mid-market adjustable design specialists. Competitive moves concentrate on M&A absorption of ISO 13485-certified converters and strategic partnerships with telehealth platforms for sensor-enabled positioning data.
Among clinically positioned suppliers, MedCline Inc. and Contour Products exemplify the premium-tier archetype built around physician-adjacent channels and multi-position adjustability. Brentwood Home LLC anchors the foam-mattress ecosystem approach, representing how domestic manufacturing and material transparency claims compete against standalone therapeutic brands. These three occupy distinct competitive vectors without direct product overlap, allowing parallel expansion across reimbursement-dependent and direct-pay channels.
| Leading Market Players |
|---|
| MedCline Inc. |
| Brentwood Home LLC |
| Contour Products |
| Avana Comfort |
| Alex Orthopedic, Inc. |
| OneUp Innovations, Inc. |
| Inventive Sleep, Inc. |
| MedSlant LLC |
| Brooklyn Bedding, LLC |
| Others |
Value Network & Pricing Analysis
Domestic U.S. viscoelastic foam production concentrates among three major chemical conglomerates, channeling margin capture toward converters with captive supply agreements and long-term polyether polyol contracts. This upstream oligopoly forces downstream assemblers to absorb inventory risk or surrender pricing power to retail partners.
Pricing Analysis
The customization-premium spread between standard fixed-angle wedges and sensor-integrated adjustable configurations exceeds threefold, with programmable elevation systems commanding physician-adjacent channel placement. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and gel-infusion material grade. Cost compression in the standard polyurethane segment is intensifying because direct-to-consumer mattress brands bundle wedges as loss-leader attachments. Hospital procurement committees exhibit lowest price sensitivity, while drugstore chain buyers drive aggressive annual renegotiation cycles.
Supply Chain Analysis
Contract manufacturing for adjustable wedge mechanisms concentrates with Taiwanese and South Korean EMS providers holding pneumatic and electromechanical assembly capacity. Raw material flows draw from German TDI suppliers, Chinese polyether polyol producers, and Malaysian natural latex processors. Single-source vulnerability runs through domestic viscoelastic foam allocation during force majeure disruptions. Distribution runs through durable medical equipment distributors controlling Medicare reimbursement pathways, parallel to direct-to-consumer mattress brand fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bed wedge market functions as a service-attach opportunity where digital health subscription layers for sleep positioning data capture expand faster than hardware unit economics. Recurring revenue from telehealth platform integration outpaces one-time wedge sales velocity.
For Market Incumbents: Harden clinical validation moats through ISO 13485 certification expansion and backward integration into gel-infusion foam production. Adjustable bed substitution from motorized hospital-grade alternatives threatens premium segment volume. Priority investment centers on sensor-enabled positioning systems with embedded biometric capture.
For New Entrants and Emerging Players: Pursue post-surgical rehabilitation white space in French and Italian hospital discharge protocols where home-based elevation therapy specifications remain undersupplied. The rehabilitation center segment offers lowest competitive density. Go-to-market positioning should emphasize MDR technical documentation readiness for European tender eligibility.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed foam converters holding ISO 13485 certification but lacking digital health integration capabilities. Five-to-ten year viability hinges on recurring revenue attachment rates from connected positioning platforms. Acquisition target archetype: mid-market adjustable wedge specialists with established institutional relationships. Signal to monitor: telehealth platform partnership announcements indicating sensor integration commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | European hospital tenders increasingly exclude suppliers lacking EU Medical Device Regulation compliance, concentrating procurement. |
| Sensor-Enabled Wedge Development | Telehealth platforms in Germany and Australia incorporate positioning data capture, enabling recurring subscription revenue streams. |
| Backward Integration into Gel-Infusion Foam | Captive supply of phase-change materials addresses thermal retention complaints and protects margin from petrochemical volatility. |
| Hospital System Partnership | Direct relationships with French and Italian discharge planners secure preferred supplier status for post-surgical elevation protocols. |
| Direct-to-Consumer Clinical Content Strategy | GERD-diagnosed households in the United States research physician-recommended solutions independently of bedding replacement cycles. |
Research Methodology
A spread of perspectives from foam converter operations directors, hospital purchasing committee members, durable medical equipment distributors, and sleep clinic medical directors converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, ISO 13485 certification registries, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up unit economics triangulated against top-down category spending estimates across home care and institutional channels.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling across product type, material grade, end-user channel, and clinical application indication. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for regulatory pathway acceleration. Industry-specific forecast inputs included GERD diagnosis rate trajectories and hospital discharge protocol evolution toward home-based elevation therapy.
Sensitivities concentrate around petrochemical input cost volatility, EU MDR compliance timeline compression, and adjustable bed substitution rates in premium consumer segments. Forecasts reflect documented assumptions regarding telehealth platform integration velocity and reimbursement policy stability. Quarterly review of hospital tender specifications, foam chemical spot pricing, and digital health partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bedding Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
Queen Mattress Market