
 Bunk Beds Market | 2026-2036
Bunk Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Bunk Beds Market Analytics
Subscription-based mattress replacement and extended warranty programs is shifting how bunk bed value gets captured across the ownership cycle. Woodcrest Manufacturing leverages vertical integration into solid-wood milling to control raw material quality and lead times. AFI Furnishings anchors its position through specialized hospitality contracts with summer camp and dormitory operators. Max & Lily differentiates via direct-to-consumer channels that bypass traditional furniture retail markups.
A bunk bed is a stacked sleeping apparatus consisting of two or more bed frames arranged vertically, typically constructed with posts at each corner, side rails, and a ladder or staircase access system, designed to maximize floor space utilization in residential, institutional, and commercial sleeping quarters. Standard bunk beds dominate volume shipments, while loft bunk beds command higher margins by integrating desks, storage, or seating beneath the elevated sleeping platform. Wood and metal materials split the market by price tier, with engineered wood gaining ground in flat-pack e-commerce fulfillment where shipping weight determines competitiveness.
The Consumer Product Safety Commission enforces 16 CFR Part 1513 for entrapment hazards and guardrail spacing, while ASTM F1427 governs structural integrity and labeling requirements for U.S. distribution. The EU's General Product Safety Directive and harmonized EN 747 standards govern European market access, with CE marking mandatory for cross-border sales. Stakeholders must monitor evolving flammability testing protocols and traceability requirements for engineered wood substrates, as regulatory divergence between jurisdictions reshapes sourcing and certification budgets.
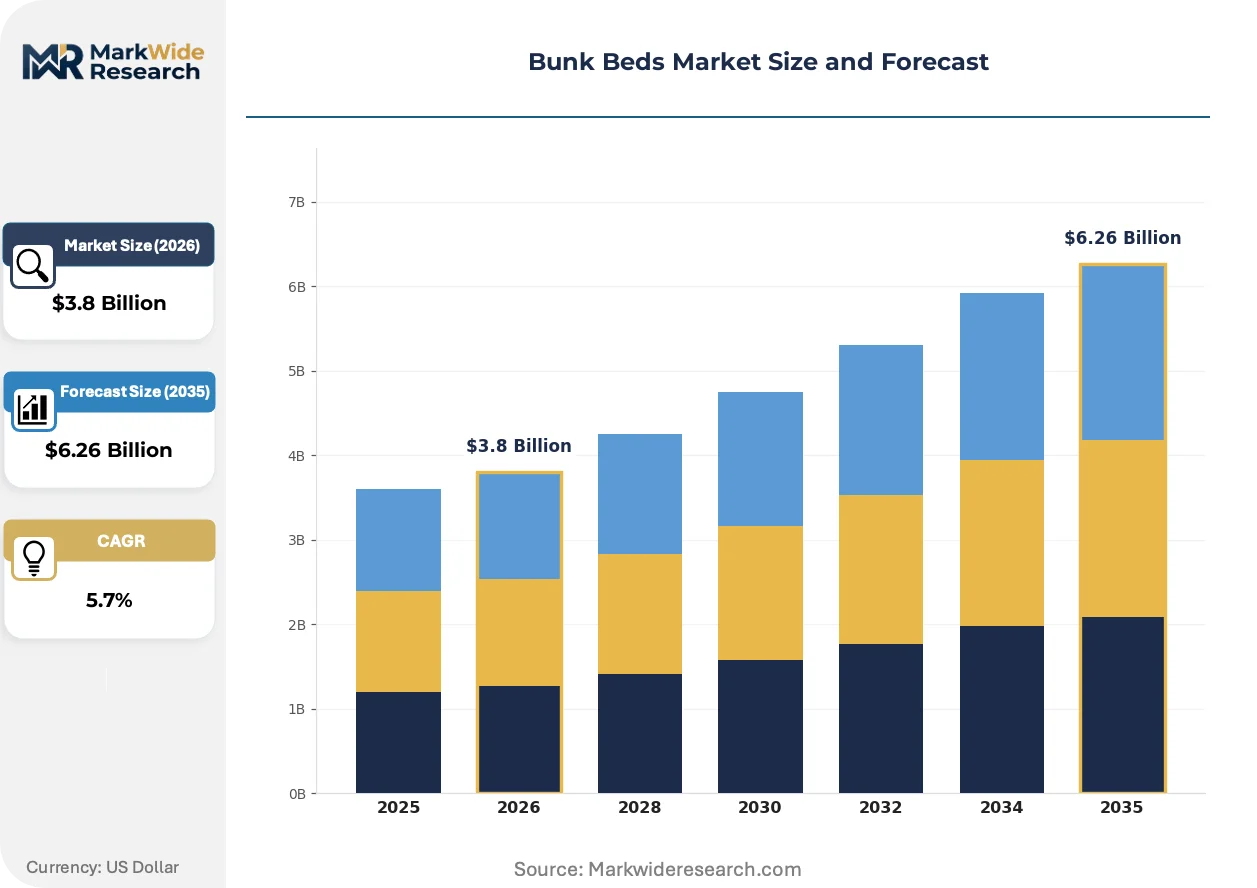
Market Dynamics
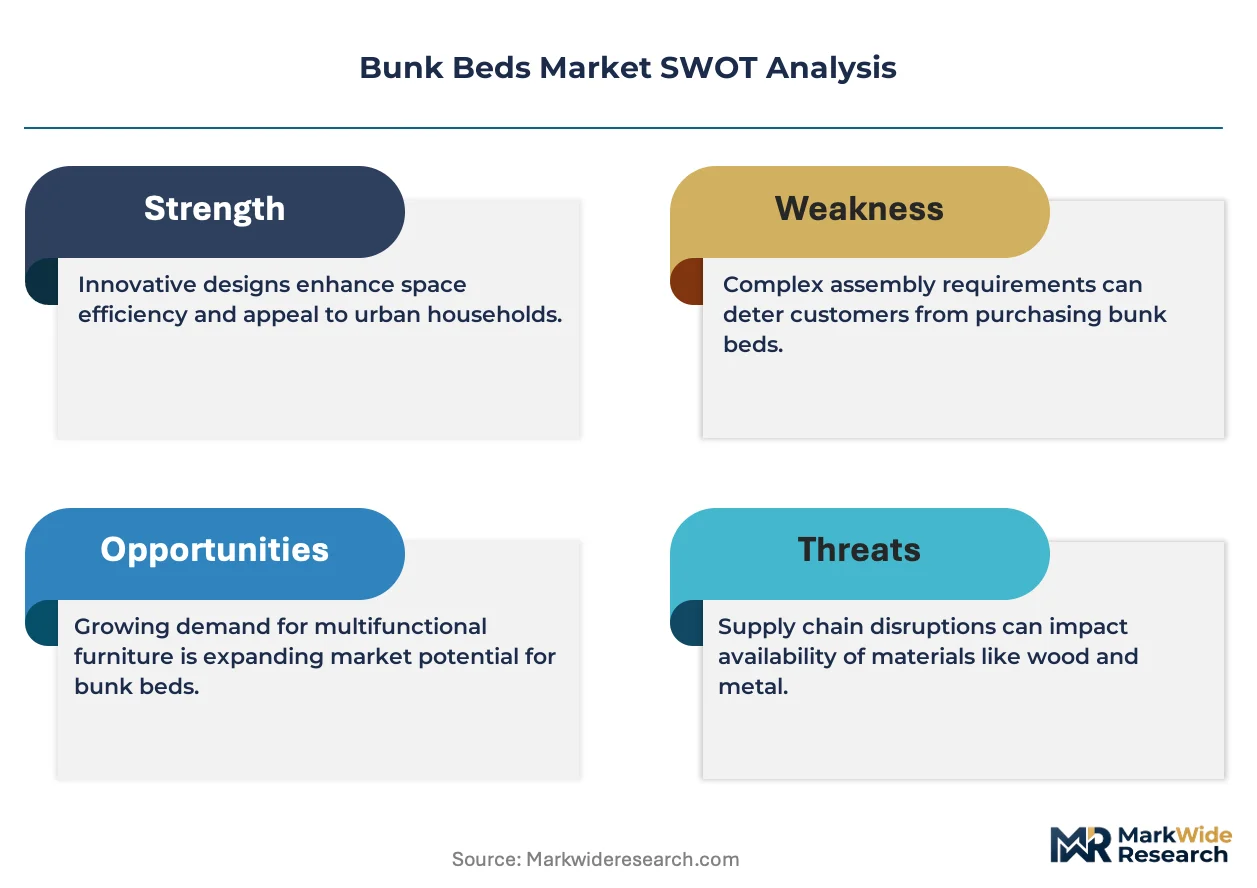
Hospitality procurement cycles are compressing as hostel and budget hotel operators in the United States accelerate renovation schedules, pulling forward replacement demand that previously stretched across decade-long intervals. This temporal compression is forcing manufacturers to reconfigure production planning and inventory buffers.
Growth Catalysts
- 16 CFR Part 1513 enforcement:The CPSC's entrapment and guardrail standards create compliance barriers that filter out low-quality imports, protecting certified domestic and export-oriented manufacturers who have invested in testing infrastructure.
- Solid-wood milling backward integration:Captive timber processing capabilities allow producers to control raw material quality and compress lead times when overseas supply chains face disruption.
- Summer camp and dormitory procurement:Institutional buyers with multi-unit annual contracts provide predictable volume anchors that smooth seasonal residential demand fluctuations.
Market Restraints
- Engineered wood substrate volatility:Resin and adhesive input costs fluctuate with petrochemical feedstock prices, squeezing margin on flat-pack e-commerce SKUs where shipping weight already constrains pricing flexibility.
- Furniture cluster concentration in China:Export-oriented manufacturing districts concentrate supply risk, with port congestion or trade policy shifts capable of disrupting North American and European retailer inventory pipelines.
- ASTM F1427 structural testing requirements:Third-party certification timelines extend product development cycles, delaying market entry for new designs and favoring incumbents with established laboratory relationships.
Strategic Opportunities
- Direct-to-consumer channel expansion:Bypassing traditional furniture retail markups allows manufacturers to capture value previously allocated to distributor networks, particularly for premium solid-wood configurations.
- Subscription-based mattress replacement programs:Service revenue streams extend customer lifetime value beyond the initial bunk bed transaction, creating recurring income from institutional and hospitality accounts.
- EU Green Deal circularity requirements:Anticipated extended producer responsibility frameworks favor designs with disassembly-friendly joinery and recyclable material specifications, rewarding early compliance investment.
Industry Challenges
- Flammability testing protocol divergence:Jurisdictional differences between US, EU, and emerging market fire safety standards force redundant certification expenditures and complicate single-SKU global distribution strategies.
- Traceability system implementation:Engineered wood substrate chain-of-custody documentation requirements demand ERP upgrades and supplier auditing capabilities that strain mid-tier manufacturer IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bunk Beds Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bunk Beds, Loft Bunk Beds, Futon Bunk Beds, Trundle Bunk Beds Material: Wood, Metal, Engineered Wood, Plywood End User: Residential, Commercial, Educational, Hospitality Design Style: Modern, Rustic, Industrial, Classic |
| Companies Covered | Woodcrest Manufacturing, AFI Furnishings, Max & Lily, DHP, Harper & Bright Designs, Clafbebe, American Bedding Manufacturers, Oeuf, Camaflexi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bunk Beds Market Evolving Landscape
Modular configuration systems are displacing fixed-frame designs across residential and institutional segments, enabling buyers to reconfigure sleeping capacity without complete replacement. This shift is compressing traditional product lifecycles and reshaping after-sales service expectations.
Cross-laminated timber construction is converging with CNC machining capabilities to produce loft bunk beds with integrated desks and storage modules. University housing operators are adopting these configurations at accelerated procurement cycles. The technology is converging with parametric design software to enable mass-customization at production costs approaching standard SKU economics.
REACH substance restrictions on formaldehyde emissions and flame retardants are forcing reformulation of engineered wood adhesives and surface treatments. Manufacturers serving European distribution channels must recertify product lines under harmonized EN 747 standards. Hospitality buyers with cross-border property portfolios are consolidating procurement around specifications that satisfy both EU and US testing protocols to simplify inventory management.
Buyer concentration among multi-property hospitality operators is consolidating vendor relationships and compressing negotiation cycles. Traditional furniture retail intermediaries are losing share to direct manufacturer contracts and specification-driven procurement teams. This pattern is most visible in United States hostel and budget hotel renovation programs, where procurement directors now centralize bunk bed purchasing across property portfolios exceeding fifty units.
Bunk Beds Market Segmentation
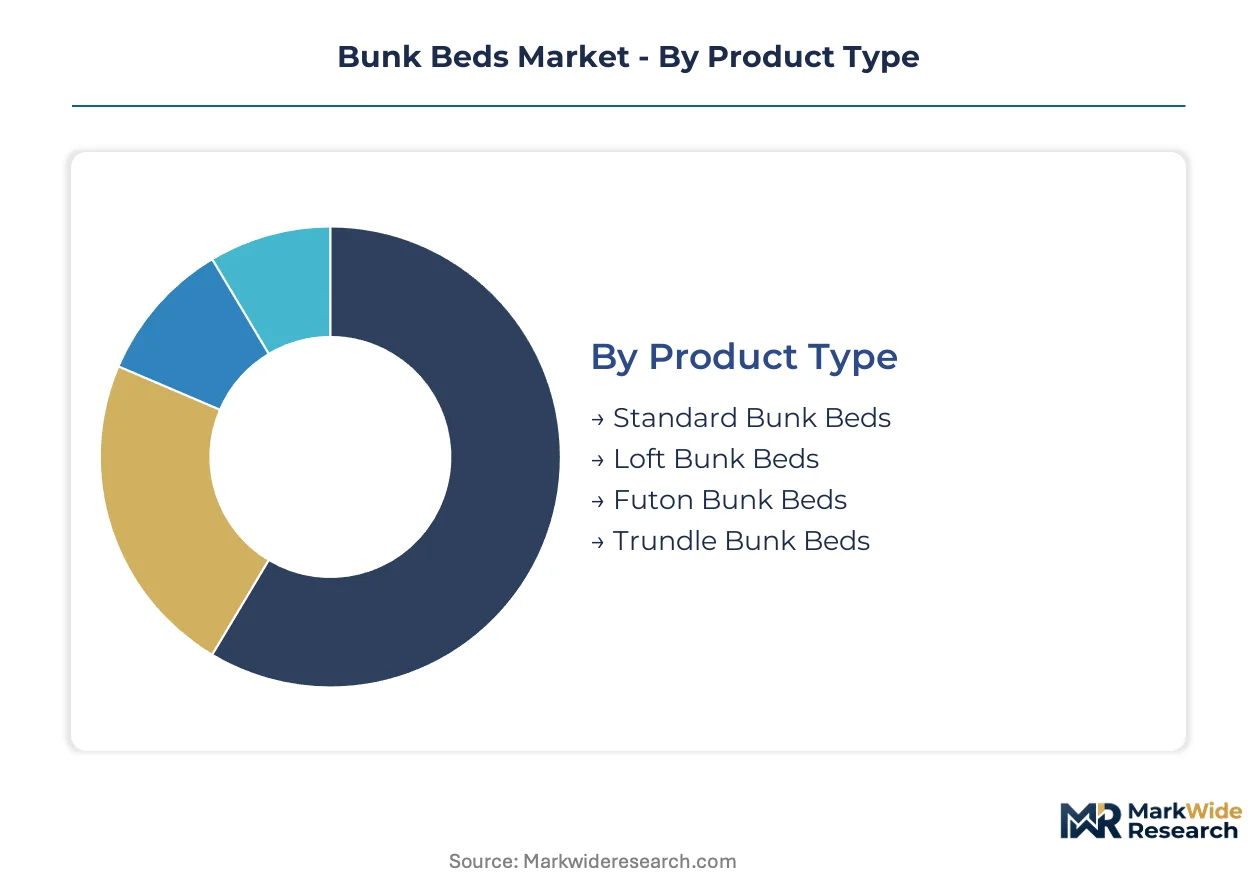
Segmentation in the bunk beds market reveals how manufacturing capabilities and regulatory compliance cluster around specific product configurations. Understanding these divisions helps stakeholders align procurement strategies with supply availability and certification requirements.
Product Type:
Supply concentration for bunk bed frames tilts heavily toward manufacturers with dedicated jigging and CNC routing capacity for repetitive post-and-rail construction.
- Standard Bunk Beds:Two-tier stacked frames with integrated ladders and guardrails dominate volume manufacturing. Hostel and budget hotel operators in the United States pull the majority of procurement for this configuration, with CPSC 16 CFR Part 1513 compliance filtering out uncertified imports.
- Loft Bunk Beds:Elevated sleeping platforms with open space beneath for desks, storage, or seating command premium positioning. University housing operators are accelerating adoption of these configurations as they maximize square footage efficiency in dormitory renovations.
- Futon Bunk Beds:Lower bunk convertible to seating combines sleeping and lounge functionality in compact footprints. Asian export manufacturers specialize in metal-frame variants for North American retail distribution.
- Trundle Bunk Beds:Pull-out third sleeping surface accommodates variable occupancy without permanent floor space commitment. Summer camp operators favor these for seasonal capacity flexibility.
Standard bunk beds absorb the bulk of installed capacity; loft bunk beds are expanding most quickly.
Material:
Raw material selection directly determines which manufacturing clusters can compete, with timber access and metalworking infrastructure defining regional supply bases.
- Wood:Solid hardwood construction targets premium residential and institutional buyers seeking durability and repairability. Woodcrest Manufacturing's captive milling operations in North America control quality and compress lead times for this tier.
- Metal:Tubular steel and aluminum frames dominate commercial and hospitality applications requiring fire resistance and sanitization compatibility. Chinese export clusters specialize in high-volume metal fabrication for cost-sensitive retail channels.
- Engineered Wood:Particleboard and MDF substrates enable flat-pack e-commerce fulfillment where shipping weight constrains pricing. REACH substance restrictions on formaldehyde emissions are forcing adhesive reformulation for European-bound inventory.
- Plywood:Cross-laminated timber construction converges with CNC machining for mid-tier loft configurations. This material bridges solid-wood durability with engineered-wood production efficiency.
Metal frames capture the highest shipment volumes; engineered wood is climbing the fastest as direct-to-consumer channels expand.
End User:
Procurement authority concentrates differently across end-user categories, with institutional buyers centralizing purchasing and residential buyers fragmenting across retail channels.
- Residential:Parents purchasing for children and young adults in shared housing drive demand for configurable, safety-certified designs. Direct-to-consumer brands like Max & Lily bypass traditional furniture retail markups in this segment.
- Commercial:Workplace nap pods and co-living operators represent emerging demand with specialized space constraints and duty-cycle requirements.
- Educational:University housing and boarding schools operate on predictable replacement cycles with multi-unit annual contracts. AFI Furnishings anchors market position through specialized dormitory procurement relationships.
- Hospitality:Hostel and budget hotel renovation programs are compressing procurement timelines across property portfolios exceeding fifty units. Buyer concentration is consolidating vendor relationships and squeezing negotiation leverage.
Residential purchases account for the greatest transaction frequency; hospitality procurement is gaining share fastest as renovation cycles accelerate.
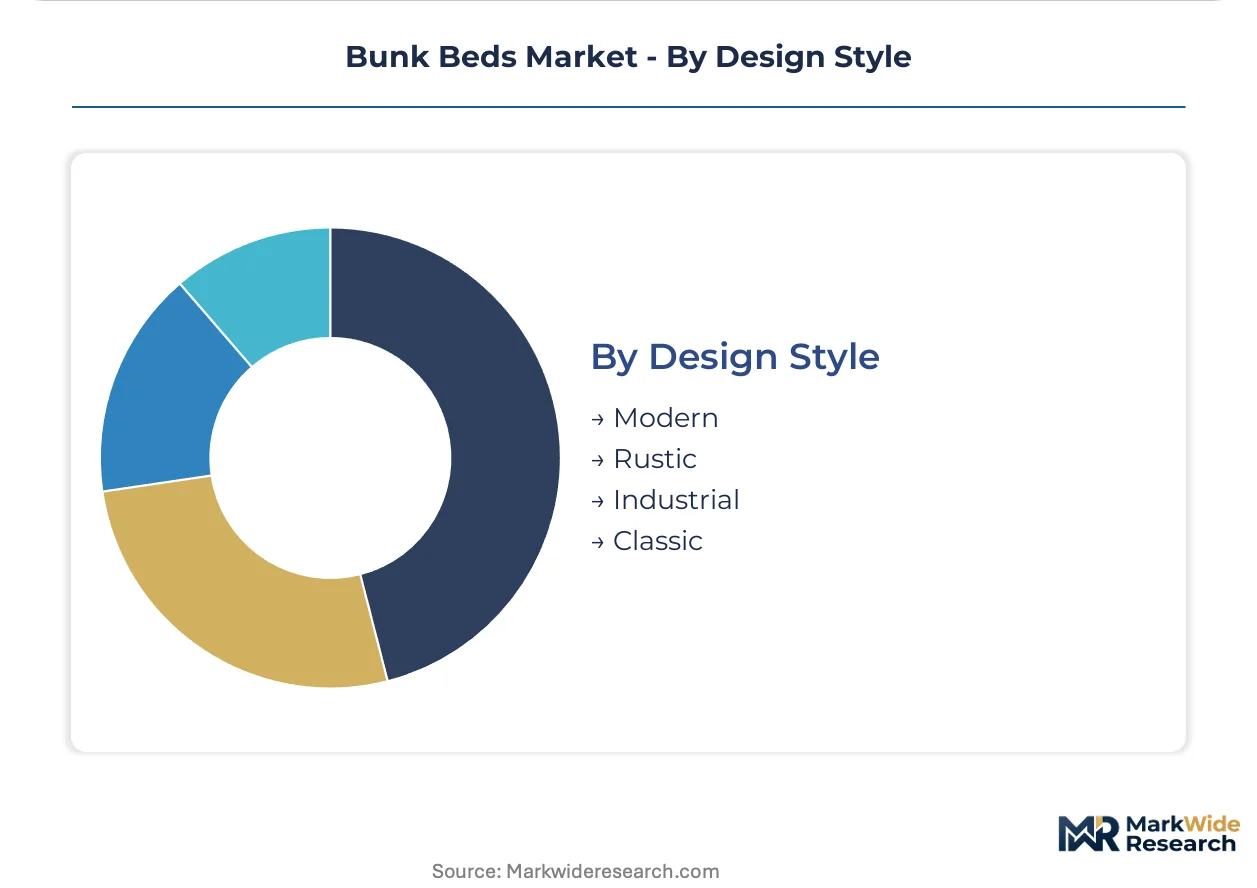
Design Style:
Aesthetic differentiation creates price tier separation without requiring fundamental structural redesign, allowing manufacturers to leverage common tooling across style variants.
- Modern:Clean lines, minimal ornamentation, and neutral finishes align with contemporary interior design trends in urban residential and co-living spaces. This style commands premium positioning in direct-to-consumer channels.
- Rustic:Distressed wood finishes and farmhouse-inspired hardware target suburban residential buyers seeking warmth and perceived craftsmanship. Regional furniture retailers favor this aesthetic for showroom differentiation.
- Industrial:Exposed metal frames, pipe fittings, and utilitarian aesthetics resonate with converted warehouse hospitality projects and urban loft residences.
- Classic:Traditional post-and-rail proportions with turned wood details persist in heritage boarding schools and traditional residential settings where longevity signals quality.
Modern styling dominates new product development investment; industrial design is expanding most quickly in hospitality retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China's export-oriented furniture districts while consumption concentrates across North American and European residential and hospitality markets. This geographic split creates supply chain exposure for retailers dependent on trans-Pacific shipping lanes. Regulatory divergence between jurisdictions forces redundant certification expenditures that reshape competitive positioning.
United States
Hostel and budget hotel renovation programs are accelerating procurement cycles across property portfolios exceeding fifty units. The Consumer Product Safety Commission enforces 16 CFR Part 1513 for entrapment hazards and guardrail spacing, filtering out uncertified imports. North Carolina's furniture manufacturing corridor hosts domestic producers serving institutional buyers with compressed lead time requirements.
China
Export-oriented furniture clusters in Guangdong and Zhejiang provinces supply mid-tier and premium inventory to North American and European retailers. The State Administration for Market Regulation oversees GB standards for domestic product safety while export production targets ASTM F1427 and EN 747 compliance. Dongguan's manufacturing district specializes in metal-frame fabrication for cost-sensitive hospitality applications.
Germany
University housing operators are adopting loft bunk bed configurations with integrated desks and storage modules at accelerated replacement cycles. The EU's General Product Safety Directive and harmonized EN 747 standards govern market access with CE marking mandatory for cross-border sales. North Rhine-Westphalia's timber processing region supplies cross-laminated timber components for mid-tier loft configurations.
United Kingdom
Co-living operators and workplace nap pod installations represent emerging demand with specialized space constraints. REACH substance restrictions on formaldehyde emissions force adhesive reformulation for engineered wood products bound for European distribution. Midlands furniture manufacturing centers focus on flat-pack e-commerce fulfillment where shipping weight determines pricing competitiveness.
India
Boarding school and budget hospitality procurement is expanding as institutional buyers centralize purchasing across multi-unit contracts. The Bureau of Indian Standards maintains safety specifications for domestic furniture production while export-oriented manufacturers target ASTM compliance for North American markets. Gujarat's engineered wood processing clusters supply particleboard and MDF substrates for cost-optimized product lines.
Bunk Beds Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where captive timber milling operations face off against outsourced fabrication networks. The vendor base splits between vertically integrated specialists controlling raw material quality and digital-native brands bypassing traditional retail intermediaries. Three archetypes dominate: solid-wood millers with backward integration into timber supply, hospitality contract specialists anchoring institutional procurement relationships, and direct-to-consumer operators capturing retail margin through owned channels. Competitive moves center on capacity expansion in cross-laminated timber machining and strategic partnerships with hospitality property managers seeking portfolio-wide specification consolidation.
Within the solid-wood milling tier, Woodcrest Manufacturing exemplifies captive timber processing capabilities that compress lead times when overseas supply chains face disruption. Among hospitality contract specialists, AFI Furnishings occupies a position representing multi-unit annual relationships with summer camp and dormitory operators. On the direct-to-consumer vector, Max & Lily sits within the asset-light archetype bypassing traditional furniture retail markups through owned digital channels.
| Leading Market Players |
|---|
| Woodcrest Manufacturing |
| AFI Furnishings |
| Max & Lily |
| DHP |
| Harper & Bright Designs |
| Clafbebe |
| American Bedding Manufacturers |
| Oeuf |
| Camaflexi |
| Others |
Value Network & Pricing Analysis
Lumber futures volatility and engineered wood resin costs cascade through bunk bed manufacturing into three distinct pricing tiers, with solid-wood configurations absorbing premium positioning while flat-pack SKUs compete on shipping-weight economics.
Pricing Analysis
Margin tightening in engineered wood flat-pack tiers reflects petrochemical feedstock cost swings that constrain pricing flexibility where dimensional weight already caps margins. Three-tier pricing structure across premium solid-wood, mid-market plywood, and economy metal frames separates buyers by durability expectations and certification grade. Cost-down pressure on hospitality contract volumes accelerates as procurement directors consolidate portfolio-wide purchasing across fifty-plus unit property networks. Residential direct-to-consumer buyers show lowest price sensitivity, prioritizing safety certification and configurable joinery over per-unit cost.
Supply Chain Analysis
Direct-to-retail channels handle North American big-box fulfillment while hospitality contract manufacturers ship direct to property renovation sites. Production gravity centers on Guangdong and Zhejiang provinces in China, with secondary clusters in North Carolina and North Rhine-Westphalia. Raw material flows draw from Appalachian hardwoods, Nordic softwoods, and Malaysian rubberwood plantations. Single-source vulnerability concentrates in Chinese port infrastructure, where congestion or policy shifts disrupt trans-Pacific inventory pipelines for seasonal procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where CPSC 16 CFR Part 1513 certification infrastructure creates a barrier-to-entry moat protecting tested domestic and export-oriented manufacturers from uncertified import competition.
For Market Incumbents: Hedge against resin cost volatility through captive timber milling or long-term adhesive supply agreements. Expand cross-laminated timber machining capacity to capture university housing loft bed demand. Defend hospitality contract relationships by embedding after-sales service teams within property management portfolios. For New Entrants and Emerging Players: Enter via direct-to-consumer channels where traditional furniture retail markups leave margin headroom for digital-native brands. Target co-living and workplace nap pod installations as underpenetrated commercial segments with specialized space constraints. Lead with parametric design capabilities enabling mass-customization at standard SKU economics. For Investors and Strategic Acquirers: Distressed-cycle entries favor solid-wood millers with backward integration into timber supply in North American manufacturing corridors. Five-to-ten year viability hinges on compliance infrastructure amortization across multi-jurisdiction certification portfolios. Monitor REACH substance restriction expansion and EU Green Deal circularity timelines as inflection indicators for adhesive reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive milling operations compress lead times when overseas supply chains face disruption. |
| Cross-Laminated Timber Capacity Expansion | CNC machining convergence enables loft configurations for university housing procurement cycles. |
| Direct-to-Consumer Channel Launch | Owned digital channels bypass traditional furniture retail markups in residential segments. |
| Subscription-Based Service Program | Recurring mattress replacement revenue extends customer lifetime value beyond initial transactions. |
| Multi-Jurisdiction Certification Investment | Dual CPSC and EN 747 compliance opens hospitality procurement across US and EU property portfolios. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with furniture manufacturing executives, hospitality procurement directors, dormitory facility managers, and retail category buyers provided operational validation. Bottom-up shipment analysis triangulated against top-down consumption estimates from residential construction permits and institutional renovation budgets.
Segment-level modeling tracked product type, material grade, end-user category, and design style across the projection horizon. CAGRs derived from historical shipment trajectories adjusted for regulatory enforcement intensity and channel migration patterns. Cross-laminated timber adoption curves and hospitality renovation cycle compression served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under trade policy shifts or REACH substance restriction acceleration. Practitioners should monitor port congestion indices and flammability testing protocol divergence for early signals of supply disruption or certification cost inflation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Global Mattress Market
Bedroom Furniture
US Wall Beds Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Children Mattress Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Bed Wedge Market