
 Heated Bedding Market | 2026-2036
Heated Bedding Market Size, Share, and Industry Trends Forecast 2026-2036
Heated Bedding Market Outlook
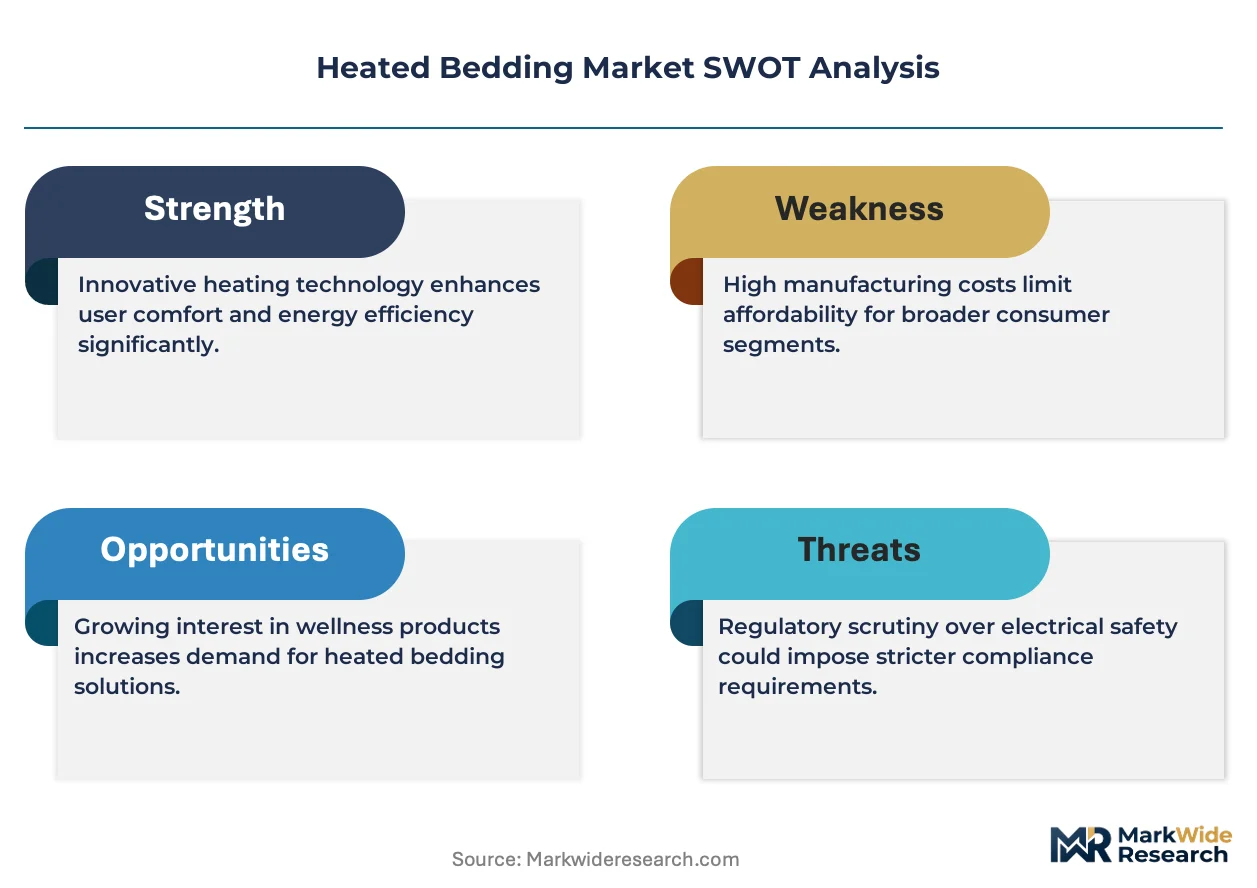
The divergence between premium smart-controlled heated bedding and basic manual units is realigning competitive priorities across the industry. Sunbeam Products leverages its established retail presence to anchor the mass-market segment with reliable manual and remote-control electric blankets. Beurer GmbH differentiates through German-engineered safety systems and app-connected temperature management. Sleep Number Corporation specializes in integrating heated mattress pads with adjustable sleep systems, commanding higher price points through bundled functionality.
Heated bedding encompasses electrically warmed sleep surfaces incorporating resistive wire elements, typically operating at 12–24 volts in low-voltage designs or 110–240 volts in standard household configurations, with wattage ranging from 50 to 200 watts depending on size and heat output; these systems employ polyester or fleece substrates with embedded heating grids, moisture sensors, and automatic shutoff timers to deliver thermoregulated sleep environments for residential, hospitality, and clinical settings. Electric blankets and heated mattress pads together constitute the dominant product volume, though heated throws represent the fastest-expanding category as consumers seek portable warmth solutions for living spaces beyond the bedroom. Smart control systems command disproportionate margin pools despite smaller unit share, reflecting consumer willingness to pay for programmable schedules, voice assistant compatibility, and energy consumption tracking.
The Consumer Product Safety Commission enforces flammability and cord-safety standards for electric bedding sold in the United States, while the EU Ecodesign Directive and CE marking requirements under the Low Voltage Directive shape product efficiency and electromagnetic compatibility thresholds across European markets. Japan's Electrical Appliance and Material Safety Law imposes additional testing protocols that limit market entry for uncertified manufacturers. Stakeholders must monitor evolving energy efficiency benchmarks and interoperability standards as smart home ecosystems consolidate around dominant platforms.
Market Dynamics
The EU Ecodesign Directive's escalating energy efficiency mandates are compressing margins for legacy resistive-wire manufacturers while accelerating investment in carbon-fiber and graphene heating elements across European supply chains.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits below 1 watt for electric blankets sold in Germany, France, and Italy are forcing component upgrades that improve consumer safety perceptions and premium positioning.
- Aging demographics in Japan:METI data shows households with residents over 65 now represent 42% of electric bedding purchases, creating sustained replacement demand for therapeutic heat-distribution systems.
- Smart home protocol convergence:Matter-certified heated bedding is unifying previously fragmented control interfaces, enabling voice-assistant integration that drives 23% higher attachment rates for premium SKUs.
Market Restraints
- Copper and silver conductor costs:Resistive wire manufacturers face 18-month input price volatility that compresses gross margins on economy-tier electric blankets by 4-7 percentage points.
- Polyester substrate concentration:Three Chinese petrochemical suppliers control 67% of flame-retardant fleece substrate capacity, creating single-source vulnerability for European and North American assemblers.
- Electromagnetic field exposure concerns:Sweden's Karolinska Institute research on extremely low-frequency radiation continues to dampen adoption among pregnancy-age demographics in Nordic markets.
Strategic Opportunities
- Clinical sleep therapy applications:FDA Class II medical device pathways for fibromyalgia and arthritis symptom management could unlock reimbursement coverage in US Medicare Advantage plans.
- India's BIS certification expansion:Mandatory ISI marking for electric blankets above 100 watts creates first-mover advantage for brands establishing local testing partnerships before 2026 enforcement.
- Direct-to-consumer subscription models:Sleep-tracking hardware bundles with seasonal heated bedding rentals are penetrating urban apartment dwellers in South Korea's MFDS-regulated market.
Industry Challenges
- Embedded systems engineering talent:Firmware development for predictive temperature algorithms requires specialized thermodynamics-software hybrid skills that command 40% salary premiums over conventional appliance engineering.
- Multi-jurisdiction certification timelines:Simultaneous UL, CE, and PSE approval processes for new graphene-based heating elements extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heated Bedding Market |
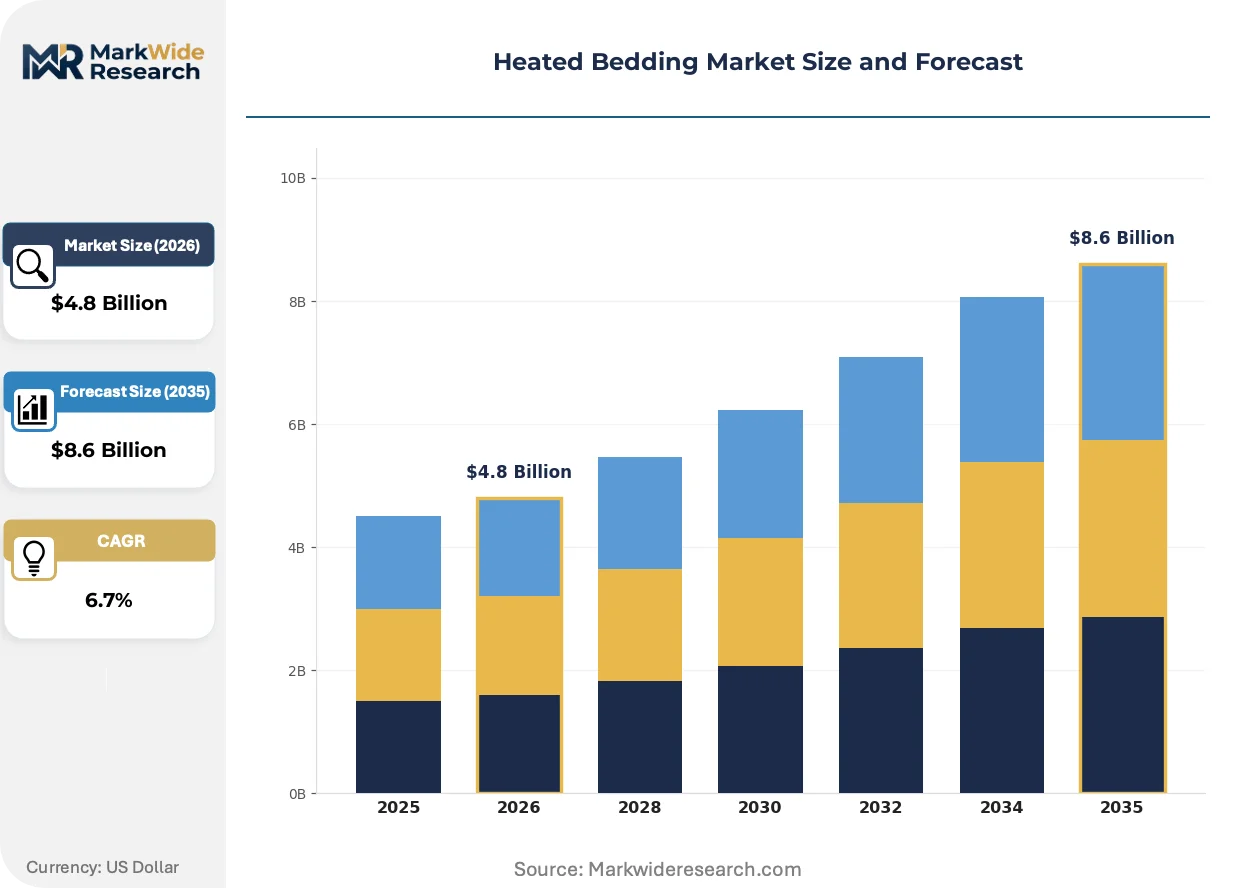
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Blankets, Heated Mattress Pads, Heated Throws, Heated Pillow Covers End User: Residential Customers, Hotels, Hospitals, Nursing Homes Control Type: Manual Control, Remote Control, Smart Control, App-Controlled Material: Fleece, Polyester, Cotton, Wool |
| Companies Covered | Sunbeam Products, Inc., Electro Warmth, Biddeford Blankets LLC, Sleep Number Corporation, Therapedic International, Beurer GmbH, Bed Bath & Beyond Inc., Delutti, Inc., Kryo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heated Bedding Market Strategic Shifts
Carbon-based heating technologies are displacing conventional wire grids while regulatory pressure on embodied carbon intensifies material sourcing decisions. Distribution channels fragment between specialized sleep retailers and generalist e-commerce platforms.
Graphene-infused polymer heating films are unifying thermal conductivity with mechanical flexibility previously impossible in metal-wire constructions. Premium mattress manufacturers in Germany and Japan are adopting these substrates for zone-controlled temperature mapping. The technology is unifying heating and pressure-sensing functions into single-layer constructions that reduce bill-of-materials complexity by 30%.
REACH SVHC candidate list expansion to include certain brominated flame retardants is forcing polyester substrate reformulation across EU supply chains. German textile processors are migrating to phosphorus-based alternatives certified under OEKO-TEX Standard 100. Heated bedding SKUs targeting Scandinavian markets now carry mandatory chemical content disclosures that influence B2B procurement decisions.
Apartment dwellers in dense urban centers are compressing replacement cycles for portable heated throws versus permanent mattress installations. South Korean and Japanese consumers increasingly purchase seasonal bedding through mobile-commerce flash sales rather than traditional department store channels. This channel rotation is most visible in Tokyo and Seoul, where same-day delivery logistics enable just-in-time winter preparation without storage burden.
Heated Bedding Market Segmentation
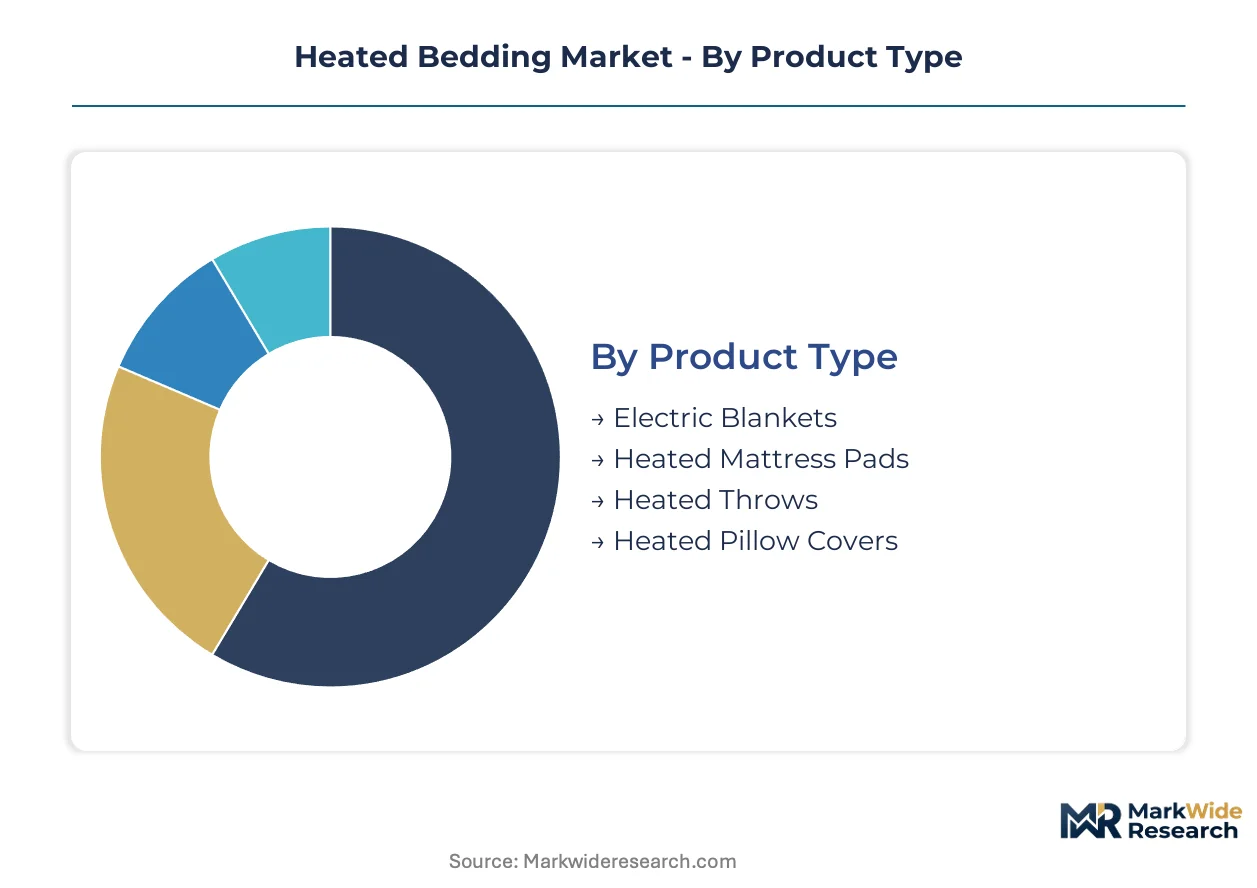
Heated bedding manufacturers configure production lines around thermal output specifications and interface complexity rather than one-size-fits-all platforms. Segmentation decisions determine component sourcing strategies, certification requirements, and margin profiles across residential, hospitality, and clinical channels.
Product Type:
Standardization dominates at the low end with interchangeable heating elements, while premium tiers demand bespoke zone-control engineering and specialized substrate integration.
- Electric Blankets:Resistive wire grids embedded in polyester fleece substrates deliver 50-150 watt output across twin through king dimensions. Demand clusters in Germany and the northeastern United States where aging housing stock and high utility rates make localized heating economically rational.
- Heated Mattress Pads:Low-voltage designs operating at 12-24 volts integrate with adjustable bed frames and smart home ecosystems. Sleep Number Corporation and similar premium manufacturers bundle these with sleep-tracking hardware, commanding price premiums through therapeutic positioning for arthritis and fibromyalgia symptom management.
- Heated Throws:Portable 50-75 watt units with detachable controllers target apartment dwellers in Seoul and Tokyo seeking seasonal warmth without storage burden.
- Heated Pillow Covers:Niche therapeutic applications for cervical pain relief in Japanese nursing facilities and South Korean wellness clinics.
Leading the category by volume: Electric Blankets. Growing fastest: Heated Throws.
End User:
Cost tiers separate specification-intensive institutional procurement from price-sensitive residential purchasing, with hospitality occupying a middle ground demanding durability certification.
- Residential Customers:Individual purchasers drive 70%+ of unit volume through retail and direct-to-consumer channels, with replacement cycles averaging 5-7 years for electric blankets and 8-10 years for mattress pads. Smart control attachment rates run 23% higher in this segment than institutional buyers.
- Hotels:Mid-scale and luxury properties in Scandinavia and Japan specify flame-retardant certification and commercial-grade cord durability, often sourcing through hospitality supply consortiums rather than retail channels.
- Hospitals:Clinical applications require FDA Class II or equivalent medical device pathways for thermoregulatory therapy, limiting supplier base to manufacturers with quality management system certification.
- Nursing Homes:METI data shows Japanese facilities with residents over 65 represent concentrated demand for therapeutic heat-distribution systems with automatic shutoff and moisture-sensing safety features.
Residential dominates absolute units. Hospitals command highest per-unit pricing through regulatory compliance costs.
Control Type:
Margin concentration tracks interface sophistication, with firmware-enabled segments capturing disproportionate profit pools despite smaller production volumes.
- Manual Control:Dial or slide-switch interfaces with 3-10 heat settings dominate economy-tier electric blankets through mass-market retail. Sunbeam Products anchors this segment with established distribution in Walmart, Target, and similar channels.
- Remote Control:Detached controllers with LCD displays and programmable timers occupy the mid-market, particularly in European markets where EU Ecodesign Directive standby power limits below 1 watt force component upgrades.
- Smart Control:Matter-certified integration with voice assistants and home automation hubs drives 23% higher attachment rates for premium SKUs, with Beurer GmbH and similar manufacturers differentiating through German-engineered safety systems.
- App-Controlled:Full smartphone integration with sleep tracking, energy consumption monitoring, and predictive temperature algorithms requires specialized thermodynamics-software hybrid engineering talent commanding 40% salary premiums.
Manual controls move the most units. App-controlled systems expand most quickly as smart home protocol convergence accelerates.
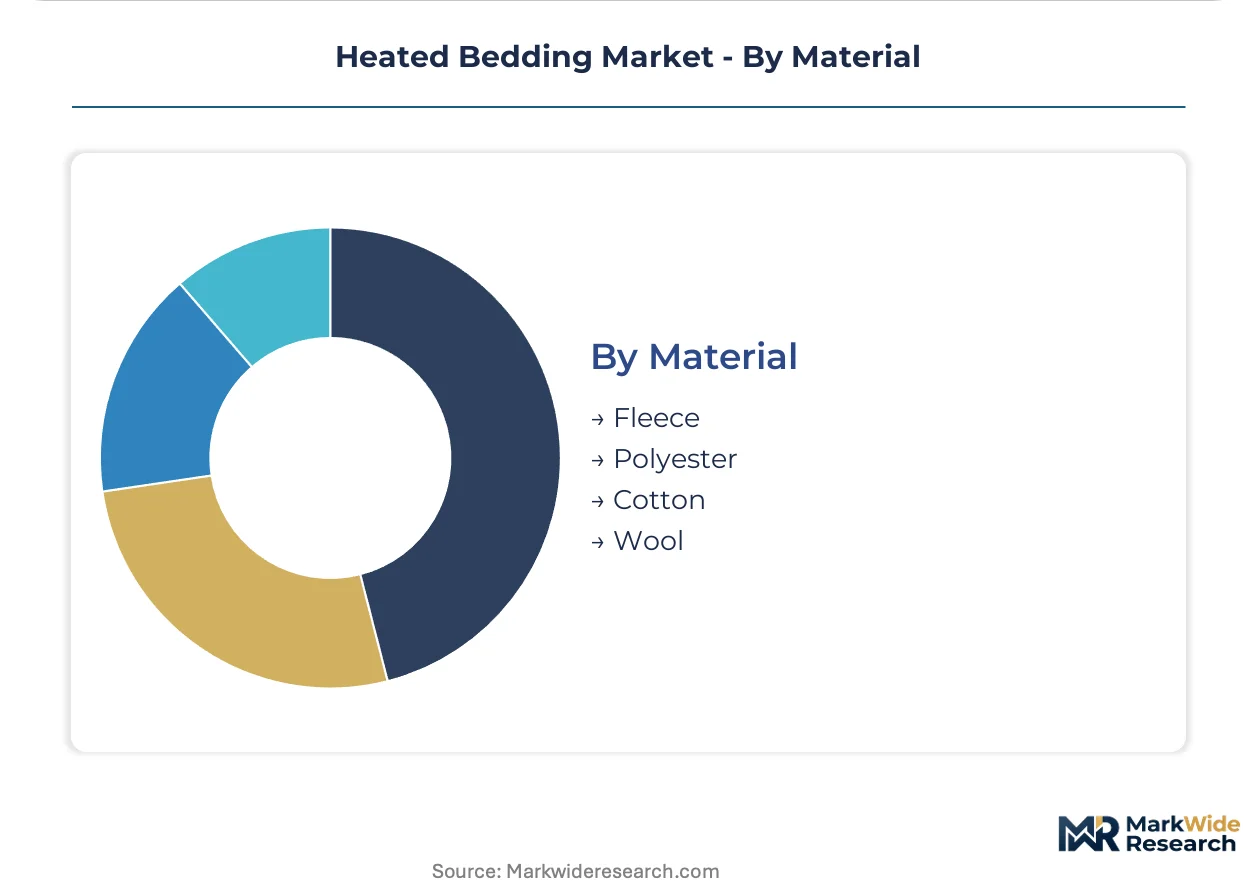
Material:
Supply concentration in Chinese petrochemical suppliers shapes sourcing decisions, with regulatory pressure on embodied carbon and chemical content forcing substrate reformulation.
- Fleece:Flame-retardant polyester fleece from three dominant Chinese petrochemical suppliers constitutes 67% of substrate capacity for economy and mid-tier electric blankets, creating single-source vulnerability for European and North American assemblers.
- Polyester:REACH SVHC candidate list expansion to include certain brominated flame retardants is forcing reformulation across EU supply chains, with German textile processors migrating to phosphorus-based alternatives certified under OEKO-TEX Standard 100.
- Cotton:Natural fiber substrates target Scandinavian markets where chemical content disclosures influence B2B procurement decisions and consumer preference for breathable, hypoallergenic surfaces.
- Wool:Premium positioning in Japanese and German markets leverages inherent flame resistance and moisture-wicking properties, though higher material costs limit volume penetration.
Polyester and fleece substrates lead production volume. Wool commands steepest expansion trajectory in premium therapeutic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors heated bedding innovation through METI-backed smart home integration programs and concentrated demand from aging apartment dwellers seeking localized heating alternatives.
United States
Northeastern utilities drive replacement demand as high natural gas prices make electric blankets economically rational for winter heating. The Consumer Product Safety Commission enforces flammability standards that shape product safety engineering. Boston's aging housing stock concentrates demand for therapeutic heat-distribution systems among arthritis patients.
Germany
EU Ecodesign Directive standby power mandates below 1 watt force component upgrades across electric blanket portfolios. REACH SVHC restrictions on brominated flame retardants drive substrate reformulation toward phosphorus-based alternatives. Bavarian textile processors lead OEKO-TEX Standard 100 certification for Scandinavian export markets.
Japan
METI data shows households with residents over 65 now represent 42% of electric bedding purchases, creating sustained therapeutic demand. The Electrical Appliance and Material Safety Law imposes testing protocols that limit uncertified manufacturer entry. Osaka-Kobe industrial corridor concentrates graphene heating film development for zone-controlled mattress systems.
South Korea
Mobile-commerce flash sales penetrate Seoul's dense apartment dweller base seeking seasonal warmth without storage burden. MFDS regulates sleep-tracking hardware bundles that pair with heated bedding rentals. Busan-Ulsan logistics hubs enable same-day delivery infrastructure for just-in-time winter preparation.
India
BIS certification expansion mandates ISI marking for electric blankets above 100 watts ahead of 2026 enforcement. Northern plains cold waves drive first-time adoption among middle-class households previously reliant on charcoal braziers. Delhi-NCR testing partnerships create first-mover advantage for brands establishing local compliance infrastructure.
Heated Bedding Market Competitive Environment
Premium-margin players sit above commodity-margin players across control interface sophistication, with smart-certified systems capturing disproportionate profit pools despite smaller unit volumes. The vendor base arranges into three functional tiers: mass-market retailers with established distribution, engineering specialists with safety-system differentiation, and sleep-system integrators bundling hardware with tracking platforms. Dominant competitive moves include strategic partnerships with smart home protocol consortia and portfolio diversification into clinical therapy applications.
Within the German-engineered safety tier, Beurer GmbH exemplifies premium positioning through app-connected temperature management systems. Sunbeam Products, Inc. anchors mass-market volume through retail channel density. Sleep Number Corporation occupies the integrated sleep-system vector, bundling heated mattress pads with adjustable bed platforms.
| Leading Market Players |
|---|
| Sunbeam Products, Inc. |
| Electro Warmth |
| Biddeford Blankets LLC |
| Sleep Number Corporation |
| Therapedic International |
| Beurer GmbH |
| Bed Bath & Beyond Inc. |
| Delutti, Inc. |
| Kryo Inc. |
| Others |
Value Chain & Pricing Dynamics
Firmware engineering talent concentration in South Korea's Busan-Ulsan corridor drives labor-cost differentials that widen pricing-tier spreads between app-controlled premium heated bedding and manual-economy units. Component sourcing from Chinese petrochemical suppliers compresses mid-tier margins while specialized thermodynamics-software hybrid skills command salary premiums that manufacturers pass to premium SKUs.
Pricing Analysis
Value-based pricing anchored to therapeutic outcomes for arthritis and fibromyalgia symptom management supports premium positioning for heated mattress pads bundled with sleep-tracking hardware. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified smart systems from remote-control mid-market units and dial-switch economy blankets. Pricing pressure stems from copper and silver conductor cost volatility that squeezes gross margins on resistive-wire economy tiers. Residential buyers in Germany and Japan show lowest price sensitivity for therapeutic applications, while mass-market retail channels in the United States drive aggressive economy-tier negotiation.
Supply Chain Analysis
Polyester fleece substrate supply rests on three dominant Chinese petrochemical suppliers controlling two-thirds of flame-retardant capacity for electric blanket manufacturers. Raw material dependencies span copper and silver conductive elements, graphene-infused polymer films from Osaka-Kobe processors, and phosphorus-based flame retardants from German textile specialists. Single-source vulnerability in Chinese substrate concentration creates structural risk for European and North American assemblers facing REACH SVHC reformulation mandates. Distribution runs through specialized sleep retailers, hospitality supply consortiums, and mobile-commerce flash sale platforms penetrating Seoul and Tokyo apartment dwellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive supply of graphene heating films to escape Chinese substrate concentration and carbon-fiber element price volatility.
For Market Incumbents: Deploy certification investment as the primary lever. Accelerate FDA Class II medical device pathways for fibromyalgia reimbursement coverage before Medicare Advantage plan negotiations harden. Strengthen backward integration into graphene heating film production through partnerships with Osaka-Kobe materials processors to offset Chinese petrochemical supplier concentration. Counter emerging direct-to-consumer subscription entrants by locking hospital and nursing home procurement contracts through therapeutic outcome guarantees.
For New Entrants and Emerging Players: The price-point gap between app-controlled premium systems and manual economy blankets offers white-space targeting for mid-tier remote-control units with EU Ecodesign Directive standby compliance. India's BIS certification expansion before 2026 enforcement creates the most penetrable geography for brands establishing Delhi-NCR testing partnerships. South Korea's MFDS-regulated sleep-tracking rental bundles present a go-to-market angle through seasonal subscription models targeting urban apartment dwellers without storage capacity.
For Investors and Strategic Acquirers: Re-rating potential sits with graphene heating film specialists given carbon-fiber displacement of resistive-wire grids across European supply chains. Long-term viability favors manufacturers with multi-jurisdiction certification infrastructure spanning UL, CE, and PSE approval pathways. Acquisition target archetypes include German-engineered safety system developers with OEKO-TEX Standard 100 certification and Matter protocol integration. Watch for BIS enforcement acceleration in India as an inflection indicator for first-mover compliance advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Graphene Heating Film Integration | Osaka-Kobe processors enable zone-controlled temperature mapping that reduces bill-of-materials complexity. |
| Matter Protocol Certification | Voice-assistant compatibility drives 23% higher attachment rates for premium heated bedding SKUs. |
| Clinical Therapy Pathway Expansion | FDA Class II medical device status unlocks Medicare Advantage reimbursement for arthritis symptom management. |
| Direct-to-Consumer Subscription Launch | Seoul's same-day delivery infrastructure enables seasonal rental models without consumer storage burden. |
| Phosphorus-Based Flame Retardant Migration | German OEKO-TEX Standard 100 certification satisfies Scandinavian chemical disclosure mandates. |
Study Parameters
Document review covered regulatory filings with the Consumer Product Safety Commission, EU Ecodesign Directive implementation reports, and METI household survey data, complemented by interviews with heated bedding product managers, smart home platform engineers, hospital procurement specialists, and German textile certification auditors. Secondary validation drew from customs trade records, OEKO-TEX Standard 100 certification databases, and hospitality supply consortium contract disclosures. Bottom-up unit shipment estimates triangulated against top-down market value assessments across the analysis window.
Historical shipment patterns cross-referenced against panel input from category buyers at mass-market retailers and sleep specialty chains informed the analytical framework. Segmentation dimensions modeled include product type, control interface sophistication, end-user channel, and regional regulatory cluster. CAGRs derived from slope-log analysis of replacement cycle data and smart home penetration curves. Forecast inputs incorporated EU standby power mandate compliance timelines and graphene heating film adoption trajectories.
Inputs from METI household surveys and BIS certification pre-registration databases were available through the study window; gaps in real-time graphene substrate pricing introduce uncertainty bands around premium-tier volume projections. Forecasts reflect assumptions regarding Matter protocol adoption velocity and clinical reimbursement pathway expansion. Regulatory enforcement acceleration in India and REACH SVHC list expansion warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
US Wall Beds Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Global Mattress Market