
 Japan Mattress Market | 2026-2036
Japan Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Mattress Market Foresight
Japan's domestic manufacturing base around Osaka and Nagoya is rewriting supply reliability for mattress producers serving premium residential buyers. Nishikawa Co., Ltd. leverages its century-old textile heritage to sustain quality positioning in high-end innerspring lines. France Bed Holdings Co., Ltd. anchors the healthcare segment through specialized hospital bed systems. Airweave Inc. differentiates via proprietary fiber technology targeting athletic recovery and temperature-sensitive sleepers.
A mattress is a sleep support system engineered with specified core densities, foam indentation load deflection ratings, or coil gauge configurations to distribute body weight and maintain spinal alignment during rest. Manufacturing involves layered assembly of comfort materials over structural cores, with quilting and edge reinforcement determining durability and performance. Innerspring remains the dominant product type in Japan due to consumer familiarity and established domestic supply chains, though hybrid constructions combining foam layers with pocketed coils capture the fastest growth as buyers seek pressure relief without sacrificing support. The hospitality end user segment commands premium average selling prices as hotel operators specify flame-retardant certifications and extended warranty terms.
METI enforces product safety standards under the Consumer Product Safety Act, while the JIS S 1102 standard governs mattress flammability and dimensional tolerances for domestic sale. The Fire Service Act mandates specific combustion performance for materials used in commercial lodging facilities, directly shaping procurement specifications for hospitality buyers. Stakeholders must monitor evolving chemical substance restrictions under Japan's implementation of the Stockholm Convention, which will determine foam formulation choices and supplier qualification requirements.
Market Dynamics
METI's circular economy mandates are forcing foam recyclers and mattress manufacturers to reconfigure supply chains around certified recycled content quotas, compressing legacy petroleum-based polyurethane feedstock demand.
Growth Catalysts
- Inbound tourism recovery:Hospitality procurement in Osaka and Tokyo is accelerating as international visitor volumes rebound, driving flame-retardant certified mattress orders for hotel renovations.
- JIS S 1102 compliance:Stricter domestic flammability standards are filtering out uncertified imports, protecting market share for compliant domestic producers.
- Hybrid construction adoption:Pocketed coil-plus-foam designs are capturing buyer preference shifts toward pressure relief without sacrificing traditional support feel.
Market Restraints
- Petrochemical input volatility:Polyether polyol and TDI pricing swings compress margin predictability for foam-dependent producers in the Kansai manufacturing belt.
- Osaka-Nagoya supply concentration:Domestic coil spring and textile sourcing clusters in central Japan create geographic vulnerability to logistics disruptions or seismic events.
- Stockholm Convention chemical restrictions:Evolving persistent organic pollutant controls limit legacy flame retardant formulations, forcing costly reformulation cycles.
Strategic Opportunities
- Athletic recovery positioning:Fiber-based sleep surfaces targeting professional sports teams and fitness-conscious consumers command premium pricing with minimal foam regulatory exposure.
- Healthcare facility upgrade cycles:Aging hospital infrastructure in prefectures outside Tokyo creates demand for specialized pressure-relief bed systems.
- Direct-to-residential digital channels:Online mattress-in-a-box models bypass traditional furniture retailer markups, capturing younger demographic trial in Greater Tokyo.
Industry Challenges
- Circular economy certification timelines:METI's recycled content verification protocols require 12-18 month supplier qualification cycles, delaying product launches.
- Fire Service Act commercial lodging compliance:Multi-property hospitality operators face fragmented prefectural enforcement interpretations, complicating nationwide rollout standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Mattress Market |
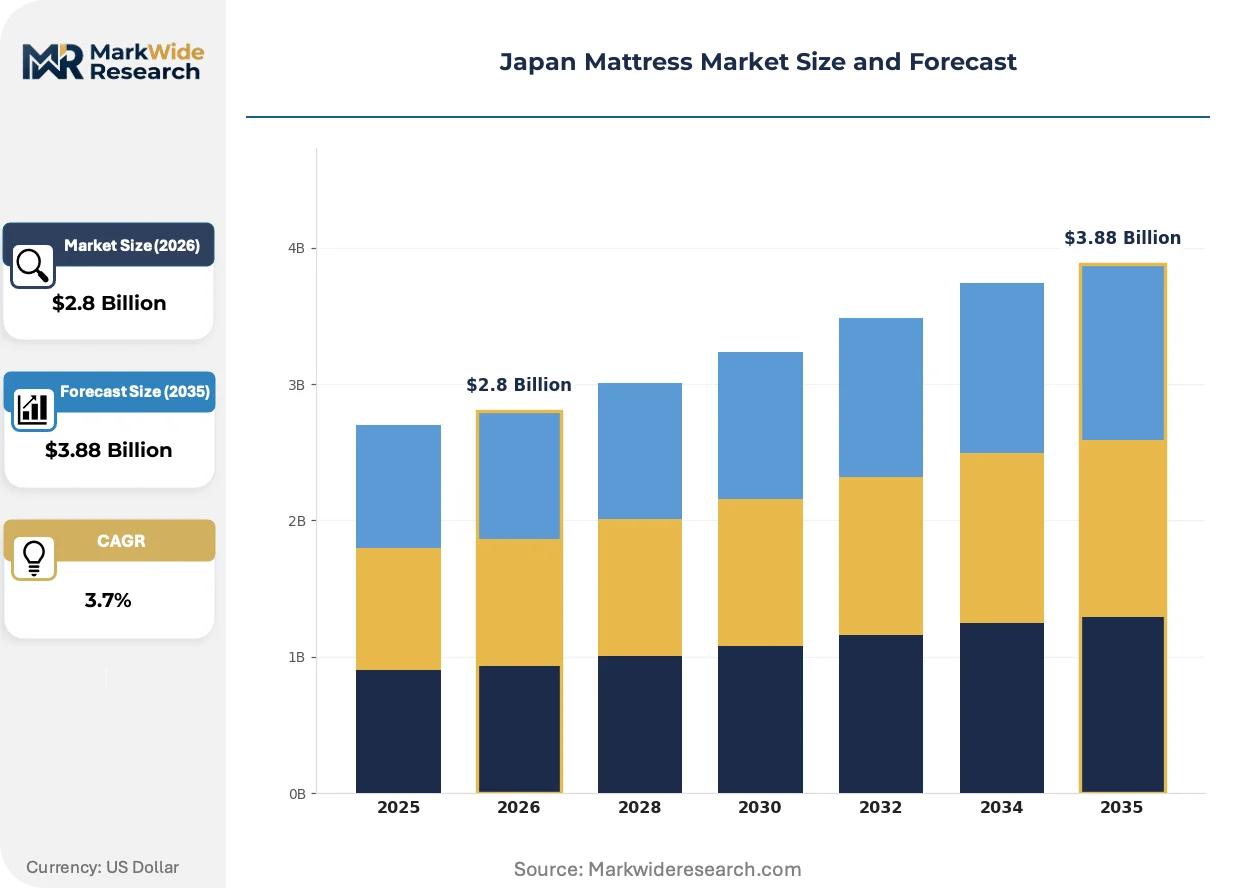
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Innerspring, Latex, Hybrid End User: Residential, Hospitality, Healthcare, Retail Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Nishikawa Co., Ltd., France Bed Holdings Co., Ltd., Nitori Holdings Co., Ltd., Airweave Inc., Simmons Co. Ltd., Tempur Sealy Japan, Paramount Bed Holdings Co., Ltd., Serta Simmons Bedding Japan, Sleep Select Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Mattress Market Shifts & Advancements
Sleep technology convergence with wellness monitoring and sustainable material science is collapsing traditional product boundaries, while regulatory chemistry constraints and hospitality procurement centralization reshape competitive requirements.
Proprietary fiber architectures are collapsing the performance gap between synthetic monofilament cores and conventional foam comfort layers. Athletic training facilities and luxury ryokan operators are specifying these breathable, washable systems for humidity management. The technology is collapsing aftermarket replacement cycles by enabling modular component swaps rather than full mattress disposal.
METI's implementation of extended producer responsibility frameworks under the Consumer Product Safety Act is mandating take-back infrastructure investment. Manufacturers must now finance collection networks for end-of-life mattress decomposition, raising fixed cost structures. Small and mid-tier producers in Aichi and Shizuoka prefectures are consolidating to share reverse logistics burdens.
Prefecture-level hospitality procurement consortia are consolidating mattress specifications across independent hotel operators, compressing supplier negotiation leverage. Osaka Tourism Bureau's collective purchasing program now covers 340 properties, standardizing on dual-firmness hybrid constructions. This buyer concentration is most visible in Kansai's budget and mid-scale lodging segment, where property managers prioritize warranty administration simplicity over brand differentiation.
Japan Mattress Market Segmentation
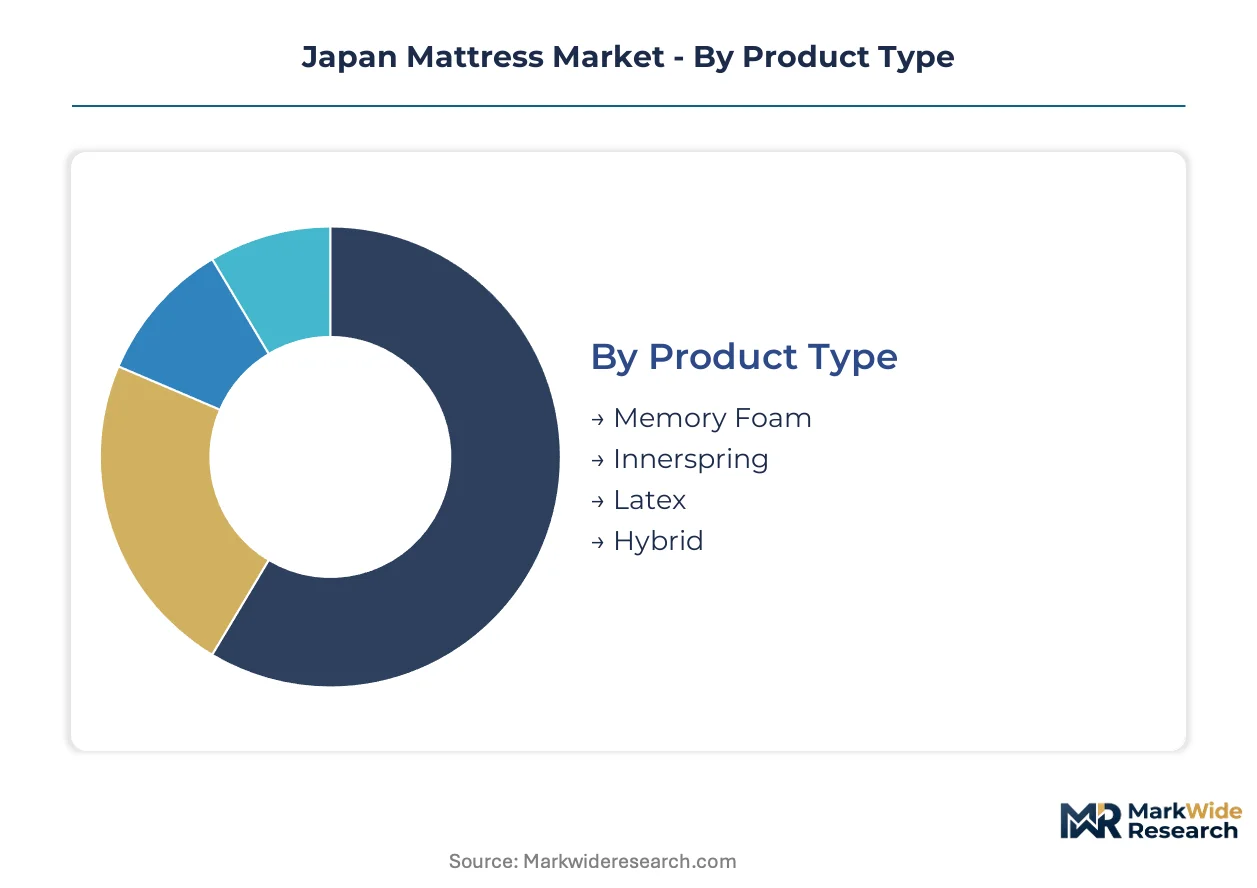
Mattress purchasing cycles diverge sharply across Japanese households, lodging operators, and medical facilities. Procurement timelines stretch from impulse online trials to decade-long hospital infrastructure contracts, fragmenting go-to-market economics for producers.
Product Type:
Replacement velocity separates fiber-core athletic surfaces from institutional foam systems with decade-long depreciation schedules.
- Innerspring:Continuous and pocketed coil assemblies dominate Japanese residential familiarity, with domestic wire drawing and textile quilting concentrated in Osaka-Nagoya manufacturing belts. Hospitality procurement in Tokyo and Osaka specifies these for standard guest room durability under JIS S 1102 flammability mandates.
- Hybrid:Pocketed coil bases layered with polyurethane or latex comfort zones capture renovation-driven demand from ryokan operators seeking pressure relief without abandoning traditional support feel. METI circular economy compliance costs compress margin structures for foam-dependent hybrid producers.
- Memory Foam:Viscoelastic polyurethane formulations face feedstock volatility from polyether polyol and TDI pricing swings in the Kansai petrochemical corridor.
- Latex:Natural rubber and synthetic latex cores serve humidity-sensitive sleepers in coastal prefectures with mold-resistant specifications.
Innerspring dominates installed base. Hybrid is where expansion concentrates.
End User:
Customer lifetime value escalates from single-transaction residential trials to multi-year healthcare facility service agreements with embedded maintenance revenue.
- Hospitality:Hotel operators in Osaka and Tokyo command premium average selling prices through flame-retardant certifications and extended warranty terms mandated by the Fire Service Act. Collective purchasing programs through prefecture tourism bureaus compress supplier negotiation leverage across 340-plus properties.
- Healthcare:Specialized pressure-relief bed systems for hospital infrastructure target aging prefectural facilities outside Tokyo with reimbursement-linked procurement cycles. France Bed Holdings anchors this segment through motorized frame integration.
- Residential:Greater Tokyo density drives online mattress-in-a-box trial among younger demographics bypassing traditional furniture retailer markups.
- Retail:Furniture showroom floor space allocation determines brand visibility for premium positioning in Kanto urban corridors.
Residential commands transaction volume. Healthcare is climbing the fastest for contract value per bed.
Distribution Channel:
Working capital intensity separates inventory-heavy retail networks from asset-light direct-to-consumer digital fulfillment.
- Online:Digital-native brands bypass traditional furniture retailer markups through compressed delivery logistics in Greater Tokyo, capturing demographic trial with modular component return policies.
- Retail Stores:Department store and specialty furniture floor space in Osaka and Nagoya concentrates premium brand visibility with tactile evaluation requirements.
- Wholesale:Hospitality procurement consortia and healthcare group purchasing organizations consolidate volume across multi-property operators.
- Direct Sales:Manufacturer-owned showrooms and sleep consultation services sustain margin capture for fiber-technology positioning in athletic recovery segments.
Retail stores dominate premium consideration. Online is gaining share fastest among first-time buyers.
Price Tier:
Margin structure stratifies by certification burden and component modularity rather than simple material cost ladders.
- Premium:Proprietary fiber architectures and certified recycled content quotas command positioning above standard foam constructions, with athletic training facilities and luxury ryokan operators specifying washable modular systems.
- Mid-range:Hybrid constructions with domestic coil sourcing and imported foam layers balance JIS compliance costs against price elasticity in Kanto residential markets.
- Economy:Basic innerspring and petroleum-based polyurethane systems face margin compression from petrochemical input volatility and METI take-back infrastructure financing requirements.
- Luxury:Custom dimensional specifications and extended warranty terms for high-net-worth residential and boutique hospitality projects sustain artisan production scales in textile heritage regions.
Mid-range holds volume concentration. Premium is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI anchors the Kanto region's regulatory framework through circular economy mandates and JIS S 1102 flammability enforcement. Prefecture-level procurement patterns diverge sharply between Tokyo's dense residential corridors and Osaka's hospitality-driven demand clusters.
Kanto/Tokyo
Greater Tokyo's residential density drives online mattress-in-a-box trial among younger demographics bypassing traditional furniture retailer markups. METI's extended producer responsibility frameworks mandate take-back infrastructure investment across manufacturers serving this corridor. Sleep technology convergence with wellness monitoring accelerates in Saitama and Chiba prefectures as direct-to-consumer brands establish fulfillment centers.
Kansai/Osaka
Osaka Tourism Bureau's collective purchasing program consolidates specifications across 340-plus independent hotel properties, standardizing dual-firmness hybrid constructions. The Fire Service Act's commercial lodging compliance requirements filter procurement toward flame-retardant certified domestic producers. Coil spring and textile quilting manufacturing clusters in Osaka and Kyoto prefectures sustain supply reliability for hospitality renovation cycles.
Chubu/Nagoya
Automotive industry heritage in Aichi prefecture translates into precision manufacturing capabilities for pocketed coil assembly and foam layering systems. Small and mid-tier producers in Shizuoka prefecture consolidate to share reverse logistics burdens under METI's recycled content verification protocols. Nagoya's logistics hub position enables just-in-time component delivery to hybrid construction facilities across central Japan.
Kyushu
Fukuoka's emerging startup ecosystem attracts direct-to-consumer mattress brands seeking lower operational costs than Tokyo corridors. Humidity-resistant latex specifications gain traction in coastal Oita and Kumamoto prefectures where mold-resistant sleep surfaces command premium positioning. Prefectural healthcare facility upgrade cycles create demand for pressure-relief bed systems in aging hospital infrastructure.
Hokkaido
Sapporo's distinct seasonal climate drives demand for temperature-regulating sleep surfaces among residential buyers. Insulated logistics requirements raise distribution costs for mattress-in-a-box operators serving rural prefectural populations. Tourism seasonality in Niseko and Furano creates intermittent hospitality procurement spikes distinct from mainland renovation cycles.
Japan Mattress Market Competitive Landscape
Capability concentration sits with heritage textile and healthcare specialists; scale advantage sits with diversified furniture retailers and global bedding conglomerates. The vendor base stratifies across three tiers: century-old domestic manufacturers with proprietary fiber architectures, multinational licensees leveraging brand recognition, and digital-native direct-to-consumer entrants compressing traditional markups. Strategic archetypes include athletic-recovery positioning specialists, hospital-system integrators, and hospitality procurement consolidators. Dominant competitive moves encompass circular economy certification preemption and prefecture-level tourism bureau partnership capture.
Among heritage-rooted specialists, Nishikawa Co., Ltd. and Airweave Inc. exemplify proprietary technology positioning, while France Bed Holdings Co., Ltd. anchors the healthcare facility integration archetype. These three occupy positions where century-old manufacturing lineage or specialized fiber engineering commands premium tier access distinct from commodity foam-dependent competitors.
| Leading Market Players |
|---|
| Nishikawa Co., Ltd. |
| France Bed Holdings Co., Ltd. |
| Nitori Holdings Co., Ltd. |
| Airweave Inc. |
| Simmons Co. Ltd. |
| Tempur Sealy Japan |
| Paramount Bed Holdings Co., Ltd. |
| Serta Simmons Bedding Japan |
| Sleep Select Co. Ltd. |
| Others |
Supply & Pricing Matrix
Osaka-Nagoya coil spring and textile quilting clusters concentrate upstream manufacturing leverage, directing margin capture toward hospitality procurement consortia and certified recycled-content producers while compressing foam-dependent hybrid margins under METI circular economy mandates.
Pricing Analysis
Greater Tokyo residential corridors command 15-25% premiums over Kansai wholesale channels for identical JIS S 1102-certified constructions. Three-tier pricing structure across premium, standard, and economy levels separates proprietary fiber architectures with modular component systems from petroleum-based polyurethane systems facing cost compression from polyether polyol volatility. Price differentiation rests on flame-retardant certification tier and extended warranty bundling. Healthcare facility buyers exhibit lowest price sensitivity due to reimbursement-linked procurement cycles, while budget hospitality operators in Kansai prioritize warranty administration simplicity over performance tier.
Supply Chain Analysis
Contract manufacturing for pocketed coil assembly concentrates in Aichi prefecture precision manufacturing facilities and Osaka textile heritage regions. Raw material sourcing draws from domestic wire drawing operations, imported natural rubber for latex cores, and Kansai petrochemical corridor polyether polyol feedstocks. Single-source vulnerability concentrates in seismic-exposed Osaka-Nagoya logistics clusters. Distribution runs through department store floor space allocation in urban corridors, direct-to-consumer compressed logistics in Greater Tokyo, and prefecture-level hospitality procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Osaka Tourism Bureau's 340-property collective purchasing program and prefecture-level healthcare group purchasing organizations, fragmenting supplier negotiation leverage across standardized specifications.
For Market Incumbents: Pre-empt circular economy certification displacement by securing METI recycled content verification ahead of 12-18 month qualification cycles. Lock in coil spring supply agreements with Aichi and Osaka manufacturing clusters before seismic disruption risk materializes. Defend against fiber-architecture athletic recovery positioning by accelerating proprietary washable modular system R&D.
For New Entrants and Emerging Players: Kyushu's emerging startup ecosystem in Fukuoka offers underpenetrated direct-to-consumer trial with lower operational costs than Tokyo corridors. Target humidity-resistant latex specifications in coastal Oita and Kumamoto prefectures where mold-resistant sleep surfaces command premium positioning. Bypass furniture retailer markups through digital-native compressed delivery logistics.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across foam-dependent hybrid construction segments as METI take-back infrastructure financing requirements raise fixed cost structures. Prioritize acquisition targets with proprietary fiber technology positioning and minimal petroleum-based polyurethane exposure. Monitor circular economy certification timeline acceleration as inflection signal for consolidation velocity among Aichi and Shizuoka small-tier producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Circular Economy Certification Preemption | Secures METI recycled content verification ahead of 12-18 month supplier qualification cycles blocking competitor launches. |
| Prefecture Tourism Bureau Partnership Capture | Osaka Tourism Bureau's 340-property collective purchasing program standardizes specifications and compresses supplier negotiation leverage. |
| Proprietary Fiber Architecture Development | Airweave Inc.'s synthetic monofilament core technology commands athletic recovery premium with minimal foam regulatory exposure. |
| Direct-to-Consumer Digital Channel Establishment | Compressed delivery logistics in Greater Tokyo bypass traditional furniture retailer markups capturing younger demographic trial. |
| Healthcare Facility Integration Partnership | France Bed Holdings Co., Ltd. anchors hospital-system integrator archetype through motorized frame integration and reimbursement-linked procurement cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, JIS S 1102 flammability standard documentation, and prefecture-level tourism bureau procurement records. Primary interviews incorporated mattress manufacturing plant managers in Aichi and Osaka, hospitality procurement directors at Tokyo and Osaka hotel operators, healthcare facility biomedical engineers, and furniture retailer category buyers in Kanto urban corridors. Secondary validation drew from Japan Customs trade data, Consumer Product Safety Act implementation guidelines, and Fire Service Act commercial lodging compliance interpretations. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Forecast inputs considered product type segmentation across innerspring, hybrid, memory foam, and latex constructions; end-user segmentation spanning hospitality, healthcare, residential, and retail channels; and distribution channel dynamics across online, retail store, wholesale, and direct sales. Modeled variables included inbound tourism recovery velocity, METI circular economy mandate implementation timelines, and petrochemical input price volatility. CAGRs were derived through regression analysis of historical consumption patterns against projected demographic and regulatory drivers.
Practitioners should monitor METI recycled content verification protocol acceleration, Fire Service Act prefectural enforcement fragmentation, and Stockholm Convention chemical restriction expansion for early signals of forecast revision. Assumptions reflect current regulatory trajectory and inbound tourism recovery sustainability. Quarterly review of hospitality renovation cycle announcements, foam recycler certification timelines, and polyether polyol pricing volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Heated Bedding Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Latin America Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Queen Mattress Market