
 Vietnam Mattress Market | 2026-2036
Vietnam Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Mattress Market Outlook
Hospitality buyers are unwinding the historical dominance of individual residential consumers in Vietnam's mattress procurement. Kim Cương Mattress anchors its position through deep wholesale relationships with furniture retailers across the Mekong Delta. Vua Nệm competes aggressively on digital channels, leveraging live-stream commerce to reach first-time homebuyers in urban districts. Tempur Sealy differentiates through premium memory foam positioning targeted at expatriate communities and high-end condominiums.
A mattress is a sleep support system comprising a textile-encased core of steel coils, polyurethane foam, natural latex, or layered combinations engineered to distribute body weight and maintain spinal alignment during rest. Foam density ratings between 25 and 40 kilograms per cubic meter determine durability grades for tropical climates with high humidity exposure. Memory foam and hybrid constructions now lead product type demand as Vietnamese consumers upgrade from basic innerspring units, while the hospitality end user segment generates the fastest order velocity through bulk procurement contracts. Distribution channel dynamics reveal online platforms capturing growing transaction volume despite showroom purchases retaining higher average order values for premium-tier products.
Vietnam's Directorate for Standards, Metrology and Quality enforces national technical regulations on mattress flammability and formaldehyde emissions under QCVN standards, while the Ministry of Construction oversees fire safety compliance for hospitality and institutional installations. These frameworks elevate manufacturing costs for domestic producers but simultaneously create compliance barriers against unregulated imports from neighboring markets. Stakeholders must monitor enforcement consistency across provincial inspection regimes and anticipate whether expanded QCVN coverage will mandate recycled content thresholds in foam production.
Market Dynamics
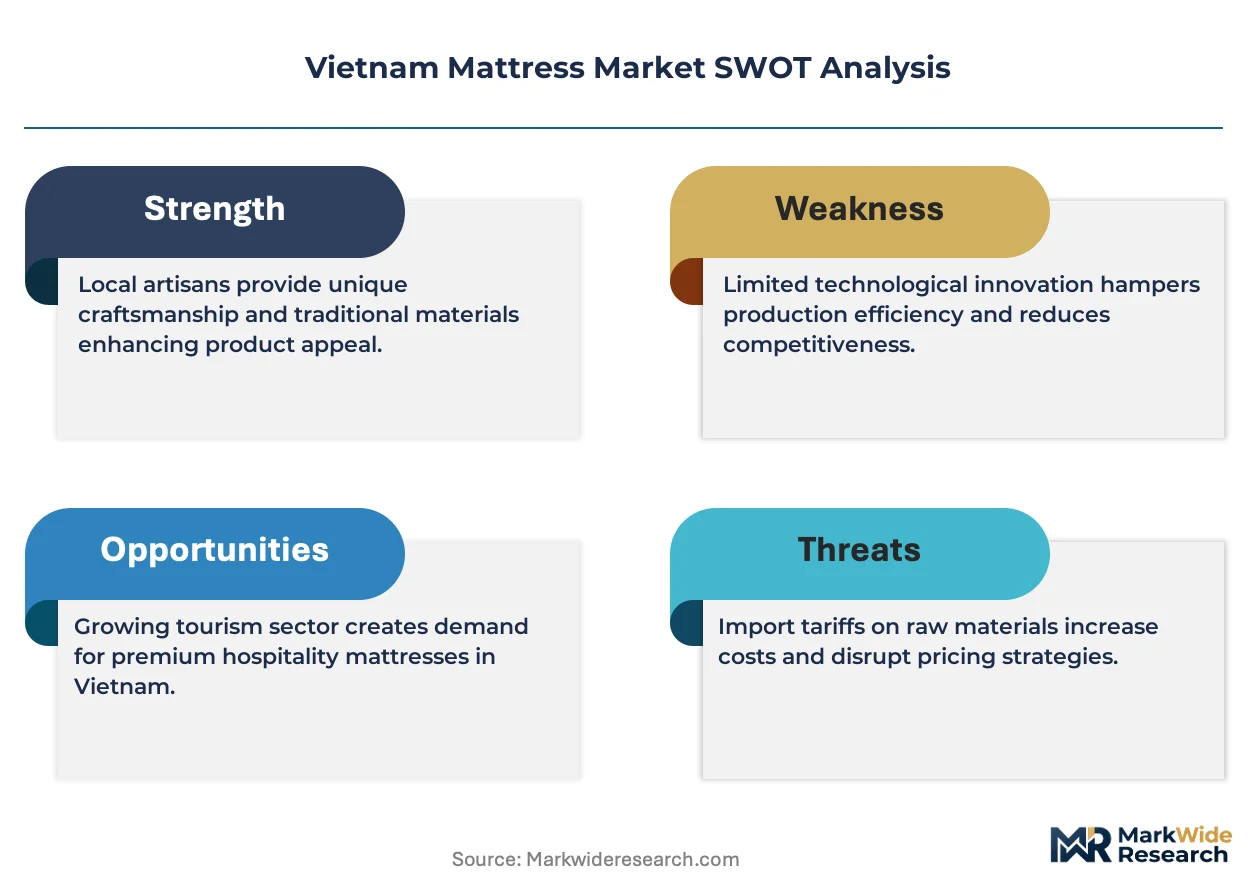
Hospitality procurement contracts are compressing residential dominance in Vietnam's mattress distribution, as bulk orders from international hotel chains in Ho Chi Minh City and Da Nang reshape volume allocation across domestic manufacturing capacity.
Growth Catalysts
- QCVN flammability mandates:Vietnam's Directorate for Standards, Metrology and Quality enforces tighter foam density and fire safety specifications, elevating product quality thresholds and filtering out substandard imports from neighboring markets.
- Hybrid construction adoption:Memory foam layered with pocketed coil systems delivers pressure relief and airflow suited to tropical humidity, capturing upgrade demand from basic innerspring units in urban districts.
- Southern economic corridor concentration:Binh Duong province's manufacturing clusters and Ho Chi Minh City's retail density create integrated supply-demand loops that accelerate fulfillment velocity for hospitality buyers.
Market Restraints
- Polyol and TDI feedstock volatility:Petrochemical input costs for polyurethane foam production fluctuate with crude oil benchmarks, compressing margin predictability for domestic manufacturers lacking long-term supply contracts.
- Import dependency for natural latex:Vietnam sources raw latex primarily from Thailand and Indonesia, exposing processors to cross-border supply interruptions and currency translation effects.
- QCVN compliance cost burden:Testing and certification requirements for formaldehyde emissions and fire resistance add fixed overhead that disadvantages smaller producers against scaled competitors.
Strategic Opportunities
- Central Highlands underpenetration:Da Lat and surrounding provinces lack dedicated mattress retail networks, creating first-mover advantage for brands establishing showroom-distribution hybrids outside the southern corridor.
- Live-stream commerce channels:Digital platforms enabling real-time product demonstration and installment payment integration unlock first-time homebuyer segments in secondary cities.
- Recycled content thresholds:Anticipated expansion of QCVN standards to mandate post-industrial foam reuse would reward early investors in circular production infrastructure.
Industry Challenges
- Skilled foam-cutting technician scarcity:Precision contouring for hybrid mattresses requires trained operators, yet vocational pipelines in Vietnam underproduce specialized manufacturing labor.
- Provincial inspection inconsistency:Enforcement of QCVN standards varies across regional quality bureaus, creating compliance uncertainty for multi-facility producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Mattress Market |
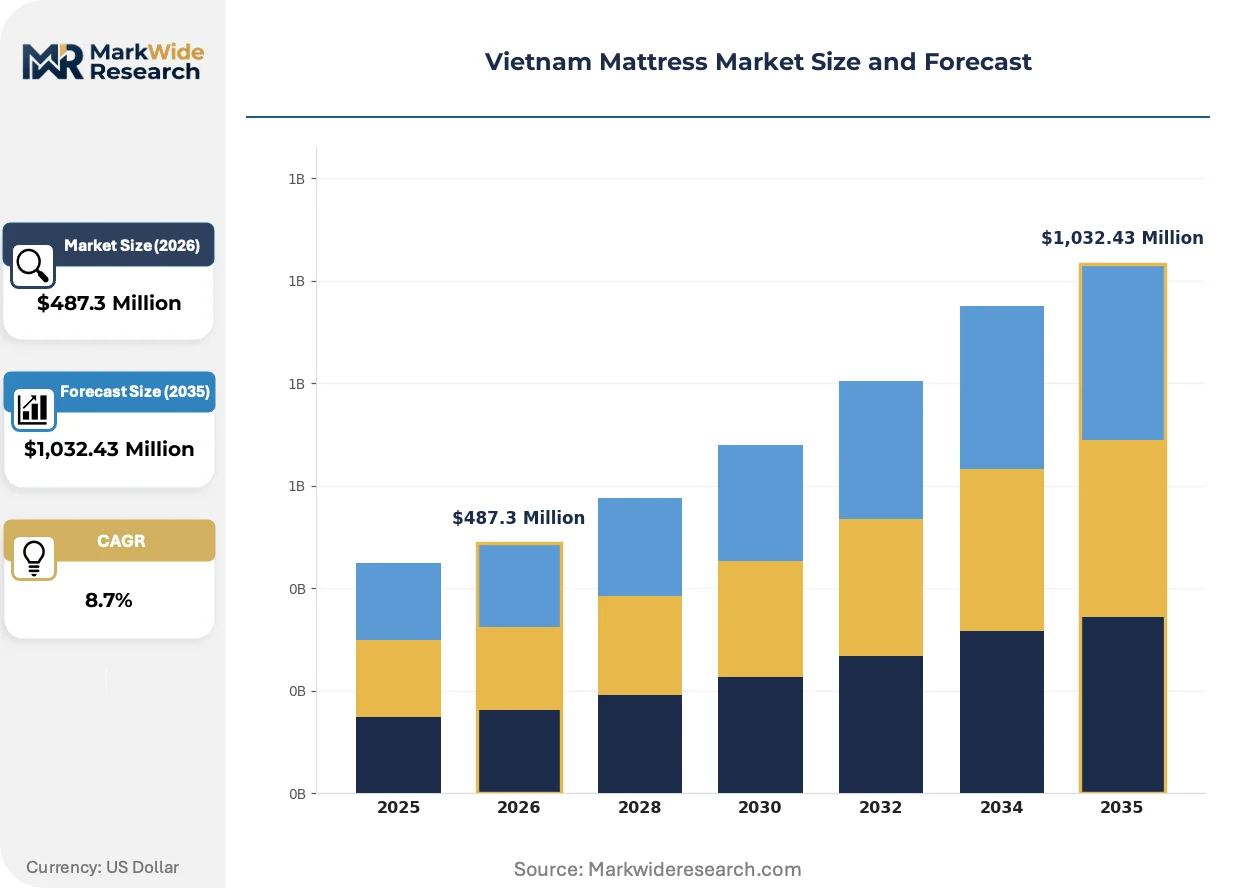
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid Size: Single, Queen, King, Custom Distribution Channel: Online, Retail Stores, Showrooms, Wholesale End User: Residential, Hospitality, Healthcare, Institutions |
| Companies Covered | Dunlopillo Vietnam, Kim Cương Mattress, Vua Nệm, Vinafoam, Hanvico, Liên Á, Everpia Everon, Tempur Sealy, Kymdan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Mattress Market Strategic Shifts
Product engineering and distribution mechanics are converging to reshape how sleep systems reach Vietnamese buyers, with regulatory pressure and digital commerce compressing traditional retail timelines.
Gel-infused memory foam formulations are miniaturizing thermal regulation into thinner profile layers, enabling mattress-in-a-box shipping formats. Hospitality procurement teams in Da Nang are adopting these compressed hybrids for rapid room turnover renovations. The technology is miniaturizing warehouse footprint requirements and enabling direct-to-project logistics that bypass traditional furniture retailer markups.
Vietnam's Ministry of Construction is tightening fire safety compliance protocols for hospitality installations, extending QCVN coverage to mattress specifications in hotels and serviced apartments. Domestic manufacturers are reconfiguring production lines to integrate intumescent barrier fabrics. High-rise condominium developments in Ho Chi Minh City face the steepest retrofit timelines, accelerating specification shifts toward certified foam constructions.
Buyers are fragmenting across channel preferences, with showroom purchases retaining premium-tier average order values while digital platforms capture growing transaction volume for entry-level and mid-range segments. Live-stream commerce is displacing catalog-based wholesale for furniture retailers in the Mekong Delta. This bifurcation is most visible in Ho Chi Minh City, where expatriate communities sustain flagship store traffic while young professionals transact primarily through mobile-optimized marketplaces.
Vietnam Mattress Market Segmentation
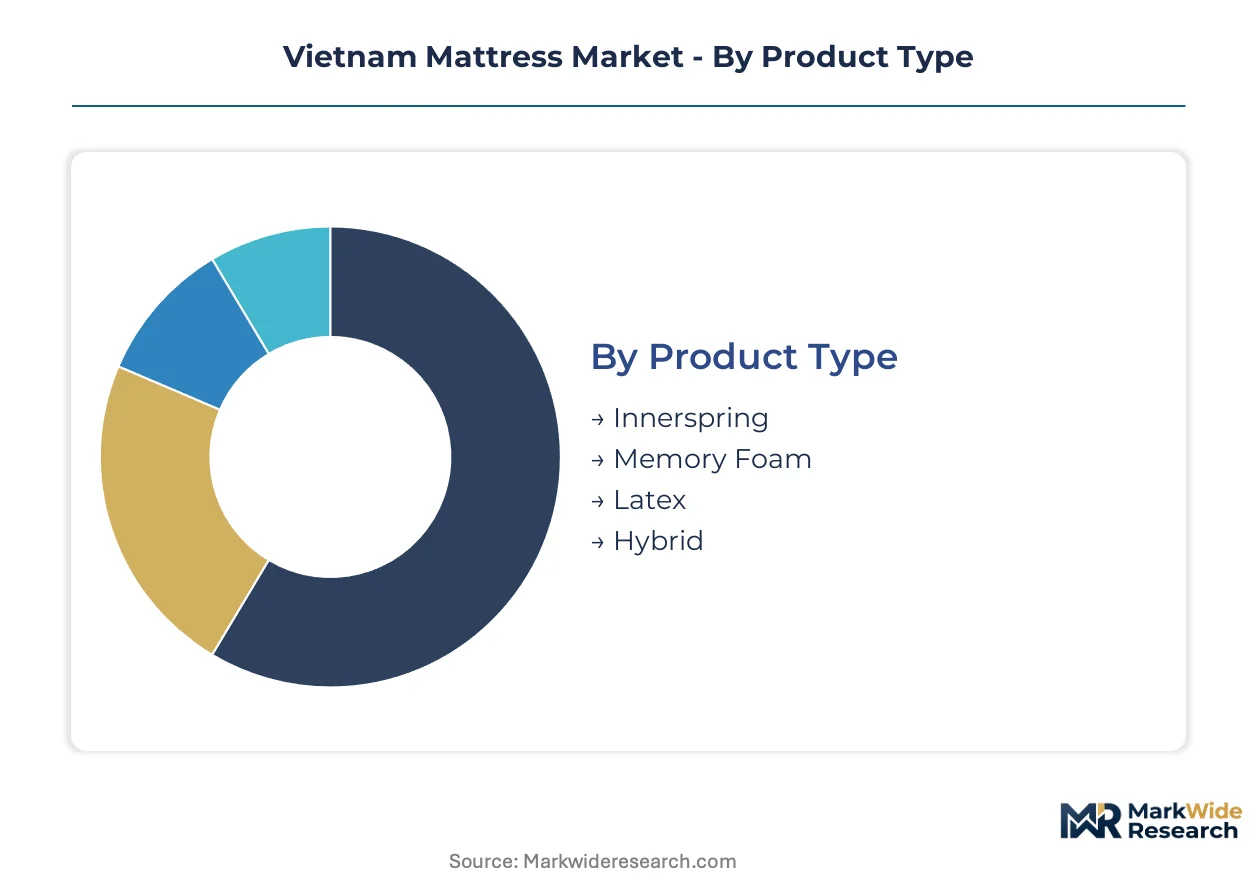
Vietnam's mattress market fragments across four structural dimensions that determine pricing power, fulfillment velocity, and regulatory exposure. Channel mix varies sharply by segment, with hospitality procurement bypassing retail entirely while residential buyers split between digital platforms and showroom experiences.
Product Type:
Channel allocation diverges by construction technology, with compressed hybrids dominating direct-to-hotel logistics and traditional innerspring units flowing through furniture retailer networks in the Mekong Delta.
- Innerspring:Steel coil cores with quilted padding remain the baseline construction for price-sensitive residential buyers in secondary cities. Demand concentrates in rural provinces where replacement cycles stretch beyond ten years and durability concerns override comfort preferences.
- Memory Foam:Viscoelastic polyurethane formulations adapt to body contours and isolate motion transfer. Urban condominium dwellers in Ho Chi Minh District 2 and Binh Duong factory workers upgrading from basic units drive the steepest volume expansion through live-stream commerce channels.
- Latex:Natural rubber sap derivatives offer antimicrobial properties suited to tropical humidity. Boutique hotels in Da Nang specify certified organic latex for wellness-positioned properties, though import dependency on Thai raw material constrains domestic processor margins.
- Hybrid:Pocketed coil bases layered with memory foam or latex comfort zones balance support and pressure relief. Hospitality procurement teams in Ho Chi Minh City favor compressed hybrid formats for rapid renovation timelines in high-rise hotel properties.
Innerspring dominates installed base. Hybrid constructions are where expansion concentrates.
Size:
Unit economics and shipping logistics reshape margin profiles across dimensional categories, with standardized queen formats enabling warehouse efficiency and custom dimensions capturing premium positioning in serviced apartment developments.
- Single:Compact dimensions target dormitory housing, worker accommodations, and budget hospitality installations. University-adjacent retail clusters in Thu Duc City move high volumes through cash-and-carry wholesale.
- Queen:The dimensional standard for Vietnam's emerging middle-class households and three-star hotel specifications. Binh Duong manufacturing clusters optimize production lines around queen-format cutting patterns to minimize foam waste.
- King:Expanded surface area commands premium positioning in luxury condominiums and international-branded hotels. Expatriate enclaves in District 7 sustain showroom traffic for king-format demonstrations.
- Custom:Non-standard dimensions serve yacht builders, premium serviced apartments, and heritage hotel renovations requiring bespoke fittings. Da Nang's resort architecture firms specify custom widths for ocean-view suite configurations.
Queen formats anchor manufacturing scale. Custom sizing is climbing the fastest.
Distribution Channel:
Customer acquisition costs and average order values invert across channel structures, with digital platforms capturing transaction volume while physical touchpoints retain margin concentration in premium tiers.
- Online:Mobile-optimized marketplaces and live-stream commerce enable installment payment integration for first-time homebuyers. Vua Nệm's digital-first positioning targets urban professionals in Ho Chi Minh City through real-time product demonstrations.
- Retail Stores:Furniture retailer networks across the Mekong Delta provide tactile evaluation for consumers upgrading from multi-generational sleeping arrangements. Kim Cương Mattress anchors wholesale relationships with provincial showroom operators.
- Showrooms:Flagship experiential spaces in Ho Chi Minh City District 1 sustain premium-tier average order values through white-glove delivery positioning. Expatriate communities and high-net-worth Vietnamese households dominate foot traffic.
- Wholesale:Direct bulk procurement contracts bypass retailer markups for hospitality and institutional buyers. International hotel chains in Da Nang negotiate project-specific pricing through manufacturer-direct relationships.
Retail stores command the broadest geographic footprint. Online channels are gaining share fastest.
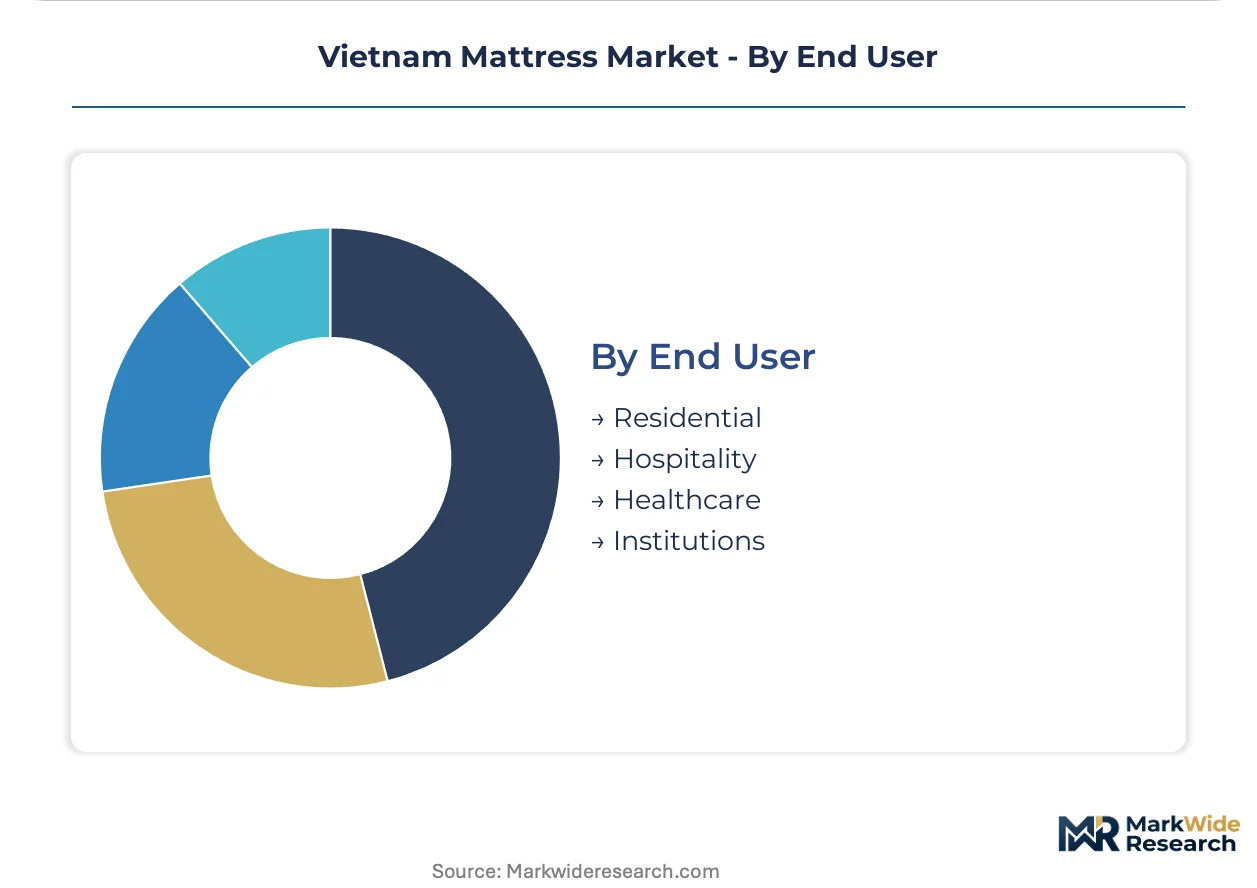
End User:
Procurement sophistication and specification intensity separate institutional buyers from individual consumers, with hospitality and healthcare segments driving standardization toward certified foam constructions.
- Residential:Individual households and family units represent the historical demand core, though share is compressing as hospitality procurement accelerates. Urban first-time buyers in Thu Duc and Binh Duong favor memory foam upgrades through digital channels.
- Hospitality:International hotel chains and domestic resort operators in Ho Chi Minh City and Da Nang generate the fastest order velocity through multi-year supply agreements. QCVN flammability compliance is non-negotiable for starred hotel classifications.
- Healthcare:Hospitals and eldercare facilities specify pressure-relief surfaces with antimicrobial treatments. The Ministry of Construction's fire safety protocols extend to healthcare mattress installations, elevating certified supplier requirements.
- Institutions:Military barracks, university dormitories, and correctional facilities prioritize durability and cost efficiency over comfort features. Bulk tender processes favor domestic manufacturers with scaled production capacity.
Residential users dominate transaction count. Hospitality buyers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports finished mattresses to hospitality buyers across Southeast Asia while importing natural latex feedstock from Thailand and Indonesia, creating a trade-flow corridor that concentrates manufacturing capacity in the southern economic corridor.
Ho Chi Minh City
Expatriate communities and luxury condominium developments drive premium-tier demand through flagship showroom channels. The Ministry of Construction enforces QCVN fire safety protocols for high-rise installations. District 1 and District 2 retail clusters sustain the highest average order values for memory foam and hybrid constructions.
Binh Duong Province
Manufacturing clusters optimize queen-format production lines to serve hospitality procurement contracts. Vietnam's Directorate for Standards, Metrology and Quality operates provincial inspection bureaus monitoring foam density compliance. Thuận An and Dĩ An industrial zones host compressed hybrid assembly operations for direct-to-hotel logistics.
Da Nang
International resort operators and boutique wellness properties generate bulk orders for certified latex and gel-infused memory foam. QCVN flammability mandates apply to starred hotel classifications under national tourism standards. The Hòa Hải and Ngũ Hành Sơn districts concentrate ocean-view suite developments specifying custom mattress dimensions.
Mekong Delta
Furniture retailer networks across Cần Thơ and Long An provinces distribute basic innerspring units to rural households with extended replacement cycles. Provincial quality bureaus enforce QCVN formaldehyde emission standards with variable consistency. Cash-and-carry wholesale channels dominate transaction volume outside urban centers.
Vietnam Mattress Market Competitive Environment
Listed leaders compete with private specialists across distribution channel control, creating a tiered structure where scale-driven manufacturers battle digital-native retailers for residential segment share. Domestic producers with captive foam-cutting operations hold cost advantages against import-reliant competitors. Three archetypes dominate: vertically integrated fabricators controlling polyurethane supply, digital-first retailers leveraging live-stream commerce, and premium-positioned international brands targeting expatriate enclaves. Capacity expansion and wholesale relationship deepening represent the dominant competitive moves.
Among domestic specialists, Kim Cương Mattress and Vua Nệm occupy distinct positioning vectors. Kim Cương Mattress exemplifies the wholesale-anchored archetype through furniture retailer network penetration across provincial Vietnam. Vua Nệm represents the digital-native model, capturing urban first-time homebuyers through mobile-optimized marketplaces. Tempur Sealy sits within the premium international tier, targeting high-net-worth households and luxury hospitality specifications.
| Leading Market Players |
|---|
| Dunlopillo Vietnam |
| Kim Cương Mattress |
| Vua Nệm |
| Vinafoam |
| Hanvico |
| Liên Á |
| Everpia Everon |
| Tempur Sealy |
| Kymdan |
| Others |
Value Chain & Pricing Dynamics
Queen-format production line optimization in Binh Duong's manufacturing clusters generates scale economies that compress unit costs while simultaneously elevating price floors for non-compliant imports facing QCVN certification barriers. This concentration of foam-cutting capacity and regulatory enforcement in Vietnam's southern corridor creates asymmetric pricing power where domestic scaled producers capture margin expansion against fragmented regional competitors.
Pricing Analysis
The technology-generation pricing gap separating basic innerspring constructions from gel-infused memory foam and hybrid systems spans three distinct performance tiers. Pricing stratifies across premium certified foam, standard polyurethane, and economy innerspring levels, with QCVN flammability compliance and density ratings serving as primary differentiation drivers. Cost compression in the standard tier is intensifying because petrochemical feedstock volatility erodes margin predictability for manufacturers lacking long-term polyol contracts. Hospitality procurement teams exhibit the lowest price sensitivity due to bulk contract structures, while rural residential buyers in the Mekong Delta remain most responsive to unit cost fluctuations.
Supply Chain Analysis
Thai and Indonesian natural latex feedstock transit through cross-border corridors that expose Vietnamese processors to currency translation effects and supply interruptions. Domestic manufacturing draws from imported polyol and TDI petrochemicals, natural rubber derivatives, and steel coil components sourced from regional metallurgical suppliers. Single-source vulnerability concentrates in natural latex dependency where Thai plantation supply dominates regional availability. Distribution runs through compressed hybrid direct-to-hotel logistics for institutional buyers and furniture retailer networks for provincial residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Vietnam's mattress market creates multiple niche entry points as hospitality procurement accelerates and digital channels displace traditional retail hierarchies. The divergence between bulk institutional contracts and individualized residential transactions generates distinct competitive arenas with divergent capability requirements.
For Market Incumbents: Consolidate wholesale relationships with provincial furniture retailers in the Mekong Delta to defend share against digital-native competitors capturing urban first-time buyers. Deepen captive foam-cutting operations to offset petrochemical input volatility and create margin buffers against scaled import competition. Prioritize QCVN certification maintenance as regulatory enforcement tightens across provincial inspection regimes.
For New Entrants and Emerging Players: QCVN fast-track certification for compressed hybrid formats unlocks hospitality procurement channels in Da Nang's resort corridor where renovation timelines demand rapid fulfillment. Target the Central Highlands around Da Lat where dedicated mattress retail networks remain absent and showroom-distribution hybrids can capture first-mover positioning. Deploy live-stream commerce with installment payment integration to reach secondary city professionals outside Ho Chi Minh City's saturated digital marketplace.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic manufacturers with integrated polyurethane supply and established wholesale networks over import-reliant distributors facing tariff exposure. Long-term viability rests on circular production infrastructure readiness as anticipated QCVN expansion mandates recycled content thresholds. Monitor enforcement consistency across Vietnam's provincial quality bureaus as the signal indicating whether compliance barriers will structurally advantage scaled domestic producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Feedstock | Captive polyol supply insulates margin structures from crude oil benchmark volatility affecting competitors. |
| QCVN Certification Pre-Positioning | Early compliance investment creates procurement eligibility for starred hotel classifications under Ministry of Construction protocols. |
| Live-Stream Commerce Platform Development | Real-time demonstration capability with installment integration captures first-time homebuyer segments in Thu Duc and Binh Duong. |
| Central Highlands Distribution Network Establishment | Showroom-distribution hybrids in Da Lat address underpenetrated provinces lacking dedicated mattress retail infrastructure. |
| Circular Production Infrastructure Investment | Post-industrial foam reuse capabilities anticipate expanded QCVN mandates rewarding early circular economy adopters. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospitality procurement managers at international hotel chains, foam production technicians in Binh Duong manufacturing clusters, furniture retailer owners across Mekong Delta provinces, and e-commerce platform specialists operating live-stream commerce channels. Secondary validation incorporated Vietnam Directorate for Standards, Metrology and Quality regulatory filings, Ministry of Construction fire safety protocols, customs trade data on natural latex imports, and provincial industrial zone capacity reports. Bottom-up triangulation across manufacturing facility outputs and top-down reconciliation against hospitality construction permits anchored volume estimates.
The projection horizon spans the analysis window with segmentation modeling across product type, size format, distribution channel, and end-user category dimensions specific to Vietnam's mattress procurement structure. CAGRs were derived from regression analysis of historical hospitality contract velocity, residential replacement cycle compression, and digital channel penetration rates. Industry-specific forecast inputs incorporated QCVN enforcement trajectory assumptions and petrochemical feedstock price band scenarios.
Decision-makers should treat outputs as directional under base assumptions of continued southern economic corridor manufacturing concentration and steady QCVN compliance tightening; material deviation in provincial enforcement consistency or cross-border latex supply disruption would warrant model refresh. Practitioners should keep alternative scenarios live as regulatory expansion timelines and circular economy mandate specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
Malaysia Mattress Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market