
 Bedding Market | 2026-2036
Bedding Market Size, Share, and Industry Trends Forecast 2026-2036
Bedding Market Analysis
Upholstery craftsmanship and textile engineering talent is bifurcating the competitive landscape between artisanal producers and automated manufacturers. Tempur Sealy International leverages vertical integration across foam production and retail distribution to control margin capture. Serta Simmons Bedding sustains manufacturing scale across North American plants, anchoring its position in wholesale and hospitality supply. Sleep Number Corporation differentiates through adjustable air-chamber technology, specializing in personalized sleep systems that command premium pricing.
Bedding encompasses mattresses, bed linens, pillows, and complementary sleep surfaces engineered from layered textiles, foams, springs, or natural fills to provide ergonomic support and thermal regulation during rest. Production integrates quilting, tufting, foam pouring, and fabric finishing processes where thread count, fill power, and density ratings determine performance grades and price positioning. Cotton and silk materials occupy the highest margin pools in residential channels, while polyester dominates hospitality procurement due to durability requirements and laundering economics. Online retail is accelerating fastest among distribution channels, displacing brick-and-mortar stores as direct-to-consumer brands like Casper Sleep and Brooklinen capture younger demographics with compressed delivery models and trial-period guarantees.
EPA guidelines on volatile organic compound emissions from foam manufacturing constrain domestic production standards, while OEKO-TEX and GOTS certifications shape consumer trust and retail access across European and North American markets. The EU Green Deal textile strategy and REACH chemical restrictions are forcing reformulation of flame retardants and dye processes, raising compliance costs for exporters. Stakeholders must monitor how evolving extended producer responsibility frameworks for mattress recycling reshape cost structures and regional manufacturing location decisions.
Market Dynamics
Hotel renovation cycles and EU textile sustainability mandates are compressing supplier lead times while forcing material reformulation across foam and fabric production networks.
Growth Catalysts
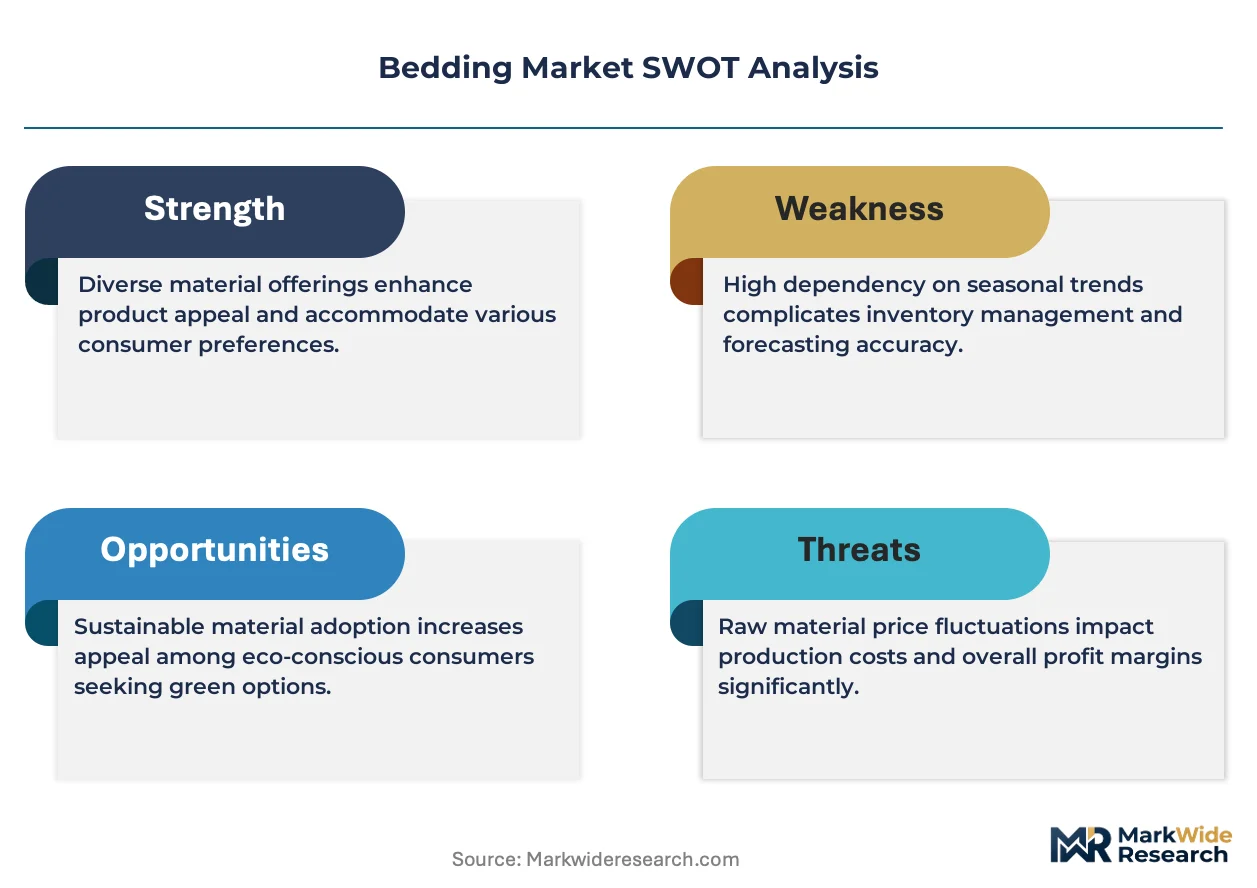
- REACH chemical restrictions:European manufacturers are accelerating investment in bio-based flame retardants and natural dye processes to maintain retail access across Germany, France, and the Netherlands.
- Hospitality procurement expansion:Premium linen orders from hotel chains in the United States and Spain are pulling specialized cotton and silk suppliers into long-term supply agreements.
- Direct-to-consumer compression:Mattress brands operating on compressed delivery models with trial-period guarantees are capturing younger demographics previously served by department store channels.
Market Restraints
- Petrochemical input volatility:Polyurethane foam producers face margin pressure from propylene oxide and TDI price swings that resist hedging through standard commodity instruments.
- Single-origin supply concentration:Egyptian long-staple cotton availability concentrates around the Nile Delta, exposing premium bedding manufacturers to climate and currency risk.
- Recycling infrastructure gaps:Extended producer responsibility frameworks for mattress end-of-life processing remain underdeveloped across most US states and Canadian provinces.
Strategic Opportunities
- India residential underpenetration:Organized mattress and linen distribution remains concentrated in tier-1 cities, leaving tier-2 and tier-3 urban centers accessible to brands with localized supply chains.
- EU Green Deal textile strategy:Mandatory recycled content thresholds and carbon footprint labeling create first-mover advantage for manufacturers with certified circular material flows.
- Sleep tracking convergence:Integration of biometric sensors with adjustable air-chamber and foam core systems opens premium pricing tiers in the United States and Germany.
Industry Challenges
- Quilting and tufting craft scarcity:Artisanal upholstery skills required for high-thread-count finishing are retiring faster than vocational programs in Portugal and Italy can replenish them.
- OEKO-TEX certification timelines:Testing backlogs at accredited laboratories extend product launch schedules by four to six months for new fabric formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bedding Market |
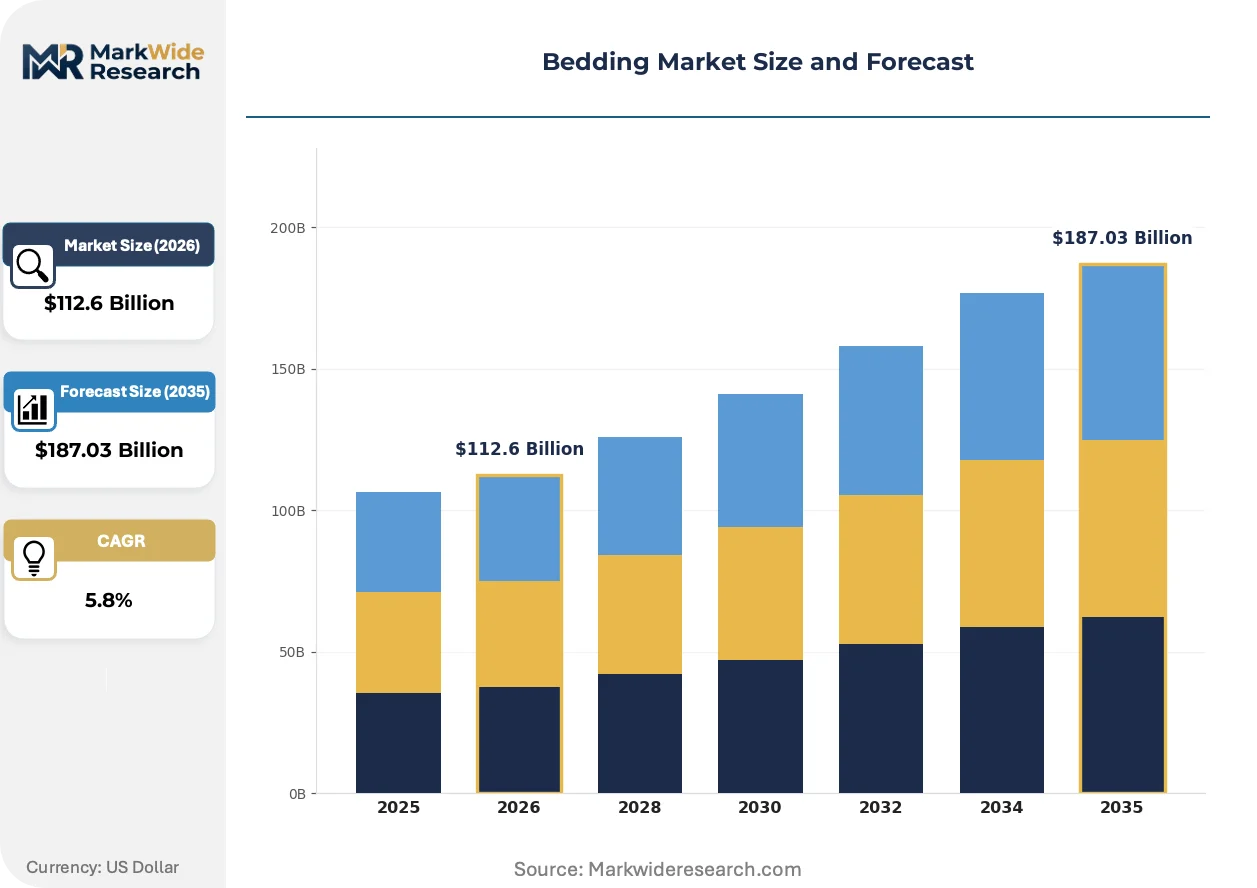
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $187.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedsheets, Pillowcases, Comforters, Duvet Covers Material: Cotton, Polyester, Silk, Linen End User: Residential, Hospitality, Healthcare, Educational Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Tempur Sealy International, Serta Simmons Bedding, Sleep Number Corporation, Casper Sleep, Boll & Branch, Brooklinen, Parachute Home, Hollander Sleep Products, Kingsdown, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bedding Market Emerging Trajectories
Sleep technology, regulatory chemistry, and distribution logistics are converging to reshape how bedding manufacturers design, certify, and deliver products to residential and commercial buyers.
Phase-change materials embedded in mattress covers and pillow fabrics are fragmenting thermal regulation performance across price tiers. Hospitality buyers in Dubai and Singapore are specifying these materials for guest room renovations at accelerated rates. The technology is fragmenting what previously required separate cooling accessories into base product functionality, compressing add-on sales for traditional mattress protectors.
EPA volatile organic compound emission guidelines for foam pouring operations are tightening domestic production standards across US manufacturing facilities. Facilities in North Carolina and California are retrofitting ventilation and capture systems to comply with revised thresholds. Small and mid-size foam producers without capital reserves are exiting or consolidating, concentrating supply among operators with compliance infrastructure.
Compressed delivery models with 100-night trial guarantees are displacing brick-and-mortar mattress showrooms as the primary purchase channel for first-time buyers. Younger demographics in the United States and United Kingdom are completing transactions through mobile-optimized platforms that coordinate white-glove installation. This channel shift is compressing traditional wholesale relationships and forcing legacy manufacturers to build direct fulfillment capabilities.
Bedding Market Segmentation
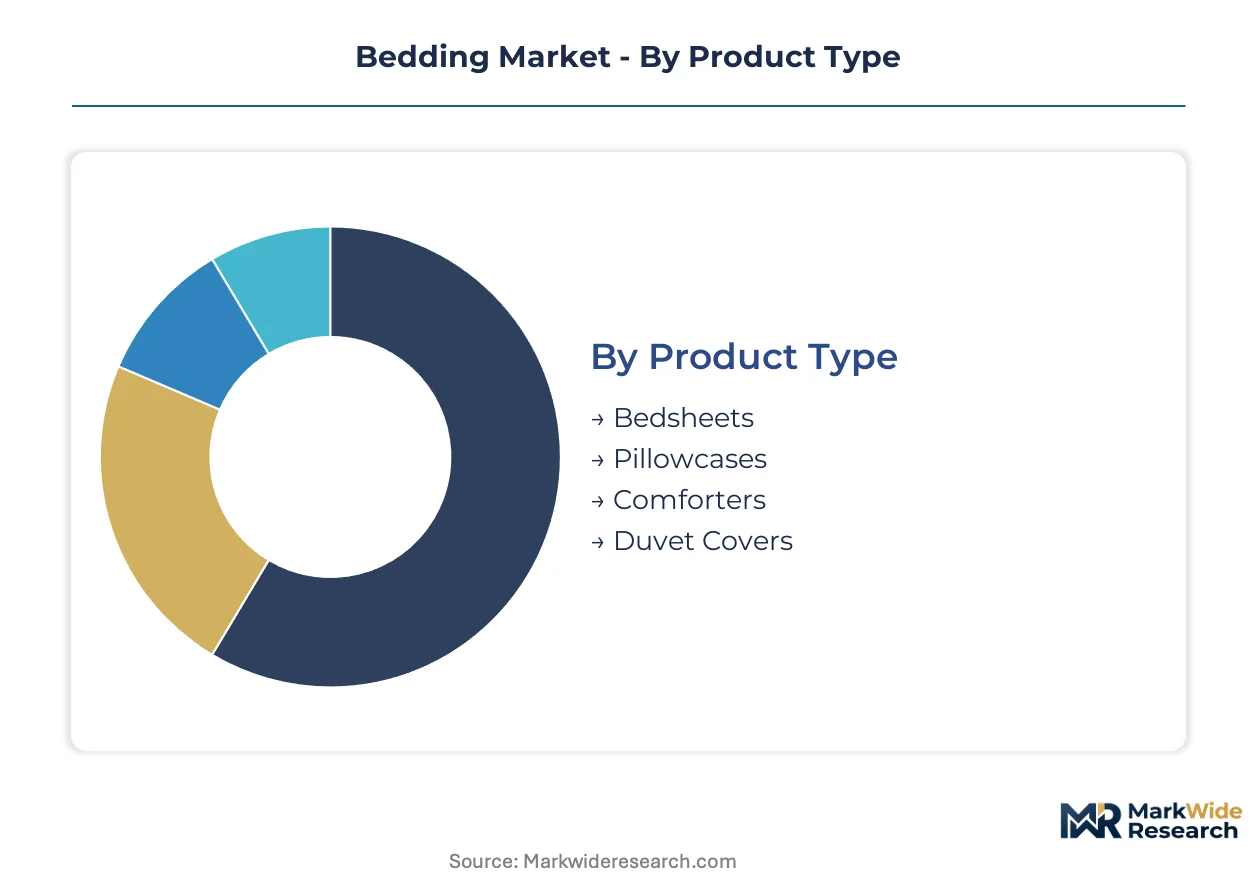
Bedding procurement patterns fragment sharply across use cases, with hospitality buyers prioritizing laundering durability while residential consumers chase thread-count prestige and thermal regulation performance. Material certification tiers and distribution channel economics create distinct margin pools that manufacturers must navigate through specialized production lines.
Product Type:
Bedsheets dominate domestic production volumes across Portugal and Italy, while duvet covers and comforters drive export-led demand from Turkish and Indian manufacturing clusters.
- Bedsheets:Woven cotton percale and sateen constructions with thread counts from 200 to 800 define quality tiers. American direct-to-consumer brands and German department store buyers concentrate orders in the 400-600 thread-count band where Egyptian and Supima cotton commands premium positioning.
- Comforters:Baffle-box construction with down, down-alternative, or wool fill determines thermal performance ratings. Hospitality procurement teams in Spain and the United States specify synthetic fills for laundering economics, while residential channels in Japan and South Korea chase goose down from Hungarian and Polish suppliers.
- Pillowcases:Envelope and housewife closures differentiate price positioning, with silk charmeuse variants capturing bridal registry demand in the United Kingdom and Australia.
- Duvet Covers:Button, tie, and zipper closures pair with interior corner ties to prevent insert shifting; Scandinavian buyers prioritize OEKO-TEX-certified organic cotton for nursery applications.
Bedsheets command the established base. The steepest expansion runs through comforters as phase-change material integration opens premium thermal regulation tiers.
Material:
Cost tier stratification separates commodity polyester volumes from certified organic cotton premiums, with silk and linen occupying niche luxury positioning.
- Cotton:Long-staple Egyptian, Pima, and Supima varieties deliver softness and durability through mercerization and singeing finishing. REACH-compliant dye houses in Portugal and Turkey are consolidating supply agreements with German and Dutch retail buyers facing EU Green Deal recycled content mandates.
- Polyester:Microfiber and brushed polyester constructions offer stain resistance and rapid drying for healthcare and hospitality institutional buyers. Chinese and Vietnamese producers dominate volume exports to North American hospitality chains seeking 200-wash lifecycle guarantees.
- Silk:Mulberry silk with 19-25 momme weight specifications serves bridal and luxury residential segments across Japan, South Korea, and the United Arab Emirates.
- Linen:Belgian and French flax-derived fibers with stone-washed finishing attract sustainability-positioned consumers in Denmark, Sweden, and California.
Cotton anchors volume production. Linen is climbing the fastest as carbon footprint labeling and farmhouse aesthetic trends converge in European and North American residential channels.
End User:
Application-driven specifications create divergent procurement calendars, with hospitality and healthcare buyers operating on renovation cycles while residential demand follows seasonal promotional patterns.
- Residential:Thread-count signaling, certification badges, and trial-period guarantees drive purchase decisions among first-time homebuyers and registry participants. Compressed delivery models from direct-to-consumer brands are displacing department store bridal departments in the United States and United Kingdom.
- Hospitality:200-thread-count minimums, industrial laundering compatibility, and color-fastness to 150+ wash cycles dominate procurement specifications. Marriott, Hilton, and Accor renovation programs across the United States, Spain, and the United Arab Emirates are pulling specialized suppliers into three-year supply agreements.
- Healthcare:Antimicrobial finishing, fluid-barrier properties, and flame-retardant compliance shape hospital and long-term care facility procurement in Germany, France, and Japan.
- Educational:Durability specifications for dormitory residence halls concentrate demand around twin-XL dimensions and polyester-cotton blends across American public university systems.
Residential channels command the established base. Hospitality is expanding most quickly as hotel renovation accelerates and premium linen specifications tighten supplier qualification requirements.
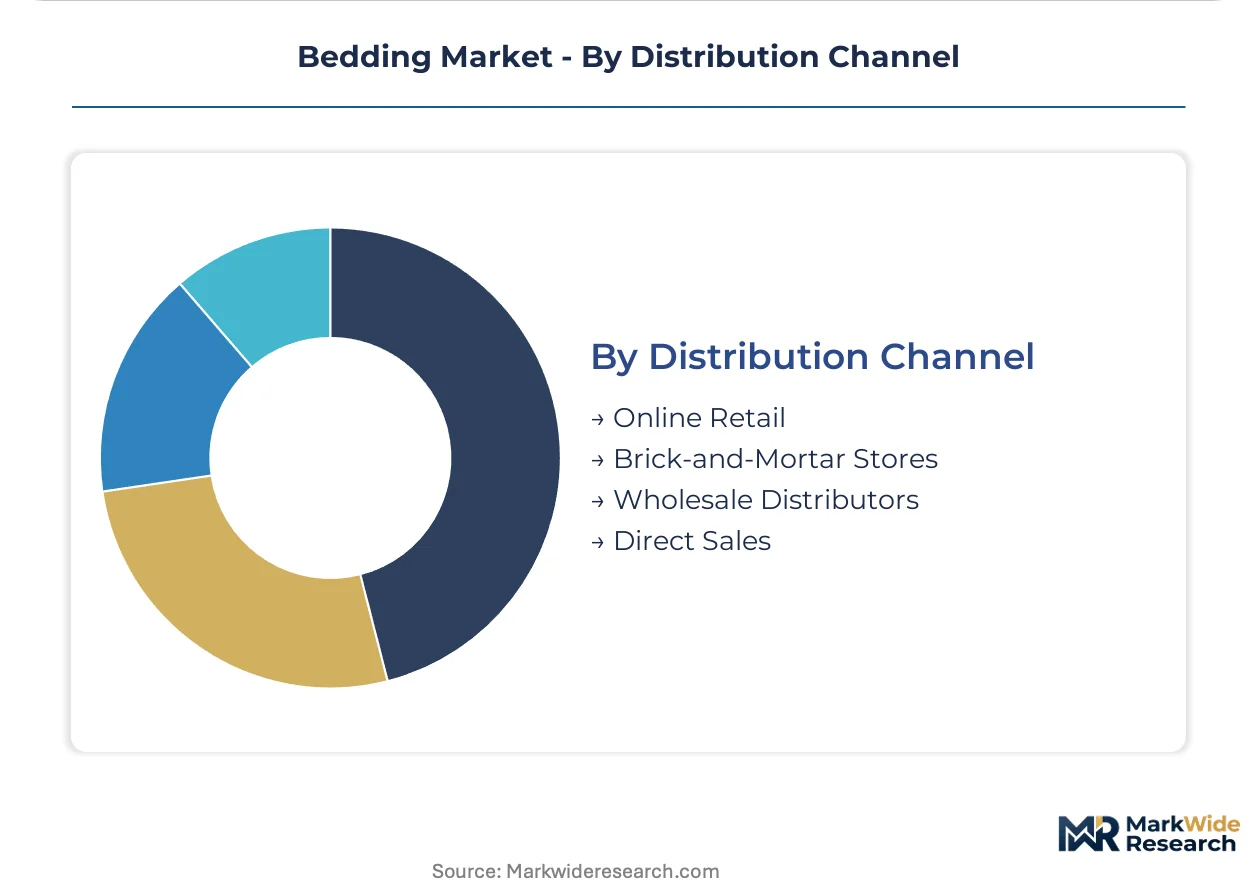
Distribution Channel:
Customer type and purchase occasion determine channel selection, with mobile-optimized platforms capturing younger demographics while wholesale relationships sustain institutional volume.
- Online Retail:Mobile-optimized storefronts with 100-night trial guarantees and white-glove delivery coordination. Casper Sleep, Brooklinen, and Parachute Home are compressing delivery timelines and displacing brick-and-mortar mattress showrooms among millennial and Gen Z buyers in the United States and United Kingdom.
- Brick-and-Mortar Stores:Tactile evaluation of thread count, hand-feel, and color matching sustains bridal registry and luxury department store traffic at Nordstrom, John Lewis, and El Corte Inglés locations.
- Wholesale Distributors:Linen service operators and hospitality procurement intermediaries aggregate volume for institutional buyers, with Sysco and Bunzl maintaining bedding categories for North American healthcare and foodservice lodging clients.
- Direct Sales:Manufacturer-owned outlet stores and catalog operations serve rural and exurban markets with limited third-party retail penetration across Australia, Canada, and the American Midwest.
Brick-and-mortar stores command the established base. Online retail is gaining share fastest as compressed delivery models and trial-period guarantees reset consumer expectations for purchase risk and fulfillment speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cotton bedding commands pricing power in the United States that Egyptian and Portuguese suppliers cannot replicate in saturated European markets. German and French buyers drive sustainability premiums through carbon footprint labeling mandates. Indian and Chinese manufacturers compete on compressed delivery economics for direct-to-consumer brands.
United States
Direct-to-consumer mattress brands and luxury linen startups capture share from department store channels through trial-period guarantees. EPA volatile organic compound guidelines constrain foam pouring operations in North Carolina and California manufacturing clusters. Dallas and Los Angeles logistics hubs coordinate white-glove installation networks for compressed delivery models.
Germany
REACH chemical restrictions and EU Green Deal recycled content thresholds reshape material sourcing for cotton and linen producers. ECHA compliance timelines extend product launch schedules for new fabric formulations. Hamburg and Munich retail buyers concentrate procurement of OEKO-TEX-certified organic bedding for nursery and residential segments.
China
Polyester microfiber volume production serves North American hospitality chains seeking 200-wash lifecycle guarantees. MEE environmental standards tighten wastewater discharge requirements for dye houses in Zhejiang and Jiangsu provinces. Nantong and Shaoxing textile clusters retrofit finishing facilities to meet export market certification demands.
India
Organized mattress distribution remains concentrated in Mumbai, Delhi, and Bangalore tier-1 cities. BIS quality standards and DGFT export incentives support cotton bedding manufacturing scale-ups in Tamil Nadu and Gujarat. Tier-2 urban centers in Pune and Hyderabad present accessible expansion corridors for localized supply chain builders.
Portugal
Artisanal quilting and tufting craftsmanship for high-thread-count finishing faces generational talent scarcity in Guimarães and Vila Nova de Famalicão industrial zones. EU Green Deal textile strategy mandates accelerate investment in bio-based flame retardants and natural dye processes. Porto-based dye houses consolidate supply agreements with Dutch and Belgian retail buyers facing recycled content mandates.
Bedding Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the bedding market. Consolidated foam and spring manufacturers with captive raw material supply compete against agile direct-to-consumer brands with asset-light fulfillment networks. Three archetypes dominate: vertically integrated material producers, digitally native vertical brands, and artisanal craft specialists. Competitive moves concentrate on backward integration into foam pouring and cotton ginning, plus compressed delivery capability buildouts.
Among North American manufacturers, Tempur Sealy International exemplifies the vertically integrated archetype with in-house foam production and retail distribution control. Serta Simmons Bedding anchors the scale-driven wholesale and hospitality supply tier across North American plant networks. Sleep Number Corporation occupies the technology-specialist position through adjustable air-chamber systems commanding premium pricing in personalized sleep segments.
| Leading Market Players |
|---|
| Tempur Sealy International |
| Serta Simmons Bedding |
| Sleep Number Corporation |
| Casper Sleep |
| Boll & Branch |
| Brooklinen |
| Parachute Home |
| Hollander Sleep Products |
| Kingsdown |
| Others |
Supply Flow & Price Mechanics
Polyester microfiber substitution for Egyptian long-staple cotton in hospitality procurement simultaneously shifts supply geography toward Vietnamese and Chinese manufacturing clusters and compresses pricing economics across institutional bedding tiers. This material displacement rewards producers with captive petrochemical feedstock access while penalizing premium cotton spinners dependent on Nile Delta sourcing.
Pricing Analysis
The customization-premium spread between configured-to-order adjustable sleep systems and standard foam mattresses spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade—OEKO-TEX and GOTS tiers command retail placement premiums—and volume scale, where hospitality procurement aggregators extract 15-20 point discounts through multi-year offtake commitments. Cost compression in economy foam tiers is intensifying because petrochemical input volatility resists standard hedging instruments. Healthcare and educational buyers exhibit highest price sensitivity due to budget-constrained procurement cycles, while luxury residential segments demonstrate lowest elasticity driven by bridal registry and first-time homebuyer prestige signaling.
Supply Chain Analysis
Just-in-time inventory strategies dominate direct-to-consumer compressed delivery models, while strategic stockpiling of Egyptian long-staple cotton and Hungarian goose down persists among European artisanal producers hedging climate and currency exposure. Geographic supply concentrates in China, Vietnam, and India for polyester microfiber and cotton ginning operations, with Portugal and Italy anchoring high-thread-count finishing. Raw material dependencies rest on propylene oxide and TDI for polyurethane foam, Nile Delta long-staple cotton, and Belgian flax for linen production. Single-origin cotton concentration around the Nile Delta creates tariff-exposed vulnerability for premium bedding manufacturers. Distribution runs through Dallas and Los Angeles logistics hubs coordinating white-glove installation networks for direct-to-consumer brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bedding market fragmentation creates entry corridors as direct-to-consumer channel shift dismantles department store gatekeeper power and splinters demand across specialized thermal regulation and sustainability-positioned niches.
For Market Incumbents: Consolidate backward integration into foam pouring operations and captive cotton ginning to defend margin position against petrochemical volatility and single-origin supply concentration. Tempur Sealy's vertical integration model demonstrates margin capture control; Serta Simmons must replicate this across North American plant networks or cede wholesale pricing power to compressed delivery entrants. Prioritize OEKO-TEX certification investment to maintain European retail access under EU Green Deal recycled content mandates. For New Entrants and Emerging Players: Anchor in tier-2 Indian urban centers—Pune, Hyderabad, Chennai—where organized mattress distribution remains underpenetrated and localized supply chains face limited legacy competition. Target sleep tracking convergence as the most penetrable premium tier, integrating biometric sensors with adjustable air-chamber systems to command pricing power in United States and German residential segments. Deploy mobile-optimized platforms with 100-night trial guarantees as the primary go-to-market angle, displacing brick-and-mortar showroom dependency. For Investors and Strategic Acquirers: EU Green Deal textile strategy implementation reshapes the acquisition landscape toward certified circular material flow operators with established bio-based flame retardant and natural dye process capabilities. Five-to-ten year viability favors manufacturers with REACH-compliant chemistry infrastructure and hospitality supply agreement backlogs from Marriott, Hilton, and Accor renovation cycles. Target acquisition archetype: mid-cap Portuguese or Italian artisanal producers with generational craft scarcity but underdeveloped direct fulfillment capabilities. Watch OEKO-TEX certification timeline compression as the signal indicating regulatory compliance moat widening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Production | Captive polyurethane supply insulates Tempur Sealy from propylene oxide volatility. |
| Certified Circular Material Flow Buildout | EU Green Deal recycled content mandates reward early bio-based flame retardant adopters. |
| Direct-to-Consumer Platform Launch | Casper Sleep's compressed delivery model displaced department store channel dominance. |
| Sleep Tracking Technology Integration | Biometric sensor convergence opens premium pricing tiers in German and US markets. |
| Hospitality Supply Agreement Consolidation | Marriott and Hilton renovation programs pull specialized linen suppliers into long-term contracts. |
Methodological Framework
Initial hypotheses were tested against primary input from hospitality procurement directors, textile plant managers, direct-to-consumer brand operations leads, and mattress retail category buyers and refined through secondary validation against customs trade records, EPA emission disclosure filings, OEKO-TEX certification databases, and EU ECHA regulatory submissions. Bottom-up demand modeling across residential, hospitality, healthcare, and educational end-use segments triangulated with top-down macroeconomic indicators.
Variance decomposition across product type, material certification tier, distribution channel, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand buildups incorporating hospitality renovation cycle timing, REACH compliance cost pass-through assumptions, and compressed delivery model penetration trajectories. Industry-specific forecast inputs included Egyptian cotton harvest yield volatility and petrochemical feedstock price correlation matrices.
Material uncertainties—climate disruption to Nile Delta cotton cultivation, EU Green Deal enforcement intensity, and extended producer responsibility framework adoption rates—sit outside the modeled envelope. Forecasts reflect assumptions documented in segmentation and regional sections without guarantee of realization. Revision becomes warranted when REACH chemical restriction scope expansion or mattress recycling infrastructure deployment crosses thresholds altering manufacturer cost structure or regional location decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Children Mattress Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Bunk Beds Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Home Bedding Market