
 Queen Mattress Market | 2026-2036
Queen Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Queen Mattress Market Analytics
Southeast Asian manufacturing capacity is fragmenting as Vietnam and Indonesia add cut-and-sew assembly lines for foam and coil systems. Tempur Sealy International leverages its vertically integrated U.S. foam pouring operations to sustain margin control. Serta Simmons Bedding anchors wholesale relationships with national furniture chains. Sleep Number competes through its adjustable air-chamber technology, occupying a distinct premium positioning.
A queen mattress measures 60 inches by 80 inches and functions as a standardized sleep surface engineered from layered polyurethane foam, steel pocketed coils, latex rubber, or hybrid combinations to provide spinal alignment and pressure relief for residential and commercial sleeping quarters. Memory foam and hybrid constructions now lead product type demand as consumers prioritize motion isolation and cooling gel infusions. The e-commerce platform customer segment is expanding fastest, though furniture retailers still control the majority of offline volume and capture higher attachment rates for adjustable bases.
The U.S. Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1633, while CertiPUR-US and OEKO-TEX restrict volatile organic compound emissions in polyurethane foams. The EU REACH regulation governs chemical substances in latex and adhesive layers exported to European markets. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York that will reshape end-of-life collection logistics.
Market Dynamics
CertiPUR-US emission standards are forcing polyurethane foam reformulation across North American manufacturing, compressing margins for non-compliant suppliers while creating certification premiums for early adopters.
Growth Catalysts
- Residential construction concentration:Sun Belt metropolitan areas in the United States are generating sustained demand for queen mattress units tied to new housing completions.
- 16 CFR Part 1633:U.S. flammability mandates are accelerating replacement cycles as older inventory fails compliance checkpoints.
- Cooling gel infusion technology:Memory foam systems with temperature regulation are capturing preference share from traditional innerspring constructions.
Market Restraints
- Polyol and TDI volatility:Petrochemical feedstock price swings compress foam pouring margins and destabilize contract pricing.
- Southeast Asian supply concentration:Vietnam and Indonesia assembly line expansion creates geopolitical exposure and shipping cost sensitivity.
- Steel coil import dependencies:Pocketed spring systems rely on concentrated offshore metal sourcing subject to tariff friction.
Strategic Opportunities
- Extended producer responsibility frameworks:California and New York mattress recycling mandates will reshape end-of-life logistics and create service revenue streams.
- E-commerce direct fulfillment:Compressed roll-pack shipping is opening geographic white space beyond traditional furniture retail territories.
- Adjustable base convergence:Smart bed technology integration with sleep tracking hardware is creating premium bundle economics.
Industry Challenges
- CertiPUR-US testing timelines:Laboratory validation bottlenecks delay product launches and freeze inventory commitments.
- Skilled foam pouring technician scarcity:Chemical process expertise gaps constrain capacity expansion at domestic pouring facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Queen Mattress Market |
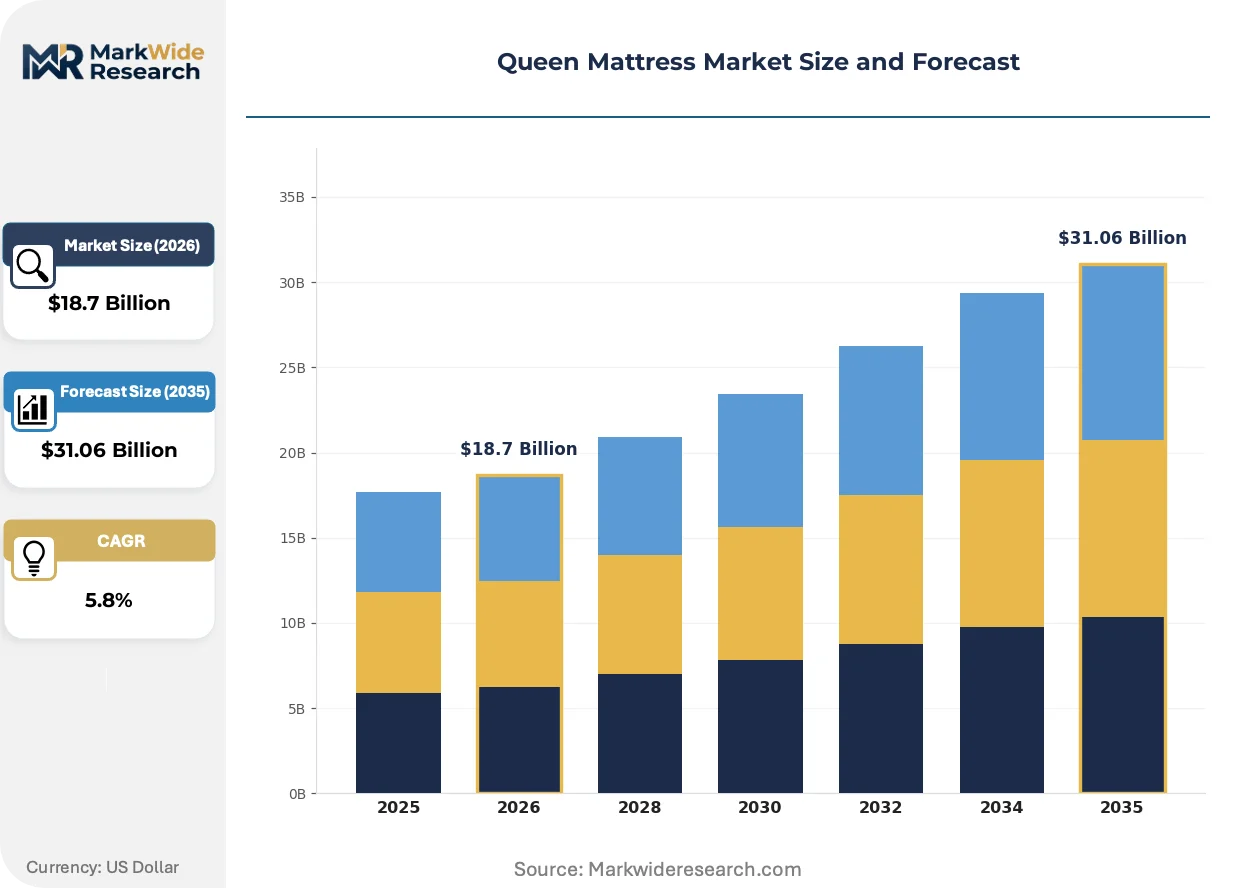
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid Customer Type: Individual Consumers, Hotels, Furniture Retailers, E-commerce Platforms Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Tempur Sealy International, Inc., Serta Simmons Bedding LLC, Sleep Number Corporation, Casper Sleep Inc., Kingsdown, Inc., Spring Air International, Paramount Bed Holdings Co., Ltd., Sheela Foam Ltd., Grupo Pikolin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Queen Mattress Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are simultaneously compressing legacy formulations and opening premium positioning for compliant alternatives.
Phase-change material coatings with graphite particle dispersion are rendering obsolete conventional memory foam constructions that trap body heat. Hospitality procurement teams are specifying these systems for guest room renovations at accelerated replacement cadences. The shift is compressing demand for basic polyurethane slabs while expanding margin capture at the performance tier.
REACH substance restrictions on latex and adhesive chemistry are forcing European export compliance investments from Asian manufacturers. Reformulation costs are filtering supplier bases to larger chemical systems houses with dedicated regulatory affairs functions. EU-bound hybrid mattress shipments now concentrate through vertically integrated producers with captive polymer laboratories.
Direct-to-consumer compressed shipping is fragmenting traditional furniture retail gatekeeper control over mattress distribution. Urban apartment dwellers without vehicle access are bypassing store visits entirely for doorstep delivery of roll-packed units. This channel rotation is most visible in United States coastal metropolitan markets with high rental turnover rates.
Queen Mattress Market Segmentation
Queen mattress procurement cycles vary dramatically by segment, with hospitality fleets turning every 5-7 years while residential replacement stretches toward decade intervals. Understanding these velocity differentials shapes inventory planning and margin capture strategies across the value chain.
Product Type:
Replacement cadence divides sharply between commodity constructions with shorter lifespans and performance-engineered systems commanding extended duty cycles.
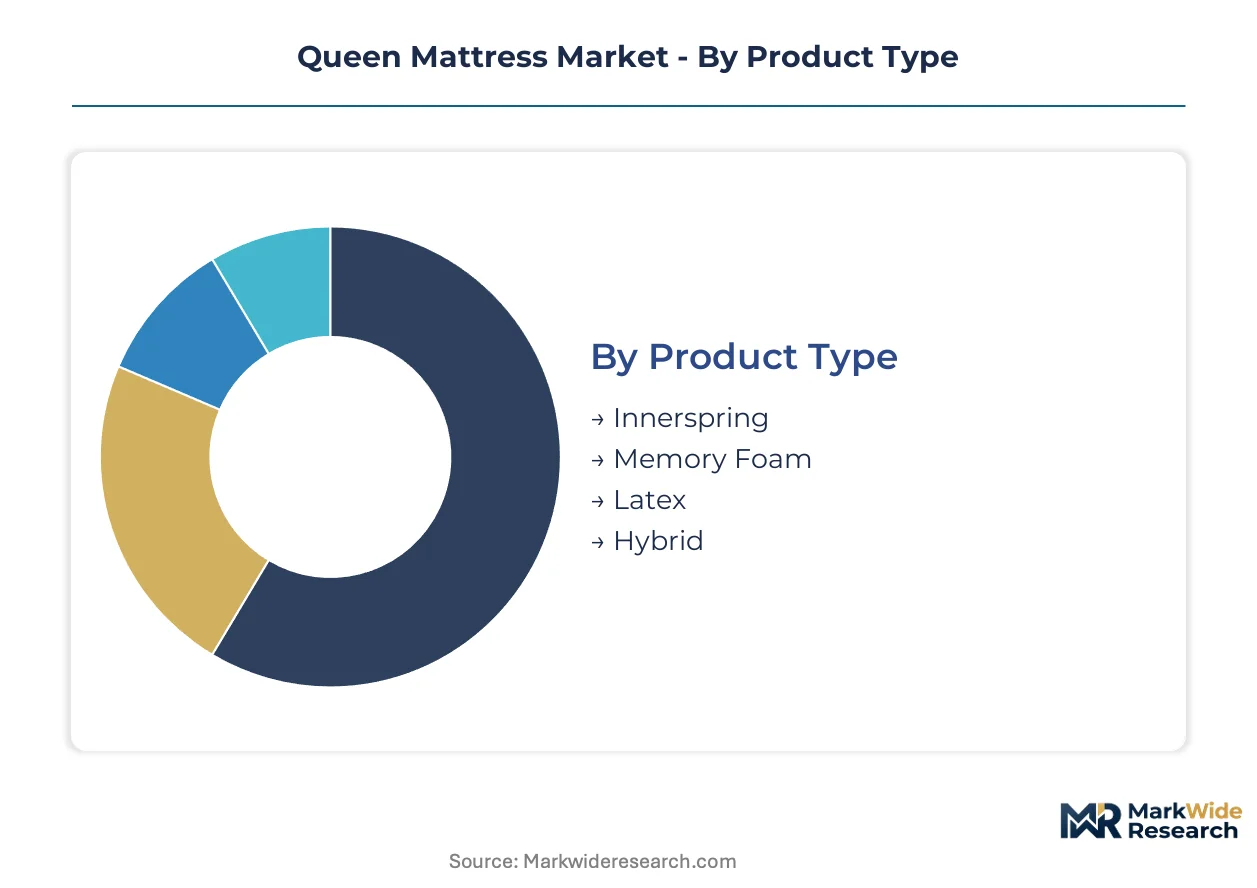
- Memory Foam:Viscoelastic polyurethane formulations with open-cell architecture deliver pressure point relief and motion isolation. Demand concentrates in United States Sun Belt metropolitan areas where residential construction activity is elevating new household formation. Cooling gel infusions are displacing basic formulations as temperature regulation becomes a non-negotiable specification.
- Hybrid:Layered systems combining steel pocketed coils with foam comfort layers balance responsiveness with contouring support. Hospitality procurement teams are specifying these for accelerated replacement programs in guest room renovation cycles. The construction commands price premiums while reducing long-term warranty exposure through component redundancy.
- Innerspring:Traditional Bonnell and offset coil systems with linked wire construction remain the lowest-cost installed base across budget furniture retail channels.
- Latex:Natural and synthetic rubber foam derived from either Hevea brasiliensis sap or styrene-butadiene polymerization serves allergen-sensitive and eco-positioned segments.
Memory Foam dominates installed base. Hybrid is where expansion concentrates.
Customer Type:
Volume concentration versus margin extraction splits across buyer categories with fundamentally different procurement behaviors and technical specifications.
- E-commerce Platforms:Direct-to-consumer compressed roll-pack fulfillment bypasses traditional furniture retail gatekeepers. Urban apartment dwellers in coastal United States markets with high rental turnover are driving this channel's steepest expansion trajectory. The format eliminates vehicle ownership requirements and enables doorstep delivery without scheduling constraints.
- Hotels:Hospitality procurement teams operate on standardized replacement cycles with bulk volume commitments and white-label customization requirements. CertiPUR-US compliance is becoming a mandatory specification in North American property portfolios. Extended producer responsibility frameworks in California and New York are adding reverse logistics complexity to fleet management.
- Individual Consumers:Residential purchasers through brick-and-mortar furniture retailers still control majority offline volume and capture higher attachment rates for adjustable bases.
- Furniture Retailers:Multi-brand showroom operators anchor wholesale relationships with national chains and regional independents.
Individual Consumers anchor volume throughput. E-commerce Platforms is where margin compression and growth velocity coincide.
Distribution Channel:
Channel economics separate by inventory carrying cost, return handling complexity, and geographic reach constraints.
- Online Retail:Third-party marketplace listings and proprietary brand storefronts enable compressed shipping logistics without physical showroom overhead. United States coastal metropolitan markets with dense apartment housing show highest penetration. Return logistics costs remain the primary profitability constraint.
- Offline Retail:Furniture showroom and department store floor space delivers tactile evaluation and same-day takeaway options. The channel captures premium pricing through salesperson attachment of adjustable bases and protection plans.
- Direct Sales:Manufacturer-owned stores and factory-direct outlets eliminate wholesale margin stacking.
- Wholesale:Business-to-business bulk supply to hospitality, healthcare, and institutional sleep quarters operates on contract pricing with extended payment terms.
Offline Retail dominates transaction value per unit. Online Retail is where geographic white space conversion occurs fastest.
Price Tier:
Certification premiums and material science differentiation are compressing the mid-range while polarizing volume toward entry and performance extremes.
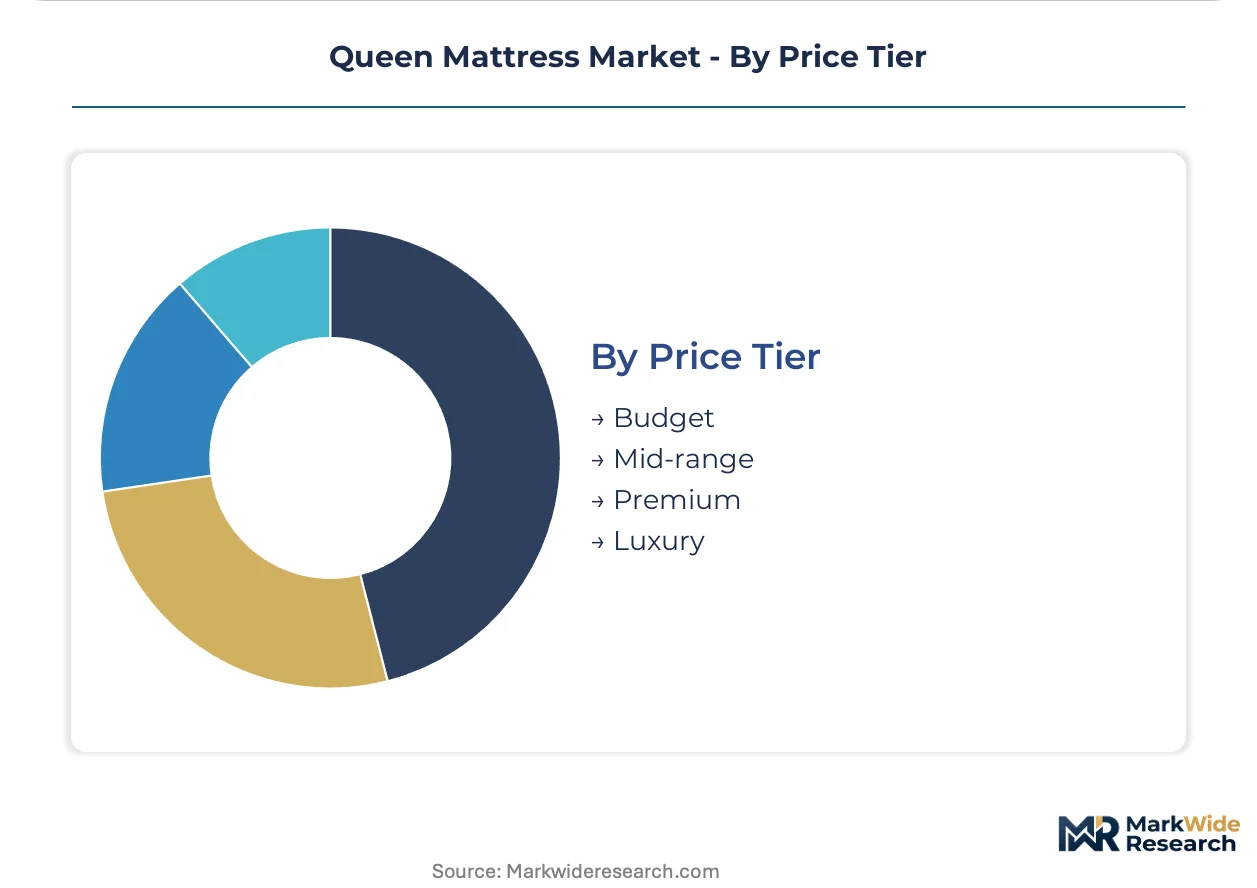
- Premium:Phase-change material coatings with graphite particle dispersion and zoned coil systems target sleep quality optimization. REACH substance restrictions on latex and adhesive chemistry are filtering supplier bases to larger chemical systems houses with dedicated regulatory affairs functions.
- Mid-range:CertiPUR-US certified polyurethane foam constructions with basic cooling treatments serve the mass-market replacement cycle. The tier faces margin pressure from reformulation costs and testing timeline delays.
- Budget:Basic polyurethane slab constructions without certification premiums serve price-sensitive first-time purchasers and secondary bedroom applications.
- Luxury:Hand-tufted natural latex, organic cotton covers, and artisan coil systems command positioning in design-focused retail environments.
Mid-range captures the widest demographic spread. Premium is where material science investment converts to margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential construction intensity varies sharply across geographies, with Sun Belt metropolitan areas in the United States consuming queen mattresses primarily for new household formation while European markets emphasize replacement cycles and regulatory compliance upgrades.
United States
Sun Belt metropolitan areas including Phoenix, Dallas, and Atlanta are driving new residential construction demand for queen mattress units. The U.S. Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1633, accelerating replacement cycles for non-compliant inventory. California and New York are implementing extended producer responsibility frameworks that will reshape end-of-life collection logistics for mattress fleets.
Germany
German consumers prioritize ergonomic sleep systems with certified material compositions for residential replacement cycles. The EU REACH regulation governs chemical substances in latex and adhesive layers, filtering supplier bases to larger chemical systems houses with dedicated regulatory affairs functions. Industrial clusters in North Rhine-Westphalia concentrate polyurethane foam pouring operations serving EU-bound hybrid mattress shipments.
China
Urban apartment dwellers in coastal metropolitan markets are adopting compressed roll-pack delivery formats for queen mattress procurement. The Ministry of Ecology and Environment enforces dual carbon goals that constrain petrochemical feedstock availability for polyurethane production. Manufacturing capacity in the Yangtze River Delta region is fragmenting as domestic brands expand cut-and-sew assembly lines for foam and coil systems.
Japan
Japanese consumers demonstrate preference for compact sleep surfaces suited to smaller residential footprints in dense urban environments. METI oversees industrial standards alignment with international flammability and emissions protocols. The Kansai region around Osaka anchors domestic assembly operations for hybrid constructions combining steel pocketed coils with foam comfort layers.
India
First-time homebuyers in metropolitan areas are expanding demand for mid-range queen mattress constructions as residential real estate development accelerates. The Bureau of Indian Standards maintains voluntary certification frameworks for mattress safety and durability. Industrial corridors in Maharashtra and Gujarat are attracting foam pouring investments to serve domestic replacement cycles and hospitality procurement.
Queen Mattress Market Competitive Landscape
Capability concentration sits with vertically integrated foam pouring specialists; scale advantage sits with wholesale-anchored national brands. The market structure divides between chemical systems houses controlling polymer formulations and assembly-focused brands managing retail distribution relationships. Three archetypes dominate: captive foam producers with laboratory-grade reformulation capacity, wholesale-anchored furniture chain suppliers, and direct-to-consumer compressed shipping specialists. Competitive moves center on certification compliance investments and e-commerce fulfillment infrastructure expansion.
Among U.S.-based integrated producers, Tempur Sealy International, Inc. exemplifies the captive foam pouring archetype, while Serta Simmons Bedding LLC occupies a position within wholesale-anchored national distribution. Sleep Number Corporation represents the adjustable technology specialization tier, competing through distinct premium positioning rather than commodity foam formulations.
| Leading Market Players |
|---|
| Tempur Sealy International, Inc. |
| Serta Simmons Bedding LLC |
| Sleep Number Corporation |
| Casper Sleep Inc. |
| Kingsdown, Inc. |
| Spring Air International |
| Paramount Bed Holdings Co., Ltd. |
| Sheela Foam Ltd. |
| Grupo Pikolin |
| Others |
Value Network & Pricing Analysis
Overcapacity in Southeast Asian cut-and-sew assembly is compressing contract pricing for foam and coil systems while simultaneously eroding supplier bargaining power across North American procurement desks. This utilization imbalance rewards vertically integrated domestic pourers with captive polymer operations and punishes non-certified suppliers facing reformulation cost spikes.
Pricing Analysis
Long-term offtake agreements dominate hospitality fleet procurement, locking in volume commitments through 5-7 year replacement cycles with white-label customization premiums. Price differentiation rests on CertiPUR-US certification grade and cooling gel infusion technology tier, with compliant systems commanding measurable premiums over basic polyurethane slabs. Pricing pressure stems from polyol and TDI feedstock volatility destabilizing foam pouring margins. Budget-tier individual consumers exhibit highest price sensitivity, while hospitality procurement teams prioritize warranty exposure reduction over unit cost minimization.
Supply Chain Analysis
Tariff exposure between Vietnam and the United States dominates supply chain risk calculus for pocketed coil sourcing, forcing manufacturers toward dual-country qualification strategies. Geographic supply concentration centers on Vietnam, Indonesia, and China for cut-and-sew assembly, with steel coil dependencies anchored in offshore metal sourcing. Raw material inputs draw from petrochemical feedstocks, natural latex from Hevea brasiliensis cultivation, and graphite particle dispersions for phase-change coatings. Distribution runs through compressed roll-pack direct fulfillment opening geographic white space beyond traditional furniture retail territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cooling gel infusion technology is accelerating replacement cadences and fragmenting traditional innerspring demand, creating a high-growth disruption window for compliant foam systems. This regulatory-cum-technology inflection compresses legacy formulation margins while opening premium positioning for certified alternatives.
For Market Incumbents: Insulate margin position through backward integration into captive foam pouring operations and accelerated CertiPUR-US laboratory capacity investments. Direct-to-consumer compressed shipping specialists threaten wholesale-anchored furniture chain relationships, demanding defensive e-commerce fulfillment infrastructure buildout. Prioritize polymer laboratory reformulation capacity to outpace testing timeline bottlenecks constraining competitor product launches.
For New Entrants and Emerging Players: Establish a beachhead in extended producer responsibility service revenue streams as California and New York mattress recycling mandates reshape end-of-life logistics. Urban apartment dwellers in coastal United States markets with high rental turnover represent the most penetrable consumer archetype, bypassing vehicle ownership requirements entirely. Deploy proprietary adjustable base convergence technology with sleep tracking hardware integration to capture premium bundle economics absent from commodity foam competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid construction manufacturing as REACH compliance investments and dedicated regulatory affairs functions filter supplier bases to larger chemical systems houses. Five-to-ten year viability favors vertically integrated producers with captive polymer laboratories over assembly-focused brands managing retail distribution relationships. Monitor extended producer responsibility framework implementation velocity as the critical signal for service revenue stream emergence timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Compliance Investment | CertiPUR-US laboratory capacity locks in premium positioning ahead of regulatory enforcement acceleration. |
| Direct-to-Consumer Channel Expansion | Compressed roll-pack fulfillment opens geographic white space beyond furniture retail gatekeeper control. |
| Backward Integration into Foam Pouring | Captive polymer operations insulate margins from polyol and TDI feedstock volatility swings. |
| Extended Producer Responsibility Services | California and New York recycling mandates create recurring revenue streams from reverse logistics. |
| Smart Bed Technology Convergence | Sleep tracking hardware integration with adjustable bases captures premium bundle economics. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with foam pouring technicians, hospitality procurement managers, furniture retailer category buyers, and e-commerce logistics directors; and secondary validation through U.S. Consumer Product Safety Commission flammability filings, CertiPUR-US certification databases, customs trade records, and SEC 10-K disclosures from vertically integrated manufacturers. Bottom-up unit economics triangulated against top-down construction completion data across Sun Belt metropolitan areas.
Forecast inputs considered product type segmentation across memory foam, hybrid, innerspring, and latex constructions; customer type splits between e-commerce platforms, hospitality fleets, individual consumers, and furniture retailers; and distribution channel dynamics spanning online retail, offline retail, direct sales, and wholesale. CAGRs were derived from replacement cycle velocity differentials and regulatory-driven inventory refresh patterns. Phase-change material adoption curves and extended producer responsibility implementation timelines served as industry-specific demand modifiers across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in residential construction permitting rates, petrochemical feedstock pricing, or tariff enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline standardization and recycling infrastructure buildout pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Wall Bed Market