
 Middle East and Africa Fermented Ingredients Market | 2026-2036
Middle East and Africa Fermented Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Fermented Ingredients Market Foresight
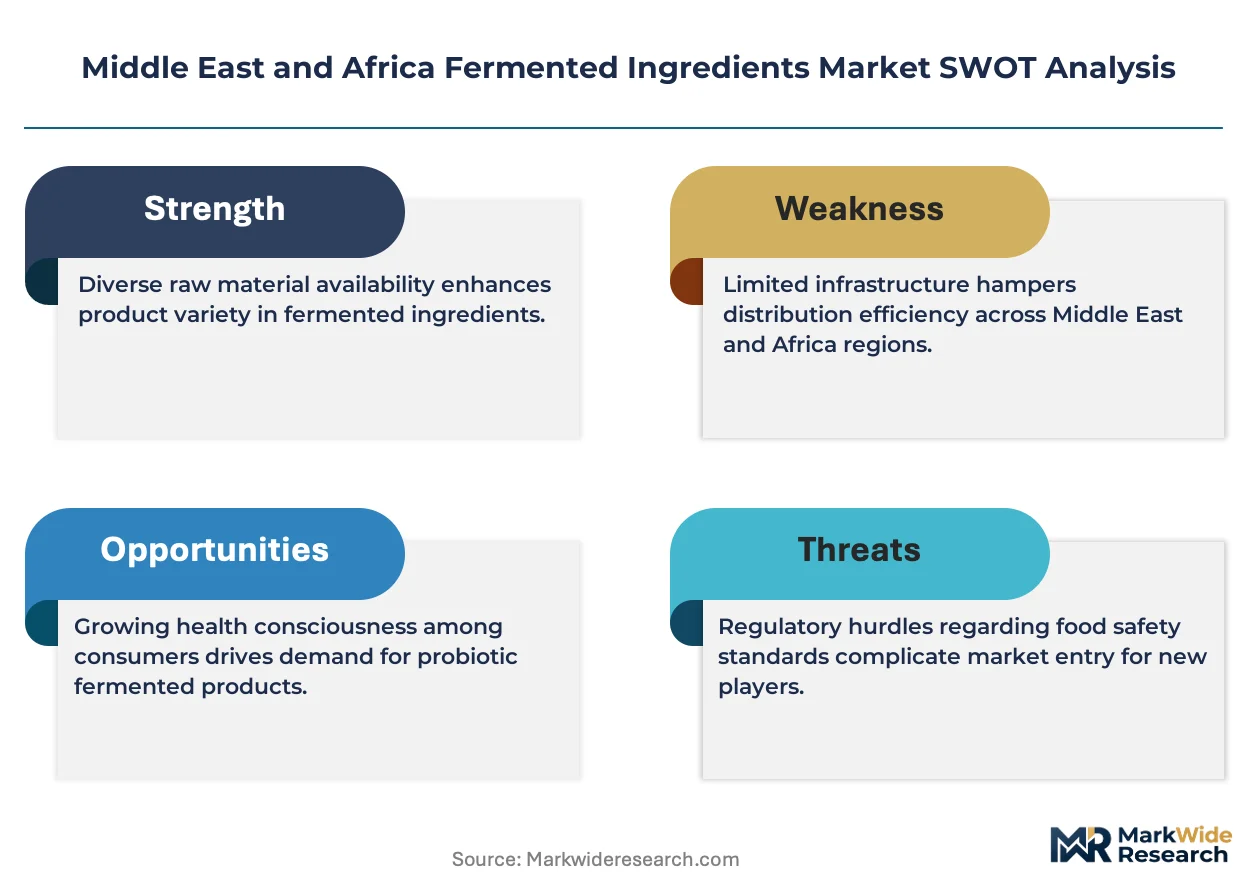
Precision fermentation is narrowing the cost gap between bio-based and chemically synthesized active ingredients across pharmaceutical and nutrition applications. DSM Nutritional Products leverages its strain development capabilities to anchor high-value probiotic supply chains in the region. Chr. Hansen competes through specialized dairy culture portfolios calibrated for ambient-temperature distribution networks common in Gulf markets. BASF SE extends its industrial enzyme reach through partnerships with local distributors serving North African food processors.
Fermented ingredients comprise metabolically active or inactivated microbial biomass, enzymes, organic acids, and amino acids produced through controlled submerged or solid-state fermentation processes, typically requiring pH ranges of 4.5 to 7.0 and temperatures between 28°C and 37°C for optimal cell viability. These inputs serve as functional catalysts, preservation agents, nutritional enhancers, or texturizing components across food, pharmaceutical, and industrial formulations. Yeast dominates volume flows into regional baking and brewing operations where Saccharomyces cerevisiae strains remain the workhorse organism. Probiotics command premium positioning within dietary supplement channels as Gulf consumers expand spending on gut-health formulations. Enzymes sustain margin pools in dairy processing, where rennet and lactase applications support cheese and lactose-free product lines.
South Africa's Department of Health enforces food additive regulations aligned with Codex Alimentarius standards, while the Saudi Food and Drug Authority applies Gulf Standardization Organization specifications for microbial culture safety and labeling. These frameworks shape import documentation burdens, strain qualification timelines, and clean-label claim permissibility for manufacturers entering Middle East and Africa markets. Stakeholders must monitor evolving halal certification requirements for fermentation media and downstream processing aids, as religious compliance increasingly functions as a non-tariff gate for regional market access rather than a voluntary product attribute.
Market Dynamics
Precision fermentation infrastructure is compressing production economics for high-value bioactives, while Gulf Standardization Organization harmonization accelerates cross-border strain registration and reduces regulatory duplication costs for suppliers.
Growth Catalysts
- Halal certification standardization:Gulf Standardization Organization unified protocols for fermentation media and processing aids eliminate redundant testing burdens, accelerating product launches across Saudi Arabia, UAE, and Kuwait.
- Dairy culture demand:Ambient-temperature distribution networks in Gulf markets drive specialized thermotolerant strain development for yogurt and cheese applications.
- South Africa:Established brewing and dairy processing infrastructure anchors domestic enzyme and yeast consumption, reducing import dependency for regional food manufacturers.
Market Restraints
- Strain qualification timelines:Saudi Food and Drug Authority documentation requirements extend import approval cycles, delaying market entry for novel microbial cultures.
- Energy input volatility:Submerged fermentation's thermal and agitation demands expose producers to electricity price swings in import-dependent Gulf economies.
- Technical limitation:Solid-state fermentation scale-up remains constrained by heat and mass transfer heterogeneity, limiting regional amino acid production capacity.
Strategic Opportunities
- Egyptian food processing:Underdeveloped domestic enzyme production creates white space for toll manufacturing partnerships serving North African bakery and confectionery sectors.
- Probiotic supplements:Gut-health spending expansion among Gulf consumers opens premium positioning for multi-strain formulations with ambient stability claims.
- Clean-label permissibility:Evolving Codex Alimentarius-aligned additive regulations in South Africa enable natural preservation claims that command shelf price premiums.
Industry Challenges
- Halal supply chain verification:Fermentation media sourcing documentation requires traceability systems that many regional distributors lack, creating compliance bottlenecks.
- Specialized technician scarcity:Strain maintenance and bioreactor operation skills concentrate in South Africa and Gulf urban centers, constraining facility expansion in secondary markets.
- Legacy system integration:North African dairy processors face retrofit costs when connecting automated culture dosing to existing batch processing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Fermented Ingredients Market |
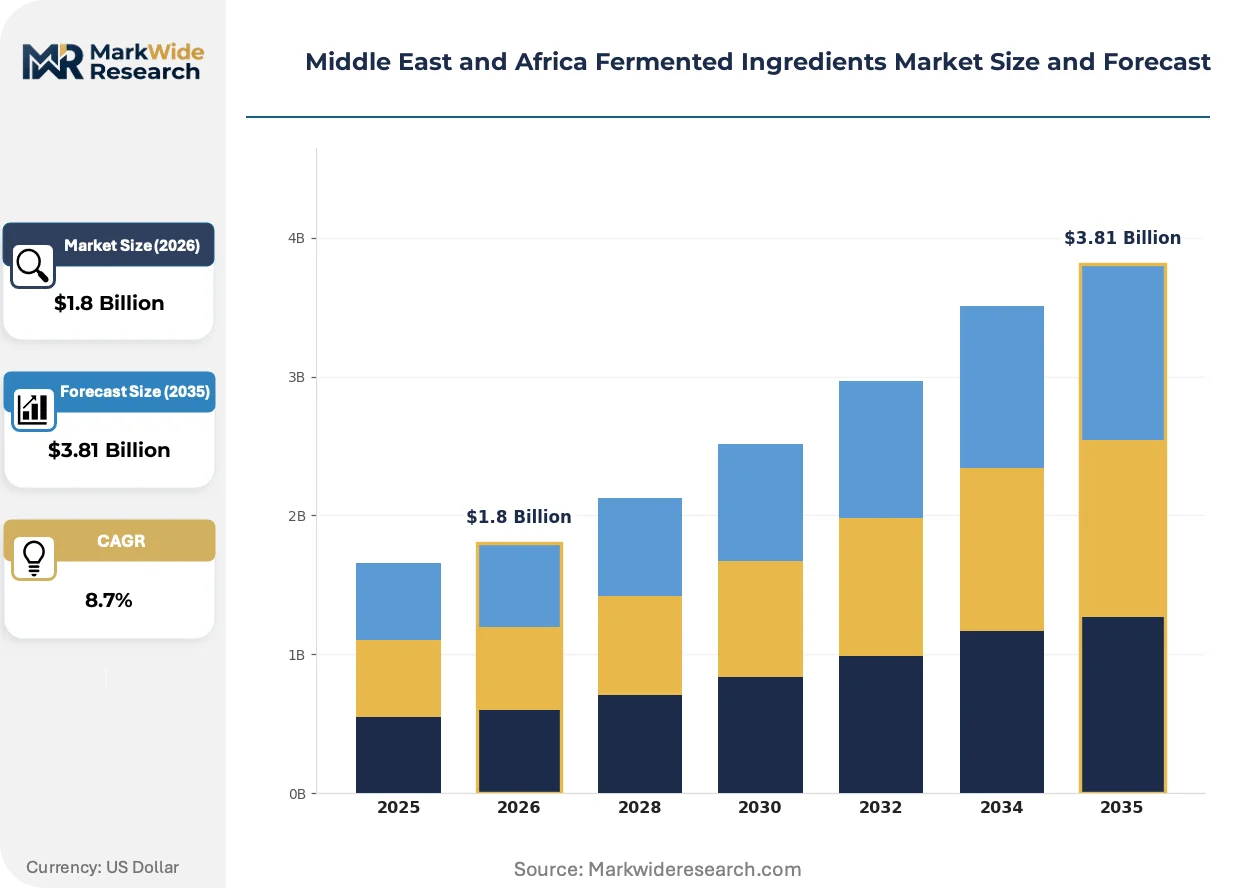
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast, Bacteria, Enzymes, Probiotics Application: Dairy Products, Beverages, Bakery, Nutrition End User: Food Industry, Beverage Industry, Pharmaceuticals, Dietary Supplements Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | BASF SE, Lonza Group, Döhler Group, Lesaffre, Evonik Industries AG, DSM Nutritional Products, Chr. Hansen, Novozymes, Archer Daniels Midland Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Fermented Ingredients Market Shifts & Advancements
Bioprocessing technology is narrowing cost gaps between fermentation-derived and synthetic ingredients, while regulatory harmonization and shifting procurement priorities reshape competitive positioning across the Middle East and Africa.
Precision fermentation platforms is migrating from pharmaceutical-grade amino acids toward commodity food ingredients, with regional contract manufacturers adopting single-use bioreactor systems to reduce sterilization energy costs. Food and beverage formulators in the Gulf are piloting these inputs for natural colorants and flavor precursors. The technology is migrating from high-value niche applications to mainstream bakery and beverage formulations, compressing price premiums for bio-based alternatives.
Gulf Standardization Organization microbial culture safety specifications are tightening strain documentation requirements for cross-border trade, forcing suppliers to consolidate qualification dossiers across Saudi Arabia, UAE, and Kuwait. Industrial consequence includes accelerated registration for pre-qualified strains and exclusion of novel organisms lacking Gulf-specific safety data. Dairy culture suppliers are responding by pre-positioning thermotolerant strain libraries in regional distribution hubs.
Ingredient buyers are consolidating supplier relationships around full-service fermentation houses capable of strain development, toll production, and regulatory filing support. Long-term offtake agreements are displacing spot purchasing for enzymes and probiotics in South African brewing and dairy processing. This concentration is most visible in Gulf markets, where multinational food manufacturers seek single-source accountability for halal compliance and supply security.
Middle East and Africa Fermented Ingredients Market Segmentation
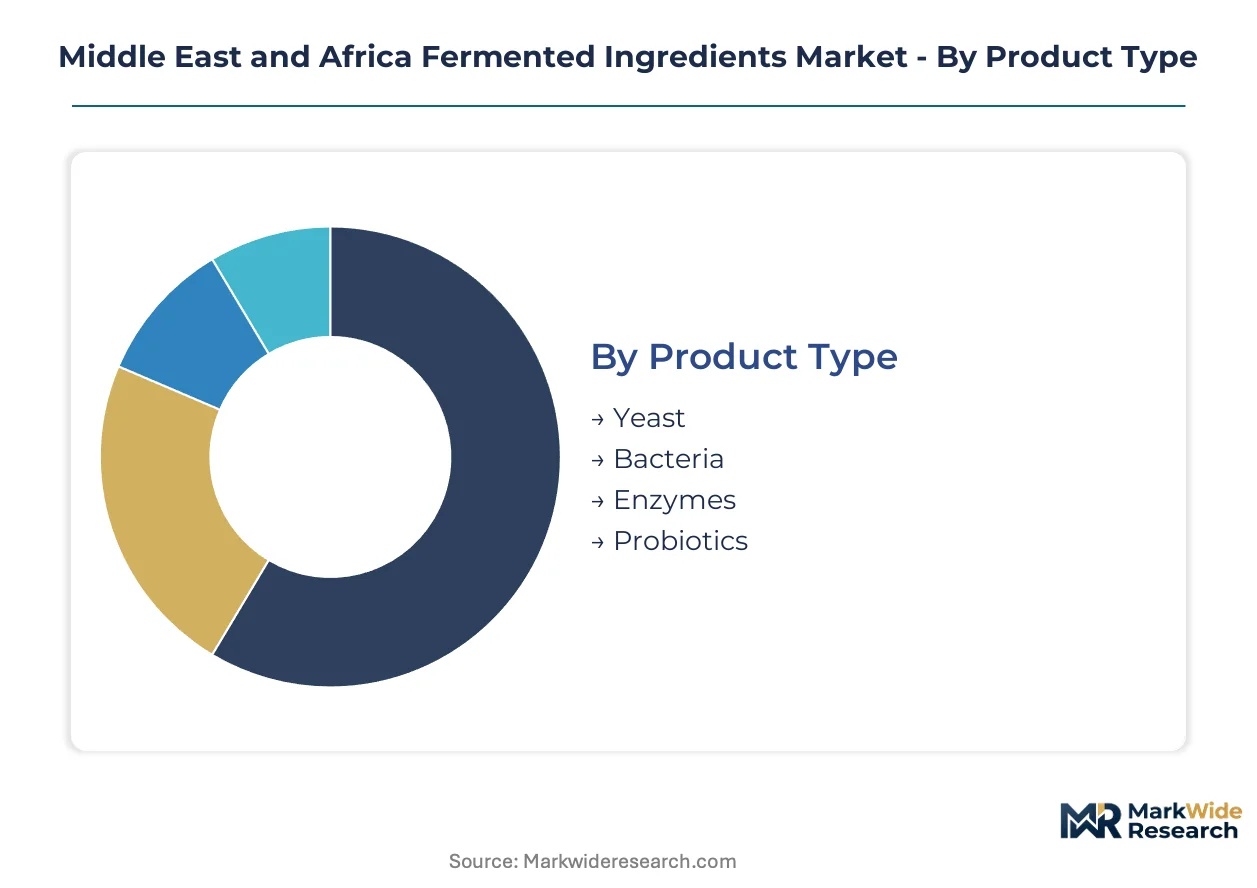
Segmentation reveals how fermentation-derived inputs map to distinct value pools across the Middle East and Africa. Product maturity, application requirements, and channel economics create divergent margin profiles that suppliers must navigate.
Product Type:
Mature commodity segments dominate volume flows, while emerging precision-fermentation platforms reshape high-value niches.
- Yeast:Saccharomyces cerevisiae strains constitute the foundational workhorse for regional baking and brewing operations. Demand concentrates in South African brewing facilities and Gulf bakery manufacturing clusters, where thermal tolerance specifications vary by ambient distribution requirements.
- Enzymes:Catalytic proteins including rennet, lactase, and amylase serve as processing aids with defined activity units per gram. Dairy processors across Saudi Arabia and Egypt drive procurement volumes for cheese-making and lactose-free milk lines, though import dependency remains elevated for specialty proteases.
- Bacteria:Starter cultures for fermentation initiation span Lactobacillus and Streptococcus genera with pH tolerance ranges of 4.0-6.5. North African dairy processors leverage these inputs for traditional fermented milk products with limited domestic strain development capacity.
- Probiotics:Live microbial formulations delivering defined colony-forming units at consumption. Gulf dietary supplement channels absorb premium-priced multi-strain products, with ambient stability claims commanding shelf price premiums in UAE and Kuwait pharmacy retail.
Yeast retains volume leadership; probiotics holds the steepest expansion curve.
Application:
End-use requirements split between high-volume commodity processing and specialized nutrition formulations with distinct certification burdens.
- Dairy Products:Fermented milk, cheese, and yogurt production consumes thermotolerant cultures engineered for ambient-temperature Gulf distribution networks. Saudi dairy cooperatives anchor regional demand, though Egyptian processors are expanding capacity for white cheese exports.
- Beverages:Alcoholic and non-alcoholic fermentation applications span brewing, kombucha, and functional drinks. South African brewing infrastructure supports domestic yeast propagation, while Gulf markets concentrate on non-alcoholic malt beverages with halal certification requirements.
- Bakery:Leavening agents and dough conditioners improve texture and shelf stability. Industrial bakeries in UAE and Morocco represent primary offtake, with artisanal segments in Tunisia and Lebanon requiring smaller batch sizes.
- Nutrition:Infant formula, clinical nutrition, and sports supplements incorporate fermented amino acids and vitamins. Precision fermentation platforms are compressing cost structures for bioactive ingredients previously sourced synthetically.
Dairy products anchor volume absorption; nutrition applications are climbing the fastest.
End User:
Customer scale determines procurement modality, with multinational food manufacturers consolidating supplier relationships around integrated service capabilities.
- Food Industry:Industrial bakeries, dairy cooperatives, and prepared food manufacturers constitute the largest collective offtake. Gulf-based multinationals increasingly demand single-source accountability for halal compliance documentation.
- Beverage Industry:Brewing conglomerates and soft drink bottlers require consistent strain performance at production scale. South African facilities maintain captive yeast propagation capabilities unavailable in secondary markets.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers leverage fermentation for antibiotic precursors and therapeutic proteins. Regulatory filing requirements through Saudi FDA and South African Health Products Regulatory Authority extend qualification timelines.
- Dietary Supplements:Capsule and powder formulators target gut-health positioning among Gulf consumers. Ambient stability specifications differentiate premium formulations from temperature-sensitive alternatives requiring cold chain logistics.
Food industry commands volume share; dietary supplements are expanding most quickly.
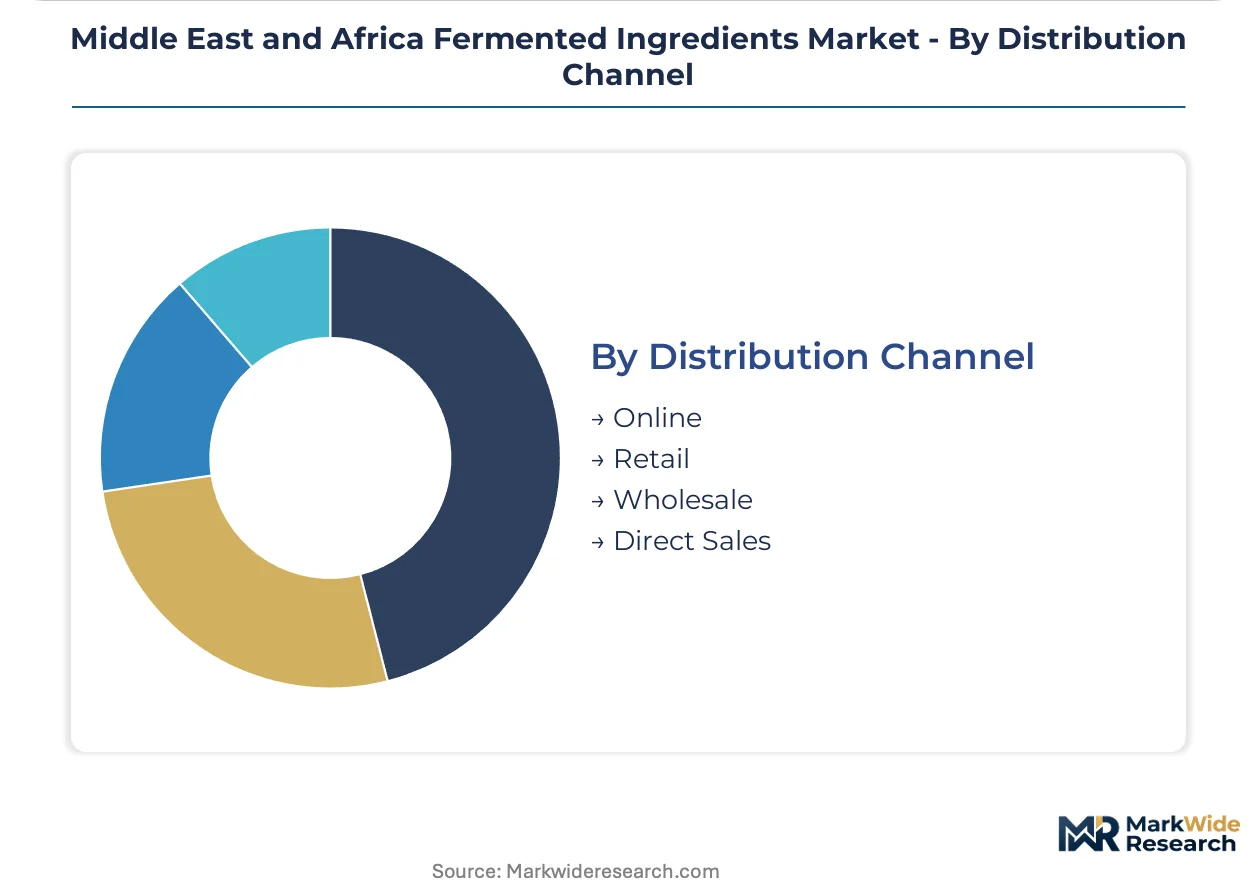
Distribution Channel:
Channel selection reflects customer technical sophistication and order scale, with direct relationships displacing intermediaries for strategic accounts.
- Direct Sales:Technical specialists negotiate long-term offtake agreements with multinational food and beverage manufacturers. Strain customization, regulatory filing support, and halal certification documentation bundle into contracted relationships.
- Wholesale:Regional distributors aggregate demand from mid-scale dairy processors and bakery operations. Inventory positioning in Jeddah, Durban, and Casablanca hubs reduces lead times for standard culture formulations.
- Retail:Pharmacy chains and specialty nutrition stores serve probiotic supplement consumers. UAE and Saudi Arabia pharmacy retail consolidation is concentrating shelf access for branded formulations.
- Online:E-commerce platforms penetrate dietary supplement and small-scale bakery ingredient segments. Direct-to-consumer channels remain limited for industrial-scale enzyme and culture procurement.
Direct sales retains volume leadership; online channels hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational food manufacturers concentrate procurement authority in Gulf urban centers, while South African processors retain captive fermentation capabilities unavailable elsewhere in the region.
Saudi Arabia
Dairy cooperatives and industrial bakeries anchor enzyme and culture consumption in Riyadh and Jeddah corridors. The Saudi Food and Drug Authority enforces Gulf Standardization Organization specifications for microbial strain registration, extending documentation timelines for novel organisms. The Eastern Province dairy cluster is expanding thermotolerant culture capacity for ambient-distribution yogurt exports.
United Arab Emirates
Pharmacy retail consolidation in Dubai and Abu Dhabi is absorbing premium-priced probiotic formulations with ambient stability claims. The Ministry of Health and Prevention applies halal certification protocols to fermentation media traceability systems. Dubai Industrial City hosts toll manufacturing partnerships serving Gulf bakery and beverage formulators.
South Africa
Brewing conglomerates and dairy processors in Gauteng and Western Cape provinces sustain domestic yeast propagation and enzyme blending operations. The Department of Health aligns food additive regulations with Codex Alimentarius standards, shaping import documentation burdens for novel strains. The Durban-Johannesburg logistics corridor positions inventory hubs for regional distribution into secondary African markets.
Egypt
White cheese exporters and industrial confectionery manufacturers in Cairo and Alexandria drive demand for imported dairy cultures and bakery enzymes. The country's national food safety regulator applies import licensing requirements that extend strain qualification timelines. The Nile Delta food processing belt is attracting toll manufacturing partnerships for North African bakery sector supply.
Kuwait
Pharmacy chains and dietary supplement distributors in Kuwait City concentrate demand for multi-strain probiotic formulations. The national standards body implements Gulf Standardization Organization harmonized protocols for cross-border culture trade. The Shuwaikh industrial zone is developing distribution infrastructure for ambient-stable fermentation-derived inputs.
Middle East and Africa Fermented Ingredients Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around full-service fermentation houses capable of strain development, toll production, and regulatory filing support. The vendor base fragments between multinational nutrition conglomerates with Gulf distribution infrastructure and regional distributors serving mid-scale North African processors. Two strategic archetypes dominate: integrated fermentation platforms with captive strain libraries, and specialized culture suppliers with thermotolerant formulation expertise. Competitive moves concentrate on long-term offtake agreements displacing spot purchasing, and pre-positioning qualified strain dossiers in regional hubs to compress Saudi FDA approval cycles.
Within the integrated nutrition platform tier, DSM Nutritional Products and BASF SE occupy positions anchored by strain development capabilities and industrial enzyme reach. Chr. Hansen exemplifies the specialized culture archetype, with positioning calibrated for ambient-temperature distribution requirements prevalent in Gulf markets. These three entities represent the competitive concentration visible across procurement channels serving Saudi dairy cooperatives, UAE pharmacy retail, and South African brewing operations.
| Leading Market Players |
|---|
| BASF SE |
| Lonza Group |
| Döhler Group |
| Lesaffre |
| Evonik Industries AG |
| DSM Nutritional Products |
| Chr. Hansen |
| Novozymes |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Single-source dependency on European strain libraries compresses pricing tier spreads while forcing Gulf distributors toward dual-sourcing arrangements that reshape regional inventory positioning. Saudi FDA documentation timelines extend approval cycles for novel organisms, amplifying cost premiums for pre-qualified cultures and tilting procurement toward established supplier relationships.
Pricing Analysis
Cost-plus contracts with corn syrup and nitrogen source indexation dominate enzyme and yeast procurement for South African brewing and dairy processors. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade probiotics from industrial bakery cultures and commodity feed yeast. Cost compression in standard-tier dairy cultures is intensifying because Egyptian toll manufacturers are expanding capacity for North African bakery supply. Mid-scale North African processors exhibit highest price sensitivity due to working capital constraints, while Gulf multinational food manufacturers prioritize halal certification assurance over unit cost.
Supply Chain Analysis
Tariff exposure between European Union member states and Gulf Cooperation Council economies elevates landed costs for thermotolerant strain imports serving Saudi dairy cooperatives. Supply concentration in the Netherlands, Denmark, and Germany feeds regional dependence on specialized culture houses with Gulf-specific qualification dossiers. Raw material dependencies span fermentation-grade glucose, yeast extract, and peptone media components. Single-source vulnerability persists for precision fermentation platforms producing pharmaceutical-grade amino acids. Distribution runs through Jeddah, Durban, and Dubai Industrial City hubs that aggregate demand from mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa fermented ingredients market is cycling through a recovery phase as Gulf Standardization Organization harmonization reduces regulatory duplication costs and reopens cross-border trade velocity.
For Market Incumbents: Harden halal supply chain verification systems to preempt compliance bottlenecks that emerging regional distributors are exploiting to win mid-scale accounts. Deepen backward integration into fermentation media production to reduce exposure to European glucose and nitrogen source price volatility. Pre-position thermotolerant strain libraries in Dubai and Jeddah distribution hubs to compress Saudi FDA approval cycles for novel dairy cultures. For New Entrants and Emerging Players: Egyptian food processing white space offers the most penetrable entry point, with underdeveloped domestic enzyme production creating demand for toll manufacturing partnerships serving North African bakery and confectionery sectors. Target ambient-stable probiotic formulations for Kuwaiti pharmacy retail, where gut-health spending expansion outpaces qualified supplier availability. Pursue technical service bundling that combines strain customization with regulatory filing support to differentiate from commodity distributors. For Investors and Strategic Acquirers: Specialized culture suppliers with thermotolerant formulation expertise and pre-qualified Gulf dossiers represent the priority acquisition archetype, given their scarcity value in ambient-distribution markets. Long-term viability rests on precision fermentation cost curves continuing to narrow against synthetic alternatives across the analysis window. Monitor Egyptian toll manufacturing partnership announcements as inflection indicators for North African supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | Gulf Standardization Organization unified protocols eliminate redundant testing burdens across Saudi Arabia, UAE, and Kuwait. |
| Toll Manufacturing Partnership | Egyptian food processing capacity expansion addresses North African enzyme supply gaps without greenfield facility investment. |
| Thermotolerant Strain Development | Ambient-temperature distribution networks in Gulf markets demand specialized cultures with extended shelf stability claims. |
| Precision Fermentation Scale-Up | Single-use bioreactor adoption reduces sterilization energy costs for regional contract manufacturers serving pharmaceutical applications. |
| Regulatory Dossier Consolidation | Pre-qualified strain libraries compress Saudi FDA approval timelines and accelerate product launches for dairy culture suppliers. |
Research Methodology
Operator-level perspectives from fermentation plant managers, dairy cooperative procurement leads, Gulf distribution channel partners, and Saudi FDA regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs records, Gulf Standardization Organization technical specifications, and South African Department of Health additive regulations. Bottom-up strain-level demand modeling triangulated against top-down food processing capacity assessments across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, application, end user scale, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth rate distributions weighted by base-year revenue shares. Industry-specific inputs included bioreactor capacity utilization rates, halal certification penetration curves, and ambient-stable probiotic shelf-life performance data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or Gulf sovereign investment vehicles would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pulses Ingredients Market
Ingredients
Hydrolyzed Egg Market
Ingredients
Global Cocoa Products Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Home Baking Ingredients Market
Ingredients
Psyllium Husk Powder Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Green Gram Powder Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Vegetable Glycerin Market