
 North America Rice Protein Ingredients Market | 2026-2036
North America Rice Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rice Protein Ingredients Market Analytics
Premium-grade isolate specifications is collapsing the gap between rice protein and whey alternatives in performance nutrition formulations. Axiom Foods Inc leverages its vertically integrated supply chain from California rice milling to finished isolate. RiceBran Technologies anchors its position through proprietary stabilization technology for bran-derived protein. Kerry Group Plc competes by extending its flavor masking systems that neutralize rice protein's traditional sensory limitations.
Rice protein ingredients are concentrated or isolated protein fractions extracted from brown or white rice, typically containing 50-90% protein by dry weight with balanced amino acid profiles excluding lysine, produced through aqueous enzymatic extraction or alkaline solubilization followed isoelectric precipitation, serving primarily as hypoallergenic plant-based alternatives in human nutrition and specialized animal feed. Isolate and hydrolysate segments command margin concentration due to superior digestibility scores and cleaner label positioning in sports nutrition. Powder form dominates current volume flows while liquid formats are gaining traction in ready-to-drink beverage applications across North American manufacturing.
The FDA's Food Safety Modernization Act and USDA organic certification requirements shape ingredient sourcing protocols and facility auditing standards for rice protein suppliers operating in the United States. Health Canada's Natural and Non-prescription Health Products Directorate and CFIA food safety regulations govern cross-border trade and label claims for Canadian market access. Stakeholders must monitor evolving allergen labeling harmonization between US and Canadian frameworks while evaluating backward integration into rice milling to secure supply consistency.
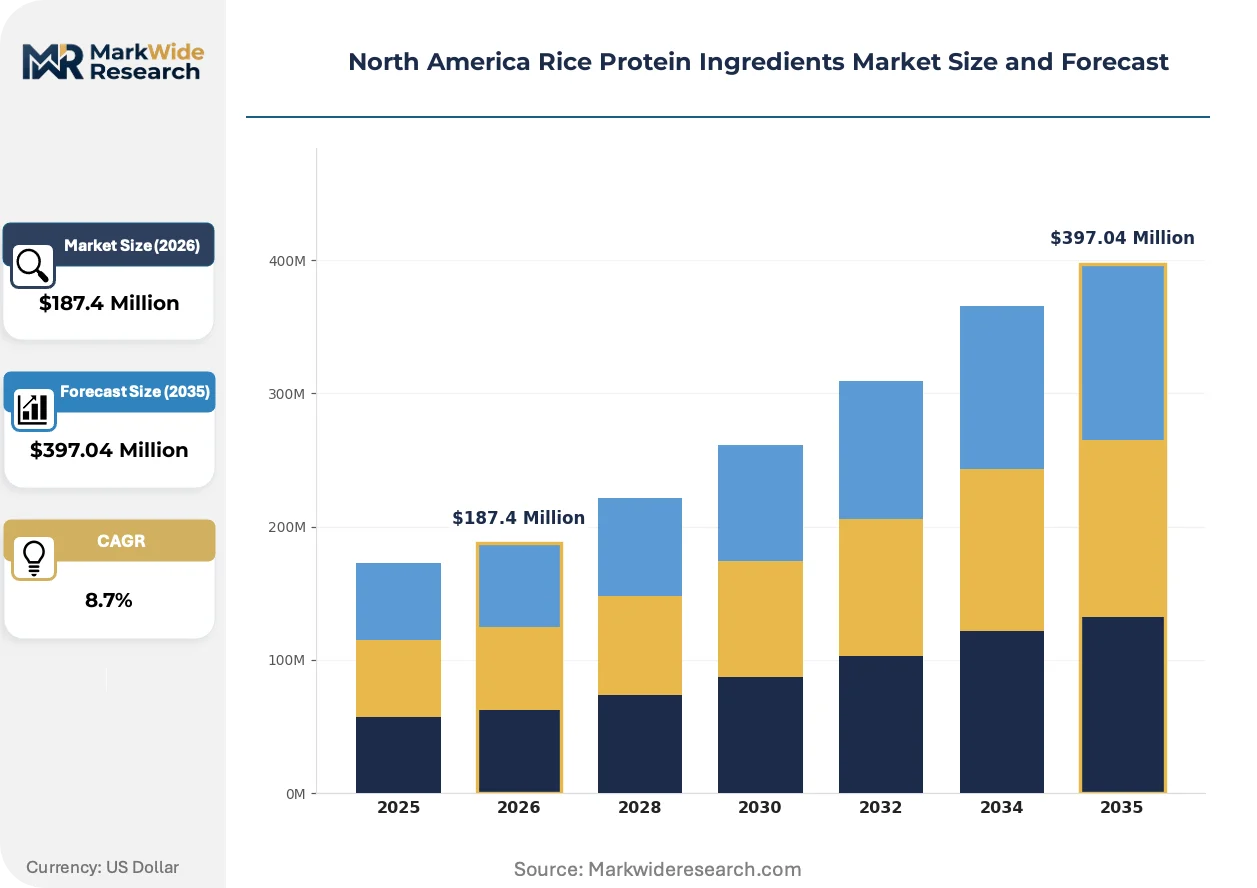
Market Dynamics
The FDA's updated Food Safety Modernization Act enforcement is compressing supplier qualification timelines while elevating traceability mandates across California's rice milling corridor. This regulatory pressure is reshaping procurement protocols for sports nutrition brands formulating with rice protein isolates.
Growth Catalysts
- FSMA Traceability Mandates:The FDA's enhanced record-keeping requirements are filtering out non-compliant suppliers, consolidating volume with certified processors capable of lot-level tracking from farm to finished ingredient.
- Sports Nutrition Formulation:Performance nutrition brands across the United States are expanding rice protein portfolios as whey alternatives face sustainability scrutiny and allergen labeling complexity.
- Enzymatic Extraction Advances:Aqueous enzymatic methods are improving protein recovery rates from brown rice bran, reducing waste streams and enabling cleaner label positioning for isolate grades.
Market Restraints
- Lysine Deficiency:Rice protein's incomplete amino acid profile requires costly blending with pea or hemp protein to achieve PDCAAS parity with dairy alternatives, compressing margin for mid-tier suppliers.
- California Water Scarcity:Concentrated rice milling in the Sacramento Valley faces irrigation restrictions and drought-driven input cost volatility, threatening supply consistency for protein processors.
- Sensory Masking Burden:Traditional rice protein carries chalky mouthfeel and grassy off-notes that demand expensive flavor system investments, disadvantaging smaller formulators against integrated competitors.
Strategic Opportunities
- Canadian Plant-Based Corridor:Health Canada's Natural and Non-prescription Health Products Directorate pathway offers faster novel food approvals than US GRAS self-affirmation, attracting brands to Vancouver and Toronto manufacturing clusters.
- Ready-to-Drink Liquid Formats:Beverage manufacturers are piloting hydrolysate-based RTD applications where improved solubility bypasses powder-format sensory limitations entirely.
- USDA Organic Premium Tier:Certified organic rice protein commands significant price multiples in infant nutrition and clinical applications where residue testing protocols exceed conventional thresholds.
Industry Challenges
- Allergen Validation Expertise:Cross-contact prevention for gluten-free certification requires specialized analytical chemists and ELISA testing infrastructure that mid-size processors struggle to staff.
- Legacy Equipment Retrofit Costs:Converting rice flour milling lines to protein isolation capacity demands isoelectric precipitation tanks and membrane filtration systems with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rice Protein Ingredients Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blends End User: Food Industry, Beverage Sector, Nutritional Supplements, Animal Feed Form: Powder, Liquid, Granules, Bars Application: Health Foods, Sports Nutrition, Vegan Products, Functional Foods |
| Companies Covered | Axiom Foods Inc, RiceBran Technologies, Kerry Group Plc, Farbest-Tallman Foods Corporation, Archer Daniels Midland Co, Roquette Frères, Südzucker AG, ACT Polyols, The Scoular Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rice Protein Ingredients Market Evolving Landscape
Processing technology and regulatory architecture are diverging competitive advantage sources in rice protein supply. Winners are securing simultaneous mastery of extraction efficiency and compliance documentation.
Enzymatic hydrolysis is bifurcating the isolate segment into standard and ultra-low molecular weight grades. Sports nutrition brands are adopting the latter for faster gastric emptying in intra-workout applications. This molecular weight stratification is compressing commodity-grade margins while rewarding processors with peptide fractionation capabilities.
The FDA's Food Safety Modernization Act Section 204 traceability rule is mandating electronic sortable records for high-risk foods including rice-derived ingredients. Protein processors must implement blockchain or comparable systems by 2026. California-based suppliers are absorbing compliance costs fastest, creating regulatory moats against importers.
Direct procurement from ingredient platforms is displacing traditional distributor relationships for mid-size sports nutrition brands. These buyers are negotiating specifications directly with Sacramento Valley processors, bypassing ingredient brokers. The pattern concentrates in western US states where logistics costs favor regional sourcing over Midwest distribution hubs.
North America Rice Protein Ingredients Market Segmentation
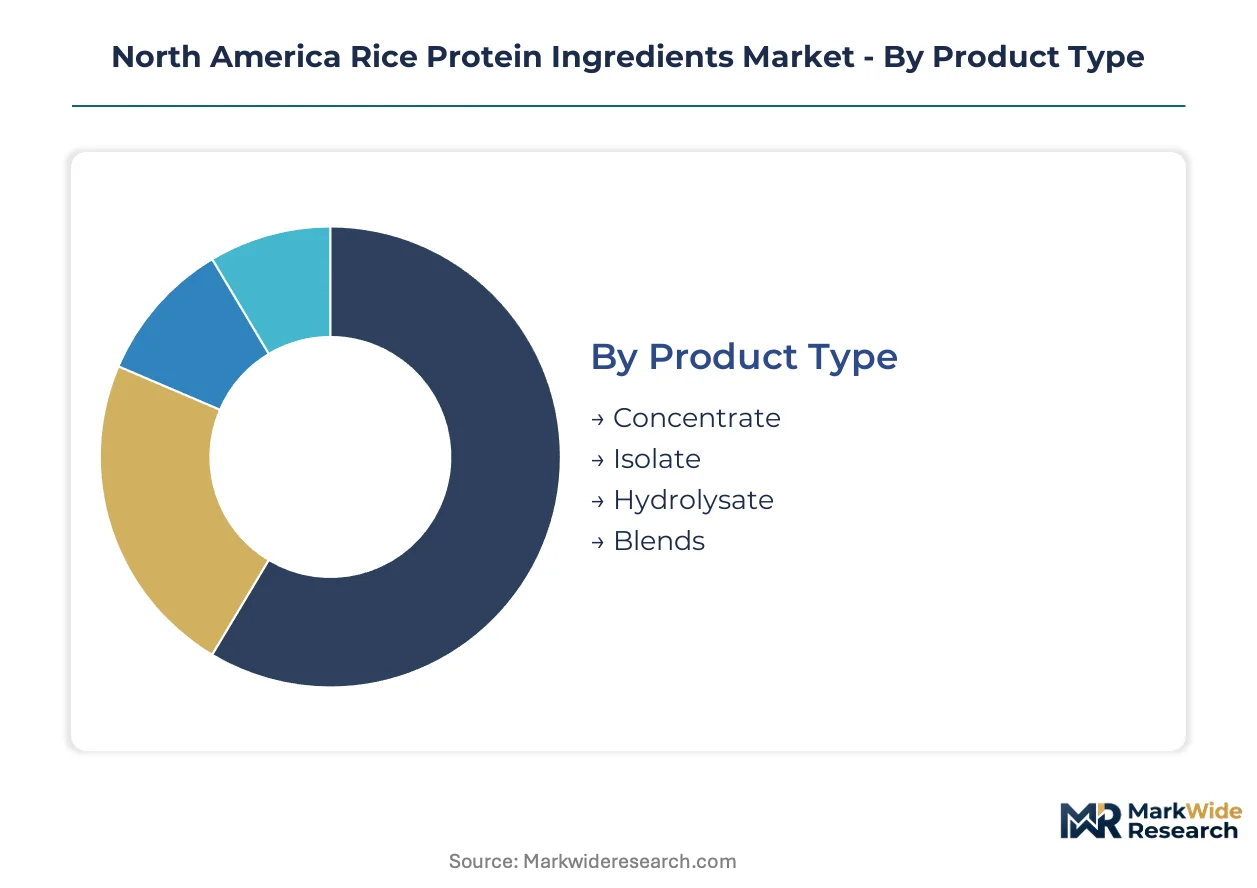
Segmentation in rice protein ingredients reveals how extraction technology and end-use specifications channel demand through distinct procurement pathways. Manufacturers configure production lines around isolate purity tiers or hydrolysate molecular weights, each serving separate customer bases with incompatible technical requirements.
Product Type:
Concentrate grades flow through commodity ingredient distributors serving mid-tier food manufacturers, while isolate and hydrolysate segments bypass traditional channels for direct processor-to-brand relationships.
- Concentrate:Protein fractions containing 50-80% protein by dry weight retain more fiber and starch carriers than refined grades. California's plant-based meat analog producers absorb concentrate volumes where cost sensitivity outweighs label clarity requirements.
- Isolate:Refined to 80-90% protein with minimal carbohydrate residue, isolate commands sports nutrition formulation slots previously held by whey. Sacramento Valley processors with membrane filtration capacity capture this segment's margin concentration.
- Hydrolysate:Enzymatically predigested for enhanced bioavailability, serving clinical nutrition and premium infant formula applications.
- Blends:Lysine-fortified combinations with pea or hemp protein addressing amino acid completeness gaps in single-source formulations.
By volume, Concentrate leads. By growth pace, Hydrolysate is expanding most quickly through ready-to-drink beverage applications.
End User:
Customer type determines specification stringency, with nutritional supplements demanding certificate-of-analysis documentation that food industry buyers rarely require.
- Food Industry:Plant-based meat and dairy analog manufacturers in California's manufacturing corridor drive bulk concentrate procurement. FDA's updated Food Safety Modernization Act traceability mandates are filtering supplier bases to certified processors with electronic lot-tracking systems.
- Beverage Sector:Ready-to-drink protein beverages favor hydrolysate and liquid formats where solubility eliminates powder-dispersion challenges. Toronto and Vancouver manufacturing clusters pilot novel hydrolysate applications under Health Canada's streamlined approval pathways.
- Nutritional Supplements:Sports nutrition brands across the United States expand rice protein portfolios as sustainability credentials displace dairy alternatives.
- Animal Feed:Specialty pet nutrition and aquaculture feed applications utilize rice protein as hypoallergenic alternatives to soy and fishmeal.
Food Industry captures the largest volume share. Nutritional Supplements generate the steepest margin expansion as isolate grades displace whey in performance positioning.
Form:
Physical format selection tracks equipment compatibility and sensory engineering requirements across manufacturing facilities.
- Powder:Dominates current volume flows through established dry-blending infrastructure. Chalky mouthfeel and solubility limitations drive flavor masking investments by integrated competitors.
- Liquid:Gaining traction in ready-to-drink applications where hydrolysate formats bypass powder-dispersion equipment entirely. Toronto beverage manufacturers pilot concentrated liquid bases for dilution-at-bottling models.
- Granules:Intermediate flow properties for tableting and capsule-filling operations in supplement manufacturing.
- Bars:Pre-hydrated protein inclusions for baked and extruded snack formats requiring moisture management.
Powder maintains volume leadership. Liquid formats climb the fastest through beverage sector adoption.
Application:
Application positioning determines certification requirements, with infant and clinical nutrition demanding residue testing protocols that exceed standard food-grade thresholds.
- Health Foods:General wellness positioning in cereals, snacks, and meat alternatives. USDA organic certification commands significant price multiples where residue testing exceeds conventional thresholds.
- Sports Nutrition:Performance-focused isolate and hydrolysate adoption accelerates as sustainability scrutiny displaces whey alternatives. California-based brands negotiate direct procurement from Sacramento Valley processors.
- Vegan Products:Clean-label positioning leverages rice protein's hypoallergenic profile against soy and wheat alternatives.
- Functional Foods:Clinical and infant nutrition applications requiring batch-level documentation and allergen validation infrastructure.
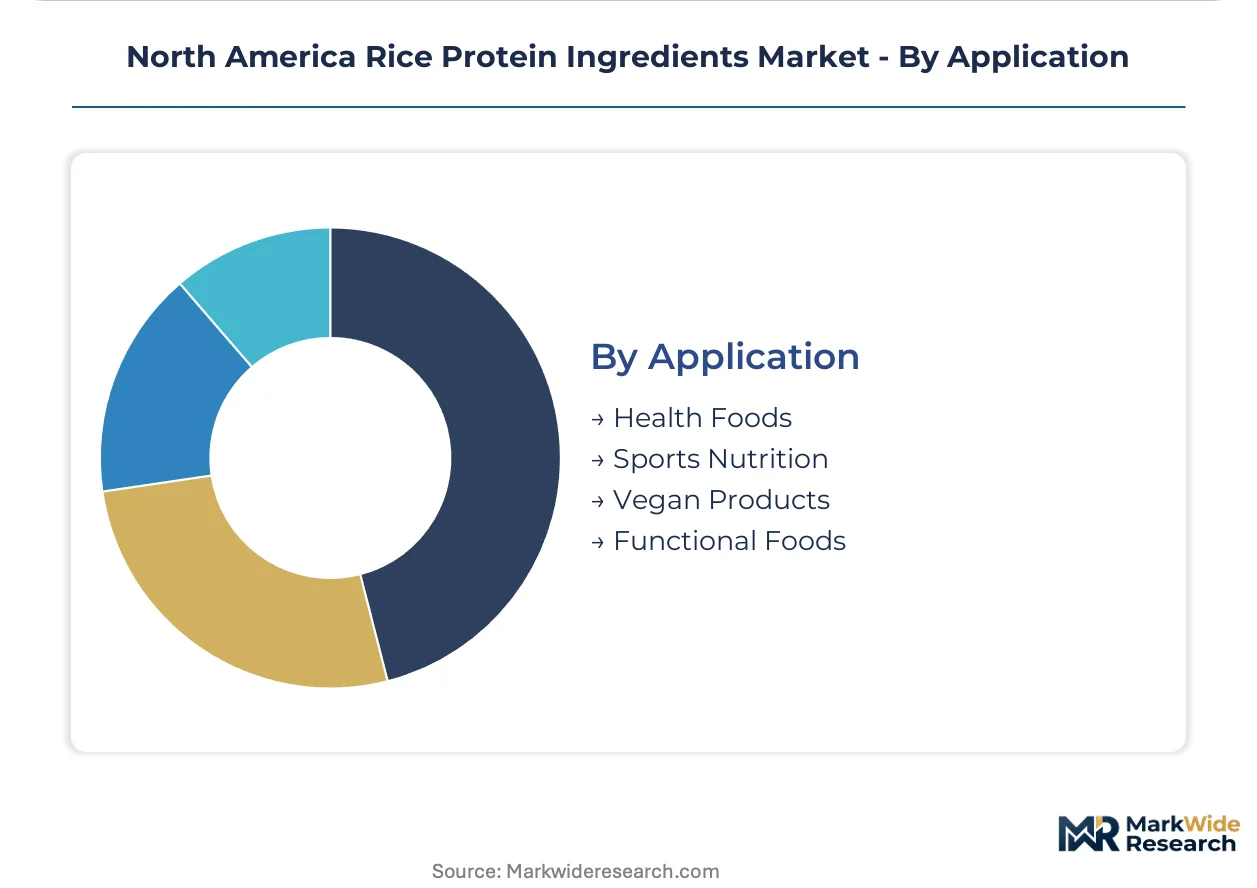
Health Foods leads by volume. Sports Nutrition gains share fastest through sustainability-driven formulation shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America operates as a net importer of rice protein isolates despite substantial domestic milling capacity, with cross-border flows between the United States and Canada intensifying as Health Canada's streamlined novel food approvals attract formulation investment northward.
United States
Sports nutrition brands in California's Sacramento Valley corridor drive premium isolate demand as sustainability positioning displaces whey alternatives. The FDA's Food Safety Modernization Act Section 204 traceability rule mandates electronic lot-tracking systems by 2026, filtering supplier bases to certified processors. Sacramento Valley rice milling clusters absorb compliance costs fastest, creating regulatory moats against importers.
Canada
Toronto and Vancouver manufacturing clusters pilot novel hydrolysate applications under Health Canada's Natural and Non-prescription Health Products Directorate pathway, which offers faster approvals than US GRAS self-affirmation. CFIA food safety regulations govern cross-border label claims and allergen harmonization with US frameworks. British Columbia's plant-based beverage sector attracts direct procurement from regional processors seeking Health Canada certification advantages.
Mexico
Baja California and Jalisco industrial corridors absorb overflow demand from California's constrained water supply, with maquiladora facilities processing rice protein concentrates for re-export to US food manufacturers. Mexico's COFEPRIS regulatory alignment with FDA standards facilitates seamless cross-border ingredient flows. Guadalajara's growing nutraceutical sector sources hydrolysate grades for infant formula applications serving Latin American markets.
North America Rice Protein Ingredients Market Competitive Landscape
Concentration sits with vertically integrated processors controlling Sacramento Valley rice milling through finished isolate production. The supplier base stratifies across three tiers: multinational ingredient conglomerates with flavor masking capabilities, mid-cap specialists with proprietary extraction technologies, and commodity concentrate traders serving cost-sensitive food manufacturers. Dominant competitive moves include backward integration into California rice milling assets and strategic partnerships with sports nutrition brands for co-development of clean-label formulations.
Among US-based integrated processors, Axiom Foods Inc and RiceBran Technologies exemplify the vertical integration archetype, anchoring positions through captive supply chains from raw milling to finished isolate grades. Kerry Group Plc represents the multinational flavor systems tier, occupying a position where sensory engineering capabilities neutralize rice protein's traditional formulation limitations. These three players illustrate how extraction mastery and compliance documentation simultaneously determine competitive advantage in this market.
| Leading Market Players |
|---|
| Axiom Foods Inc |
| RiceBran Technologies |
| Kerry Group Plc |
| Farbest-Tallman Foods Corporation |
| Archer Daniels Midland Co |
| Roquette Frères |
| Südzucker AG |
| ACT Polyols |
| The Scoular Company |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day ingredient qualification timelines at California sports nutrition brands concentrate procurement power with Sacramento Valley processors holding FDA-compliant electronic traceability systems. This lead-time compression elevates pricing power for certified isolates while squeezing commodity concentrate margins.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the concentrate segment. Premium-mid-economy pricing differentiation separates USDA organic certified isolates from conventional grades, with certification level and volume scale as primary price drivers. Cost compression in commodity concentrates is intensifying because drought-driven rice input volatility transfers upstream. Mid-tier food manufacturers show highest price sensitivity, while infant nutrition formulators demonstrate lowest sensitivity due to residue testing protocol requirements.
Supply Chain Analysis
Membrane filtration equipment bottlenecks at Sacramento Valley processing facilities constrain isolate output expansion. Geographic supply concentration centers on the United States, Canada, and Mexico, with raw material dependencies on California rice milling, enzymatic extraction inputs, and organic certification auditing capacity. Single-source vulnerability runs through the Sacramento Valley irrigation corridor facing water scarcity restrictions. Distribution feeds from processor-direct relationships displacing traditional ingredient brokers for mid-size sports nutrition brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America rice protein ingredients sit in early-cycle expansion as sustainability-driven formulation shifts displace whey alternatives in performance nutrition. Sports nutrition brand procurement teams are consolidating supplier bases around compliant processors faster than supply capacity expands.
For Market Incumbents: Compound defensible positions through backward integration into California rice milling assets and captive enzymatic extraction capacity. Threats from Kerry Group Plc's flavor masking systems demand proprietary sensory engineering investments. Certification investment in USDA organic and FDA FSMA compliance creates regulatory moats against import competition.
For New Entrants and Emerging Players: Health Canada's Natural and Non-prescription Health Products Directorate fast-track offers lower barrier entry than US GRAS self-affirmation for hydrolysate innovations. White-space targets include ready-to-drink beverage liquid formats and lysine-fortified blend formulations. Go-to-market through Toronto and Vancouver manufacturing clusters leverages faster approval timelines for novel food positioning.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty ingredient consolidation play because regulatory compliance burdens favor scaled processors with captive supply chains. Target archetypes include mid-cap enzymatic extraction specialists with membrane filtration capabilities and established FDA audit histories. Watch sports nutrition brand direct procurement rates as inflection indicator for distributor displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Milling | Captive supply from California Sacramento Valley secures input cost control against drought volatility. |
| Enzymatic Hydrolysis Capacity Expansion | Ultra-low molecular weight peptide fractionation captures premium sports nutrition intra-workout formulation slots. |
| FDA FSMA Section 204 Compliance Investment | Electronic lot-tracking systems create regulatory moats filtering non-compliant import competition by 2026. |
| Health Canada Certification Fast-Track | Toronto and Vancouver manufacturing clusters accelerate novel hydrolysate approvals versus US pathways. |
| Flavor Masking System Partnership | Sensory engineering collaborations neutralize traditional rice protein chalky mouthfeel and grassy off-notes. |
Research Methodology
Desk research of FDA enforcement guidance documents, USDA organic certification databases, and Health Canada novel food approval precedents preceded structured interviews with sports nutrition brand procurement directors, Sacramento Valley rice mill operations managers, enzymatic extraction technology suppliers, and regulatory compliance consultants. Secondary validation drew from customs trade data, SEC 10-K filings of publicly traded ingredient processors, and California agricultural irrigation restriction records. Bottom-up volume modeling and top-down value triangulation cross-verified segment outputs.
Variance decomposition across product type, end user, physical form, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling and input cost trajectory assumptions. Industry-specific forecast inputs included California water scarcity restriction scenarios and sports nutrition brand sustainability procurement policy shifts.
Decision-makers should treat outputs as directional under sustained drought conditions and FSMA enforcement continuity assumptions; material deviation in California rice yields or Health Canada approval timelines would warrant model refresh. Practitioners should keep alternative scenarios live as FDA traceability rule implementation deadlines and organic certification audit backlogs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vegetable Fats Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Virginiamycin Market
Ingredients
Pea Flour Market
Ingredients
Europe Phytosterols Market
Ingredients
Corn Starch Market
Ingredients
Bromelain Ingredient Market
Ingredients
Cheese Powder Market
Ingredients
Truffle Oil Market
Ingredients
Yeast Autolysates Market
Ingredients
Carotenes Market
Ingredients
Africa Fats and Oil Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Edible Animal Fat Market
Ingredients
Egg Yolk Powder Market