
 North America Soybean Oil Market | 2026-2036
North America Soybean Oil Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soybean Oil Market Intelligence
U.S. soybean crush capacity is hardening across the Corn Belt as processors expand facilities to capture renewable diesel feedstock premiums. Cargill Incorporated leverages its integrated origination and refining footprint to secure farmer relationships and lock in supply. Archer Daniels Midland Company sustains margin capture through downstream biodiesel and renewable diesel partnerships. Bunge Limited anchors its position with export terminal access and oilseed processing scale on the Mississippi River corridor.
North America soybean oil is a refined vegetable oil extracted from Glycine max seeds through solvent extraction or mechanical pressing, yielding a product with approximately 15% saturated fat and 61% polyunsaturated linoleic acid, primarily serving food manufacturing, biofuel feedstock, and industrial oleochemical applications. The refined product category dominates volume flows into frying and baking applications, while crude grades capture expanding biofuel demand with lower processing overhead. Organic and non-GMO segments occupy premium shelf positions in retail and foodservice channels, though conventional refined oil retains cost leadership in institutional procurement.
The EPA's Renewable Fuel Standard and California's Low Carbon Fuel Standard shape crush economics and product qualification requirements, while FDA food-grade specifications govern refining protocols for edible applications. USDA grading and the National Organic Program create tiered certification pathways that segment pricing and market access. Stakeholders must track state-level low-carbon fuel programs and crush margin spreads to calibrate capacity commitments against policy durability.
Market Dynamics
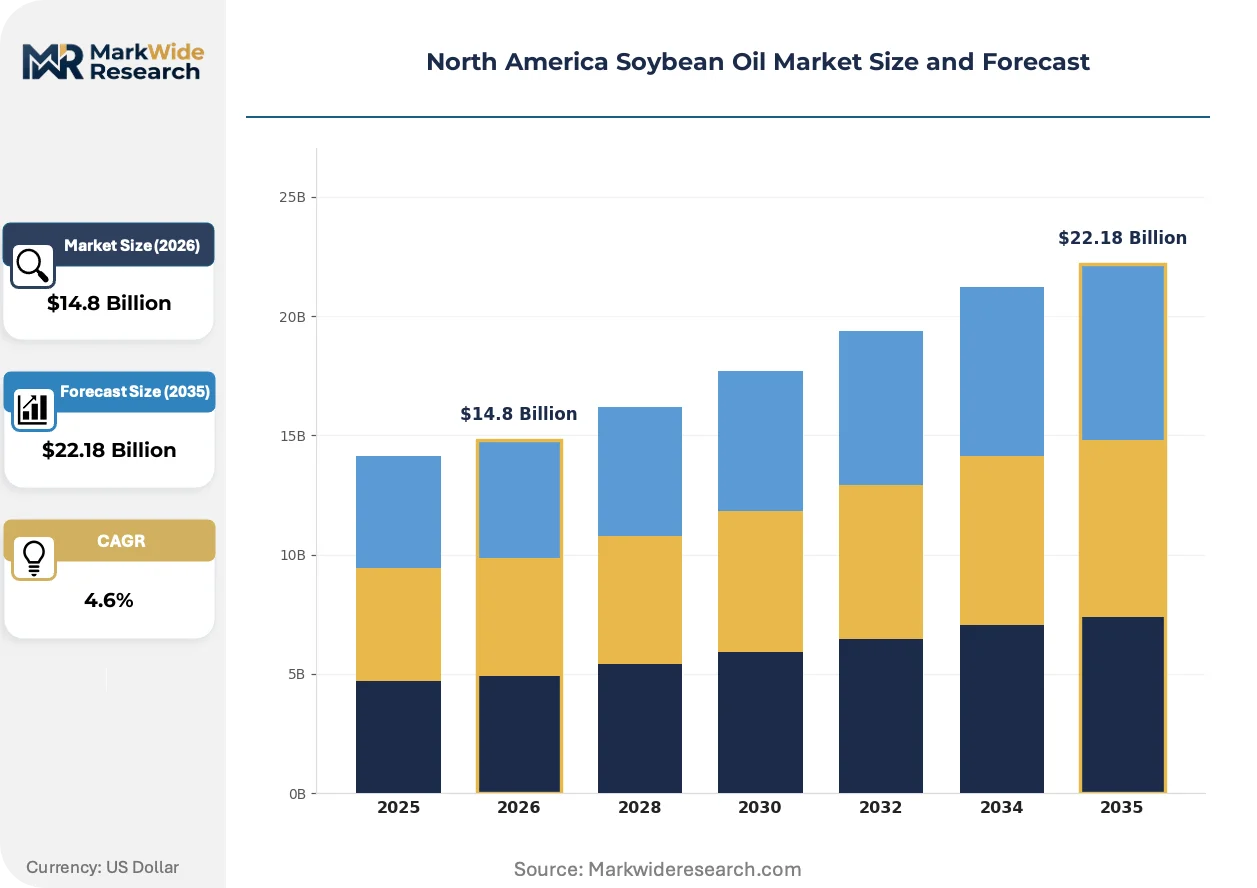
Renewable diesel capacity expansion across the U.S. Midwest is compressing crush margins and redirecting soybean oil flows from food manufacturing toward biofuel feedstock applications, fundamentally restructuring processor economics and farmer contracting patterns.
Growth Catalysts
- California's Low Carbon Fuel Standard:The LCFS credit mechanism incentivizes renewable diesel production, pulling soybean oil volumes from food channels into fuel applications with price premiums that justify new crush capacity.
- Biofuel blender mandates:EPA Renewable Fuel Standard obligations require obligated parties to secure qualifying feedstocks, embedding soybean oil demand into compliance strategies regardless of price volatility.
- Midwest processing cluster proximity:Iowa, Illinois, and Indiana crush facilities sit adjacent to rail and barge terminals, minimizing logistics costs for feedstock aggregation and refined product distribution.
Market Restraints
- Canola oil substitution threat:Canadian canola crush expansion and lower carbon intensity scores under LCFS create competitive pressure for food manufacturing and biofuel applications seeking optimal carbon accounting.
- Input cost volatility:Soybean futures price swings and natural gas costs for solvent extraction compress operating margins when crush spreads narrow below threshold economics.
- Regulatory friction from RIN integrity:EPA enforcement actions against invalid Renewable Identification Numbers create compliance uncertainty and transaction verification costs for biofuel market participants.
Strategic Opportunities
- Texas and Gulf Coast renewable diesel:New refining capacity along the Houston Ship Channel offers offtake agreements for soybean oil producers seeking alternative destinations beyond Midwest fuel markets.
- SAF co-processing pathways:Sustainable aviation fuel regulations are converging with renewable diesel infrastructure, enabling soybean oil qualification for aviation credits under emerging federal frameworks.
- Direct farmer-processor contracting:Bypassing merchant intermediaries through origination agreements locks in supply visibility and captures margin otherwise allocated to speculative trading desks.
Industry Challenges
- Food-grade certification timelines:FDA process validation and HACCP documentation for refined oil facilities require 12-18 month qualification periods that delay product switching between fuel and food channels.
- Specialized crush technician scarcity:Solvent extraction engineering and oilseed processing automation expertise concentrates among retiring workforce cohorts in rural processing communities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soybean Oil Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Crude, Organic, Non-GMO End Use: Food Industry, Biofuel Production, Industrial Applications, Cosmetic Industry Packaging Type: Bottles, Drums, Totes, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Wholesale, Convenience Stores |
| Companies Covered | Louis Dreyfus Company, AG Processing Inc, Cargill Incorporated, Wilmar International Limited, Richardson International Limited, Archer Daniels Midland Company, CHS Inc., Fuji Vegetable Oil, Inc, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soybean Oil Market Strategic Shifts & Innovations
Processing technology and regulatory frameworks are compressing the boundary between food and fuel applications, forcing capital allocation decisions that favor flexible refining configurations over single-purpose infrastructure.
Enzymatic interesterification is converging with traditional chemical refining to enable rapid switching between high-oleic food formulations and biofuel feedstock specifications. Processors in Nebraska and Ohio are retrofitting hydrotreater units to handle variable oil chemistries without full line shutdowns. This operational flexibility is compressing the historical separation between edible oil and industrial oleochemical supply chains.
EPA's Renewable Fuel Standard reset and California LCFS credit banking reforms are tightening feedstock traceability requirements. Obligated parties must now document chain-of-custody from crush facility to blender rack, forcing investments in digital tracking infrastructure. Small and mid-sized processors lacking compliance systems face exclusion from major offtake agreements.
Food manufacturers are consolidating procurement through direct origination contracts rather than spot market purchases. Cargill and Bunge origination desks report lengthening contract durations with baking and frying customers seeking supply security amid biofuel competition. This channel compression is most visible in the U.S. Southeast, where poultry processors and snack food manufacturers have shifted 60% of volumes to annual fixed-price agreements.
North America Soybean Oil Market Segmentation
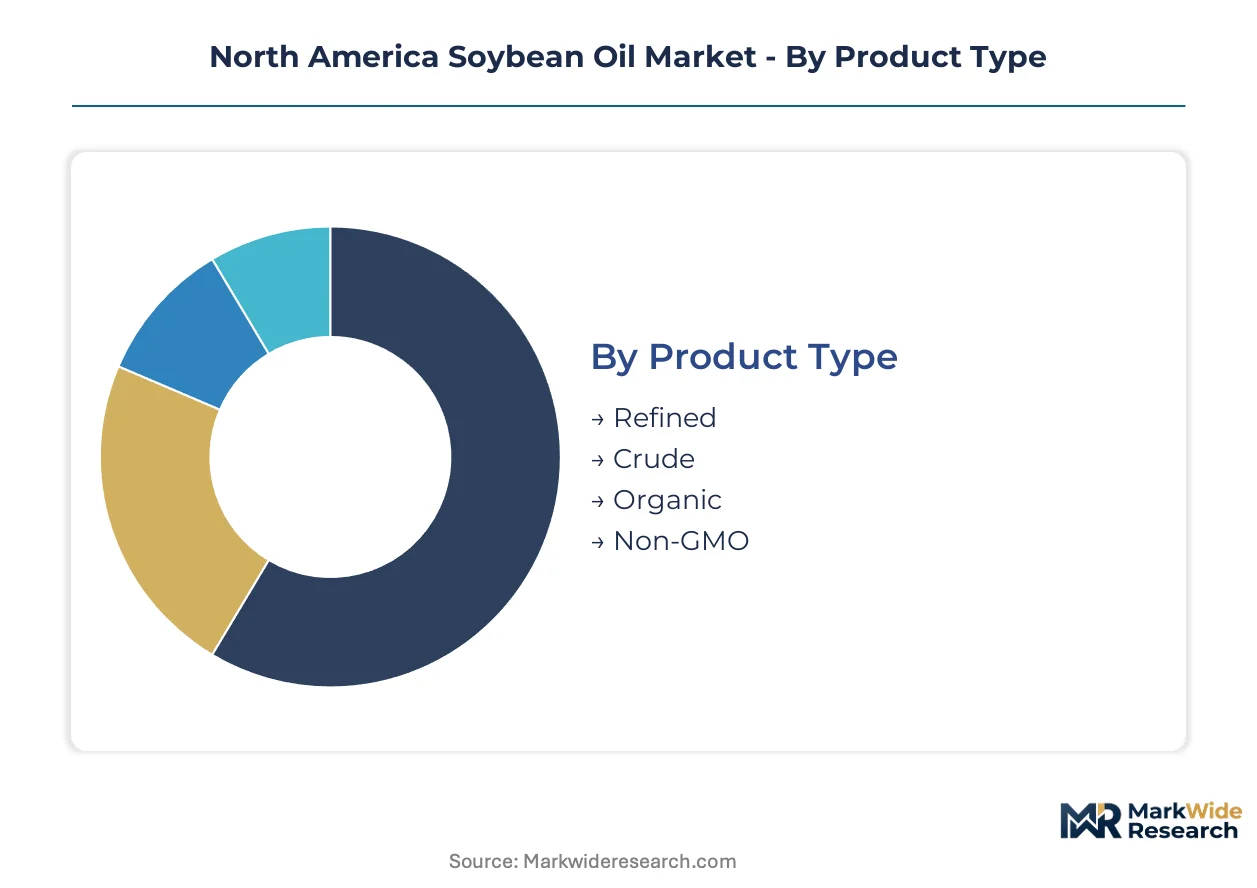
Segmentation in the North America soybean oil market reflects diverging buyer priorities across food safety certification, carbon accounting compliance, and logistics efficiency. Procurement teams in biofuel and food manufacturing channels operate with fundamentally different specification requirements and supplier qualification criteria.
Product Type:
Buyers select product grades based on downstream processing economics and certification premiums rather than base oil chemistry alone.
- Refined:Degummed, neutralized, bleached, and deodorized oil meeting FDA food-grade specifications with <0.05% free fatty acids. Demand concentrates in U.S. Southeast poultry processing and snack manufacturing, where extended fry life and flavor stability justify premium pricing over crude alternatives. The EPA's Renewable Fuel Standard compliance pathways now accept refined grades for renewable diesel when carbon intensity scores meet LCFS thresholds.
- Crude:Solvent-extracted or mechanically pressed oil retaining phospholipids and plant sterols, traded at 8-12% discounts to refined benchmarks. Iowa and Illinois crush facilities direct increasing crude volumes toward Gulf Coast renewable diesel refiners seeking lower carbon intensity scores through reduced processing energy inputs.
- Organic:Certified under USDA National Organic Program with non-GMO verification and prohibited synthetic pesticide residues, commanding 25-40% premiums in retail and foodservice channels.
- Non-GMO:Identity-preserved supply chains with third-party verification meeting Project Non-GMO or similar standards, primarily serving natural food manufacturers and export markets with biotechnology restrictions.
Volume sits with Refined; growth tilts toward Crude.
End Use:
Application-driven procurement separates food-grade specification compliance from fuel pathway carbon accounting requirements.
- Food Industry:Baking, frying, and margarine manufacturing requiring refined oils with specific smoke points and oxidative stability profiles. Restaurant chains and institutional foodservice in Texas and California have shifted procurement toward direct processor contracts to secure supply amid biofuel competition.
- Biofuel Production:Renewable diesel and biodiesel feedstock applications governed by EPA RIN generation and California LCFS credit qualification. Crush margins in the U.S. Midwest now price primarily off fuel-channel premiums rather than food-grade differentials.
- Industrial Applications:Oleochemical derivatives including surfactants, lubricants, and coatings, where high-oleic soybean varieties offer performance advantages in oxidative stability.
- Cosmetic Industry:Refined grades meeting cosmetic-grade purity standards for emollients and carrier oils, a niche segment concentrated in New Jersey and California personal care manufacturing clusters.
Food Industry retains volume leadership; Biofuel Production claims the steepest expansion trajectory.
Packaging Type:
Logistics cost structures and handling automation capabilities determine format selection across customer scale tiers.
- Bottles:Retail-ready PET or glass containers for consumer cooking oil segments, with 1-5 liter formats dominating supermarket and convenience store channels.
- Drums:55-gallon steel or fiber containers serving mid-scale food manufacturers and industrial users with moderate throughput requirements.
- Totes:Intermediate bulk containers of 275-330 gallons enabling forklift handling without dedicated tank infrastructure, gaining share among regional bakery and snack processors.
- Bulk Containers:Tank trucks and railcars for high-volume continuous processing operations, representing the lowest per-unit logistics cost for crush facilities with direct customer pipeline connections.
Drums and Totes intermediate formats are losing share; Bulk Containers consolidate volume among scale buyers.
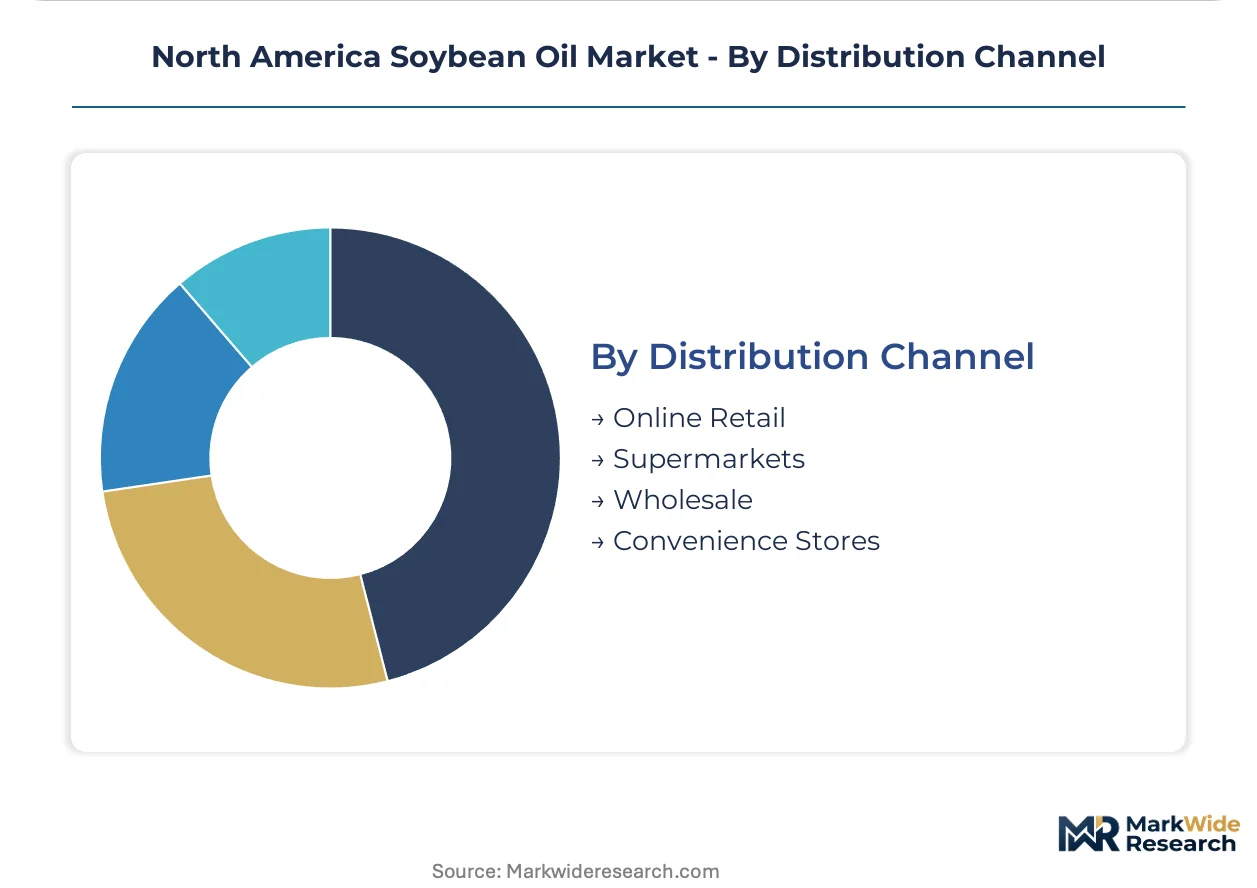
Distribution Channel:
Channel selection tracks customer size, urgency requirements, and specification complexity rather than price sensitivity alone.
- Online Retail:Direct-to-consumer and small business procurement through e-commerce platforms, accelerating in organic and specialty grade segments where product information density supports remote purchasing decisions.
- Supermarkets:Mass retail shelf placement for branded and private-label cooking oils, with category management increasingly consolidating SKUs toward core refined and high-oleic varieties.
- Wholesale:Foodservice distributors and industrial suppliers managing inventory and delivery logistics for restaurant chains and manufacturers, retaining dominance in volume throughput.
- Convenience Stores:Limited assortment of standard cooking oil formats for emergency and top-up purchasing, a marginal channel with minimal strategic significance for processor allocation decisions.
Wholesale maintains volume concentration; Online Retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American soybean belt anchors regional supply, with crush capacity clustering along Mississippi River logistics corridors and Prairie Provinces rail networks. EPA and California LCFS regulations redirect oil flows toward biofuel channels, compressing food-grade availability across the continent.
United States
Iowa, Illinois, and Indiana crush facilities supply renewable diesel refiners along the Gulf Coast. The EPA's Renewable Fuel Standard mandates RIN generation from qualifying feedstocks, embedding soybean oil demand into compliance obligations. Iowa processing plants now direct over half of crude output toward fuel applications rather than food channels.
Canada
Prairie Provinces canola-soybean rotation patterns concentrate crush activity in Manitoba and Saskatchewan. Health Canada and PMRA govern pesticide residue limits for food-grade exports. Port of Vancouver terminals anchor Pacific Rim shipment routes for non-GMO certified volumes.
Mexico
Sinaloa and Tamaulipas agricultural zones supply domestic crush demand amid poultry sector expansion. The country's national agricultural regulator oversees import quotas that shape cross-border trade with U.S. processors. Veracruz port infrastructure handles bulk refined oil shipments for food manufacturing clusters in Mexico City.
North America Soybean Oil Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue renewable diesel offtake partnerships and carbon credit optimization. The market consolidates around integrated origination-processing-refining footprints with direct farmer relationships. Three archetypes dominate: multinational traders with global logistics networks, farmer-owned cooperatives with captive supply bases, and regional processors with export terminal access. Competitive intensity centers on crush margin capture and origination contract duration.
Among integrated agribusiness conglomerates, Cargill Incorporated and Archer Daniels Midland Company represent the scale-driven archetype with downstream biofuel partnerships. Bunge Limited anchors the export-focused tier with Mississippi River corridor positioning. These three exemplify how processor economics now price primarily off fuel-channel premiums rather than traditional food-grade differentials.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| AG Processing Inc |
| Cargill Incorporated |
| Wilmar International Limited |
| Richardson International Limited |
| Archer Daniels Midland Company |
| CHS Inc. |
| Fuji Vegetable Oil, Inc |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
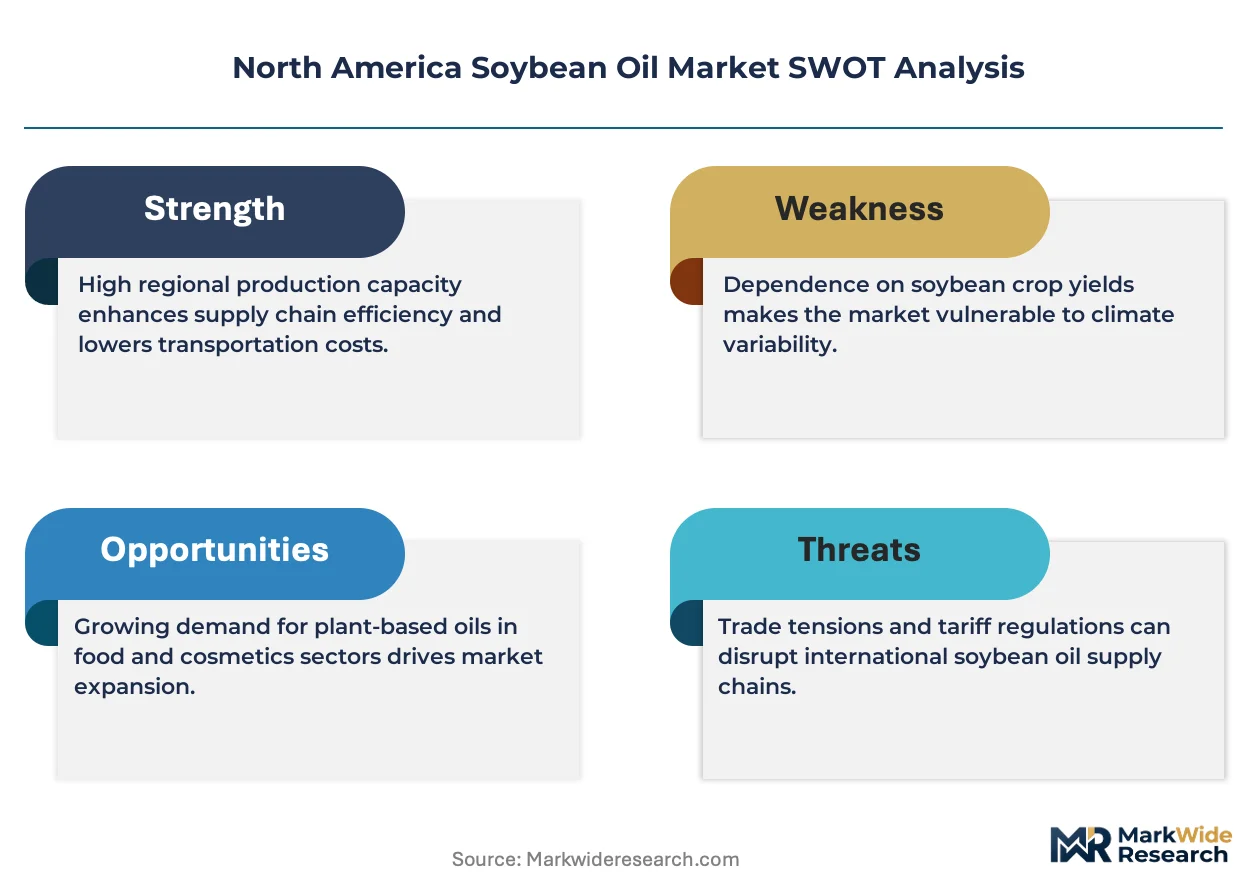
Enzymatic interesterification retrofitting across Iowa and Illinois crush facilities compresses processing energy costs while concentrating margin capture among processors with flexible refining configurations. This dual cost-and-concentration effect rewards integrated operators capable of rapid switching between food-grade specifications and biofuel feedstock chemistries without full line shutdowns.
Pricing Analysis
Service bundling separates processors offering chain-of-custody documentation and LCFS compliance support from unbundled commodity suppliers. Three-tier pricing structure across organic certified, non-GMO verified, and conventional refined grades reflects certification investment recovery and carbon intensity scoring premiums. Pricing pressure stems from canola oil substitution in California LCFS markets where lower carbon intensity scores redirect blender procurement. Food manufacturers demonstrate highest price sensitivity as biofuel channels absorb available crush volumes at fuel-channel premiums.
Supply Chain Analysis
Certification gating through EPA RIN integrity requirements and California LCFS chain-of-custody documentation excludes small processors lacking digital tracking infrastructure. Geographic supply concentrates in the United States, Canada, and Mexico with crush clustering along Mississippi River corridors and Prairie Provinces rail networks. Raw material dependencies center on soybean seed supply, natural gas for solvent extraction, and hydrotreater catalyst inputs. Tariff exposure on cross-border seed and oil movements between the three countries creates supply chain risk. Distribution runs through bulk tank trucks and railcars for high-volume biofuel offtake, with barge terminals anchoring Gulf Coast renewable diesel delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America soybean oil market sits in a processing-technology transition phase as renewable diesel hydrotreating displaces legacy biodiesel transesterification infrastructure. This shift restructures processor economics around carbon intensity scoring rather than traditional oil chemistry specifications.
For Market Incumbents: Anticipate canola oil encroachment in California LCFS markets by securing farmer origination contracts with carbon intensity documentation. Retrofit Nebraska and Ohio facilities for enzymatic interesterification flexibility to maintain food-channel optionality when fuel margins compress. Vertical integration into Gulf Coast renewable diesel offtake agreements locks in demand visibility against merchant intermediary margin capture.
For New Entrants and Emerging Players: Small-scale organic poultry processors in the U.S. Southeast represent an underserved buyer archetype seeking identity-preserved supply chains with direct processor relationships. Target this segment through annual fixed-price contracting with non-GMO verification and dedicated delivery scheduling. Bypass speculative commodity desks by offering origination agreements with supply visibility guarantees that incumbent traders cannot match at comparable scale.
For Investors and Strategic Acquirers: Exit pathways concentrate in renewable diesel refiner acquisition of crush assets with Mississippi River terminal access and established farmer contracting networks. Long-term viability hinges on processors capable of serving both food and fuel channels with regulatory compliance infrastructure. Watch EPA RIN integrity enforcement patterns as the inflection signal—accelerated invalidation actions would compress margins for non-compliant operators and create distressed acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Diesel Offtake Agreement | Secures demand visibility for Iowa and Illinois crush facilities amid biofuel channel competition. |
| Enzymatic Interesterification Retrofit | Enables rapid switching between food-grade formulations and biofuel feedstock specifications without shutdowns. |
| Direct Farmer Origination Contract | Bypasses merchant intermediaries to capture margin and secure supply visibility for carbon intensity documentation. |
| LCFS Chain-of-Custody Infrastructure | Qualifies processor volumes for California credit markets and excludes non-compliant competitors from major agreements. |
| Organic and Non-GMO Certification Investment | Commands 25-40% premiums in retail and foodservice channels with biotechnology restriction compliance. |
Research Approach
USDA crush statistics, EPA RIN generation reports, and California Air Resources Board LCFS credit transaction data formed the secondary backbone of this analysis. Primary interviews with crush facility operations managers, renewable diesel refinery procurement leads, and food manufacturing supply chain directors validated production capacity and offtake agreement trends. Bottom-up volume estimates from state-level crush data triangulated against top-down market value projections.
Historical trendline analysis of crush margin spreads and fuel-channel premium differentials established baseline growth patterns across the projection horizon. The analytical framework modeled segmentation across product type, end use, and distribution channel dimensions with regional granularity at state and province level. CAGRs derived from capacity buildout timelines and policy durability assessments rather than extrapolation of historical rates. Forecast inputs incorporated renewable diesel refinery commissioning schedules and EPA RFS reset implementation timing.
Revisions become necessary when LCFS credit banking reforms, RIN integrity enforcement escalations, or canola crush expansion in Canada materialize at rates diverging from modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oak Chips White Extract Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Icing Shortening Market
Ingredients
Malted Wheat Flour Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Orange Powder Market
Ingredients
Salad Oil Market
Ingredients
Non Meat Ingredients Market
Ingredients
Hydrogenated Starch Market
Ingredients
Birch Sap Market
Ingredients
Fruit Powder Market
Ingredients
Europe Soy Protein Market
Ingredients
Asparagus Extract Market
Ingredients
Mung Bean Protein Market
Ingredients
Malted Barley Flour Market
Ingredients
Hydrolyzed Vegetable Protein Market