
 France Protein Market | 2026-2036
France Protein Market Size, Share, and Industry Trends Forecast 2026-2036
France Protein Market Foresight
Plant-derived protein isolates is consolidating share from conventional dairy concentrates in French formulation economics. Roquette Frères leverages its pea protein extraction expertise to anchor supply for European food manufacturers. Danone competes through specialized fermentation capabilities that sustain differentiated dairy and alternative protein portfolios. Groupe Lactalis dominates whey fractionation, controlling access to premium isolate grades for sports nutrition brands.
France protein encompasses amino acid chains and peptide fractions derived from animal, dairy, and plant biomass, typically standardized to protein content thresholds between 80% and 95% on a dry-weight basis, serving nutritional fortification, muscle protein synthesis support, and metabolic health applications. Powder formats occupy the largest volume position due to shelf stability and blending flexibility in industrial food production. Sports nutrition and dietary supplements represent the fastest-expanding application clusters as French consumers shift toward proactive health management. Functional foods maintain mature, margin-defensive positions through established retail distribution.
ANSM oversees novel food safety assessments for alternative protein sources entering French commerce, while EFSA harmonizes health claim substantiation across EU member states, constraining marketing language for protein products. France's national food safety agency enforces origin labeling and nutritional composition standards that shape product development cycles. Stakeholders must monitor evolving EU protein sustainability thresholds and national carbon accounting rules that will determine facility investment viability.
Market Dynamics
Pea protein extraction infrastructure is consolidating formulation economics across French food manufacturing, as Roquette Frères and specialized fractionators scale capacity to meet sports nutrition demand. ANSM novel food assessments and EFSA health claim protocols are compressing product development timelines while enforcing stricter substantiation standards.
Growth Catalysts
- EFSA harmonized health claims:Standardized protein quality scoring enables cross-border marketing for French sports nutrition brands, reducing regulatory fragmentation across EU member states.
- Fermentation-derived proteins:Precision fermentation capacity expansion creates novel ingredient streams for dairy alternatives, attracting capital from institutional investors focused on sustainable food systems.
- Île-de-France fitness density:Metropolitan Paris hosts the highest concentration of CrossFit boxes and boutique gyms in continental Europe, concentrating demand for high-dose protein supplementation.
Market Restraints
- Yellow pea price volatility:Drought cycles in Canadian prairie provinces disrupt raw material flows to Roquette Frères' Vic-sur-Aisne facility, compressing margin predictability for isolate grades.
- Whey fractionation concentration:Groupe Lactalis controls access to premium isolate streams from Normandy dairy basins, creating supply bottlenecks for emerging sports nutrition formulators.
- ANSM novel food timelines:Cell-cultured and precision-fermented protein assessments extend 18-24 months, delaying commercialization for alternative protein entrants.
Strategic Opportunities
- Occitanie livestock integration:Underutilized dairy processing infrastructure in southwestern France offers retrofit potential for hybrid animal-plant protein facilities.
- CSRD-aligned carbon accounting:Mandatory Scope 3 disclosure creates procurement preference for regionally sourced pea protein with verified low-emission transport.
- Direct-to-consumer subscription models:Personalized protein blending platforms bypass traditional pharmacy and mass retail channels, capturing margin from convenience-seeking urban professionals.
Industry Challenges
- Protein functionality R&D talent:Formulation chemists with expertise in plant protein solubility and emulsion stability command premium compensation, constraining mid-tier manufacturer hiring.
- Clean label certification complexity:Organic, non-GMO, and carbon-neutral verifications require parallel audit streams, extending product launch timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Protein Market |
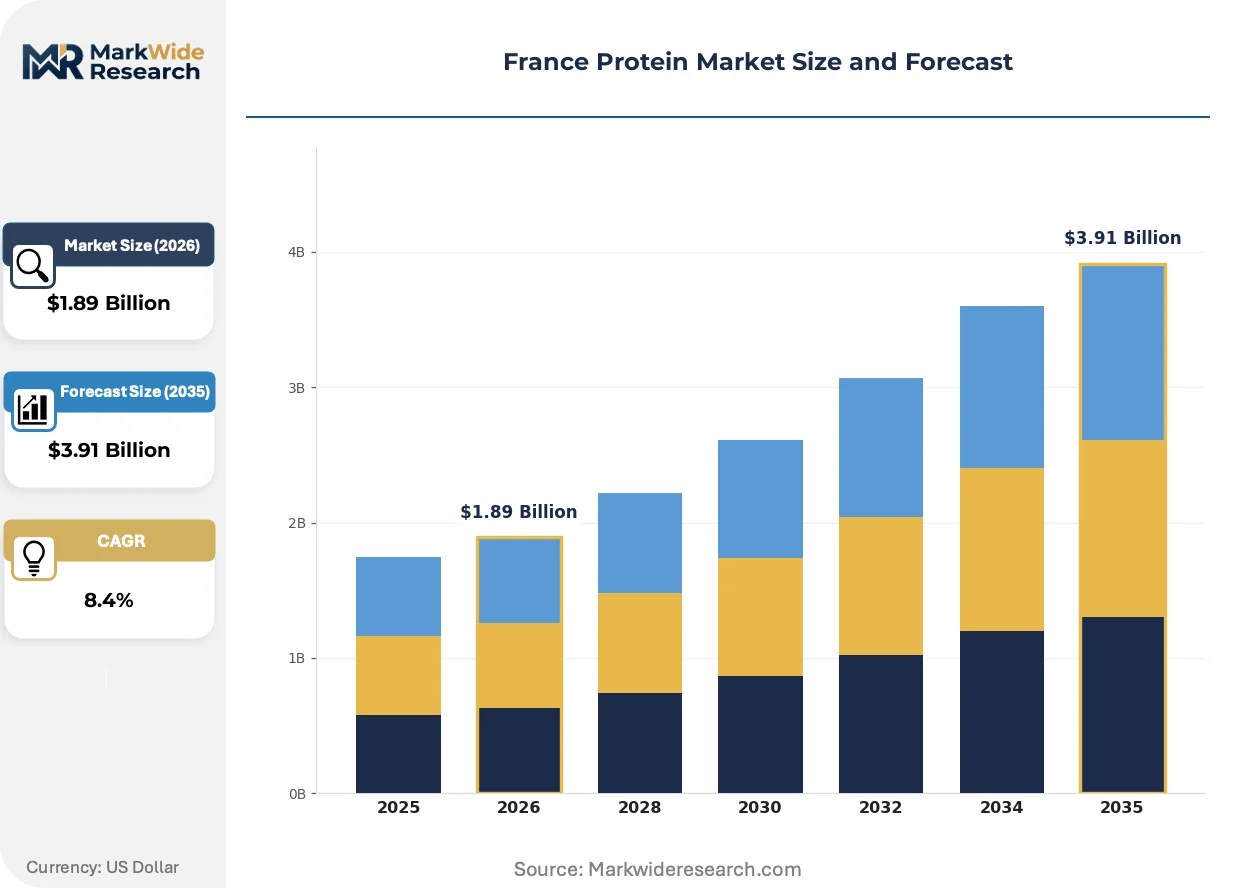
| Market Size in 2026 | $1.89 Billion |
| Market Size in 2035 | $3.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source Type: Whey, Casein, Pea, Rice, Hemp, Egg Application: Sports Nutrition, Dietary Supplements, Functional Foods, Infant Nutrition, Weight Management, Clinical Nutrition Form: Powder, Liquid, Ready-to-Drink, Bars Customer Type: Health Clubs, Pharmacies, Nutritionists, Specialty Stores |
| Companies Covered | Roquette Frères, Danone, Bonduelle, Groupe Lactalis, Cargill Incorporated, Arla Foods amba, Nestlé, Sodiaal Union SCA, Agrial Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Protein Market Shifts & Advancements
Bioprocessing advances and regulatory tightening are converging to reshape ingredient sourcing and product positioning across French protein applications. Formulators now balance functional performance against sustainability credentials in procurement decisions.
Membrane filtration technology is absorbing capital allocation previously directed toward chemical precipitation methods. Dairy processors in Brittany and Normandy are retrofitting ultrafiltration skids to capture native whey fractions with higher bioactivity retention. This shift is compressing commodity whey concentrate margins while elevating pricing power for isolate and hydrolysate grades.
France's national food safety agency is enforcing origin labeling requirements that mandate disclosure of protein source geography and primary processing location. Manufacturers must reformulate supply agreements to maintain "Made in France" positioning on retail packaging. Sports nutrition brands with export ambitions to Germany and Benelux markets are most affected, accelerating dual-sourcing strategies.
Subscription-based personalized nutrition is displacing pharmacy-centric protein retail in metropolitan areas. Digital-native brands offer algorithm-driven blending based on activity level, dietary restriction, and microbiome data, capturing share from traditional mass-market powders. This pattern is most visible in Paris and Lyon, where same-day delivery infrastructure supports perishable ingredient incorporation.
France Protein Market Segmentation
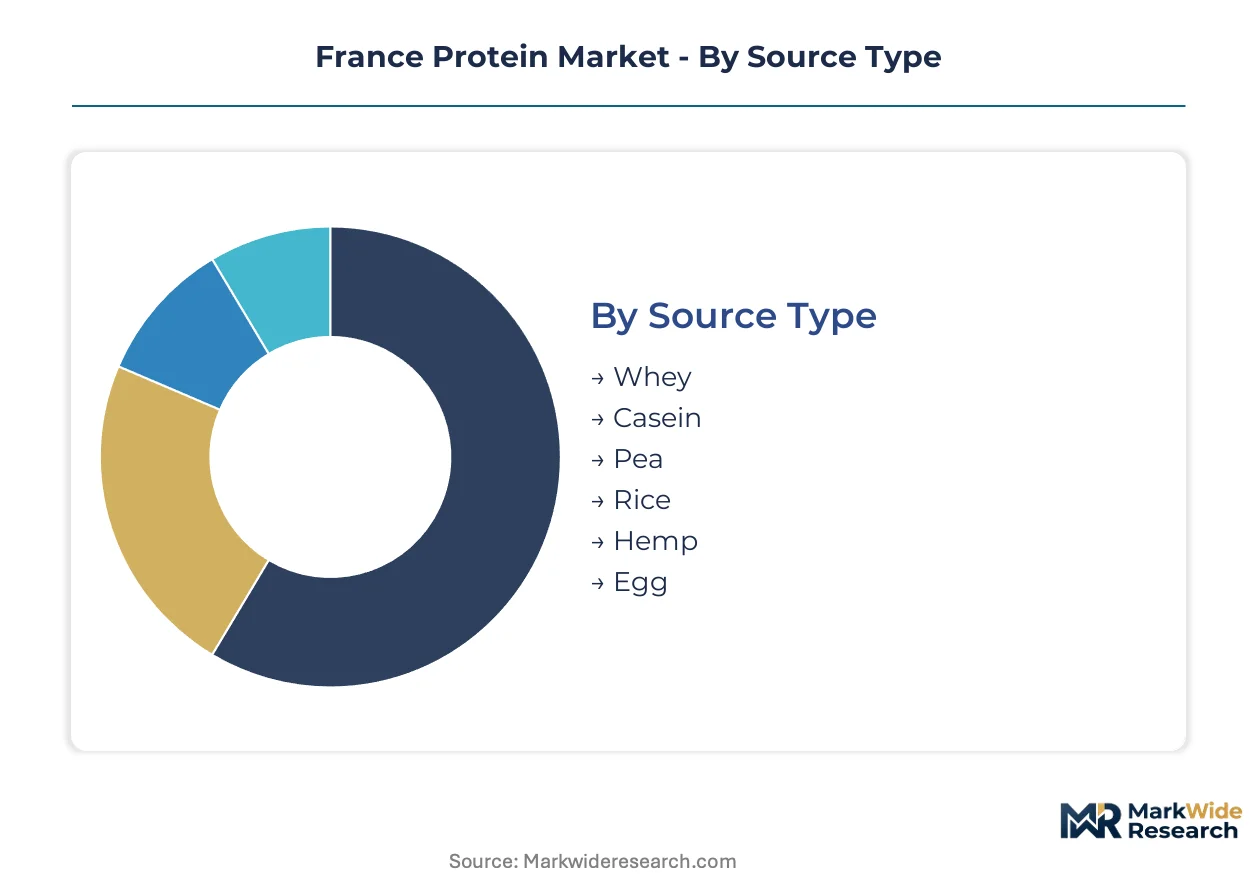
Protein segmentation in France reflects supply chain control points and formulation economics rather than simple demand categorization. Manufacturers align procurement strategies with the concentration of fractionation infrastructure and regulatory scrutiny intensity.
Source Type:
Supply concentration around specific extraction technologies and raw material basins determines competitive access and margin structures across protein categories.
- Whey:Rapidly absorbed branched-chain amino acid profile supports muscle protein synthesis timing protocols. Demand concentrates in Île-de-France sports nutrition brands competing on bioavailability claims; Groupe Lactalis' Normandy fractionation dominance constrains independent formulator access to premium isolate grades.
- Pea:Hypoallergenic legume isolate with complete essential amino acid distribution and neutral flavor compatibility. Roquette Frères' Vic-sur-Aisne facility anchors European supply; drought cycles in Canadian prairie growing regions introduce raw material price volatility that compresses margin predictability.
- Casein:Slow-digesting micellar structure enables overnight amino acid release applications.
- Rice:Grain-derived hypoallergenic option with lower lysine content requiring complementary protein pairing.
- Hemp:Cannabis sativa seed protein with omega fatty acid co-extraction and fiber content.
- Egg:Albumen and whole egg concentrates with high biological value scores and baking functionality.
Whey absorbs the bulk of installed capacity; pea is expanding most quickly.
Application:
Margin profiles and regulatory exposure vary sharply across end-use categories, with ANSM novel food assessments and EFSA health claim protocols creating divergent compliance burdens.
- Sports Nutrition:High-dose protein powders, RTDs, and bars targeting resistance training and endurance recovery protocols. Paris metropolitan boutique gym density and CrossFit box concentration drives formulation innovation; subscription direct-to-consumer models are displacing pharmacy retail in urban cores.
- Dietary Supplements:Capsule and tablet formats with specific amino acid targeting for metabolic support. EFSA protein quality scoring harmonization enables cross-border marketing standardization; clean label certification complexity extends launch timelines.
- Functional Foods:Protein-fortified dairy alternatives, baked goods, and beverages with nutritional positioning.
- Infant Nutrition:Hydrolyzed and specialized protein fractions for allergy management and developmental requirements.
- Weight Management:Satiety-focused formulations with controlled caloric density and macronutrient balance.
- Clinical Nutrition:Medical food applications for malabsorption, sarcopenia, and post-surgical recovery protocols.
Functional Foods commands the largest revenue base; Sports Nutrition is climbing the fastest.
Form:
Packaging and shelf-stability requirements shape manufacturing asset allocation and distribution channel compatibility.
- Powder:Bulk dry blends with extended stability and industrial food production flexibility. Brittany and Normandy membrane filtration retrofits are elevating native whey bioactivity retention; powder occupies dominant volume position due to blending versatility.
- Ready-to-Drink:Aseptically processed liquid formats with convenience positioning and premium pricing. Same-day delivery infrastructure in Paris and Lyon supports perishable ingredient incorporation; RTD margins reflect cold chain complexity.
- Liquid:Concentrated or ready-to-serve formats with shorter shelf life and refrigerated distribution.
- Bars:Extruded or cold-pressed solid formats with binding and texture engineering requirements.
Powder absorbs the bulk of installed capacity; Ready-to-Drink is gaining share fastest.
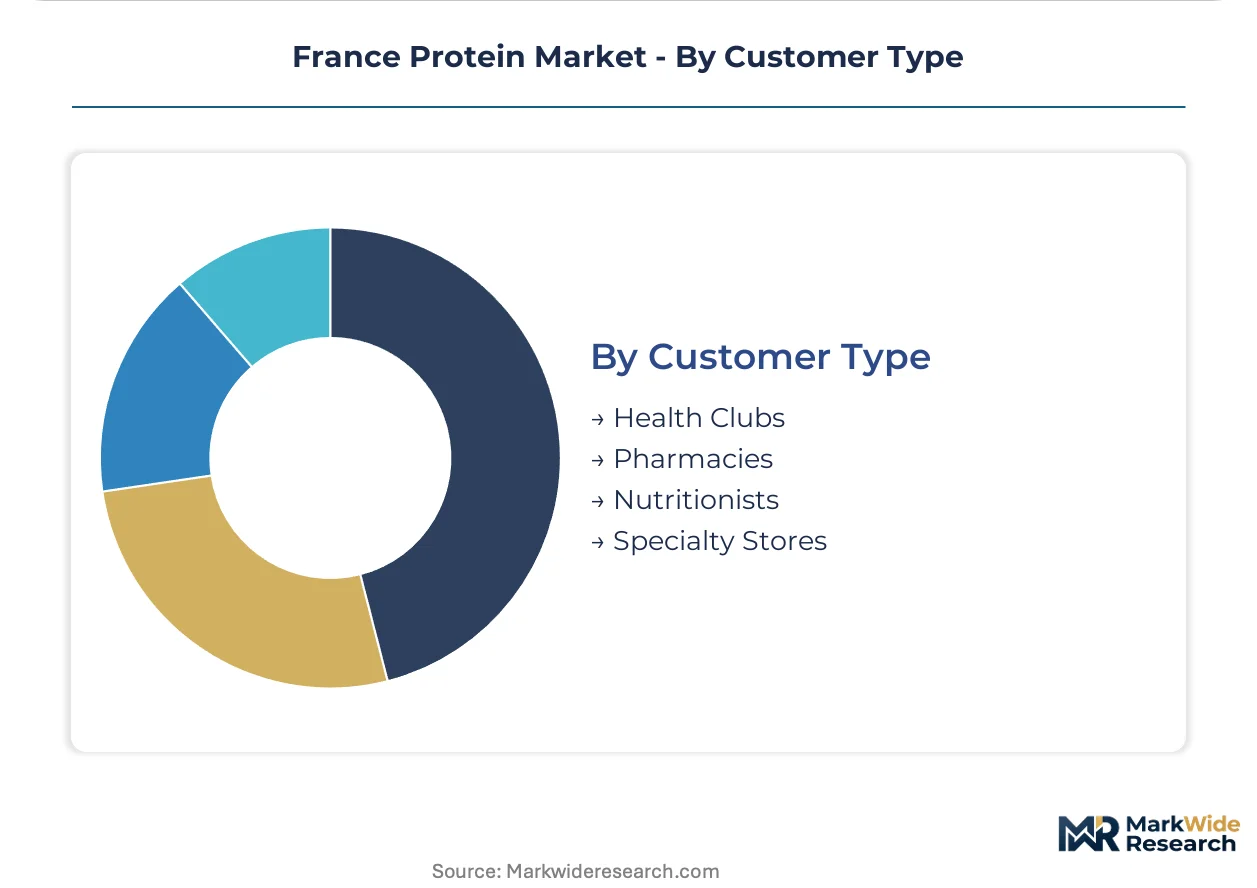
Customer Type:
Channel structure determines pricing power and consumer data access, with digital-native brands bypassing traditional intermediaries.
- Health Clubs:On-site retail and branded partnership programs with member loyalty integration. Metropolitan Paris fitness density concentrates high-dose supplementation demand; club-exclusive SKUs enable margin capture from convenience-seeking urban professionals.
- Pharmacies:Traditional retail with pharmacist consultation and reimbursement pathway access. ANSM labeling enforcement and origin disclosure requirements shape product development; pharmacy channel is losing share to direct subscription models.
- Nutritionists:Practitioner-directed recommendations with personalized protocol alignment.
- Specialty Stores:Curated retail with organic, non-GMO, and sustainability credential filtering.
Pharmacies retain the largest transaction volume; Health Clubs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protein demand concentrates in the Île-de-France metropolitan corridor, where fitness density and affluent consumer bases drive premium supplementation. The national market fragments across distinct regional production basins and consumption clusters.
Île-de-France
Paris hosts continental Europe's densest concentration of boutique gyms and CrossFit facilities, anchoring high-dose protein consumption. ANSM labeling enforcement mandates origin disclosure for all fortified products sold through pharmacy and direct-to-consumer channels. Roquette Frères maintains headquarters and R&D operations in Lestrem while serving formulation demand from the capital's sports nutrition brands.
Hauts-de-France
Vic-sur-Aisne anchors European pea protein extraction capacity, with fractionation infrastructure supplying isolate grades to food manufacturers. EFSA health claim harmonization enables cross-border shipment to Benelux markets from this northern basin. The facility draws yellow pea supply from Canadian prairie growers, exposing margin structures to drought-cycle volatility.
Normandy
Dairy processing clusters in Calvados and Manche sustain whey fractionation dominance for premium isolate streams. Groupe Lactalis controls access to native whey bioactive fractions through membrane filtration retrofits. The regional dairy basin supplies sports nutrition formulators competing on bioavailability positioning.
Auvergne-Rhône-Alpes
Lyon's metropolitan protein retail shifts toward subscription direct-to-consumer models, displacing traditional pharmacy channels. CSRD-aligned carbon accounting creates procurement preference for verified low-emission transport corridors. Same-day delivery infrastructure supports perishable ingredient incorporation in personalized nutrition platforms.
Occitanie
Southwestern dairy processing infrastructure offers retrofit potential for hybrid animal-plant protein facilities. Regional livestock integration remains underutilized relative to northern production basins. Emerging fermentation-derived protein capacity attracts institutional capital focused on sustainable food system transitions.
France Protein Market Competitive Landscape
Capacity expansion dominates the current landscape as fractionators scale extraction infrastructure to capture sports nutrition demand. The vendor base concentrates around three control points: dairy whey dominance, legume isolate extraction, and precision fermentation capacity. Strategic archetypes include integrated dairy processors controlling raw material basins, specialized plant protein fractionators with proprietary extraction IP, and multinational food conglomerates diversifying through M&A. Competitive moves center on backward integration into raw material sourcing and geographic expansion into adjacent EU markets.
Among French-based processors, Roquette Frères, Groupe Lactalis, and Danone occupy distinct archetype positions. Roquette Frères exemplifies the specialized fractionator model with captive pea protein extraction infrastructure. Groupe Lactalis anchors the integrated dairy processor tier through Normandy whey fractionation control. Danone represents the diversified multinational archetype, balancing dairy and alternative protein portfolios through fermentation capabilities.
| Leading Market Players |
|---|
| Roquette Frères |
| Danone |
| Bonduelle |
| Groupe Lactalis |
| Cargill Incorporated |
| Arla Foods amba |
| Nestlé |
| Sodiaal Union SCA |
| Agrial Group |
| Others |
Supply & Pricing Matrix
Metropolitan Paris sports nutrition brands command premium positioning through subscription direct-to-consumer models that bypass traditional pharmacy intermediaries. This buyer concentration enables value-based pricing for personalized protein blends while commodity whey and pea isolates face margin compression from raw material volatility.
Pricing Analysis
Volume concentrates in standard-grade whey concentrates serving mass-market functional foods, while margins accrue to premium isolate and hydrolysate grades targeting bioavailability claims. Price differentiation rests on certification tier—organic and non-GMO verifications command 15-25% premiums—and regional origin labeling compliance. Pricing pressure stems from Canadian yellow pea drought cycles disrupting Roquette Frères' input costs. Independent formulators show highest price sensitivity due to Groupe Lactalis' whey fractionation dominance, while established sports nutrition brands absorb premiums for supply security.
Supply Chain Analysis
Freight cost inflation across Atlantic and Mediterranean corridors elevates landed costs for Canadian pea imports serving Vic-sur-Aisne extraction. Supply concentrates in France for dairy whey, Canada for yellow pea feedstock, and Benelux for fermentation-derived alternatives. Raw material dependencies include prairie-grown legumes, Normandy milk solids, and precision fermentation feedstocks. Single-source vulnerability runs through Roquette Frères' European pea protein dominance. Distribution runs through hybrid direct-to-consumer platforms in Paris and Lyon alongside traditional pharmacy and health club channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's protein sector sits at a technology inflection as membrane filtration displaces chemical precipitation in whey fractionation, reshaping cost structures and bioactivity retention economics.
For Market Incumbents: Deploy captive extraction capacity as the defensive anchor. Groupe Lactalis should retrofit additional ultrafiltration skids in Normandy to capture native whey fractions before commodity concentrate margins erode further. Roquette Frères must secure alternative yellow pea sourcing from Baltic or Ukrainian growers to dilute Canadian drought exposure. Both moves counter emerging precision fermentation entrants and alternative protein substitutes. For New Entrants and Emerging Players: Boutique gym partnerships in Île-de-France offer the most penetrable channel wedge. White-space exists in personalized subscription platforms incorporating microbiome-driven blending algorithms for affluent urban professionals. Occitanie's underutilized dairy infrastructure presents retrofit opportunity for hybrid animal-plant facilities with lower incumbent saturation. Direct-to-consumer positioning bypasses Groupe Lactalis supply bottlenecks. For Investors and Strategic Acquirers: The window for entry favors specialized fractionators with proprietary extraction IP over commodity processors. Long-term viability hinges on CSRD-aligned carbon accounting capabilities and verified Scope 3 disclosure infrastructure. Acquisition targets should demonstrate dual-source raw material strategies and ANSM regulatory navigation experience. Watch for EFSA health claim harmonization enforcement as the inflection signal accelerating cross-border consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Brittany and Normandy dairy processors capture premium isolate grades with higher bioactivity retention. |
| Dual-Source Pea Procurement | Roquette Frères and competitors dilute Canadian drought risk through Baltic and Black Sea supplier development. |
| Precision Fermentation Scale-Up | Danone and institutional capital deploy fermentation capacity for dairy-alternative protein streams. |
| Direct-to-Consumer Platform Launch | Digital-native brands bypass pharmacy channels using same-day delivery infrastructure in Paris and Lyon. |
| CSRD Carbon Accounting Integration | Verified low-emission transport corridors create procurement preference for regional pea protein sourcing. |
Research Methodology
Multi-period observation of Roquette Frères capacity utilization, Groupe Lactalis fractionation output, and ANSM novel food assessment timelines anchored the trend analysis, supplemented by interviews with sports nutrition formulators, dairy procurement directors, and membrane filtration equipment suppliers. Secondary validation drew from EFSA health claim registers, CSRD disclosure frameworks, and customs trade data for yellow pea and whey concentrate flows. Bottom-up facility capacity modeling and top-down consumption surveys were triangulated against subscription platform transaction data.
Segment-weighting applied differential growth assumptions across sports nutrition, dietary supplements, and functional foods, with source-type splits for whey, pea, and emerging fermentation-derived proteins. CAGRs were derived from installed capacity expansion schedules, fitness facility density projections, and regulatory approval velocity. Forecast inputs included EFSA harmonization timelines, drought-cycle probability distributions for Canadian prairie regions, and CSRD Scope 3 disclosure mandates.
Caveats apply where ANSM novel food assessment delays, Canadian agricultural weather shocks, or EFSA health claim rejections could materially shift the outlook. Forecasts reflect documented assumptions around capacity commissioning schedules and consumer subscription adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Distillers Corn Oil Market
Ingredients
Lupin Flour Market
Ingredients
Tryptose Market
Ingredients
Plant Protein Ingredients Market
Ingredients
South America Spirulina Extract Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Global Tomato Powder Market
Ingredients
Dairy Ingredients Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Almond Ingredients Market
Ingredients
Vegetable Glycerin Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Cocoa Market
Ingredients
Wort Concentrate Market
Ingredients
Algae-Based Ingredients Market