
 Pine Needle Oil Market | 2026-2036
Pine Needle Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Pine Needle Oil Market Analytics
Aftermarket service revenue from custom blending and private-label formulation is tilting margin pools away from commodity bulk supply. Mountain Rose Herbs leverages its direct farm relationships to control raw material provenance. Now Foods sustains broad retail shelf presence across mass-market channels. Biolandes specializes in certified organic distillation, occupying a premium tier that commands higher unit economics.
Pine needle oil is a volatile essential oil obtained by steam distillation from needles of Pinus sylvestris and related species, typically containing alpha-pinene, beta-pinene, and limonene as dominant terpenes, and functions as an antimicrobial, decongestant, and fragrance agent across therapeutic and industrial applications. The essential oil segment dominates value capture due to concentration requirements in pharmaceutical and cosmetology applications, while the aromatherapy application segment records the fastest trajectory as wellness consumers shift toward inhalation and topical diffusion protocols. Specialty stores remain the critical distribution channel for quality-assured grades, though online retail is gaining velocity among direct-to-consumer botanical brands.
REACH in Europe governs terpene content declarations and safety data sheet obligations for cosmetic and cleaning product formulations, while FDA oversight in the United States shapes labeling for any therapeutic claims attached to pine needle oil products. EMA standards for herbal medicinal products create a compliance threshold that filters out uncertified distillers from pharmaceutical supply chains. Stakeholders must monitor evolving VOC emission rules in multiple jurisdictions, as these determine whether solvent-free steam distillation becomes a mandatory rather than preferred extraction method.
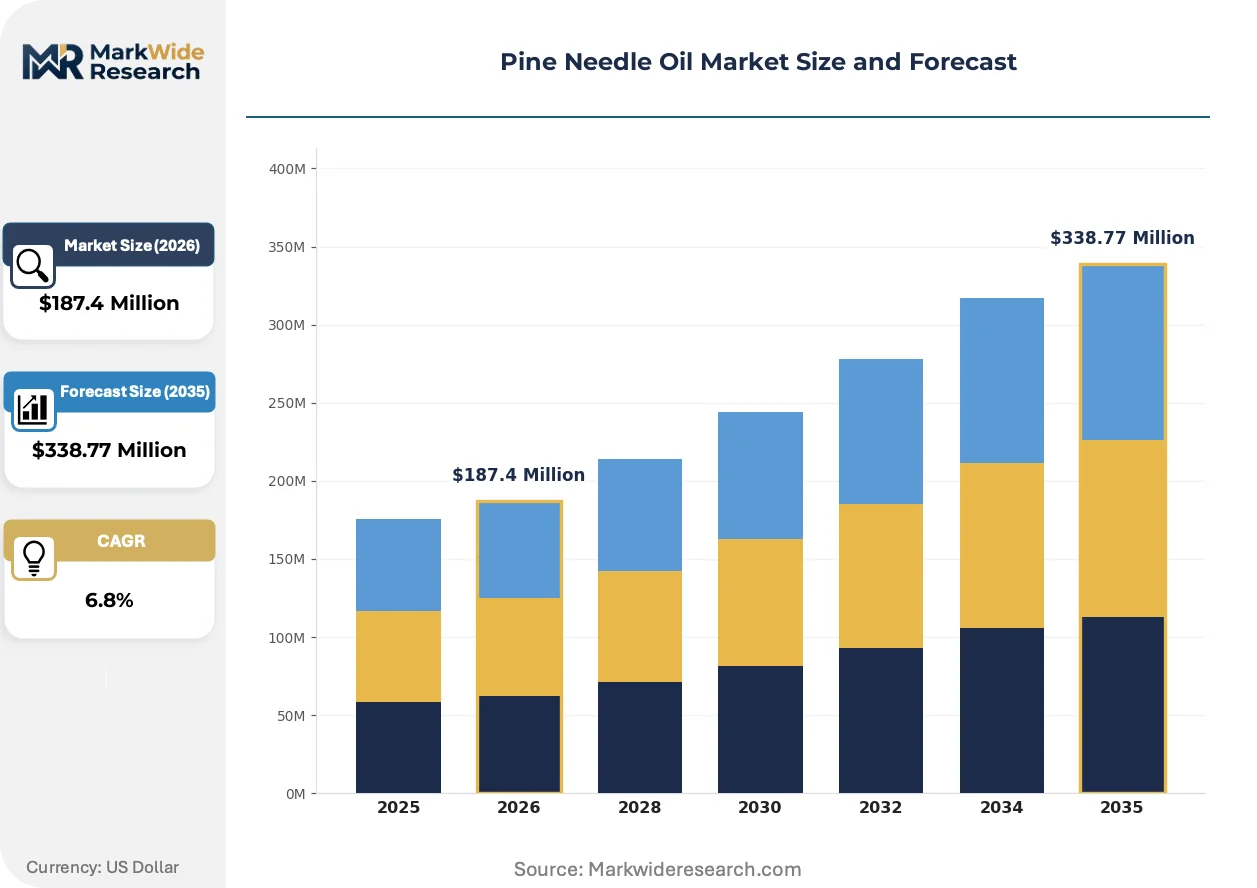
Market Dynamics
REACH compliance and tightening volatile organic compound standards are forcing steam distillation upgrades across European and North American supply chains, while certified organic demand from French fragrance houses concentrates procurement toward provenance-controlled sources.
Growth Catalysts
- Aromatherapy protocol adoption:Spa and wellness centers in France and Germany now specify certified organic grades for inhalation and topical diffusion, pulling volume toward pharmaceutical-grade distillers.
- REACH terpene declarations:ECHA mandates for safety data sheets and content transparency filter uncertified suppliers from cosmetic and cleaning product formulations.
- Steam distillation preference:Solvent-free extraction methods gain preference over hexane-based processes as VOC emission rules tighten in multiple jurisdictions.
Market Restraints
- Raw material concentration:Pinus sylvestris needle supply concentrates in Baltic and Alpine forest zones, exposing processors to climate-driven harvest volatility.
- Substitution pressure:Synthetic alpha-pinene from petrochemical routes undercuts natural distillate pricing in industrial fragrance applications.
- Certification cost barriers:EMA herbal medicinal product standards and USDA organic accreditation impose multi-year compliance timelines that exclude small-scale distillers.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online retail platforms enable botanical brands to bypass specialty store markups and capture margin through subscription models.
- Pharmaceutical compounding partnerships:French fragrance houses seek therapeutic-grade supply for decongestant and antimicrobial formulations.
- Private-label formulation services:Custom blending capabilities allow distillers to capture aftermarket revenue from wellness brands lacking in-house R&D.
Industry Challenges
- Skilled distiller scarcity:Traditional steam distillation expertise for terpene preservation is concentrating among aging craft practitioners in rural France and Bulgaria.
- Batch-to-batch standardization:Natural variation in needle harvest chemistry complicates consistent alpha-pinene and limonene ratios for pharmaceutical clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pine Needle Oil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Extract, Infusion, Concentrate Application: Aromatherapy, Cosmetology, Pharmaceuticals, Cleaning Products End User: Households, Commercial, Spa & Wellness, Healthcare Facilities Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Now Foods, Mountain Rose Herbs, Aroma Land, Global Natural Spice, Biolandes, Scatters Oils, Hobart Company, Still Pure, Heng Cheng Natural Perfume Oil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pine Needle Oil Market Evolving Landscape
Extraction technology and compliance architecture are reshaping competitive positioning in pine needle oil supply chains. Three developments merit particular attention for their structural implications.
Spectroscopic quality verification is digitizing batch release protocols for organic certification. Pharmaceutical compounders in France and Germany now require terpene fingerprint documentation for every lot. This technology compresses quality assurance timelines from weeks to hours while excluding suppliers lacking analytical capabilities.
REACH Annex XVII restrictions on volatile organic compounds in consumer products are mandating reformulation across European cleaning and fragrance applications. Manufacturers must declare exact terpene concentrations and submit updated safety data sheets. Cosmetic formulators are responding by sourcing from distillers with pre-validated compliance documentation.
Wellness consumers now demand provenance transparency that extends to forest coordinates and harvest dates. Specialty stores in Paris and Berlin capture this preference through QR-linked supply chain visualization. Direct-to-consumer brands accelerate this shift by marketing single-origin distillation stories that mass-market channels cannot replicate.
Pine Needle Oil Market Segmentation
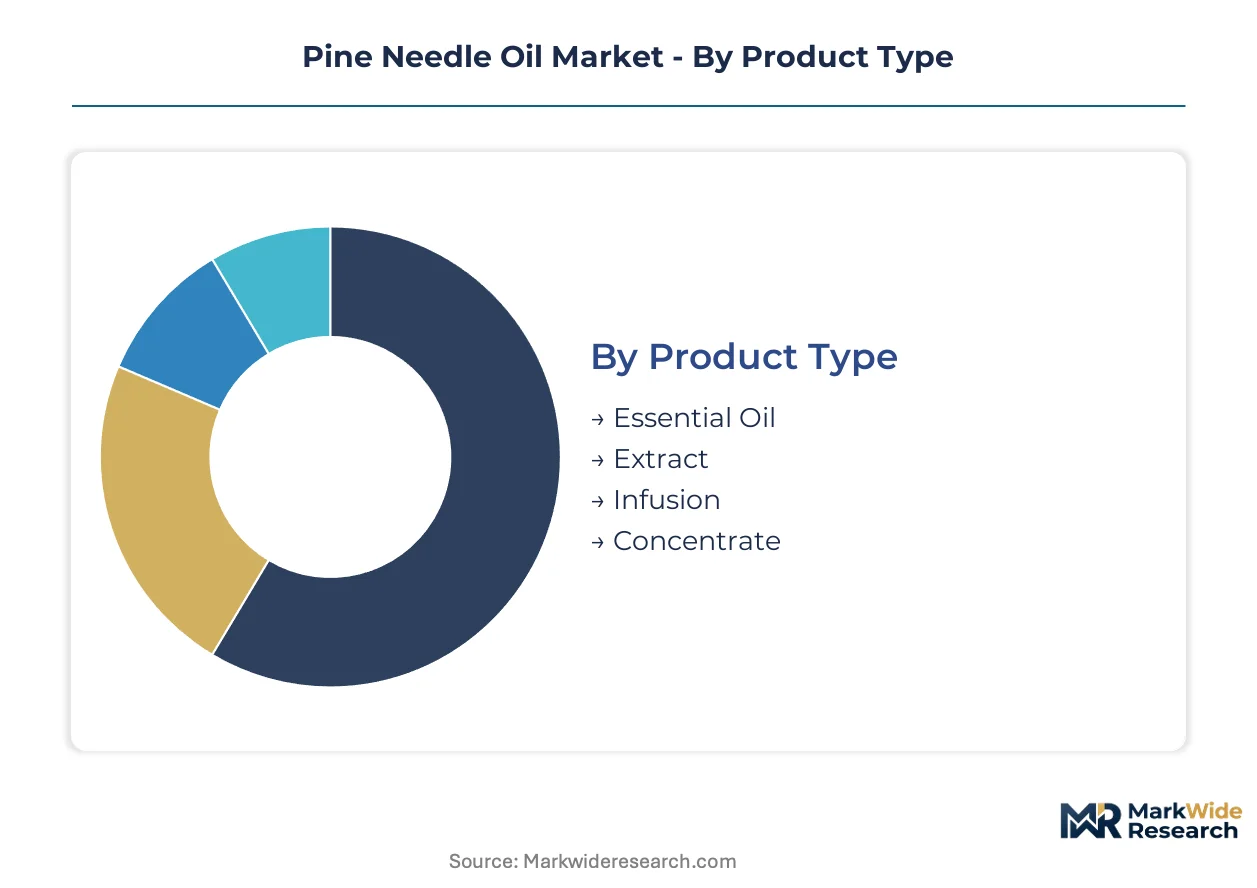
Segmentation in pine needle oil markets separates commodity bulk supply from premium therapeutic grades, with certification status and distribution channel determining margin capture. Understanding these divides reveals where value concentrates and which customer types drive specification requirements.
Product Type:
Mature distillation formats coexist with emerging concentration technologies, each commanding distinct price tiers based on terpene retention and solvent status.
- Essential Oil:Steam-distilled volatile oil containing alpha-pinene, beta-pinene, and limonene as dominant terpenes. Pharmaceutical compounders in France and Germany specify this grade for decongestant formulations, with REACH-compliant documentation now mandatory for batch release.
- Extract:Concentrated preparation obtained through solvent or supercritical processing, yielding higher terpene density per unit volume. Cosmetic formulators favor this format for fragrance compounding where scent longevity matters more than inhalation safety.
- Infusion:Needle material steeped in carrier oils for extended periods, producing lower terpene concentrations suitable for topical wellness applications.
- Concentrate:Highly refined product with standardized terpene ratios, positioned for industrial fragrance applications where batch consistency outweighs natural provenance claims.
Essential oil handles the majority of throughput; concentrate is expanding most quickly in industrial fragrance substitution.
Application:
Cost tier separation runs from premium therapeutic claims to economy cleaning formulations, with regulatory burden increasing at each ascending price level.
- Aromatherapy:Inhalation and topical diffusion protocols in spa environments demand certified organic grades with full provenance documentation. French wellness centers now require QR-linked supply chain visualization for every bottle.
- Cosmetology:Fragrance and antimicrobial functions in skincare and personal care products. ECHA terpene declaration mandates filter out uncertified distillers from European cosmetic supply chains.
- Pharmaceuticals:Decongestant and antimicrobial therapeutic formulations regulated under EMA herbal medicinal product standards. Multi-year compliance timelines exclude small-scale suppliers from this channel.
- Cleaning Products:Industrial and household formulations where natural positioning competes with synthetic alpha-pinene on cost. REACH Annex XVII VOC restrictions force reformulation toward lower-emission terpene concentrations.
Cosmetology absorbs the largest volume share; aromatherapy gains share fastest as wellness consumers shift toward inhalation protocols.
End User:
Customer type determines specification intensity, from mass-market households demanding basic purity to healthcare facilities requiring pharmaceutical-grade documentation.
- Households:Individual consumers purchasing through retail channels for personal aromatherapy and cleaning applications. Online subscription models capture this segment through direct-to-consumer botanical brands.
- Commercial:Industrial buyers integrating pine needle oil into fragrance compounds, cleaning formulations, and manufacturing processes. Synthetic substitution pressure concentrates in this price-sensitive tier.
- Spa & Wellness:Professional service providers specifying certified organic grades for client treatments. French and German spa chains now mandate inhalation-safety documentation for all essential oil purchases.
- Healthcare Facilities:Hospitals and clinics sourcing therapeutic-grade supply for decongestant and antimicrobial applications. EMA compliance thresholds create exclusive supplier relationships with proven pharmaceutical distillers.
Commercial end users move the highest absolute volumes; spa and wellness is climbing the fastest on specification premium capture.
Distribution Channel:
Supply concentration varies by channel, with specialty stores maintaining quality gatekeeper status while online retail erodes traditional markup structures.
- Online Retail:Direct-to-consumer platforms enabling botanical brands to bypass intermediaries and capture margin through subscription models. Provenance transparency through QR-linked forest coordinates differentiates premium offerings.
- Specialty Stores:Physical retailers in Paris, Berlin, and other European cities curating certified organic grades with full documentation. These outlets remain critical for quality-assured pharmaceutical and therapeutic supply.
- Wholesale:Bulk distribution to formulators, compounders, and industrial buyers purchasing by volume rather than brand. REACH pre-validated documentation increasingly determines supplier selection in this channel.
- Direct Sales:Distiller-to-manufacturer relationships for custom blending and private-label formulation. Aftermarket service revenue from this channel tilts margin pools away from commodity bulk supply.
Wholesale channels handle the majority of volume throughput; online retail shows the steepest expansion trajectory as direct-to-consumer brands scale subscription infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in industrial fragrance applications remain acutely price-sensitive, while spa and wellness centers in France and Germany absorb substantial premiums for certified organic grades with full provenance documentation.
France
French fragrance houses and pharmaceutical compounders drive specification intensity for therapeutic-grade pine needle oil. ANSM enforces stringent documentation requirements for herbal medicinal products entering decongestant formulations. The Grasse cluster concentrates distillation expertise where craft practitioners supply provenance-controlled batches to luxury wellness brands.
Germany
German spa chains and aromatherapy clinics mandate certified organic grades with QR-linked supply chain visualization. ECHA REACH compliance filters uncertified suppliers from cosmetic and cleaning product formulations. The Bavarian Forest region hosts distillers specializing in terpene preservation for pharmaceutical clients.
United States
Mass-market retailers and direct-to-consumer botanical brands compete on subscription model economics. FDA oversight shapes labeling for therapeutic claims attached to pine needle oil products. The Pacific Northwest concentrates wildcrafting operations supplying raw Pinus sylvestris needle material to domestic distillers.
Bulgaria
Bulgarian processors serve as a cost-competitive source for bulk essential oil entering European wholesale channels. The country's national pharmaceutical regulator aligns documentation standards with EMA herbal medicinal product thresholds. The Rhodope Mountains harbor aging craft practitioners whose steam distillation expertise is concentrating among rural specialists.
China
Chinese manufacturers supply concentrated extracts and industrial fragrance compounds at scale. GB standards govern volatile organic compound emissions in consumer product formulations. The Yunnan province hosts needle harvesting operations feeding supercritical extraction facilities serving Asian cosmetic markets.
Pine Needle Oil Market Competitive Landscape
Capability concentration sits with craft distillers possessing generational steam distillation expertise; scale advantage sits with integrated botanical houses controlling multi-channel distribution. The market structures around three tiers: pharmaceutical-grade specialists, mass-market retailers, and private-label formulators. Consolidation pressure intensifies as REACH compliance costs exclude small-scale operators. Dominant competitive moves include backward integration into raw material provenance and direct-to-consumer channel expansion bypassing traditional wholesale markups.
Within the certified organic tier, Biolandes and Mountain Rose Herbs exemplify provenance-controlled positioning. Now Foods anchors mass-market presence across broad retail shelf networks. These three occupy distinct archetypes—premium distillation, direct farm relationships, and scale distribution—each capturing margin through different channel configurations rather than competing directly on specification.
| Leading Market Players |
|---|
| Now Foods |
| Mountain Rose Herbs |
| Aroma Land |
| Global Natural Spice |
| Biolandes |
| Scatters Oils |
| Hobart Company |
| Still Pure |
| Heng Cheng Natural Perfume Oil |
| Others |
Value Network & Pricing Analysis
Raw material concentration in Baltic and Alpine forest zones creates harvest volatility that compresses margin spreads between pharmaceutical-grade and commodity bulk tiers while forcing processors toward backward integration into provenance-controlled sourcing.
Pricing Analysis
Aftermarket service revenue from custom blending and private-label formulation now drives lifetime value capture for distillers with in-house R&D capabilities. Three-tier pricing structure across certified organic, conventional therapeutic, and industrial fragrance grades reflects certification burden and terpene standardization intensity. Cost compression in the industrial tier is intensifying because synthetic alpha-pinene from petrochemical routes undercuts natural distillate pricing. Commercial fragrance compounders exhibit the highest price sensitivity; French spa and wellness chains absorb substantial premiums for QR-linked provenance documentation.
Supply Chain Analysis
Tariff exposure between Baltic raw material zones and French processing clusters dominates supply chain risk calculus for European distillers. Needle harvesting concentrates in Estonia, Latvia, and the Bavarian Forest region of Germany; distillation capacity clusters in Grasse, the Rhodope Mountains of Bulgaria, and the Pacific Northwest of the United States. Supply chains rest on Pinus sylvestris needle availability, steam distillation equipment, and spectroscopic quality verification systems. Single-source vulnerability in aging craft practitioner networks threatens batch consistency for pharmaceutical clients. Distribution runs through specialty store gatekeepers in Paris and Berlin alongside direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pine needle oil sits in early-cycle expansion as wellness consumers shift inhalation protocols from synthetic fragrances toward certified organic botanicals with full supply chain transparency.
For Market Incumbents: Pre-empt synthetic substitution pressure by deepening backward integration into forest coordinate traceability and captive steam distillation capacity. Lock in multi-year offtake agreements with French fragrance houses before REACH compliance costs exclude smaller competitors. Certification investment in EMA herbal medicinal product standards represents the critical defensive moat.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription models where provenance storytelling bypasses specialty store markups. Target online retail channels with single-origin distillation narratives that mass-market incumbents cannot replicate. The most penetrable white space sits in QR-linked supply chain visualization for German spa chains.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors craft distillers with generational terpene preservation expertise and pre-validated REACH documentation. Long-term viability hinges on exclusive supplier relationships with pharmaceutical compounders. Watch for spectroscopic quality verification adoption rates as the inflection signal separating analytical-capable from documentation-deficient targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Provenance | Captures margin from raw material scarcity while satisfying French fragrance house documentation requirements. |
| Spectroscopic Quality Verification Deployment | Compresses batch release timelines from weeks to hours for ECHA REACH terpene declarations. |
| Direct-to-Consumer Subscription Launch | Bypasses specialty store intermediaries and captures recurring revenue from wellness consumers. |
| EMA Herbal Medicinal Product Certification | Creates exclusive supplier status for decongestant and antimicrobial pharmaceutical formulations. |
| Private-Label Formulation Service Expansion | Captures aftermarket revenue from botanical brands lacking in-house R&D capabilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with spa procurement directors, pharmaceutical compounders, distillation plant managers, and specialty store buyers across France, Germany, and the United States. Secondary validation drew from ECHA REACH filings, ANSM herbal product registrations, customs trade data for Pinus sylvestris needle movements, and SEC disclosures from publicly traded botanical houses. Bottom-up volume estimates from distillation capacity and top-down demand segmentation were triangulated to cross-check market sizing.
Calibration against historical terpene price volatility and certification adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and distribution channel alongside regional regulatory cluster intensity. CAGRs were derived from slope analysis of adoption curves rather than extrapolation of single-year growth rates. Forecast inputs incorporated REACH enforcement timelines and wellness consumer preference shifts toward inhalation protocols.
Stress conditions across Baltic harvest yields, synthetic alpha-pinene pricing spreads, and EMA compliance exclusion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and consumer willingness-to-pay for provenance transparency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Ximenia Oil Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Global Natural Gum Market
Ingredients
Textured Wheat Protein Market
Ingredients
Cocoa Solids Market
Ingredients
Soluble Fibers Market
Ingredients
North America Potato Starch Market
Ingredients
South America Feed Yeast Market
Ingredients
Dry Molasses Products Market
Ingredients
Resistant Starch Market
Ingredients
Torula Yeast Market
Ingredients
Pomace Olive Oil Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
North America Agar Market
Ingredients
Plant-Based API Market
Ingredients
Canada Sodium Reduction Ingredients Market