
 Global Fruits and Vegetables Ingredients Market | 2026-2036
Global Fruits and Vegetables Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruits and Vegetables Ingredients Market Analysis
Project finance for cold-chain infrastructure and aseptic processing plants is tilting competitive dynamics toward capital-rich suppliers with balance-sheet depth. Cargill Incorporated leverages its grain-trading treasury function to fund captive fruit concentrate facilities in multiple hemispheres. Kerry Group anchors its position through integrated flavor-application labs that co-develop fruit-based systems with beverage clients. Döhler GmbH specializes in regional sourcing clusters, binding German technical standards to tropical supply bases.
Fruits and vegetables ingredients comprise processed or minimally altered plant materials—purees, concentrates, dried pieces, and frozen cuts—retaining organoleptic and nutritional properties through controlled thermal treatment, concentration to 65-72 Brix for juices, or rapid freezing at minus 40 degrees Celsius. These inputs serve as flavor carriers, colorants, texturizers, and clean-label fortifiers across packaged food manufacturing. Juice concentrate occupies the deepest margin pool due to capital intensity and Brix standardization barriers, while puree competes on formulation flexibility in sauces and infant nutrition. Dried fruits lead in shelf-stable snacking applications where water activity below 0.6 enables ambient distribution. Frozen vegetables dominate food-service procurement for restaurants and catering services demanding batch consistency without thaw variability.
FDA enforcement of the Food Safety Modernization Act intensifies foreign supplier verification for imported fruit purees entering US food manufacturers. EFSA pesticide residue benchmarks under EU Regulation 396/2005 redirect sourcing toward integrated farm-processing operations with traceability systems. India's FSSAI fortification directives and PLI scheme for food processing are accelerating domestic concentrate capacity. Stakeholders must monitor how divergent maximum residue limits across FDA, EFSA, and FSSAI jurisdictions reshape supplier qualification costs and origin premiums.
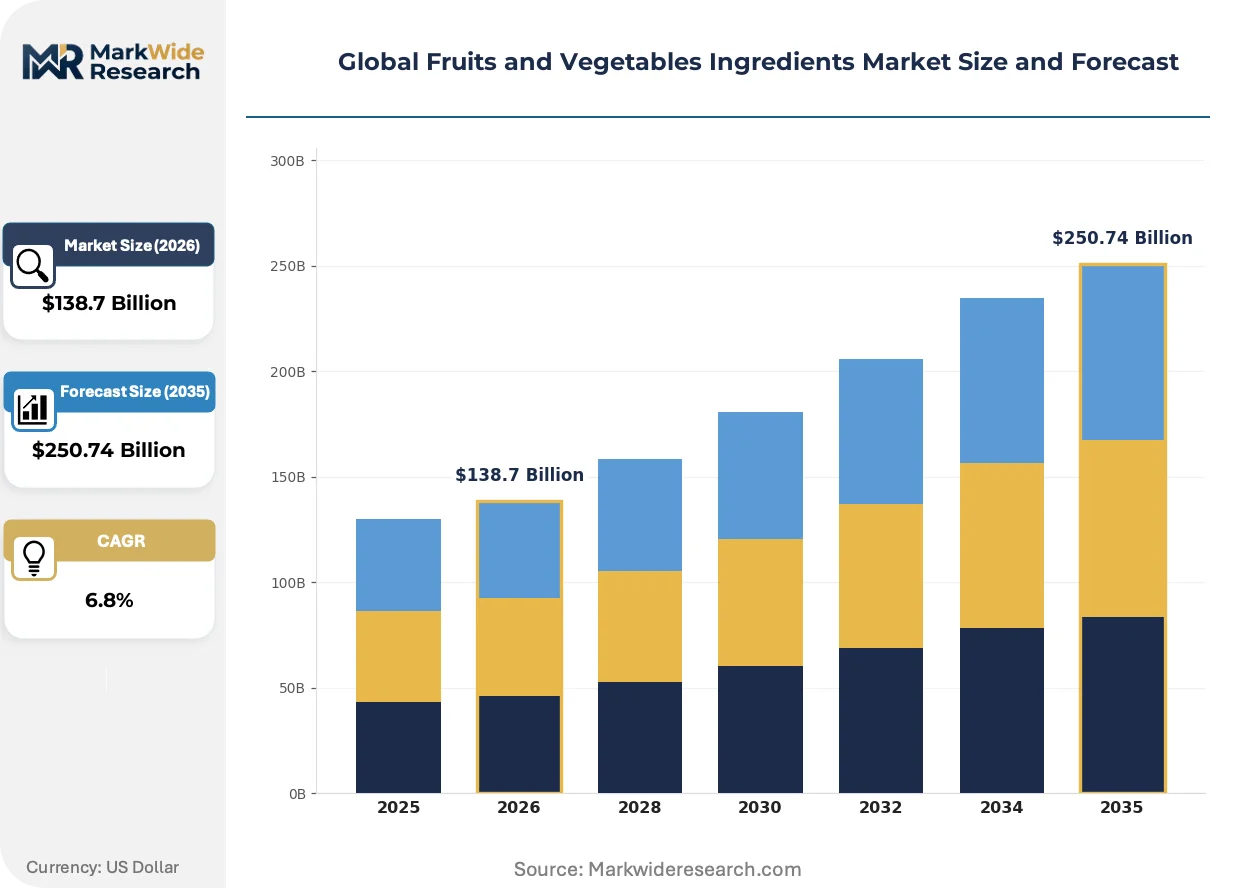
Market Dynamics
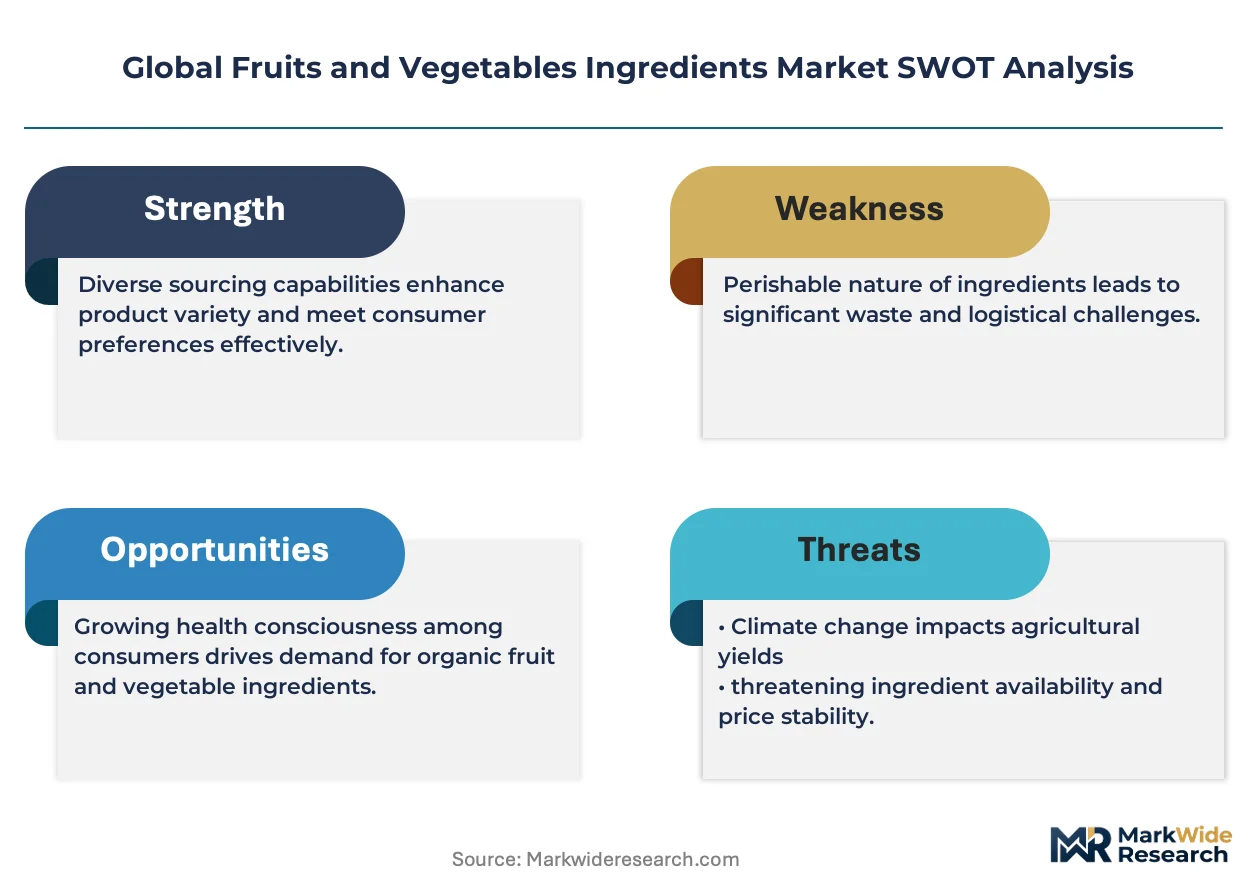
Capital intensity in aseptic processing and cold-chain logistics is consolidating procurement power among balance-sheet-heavy suppliers capable of financing multi-hemisphere sourcing networks. This structural force compresses margins for asset-light traders while rewarding integrated operators with captive farm-to-concentrate infrastructure.
Growth Catalysts
- EU Green Deal pesticide thresholds:The regulation is redirecting sourcing toward certified organic supply clusters with integrated traceability systems. German and Dutch ingredient suppliers are securing long-term contracts with tropical organic cooperatives.
- Beverage clean-label reformulation:Food manufacturers are substituting synthetic colorants and flavor enhancers with fruit purees and vegetable concentrates. Infant nutrition and sports drink segments are driving specification tightening.
- India PLI scheme for food processing:The incentive structure is accelerating domestic concentrate capacity buildout. Maharashtra and Karnataka are emerging as mango and pomegranate processing hubs reducing import dependency.
Market Restraints
- Input cost volatility in tropical fruit feedstock:Weather-driven supply shocks in Brazilian orange and Indian mango harvests create Brix standardization challenges. Concentrate producers face margin compression during El Niño cycles.
- Supply concentration risk in aseptic packaging:Three equipment vendors dominate high-speed filling lines for 65-72 Brix concentrates. Lead times extend to 18 months constraining capacity expansion timelines.
- Regulatory fragmentation across FDA-EFSA-FSSAI:Divergent maximum residue limits force suppliers to maintain parallel qualification systems. Foreign supplier verification costs under FSMA compound with EU Regulation 396/2005 benchmarking.
Strategic Opportunities
- Underpenetrated African sourcing corridors:Egypt and Morocco offer counter-seasonal citrus and tomato concentrate potential. European buyers are piloting integrated farm-processing joint ventures.
- Cell-cultured fruit scaffolding:Precision fermentation platforms are converging with plant cell culture to produce flavor-active compounds. Early-stage partnerships between biotech startups and flavor houses are forming.
- Direct-to-manufacturer digital platforms:B2B marketplaces are disintermediating traditional import-export brokers. Indian and Vietnamese concentrate suppliers are listing on specialized agricultural commodity exchanges.
Industry Challenges
- Specialized process engineering talent scarcity:Aseptic system design and Brix control automation require hybrid food science-mechanical engineering profiles. European technical universities are not graduating sufficient candidates.
- Capex intensity in freeze-drying infrastructure:Lyophilization equipment for premium dried fruit applications demands 40 million euro plus investments. Mid-scale operators struggle to justify utilization rates.
- Organic certification timeline compression:Three-year conversion periods for conventional orchards delay supply response to premium demand spikes. auditors in tropical origins face backlog constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruits and Vegetables Ingredients Market |
| Market Size in 2026 | $138.7 Billion |
| Market Size in 2035 | $250.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puree, Juice Concentrate, Dried Fruits, Frozen Vegetables Application: Beverages, Sauces, Snacks, Bakery Products End User: Food Manufacturers, Restaurants, Retailers, Catering Services Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Kerry Group, Döhler GmbH, Olam International, AGRANA Beteiligungs-AG, Sensient Technologies, Tate & Lyle, SunOpta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruits and Vegetables Ingredients Market Emerging Trajectories
Digital traceability infrastructure is rewiring supplier qualification protocols while bioprocessing advances compress extraction yield curves. These forces are simultaneously raising compliance barriers and opening formulation possibilities for ingredient manufacturers.
Blockchain-enabled farm-to-facility tracking is digitizing pesticide residue documentation and harvest-date verification. European retailers and North American beverage conglomerates are mandating real-time chain-of-custody data. This technology is compressing audit cycles from quarterly to continuous monitoring.
EFSA is tightening additive authorization timelines under reformed Novel Food regulations. Enzymatic extraction methods for pectin and natural colors face accelerated safety assessment schedules. Suppliers are pre-submission dossier building to secure 18-month approval windows.
Food-service distributors are consolidating direct procurement relationships with concentrate processors. Traditional broadline intermediaries are losing share to specialized ingredient sourcing divisions within restaurant chains. This pattern is most visible in US and UK quick-service restaurant networks seeking batch consistency guarantees.
Global Fruits and Vegetables Ingredients Market Segmentation
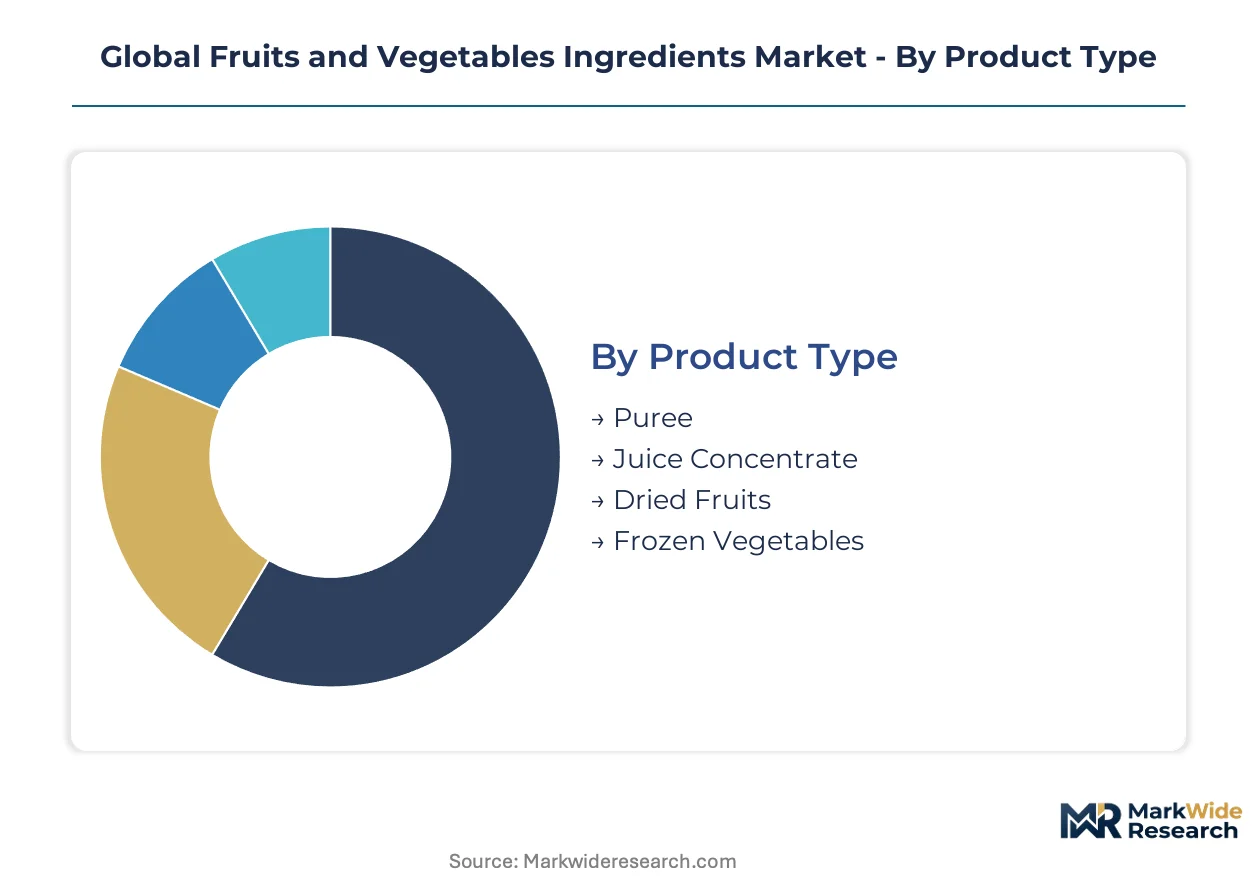
Ingredient buyers structure procurement around technical specifications and supply assurance requirements. Segmentation reveals where formulation flexibility commands premium pricing versus commodity standardization. Each dimension carries distinct margin profiles and qualification barriers.
Product Type:
After-sales technical support intensity varies sharply across processing categories, with aseptic systems demanding dedicated field engineering while dried products require minimal intervention.
- Juice Concentrate:Thermally reduced to 65-72 Brix with standardized soluble solids content. Beverage manufacturers in Germany and the Netherlands anchor procurement volumes, driven by clean-label reformulation mandates from EU retailers.
- Puree:Minimally processed fruit or vegetable pulp retaining fiber and texture. Infant nutrition brands in Maharashtra and Karnataka specify aseptic purees with pathogen-negative certification under FSSAI directives.
- Dried Fruits:Dehydrated or lyophilized pieces with water activity below 0.6. Ambient-stable snacking applications dominate offtake.
- Frozen Vegetables:Rapid-frozen cuts at minus 40 degrees Celsius. Food-service distributors in the US and UK quick-service networks prioritize batch consistency for restaurant procurement.
Juice concentrate holds the largest share; momentum sits with puree as formulation flexibility premiums expand.
Application:
Cost tier stratification separates premium positioning in infant nutrition from commodity volume in mass-market snacking.
- Beverages:Sports drinks and functional waters drive fruit concentrate specification tightening. EFSA additive authorization timelines under Novel Food regulations compress supplier pre-submission windows.
- Sauces:Tomato and pepper purees provide viscosity and umami base notes. Italian and Spanish manufacturers localize Mediterranean vegetable sourcing.
- Snacks:Dried fruit inclusions and vegetable powders serve clean-label positioning. Indian PLI scheme incentives accelerate domestic processing capacity.
- Bakery Products:Fruit pieces and concentrates replace synthetic flavor systems. German technical standards bind tropical supply bases through integrated sourcing clusters.
Beverages command the deepest margin pool; snacks are climbing the fastest on ambient distribution economics.
End User:
Volume concentration patterns separate consolidated food manufacturers from fragmented food-service procurement.
- Food Manufacturers:Packaged goods producers with captive R&D specify custom Brix and viscosity profiles. FDA foreign supplier verification under FSMA elevates documentation burdens for imported concentrates.
- Restaurants:Quick-service chains consolidate direct processor relationships, bypassing traditional broadline distributors. Batch consistency guarantees drive contract terms.
- Retailers:Private-label sourcing divisions specify traceability infrastructure. Blockchain-enabled chain-of-custody data compresses audit cycles.
- Catering Services:Institutional procurement prioritizes freeze-thaw stability and portion control. Frozen vegetable specifications dominate.
Food manufacturers represent the largest procurement volume; restaurants are gaining share fastest through direct sourcing consolidation.
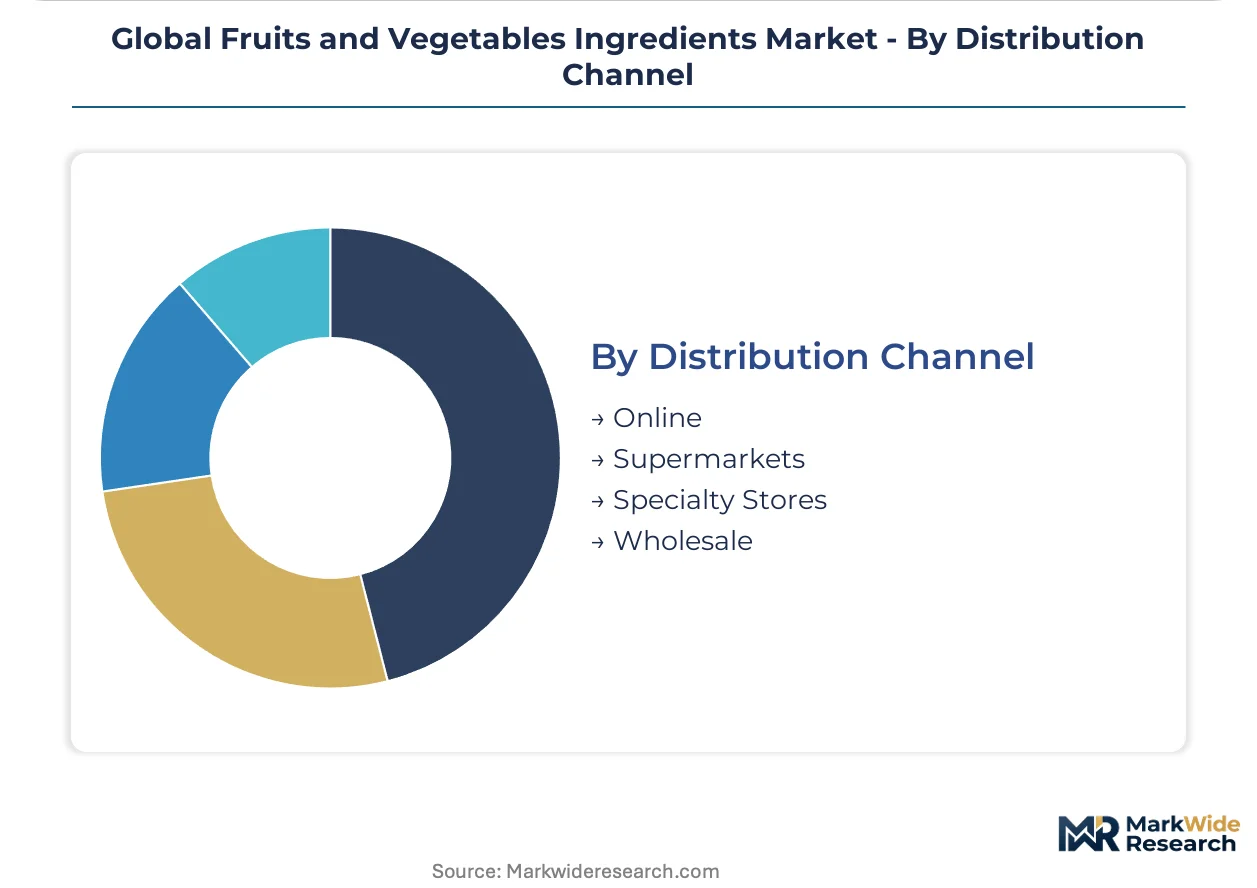
Distribution Channel:
Supply concentration in aseptic packaging equipment shapes channel economics, with three vendors controlling high-speed filling lines and extending lead times to 18 months.
- Wholesale:Traditional import-export brokers handling containerized concentrate volumes. Margin compression from B2B platform disintermediation threatens incumbent positioning.
- Online:Specialized agricultural commodity exchanges list Indian and Vietnamese concentrate suppliers. Direct-to-manufacturer digital platforms reduce intermediary layers.
- Supermarkets:Retailer-controlled private-label sourcing for ambient dried fruit. Shelf-stable categories enable centralized procurement.
- Specialty Stores:Organic certification premiums support smaller lot sizes. Three-year orchard conversion timelines delay supply response to demand spikes.
Wholesale retains dominant volume; online channels show the steepest expansion trajectory as digital platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major producing and consuming economies. Brazil and India run structural surpluses in tropical concentrates, while Germany and the United States absorb deficit volumes through processed food manufacturing demand.
Brazil
Orange and mango concentrate exports dominate Atlantic shipping lanes to European beverage manufacturers. ANVISA pesticide residue protocols align with EU Regulation 396/2005 benchmarks, easing cross-border qualification. São Paulo state anchors processing capacity with integrated crushing-to-concentrate facilities serving German and Dutch procurement desks.
India
FSSAI fortification directives and PLI scheme incentives accelerate domestic mango and pomegranate concentrate output. Maharashtra and Karnataka processing hubs reduce import dependency for tropical purees. Mumbai-Pune industrial corridor hosts aseptic packaging investments targeting infant nutrition specifications.
Germany
Beverage clean-label reformulation mandates from EU retailers concentrate procurement volumes for standardized Brix concentrates. EFSA Novel Food regulations compress supplier pre-submission timelines for enzymatic extraction methods. Hamburg and Rotterdam port clusters coordinate multi-hemisphere sourcing through integrated trading houses.
United States
FDA Food Safety Modernization Act enforcement elevates foreign supplier verification burdens for imported fruit purees. California Central Valley tomato processing anchors domestic paste and concentrate supply. Chicago and New Jersey distribution hubs consolidate procurement for quick-service restaurant networks demanding batch consistency guarantees.
Egypt
Counter-seasonal citrus concentrate potential attracts European pilot joint ventures in integrated farm-processing operations. National food safety authority benchmarks track EFSA pesticide residue thresholds for export market access. Nile Delta growing regions develop traceability infrastructure for German and Dutch retailer qualification protocols.
Global Fruits and Vegetables Ingredients Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply. The vendor base concentrates among capital-rich operators with captive farm-to-facility infrastructure and balance-sheet depth for multi-hemisphere sourcing networks. Three archetypes dominate: integrated agribusiness conglomerates with grain-trading treasury functions, flavor-application laboratories with co-development capabilities, and regional sourcing specialists binding technical standards to tropical supply bases. Competitive moves center on strategic partnerships with organic cooperatives and capacity expansion in aseptic processing corridors.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company occupy positions defined by trading infrastructure and treasury-funded processing investments. Kerry Group exemplifies the flavor-application laboratory archetype through integrated technical service models. Döhler GmbH anchors the regional sourcing specialist category, binding German quality protocols to tropical origin clusters. These three represent divergent capital deployment strategies for securing concentrate supply assurance.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Kerry Group |
| Döhler GmbH |
| Olam International |
| AGRANA Beteiligungs-AG |
| Sensient Technologies |
| Tate & Lyle |
| SunOpta |
| Others |
Supply Flow & Price Mechanics
Brazilian orange and Indian mango feedstock concentration anchors margin pools in aseptic concentrate processing, while downstream beverage manufacturers in Germany and the Netherlands arbitrage Brix standardization premiums against formulation flexibility demands. Three equipment vendors controlling high-speed filling lines for 65-72 Brix concentrates extend procurement lead times, compressing pricing power for mid-scale operators lacking balance-sheet depth for captive multi-hemisphere sourcing networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tiered adjustments, while food-service distributors face spot-market exposure during El Niño-driven harvest shocks. Price differentiation hinges on organic certification grade under EU Regulation 396/2005 and aseptic pathogen-negative certification under FSSAI directives. Cost compression in standard-grade concentrates intensifies as Indian PLI scheme capacity buildout floods mid-tier supply. Quick-service restaurant networks demonstrate highest price sensitivity due to batch consistency guarantees demanded without formulation flexibility premiums.
Supply Chain Analysis
Export-control regimes on aseptic packaging technology limit equipment flows from German and Dutch engineering centers to emerging processing hubs, constraining capacity expansion timelines. Geographic supply concentrates in Brazil, India, and Egypt for tropical and counter-seasonal citrus feedstock. Raw material dependencies rest on orange and mango harvests, Brix standardization enzymes, and aseptic barrier films. Single-source vulnerability in high-speed filling equipment creates chokepoint exposure. Distribution runs through Hamburg and Rotterdam port clusters coordinating multi-hemisphere procurement for integrated trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal pesticide threshold tightening represents a regulatory inflection accelerating certified organic supply chain reconfiguration, while precision fermentation platforms for flavor-active compounds introduce technological disruption vectors across formulation partnerships.
For Market Incumbents: Pre-empt margin compression in standard-grade concentrates by securing long-term contracts with tropical organic cooperatives before three-year orchard conversion timelines mature. Anchor defensive positioning through integrated farm-to-facility infrastructure in Maharashtra and Karnataka processing corridors, neutralizing emerging Indian domestic capacity threats. Prioritize aseptic packaging equipment forward-commitments to lock out mid-scale entrants facing 18-month vendor lead times. For New Entrants and Emerging Players: Counter-seasonal citrus corridors in Egypt and Morocco represent the most penetrable entry point for European beverage manufacturer qualification pilots. Direct-to-manufacturer digital platforms on specialized agricultural commodity exchanges offer disintermediation leverage against traditional import-export brokerage incumbents. Target infant nutrition aseptic puree specifications in Mumbai-Pune industrial corridor, where FSSAI fortification directives concentrate demand growth. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across freeze-drying infrastructure for premium dried fruit applications, demanding 40 million euro plus investments that mid-scale operators cannot justify. Long-term viability over the analysis window favors acquisition targets with captive farm-to-concentrate infrastructure and integrated traceability systems binding German technical standards to tropical supply bases. Monitor EFSA Novel Food authorization timelines for enzymatic extraction methods as inflection indicator for premium formulation pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Orchards | Secures three-year organic conversion timelines ahead of EU Green Deal threshold enforcement. |
| Aseptic Processing Capacity Expansion | Locks in 65-72 Brix concentrate supply assurance for German and Dutch beverage procurement desks. |
| Blockchain-Enabled Traceability Deployment | Compresses audit cycles from quarterly to continuous monitoring for retailer qualification protocols. |
| Precision Fermentation Partnership | Positions flavor houses for cell-cultured fruit scaffolding in next-generation clean-label formulations. |
| Regional Sourcing Cluster Development | Binds technical standards to tropical supply bases through integrated farm-processing joint ventures. |
Methodological Framework
Desk research of customs trade data, FSSAI directive filings, EFSA Novel Food submission databases, and SEC 10-K processing segment disclosures preceded structured interviews with aseptic packaging plant engineers, beverage manufacturer procurement leads, tropical cooperative agronomists, and cold-chain logistics operators. Primary fieldwork combined with secondary validation through ANVISA pesticide residue protocol documentation and EU Regulation 396/2005 benchmarking reports. Bottom-up concentrate volume modeling and top-down ingredient procurement spend analysis were triangulated for cross-verification.
Assumptions held fixed include EFSA additive authorization timelines, FSSAI fortification directive enforcement patterns, and three-year organic orchard conversion periods, while El Niño cycle severity and aseptic equipment vendor capacity were varied across sensitivity scenarios. Segmentation dimensions spanned product type, application category, end-user archetype, and distribution channel, with regional regulatory cluster effects modeled separately. CAGRs were derived from installed processing capacity buildout trajectories and clean-label reformulation penetration curves across beverage and infant nutrition segments.
Practitioners should monitor Brazilian and Indian harvest yield volatility, EFSA Novel Food pre-submission backlog accumulation, and aseptic packaging equipment vendor order book extension for early signals of forecast revision triggers. Cross-checking against IEA agricultural commodity price benchmarks and FAO tropical fruit production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Black Seed Oil Market
Ingredients
South America Lipid Market
Ingredients
Modified Maize Starch Market
Ingredients
Gelatin Substitutes Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Global Gelatin Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
South America Agar Market
Ingredients
Confectionery Ingredients Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Coconut Derivatives Market