
 Starch Market | 2026-2036
Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Starch Market Intelligence
ISO 22000 certification is unwinding competitive access for smaller millers across the starch supply chain. Cargill leverages its North American corn origination network to sustain cost leadership in native and modified grades. Roquette Frères anchors European pea and potato starch output through integrated wet-milling assets in France and the Netherlands. Ingredion Incorporated competes on specialty modified starches for pharmaceutical and industrial binders.
Starch denotes a polysaccharide carbohydrate composed of amylose and amylopectin polymers, typically extracted from corn, wheat, potato, cassava, or pea sources through wet-milling, drying, and separation processes; it functions as a thickener, gelling agent, binder, and encapsulant across food, paper, textile, and biopolymer systems. Modified starches command premium positioning where heat-shear stability and freeze-thaw resistance justify functional substitution of synthetic additives. Native starches dominate volume in emerging economies where paper coating and textile sizing applications prioritize unit economics over performance engineering. Powder form leads shipment volumes due to handling efficiency in bulk dry-blend operations, though liquid dispersions gain traction in continuous-process food manufacturing.
FDA food additive regulations and EPA biofuel mandates shape North American corn starch utilization rates, while REACH and EU Green Deal sustainability thresholds redirect European demand toward enzymatic and resistant starch variants. China's NMPA and GB standards govern food-grade import specifications, creating compliance friction for cross-border suppliers. Stakeholders must monitor how biopolymer substitution timelines in packaging intersect with feedstock cost volatility and regional carbon accounting rules.
Market Dynamics
Biopolymer substitution mandates under the EU Green Deal and F-Gas Regulation are compressing synthetic polymer demand while redirecting capital toward enzymatic starch modification capacity.
Growth Catalysts
- Clean-label food processing:Food manufacturers reformulate with native and modified starches to replace artificial thickeners and meet EFSA clean-label criteria.
- REACH sustainability thresholds:European paper coating operations pivot toward enzymatically processed starches to comply with bio-based content mandates.
- China's biodegradable packaging expansion:Provincial manufacturing clusters scale thermoplastic starch capacity to serve e-commerce logistics demand.
Market Restraints
- Feedstock cost volatility:Corn and wheat price swings in the Black Sea region transmit directly into native starch margin compression.
- ISO 22000 certification barriers:Small-scale millers in South Asia face exclusion from branded food supply chains due to audit cost concentration.
- Cellulose ether substitution:Construction and pharmaceutical binders increasingly specify cellulose derivatives where freeze-thaw performance exceeds starch capability.
Strategic Opportunities
- Resistant starch fortification:Clinical nutrition formulators in Japan and South Korea specify high-amylose variants for glycemic management applications.
- Wet-milling technology convergence:Pea protein extraction facilities retrofit for co-produced starch fractions, capturing dual-revenue streams.
- IRA biofuel incentives:US ethanol producers qualify for tax credits by diverting refined corn starch toward sustainable aviation fuel pathways.
Industry Challenges
- Specialized process engineering talent:Wet-milling optimization and enzymatic modification require skill sets concentrated among retired European technical specialists.
- Legacy equipment retrofit complexity:Continuous-process food manufacturers face downtime costs when integrating liquid dispersion handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch Market |
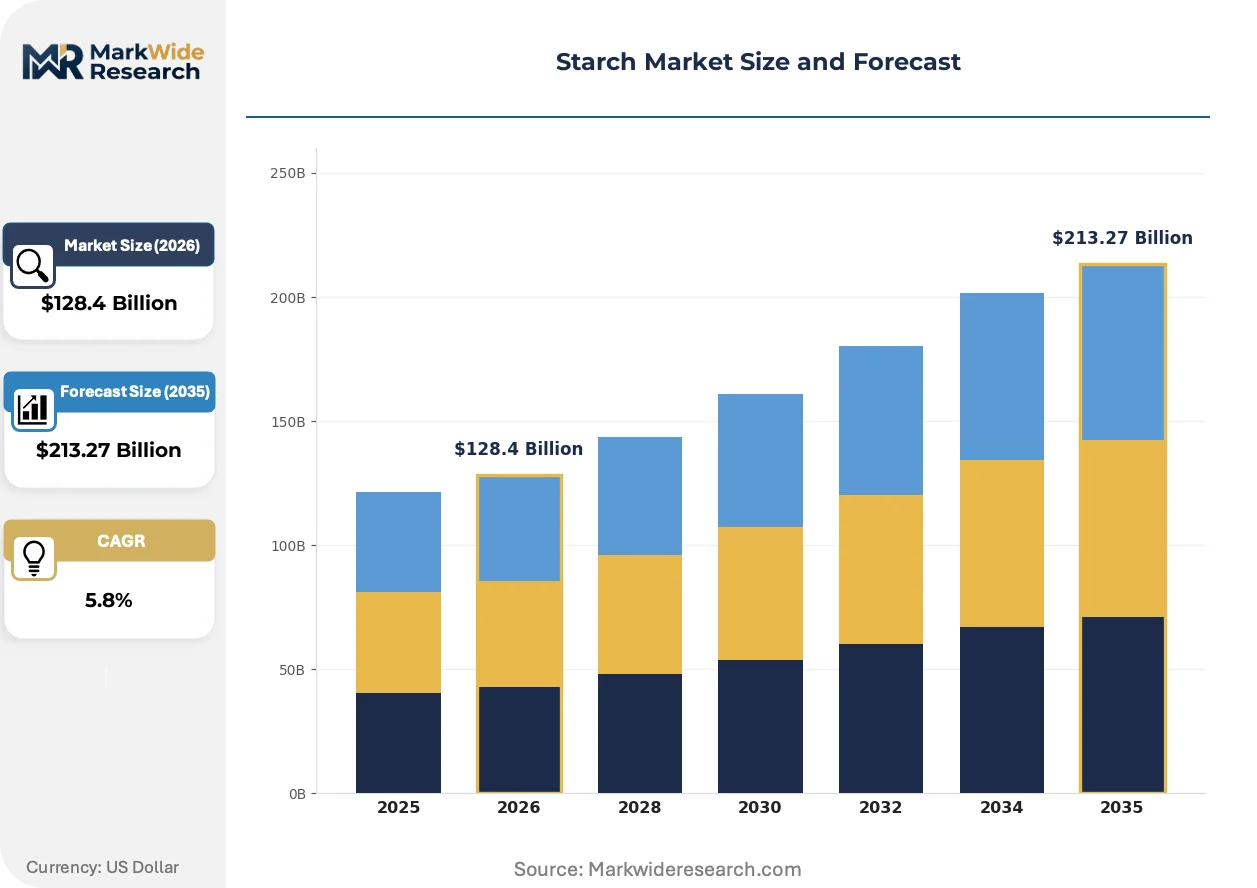
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $213.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native, Modified, Resistant, Pre-gelatinized, Enzymatic, Cross-linked Application: Food Additives, Paper Coating, Textile Sizing, Biodegradable Packaging, Adhesives, Pharmaceuticals End Use Industry: Food Processing, Paper Manufacturing, Textile Production, Pharmaceutical Manufacturing, Packaging Industry, Construction Form: Powder, Granules, Liquid, Flakes |
| Companies Covered | Tate & Lyle PLC, AGRANA Beteiligungs-AG, Cargill, Grain Processing Corporation, Tereos Group, Archer Daniels Midland Company, Roquette Frères, Royal Avebe U.A., Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch Market Strategic Shifts & Innovations
Enzymatic modification and precision fermentation are collapsing the performance gap between native starches and synthetic alternatives across food, pharmaceutical, and biopolymer applications.
Precision fermentation-derived amylose is miniaturizing batch-to-batch variability in pharmaceutical-grade starches. Contract manufacturers serving tablet binders and capsule fillers adopt these inputs to reduce dissolution testing failures. The technology is miniaturizing quality assurance overhead while enabling just-in-time raw material procurement.
The EU F-Gas Regulation accelerates thermoplastic starch adoption in flexible packaging by banning hydrofluorocarbon-based barrier films. Converters in Germany and the Netherlands retrofit blown-film lines to process starch-polymer blends. Food contact compliance under EFSA migration limits now determines formulation viability for dairy and ready-meal packaging.
Consolidated procurement by quick-service restaurant chains concentrates modified starch specification power among three North American buying groups. Regional sauce and coating suppliers lose negotiating leverage as chains mandate pre-approved ingredient lists. This concentration is most visible in the US poultry breading and Asian-style sauce segments.
Starch Market Segmentation
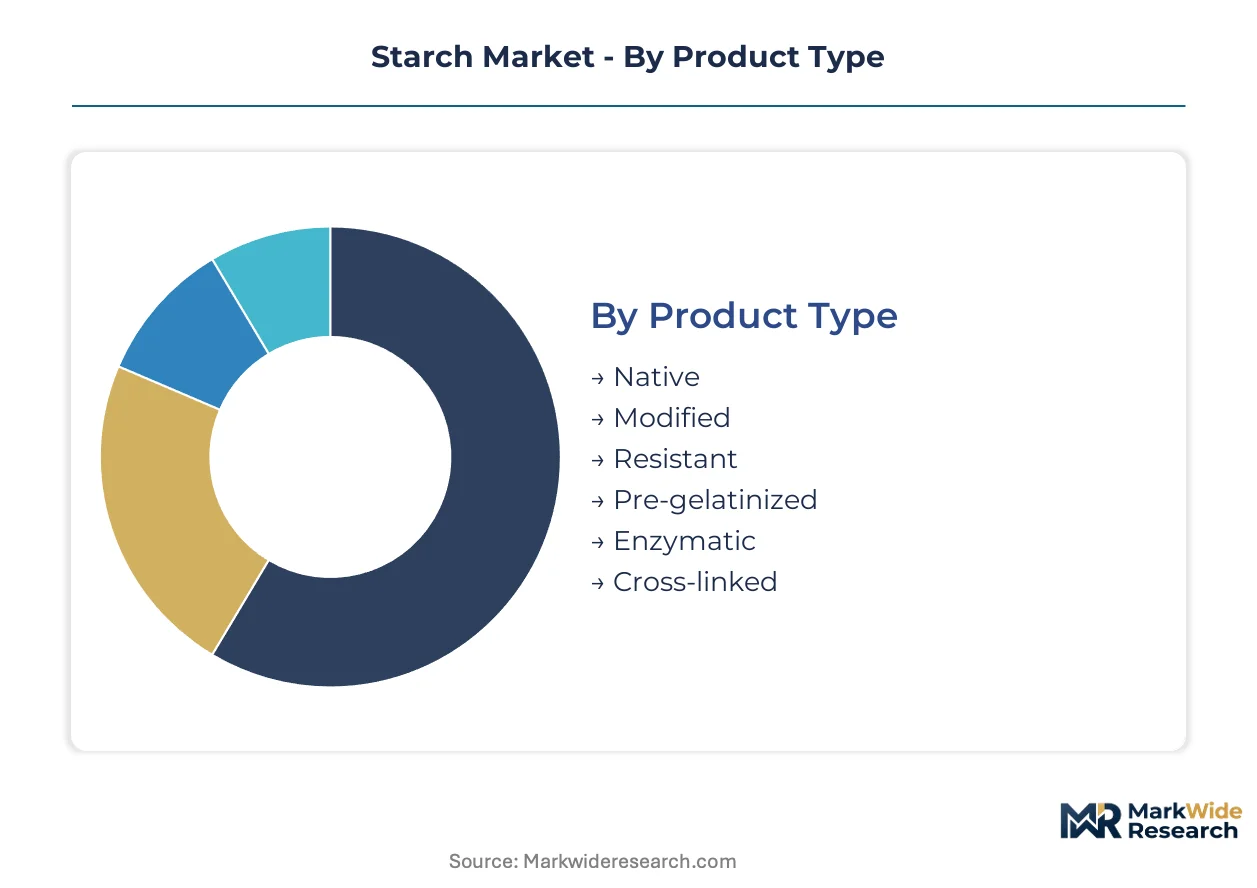
Starch market segmentation reflects divergent regulatory pathways across food contact materials, industrial binders, and biopolymer applications. Product specifications and form factors align with end-use compliance requirements rather than interchangeable commodity logic.
Product Type:
REACH and FDA food additive regulations differentiate approval pathways, with enzymatic and resistant variants commanding premium positioning under sustainability mandates.
- Native:Unmodified amylose-amylopectin composition extracted through conventional wet-milling. Paper manufacturing in China and India absorbs volume for coating formulations where unit economics outweigh performance engineering.
- Modified:Chemically or physically altered to deliver heat-shear stability, acid resistance, and freeze-thaw tolerance. Food processors in Germany and the Netherlands specify these for clean-label reformulations replacing synthetic thickeners under EFSA guidance.
- Resistant:High-amylose variants resisting small-intestine digestion. Clinical nutrition formulators in Japan leverage these for glycemic management products.
- Pre-gelatinized:Cold-water soluble through pre-cooking and drying. Instant food manufacturers favor this for no-heat reconstitution.
- Enzymatic:Processed via specific enzyme reactions for targeted molecular weight distribution. Biopolymer producers adopt these for thermoplastic starch film production under EU F-Gas Regulation compliance.
- Cross-linked:Stabilized through phosphate or adipate esterification for extreme process tolerance. Retort pouch applications specify this grade.
Established volume favors Native; emerging adoption favors Enzymatic.
Application:
Cost tiers separate commodity paper coating from pharmaceutical-grade binders where dissolution testing failures carry batch rejection costs.
- Food Additives:Thickeners, stabilizers, and gelling agents across sauces, dairy, and bakery. Clean-label reformulation by quick-service restaurant chains concentrates specification power among North American buying groups.
- Paper Coating:Surface sizing and binding for print quality enhancement. European mills pivot toward enzymatically processed starches to meet bio-based content thresholds under EU Green Deal procurement rules.
- Textile Sizing:Warp yarn protection during weaving. Bangladesh and Vietnam textile clusters absorb native starch volumes for cotton processing.
- Biodegradable Packaging:Thermoplastic starch films and foam replacements. German and Dutch converters retrofit blown-film lines to process starch-polymer blends for dairy packaging under EFSA migration limits.
- Adhesives:Corrugated board bonding and wallpaper pastes. Construction sector demand fluctuates with housing starts.
- Pharmaceuticals:Tablet binders, disintegrants, and capsule fillers. Precision fermentation-derived amylose reduces batch-to-batch variability for contract manufacturers.
Commodity applications concentrate in Paper Coating; value capture climbs fastest in Pharmaceuticals.
End Use Industry:
Customer type determines procurement scale, with multinational food processors imposing pre-approved ingredient lists on regional sauce suppliers.
- Food Processing:Largest demand sink spanning bakery, dairy, convenience foods, and beverages. ISO 22000 certification requirements exclude smaller millers from branded supply chains.
- Paper Manufacturing:Coating and surface sizing operations. China's provincial manufacturing clusters scale capacity to serve domestic packaging demand.
- Textile Production:Warp sizing and finishing applications. South Asian spinning mills prioritize native starch cost structures.
- Pharmaceutical Manufacturing:Excipient and active ingredient applications. USP-NF compliance distinguishes supplier tiers.
- Packaging Industry:E-commerce logistics and food contact materials. China's biodegradable packaging expansion drives thermoplastic starch capacity scaling.
- Construction:Gypsum board binders and adhesive formulations. Cellulose ether substitution threatens starch share where freeze-thaw performance is critical.
Volume dominance sits with Food Processing; margin expansion favors Pharmaceutical Manufacturing.
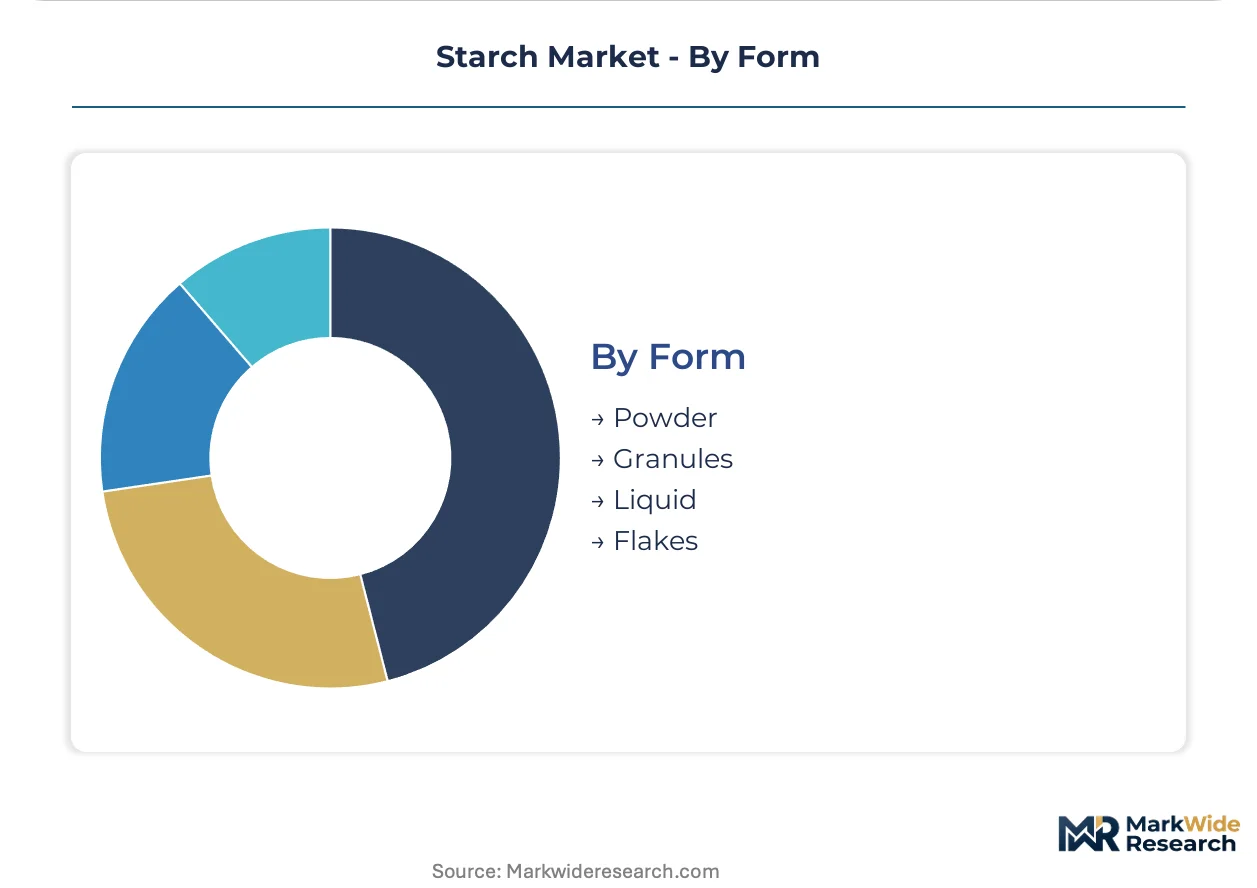
Form:
Supply concentration in powder processing reflects handling efficiency for bulk dry-blend operations, while liquid dispersion capacity requires specialized equipment investment.
- Powder:Dominant shipment format for dry-blend compatibility and storage stability. Bulk handling infrastructure across corn belt elevators and European port terminals supports scale.
- Granules:Free-flowing agglomerated form for reduced dusting. Seasoning and soup mix manufacturers specify this for metering accuracy.
- Liquid:Pre-dispersed slurries for continuous-process food manufacturing. Retrofit complexity and downtime costs slow adoption among legacy equipment operators.
- Flakes:Instant dissolution format for reconstitution applications. Limited specialty demand in instant gravy and sauce segments.
Operational inertia preserves Powder dominance; continuous-process retrofit demand elevates Liquid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational food processors and biopolymer converters concentrate procurement leverage across four demand poles. Corn wet-milling clusters in the US Midwest supply native and modified grades to North American quick-service chains. European paper coaters and packaging converters pivot toward enzymatic variants under EU Green Deal compliance timelines. Chinese provincial manufacturing bases scale thermoplastic starch capacity for e-commerce logistics. Indian textile sizing operations absorb volume through cost-optimized native starch supply chains.
United States
Ethanol producers and sustainable aviation fuel developers divert refined corn starch toward IRA tax credit pathways. FDA food additive regulations and EPA biofuel mandates shape utilization rates across wet-milling assets. Iowa and Illinois processing clusters anchor origination networks serving branded food manufacturers.
China
Provincial manufacturing clusters in Zhejiang and Guangdong scale thermoplastic starch film capacity for biodegradable packaging demand. NMPA and GB standards govern food-grade import specifications, creating compliance friction for cross-border suppliers. Shanghai and Tianjin port terminals handle bulk powder shipments for paper coating operations.
Germany
Converters in North Rhine-Westphalia retrofit blown-film lines to process starch-polymer blends under F-Gas Regulation compliance. REACH sustainability thresholds redirect demand toward enzymatic modification capacity. The Ruhr industrial corridor hosts biopolymer pilot facilities serving dairy and ready-meal packaging segments.
India
Textile sizing clusters in Gujarat and Maharashtra absorb native starch volumes for cotton warp yarn protection. FSSAI certification requirements and ISO 22000 audit costs exclude smaller millers from branded food supply chains. Ludhiana spinning mills prioritize unit economics over performance-engineered modified grades.
Japan
Clinical nutrition formulators in the Kanto region specify high-amylose resistant starch variants for glycemic management applications. METI industrial policy supports precision fermentation research for pharmaceutical-grade amylose production. Osaka-based contract manufacturers reduce dissolution testing failures through standardized inputs.
Starch Market Key Industry Players
Player mix skews toward integrated agribusiness conglomerates with captive wet-milling infrastructure. Mid-cap regional specialists occupy modified starch niches requiring certification depth. Three archetypes dominate: North American origination-integrated processors, European pea and potato starch specialists, and Asian textile-grade volume suppliers. Competitive moves concentrate on enzymatic modification capacity expansion and backward integration into protein-starch co-production facilities.
Within the integrated agribusiness tier, Cargill and Archer Daniels Midland Company exemplify scale-driven origination networks spanning corn belt elevator systems. Roquette Frères anchors European positioning through wet-milling assets concentrated in France and the Netherlands. Tate & Lyle PLC represents the specialty-modified vector where heat-shear stability specifications command premium positioning in pharmaceutical and industrial binder applications.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| AGRANA Beteiligungs-AG |
| Cargill |
| Grain Processing Corporation |
| Tereos Group |
| Archer Daniels Midland Company |
| Roquette Frères |
| Royal Avebe U.A. |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Corn wet-milling capacity utilization above 85% across Iowa and Illinois processing clusters compresses margin flexibility for native starch producers while elevating price floors for modified and enzymatic grades. Scale concentration among North American origination-integrated processors shapes contract structures that tether spot premiums to Chicago Board of Trade corn futures, with smaller South Asian millers absorbing basis risk without hedging infrastructure.
Pricing Analysis
Cost-plus contracts with Chicago Board of Trade indexation dominate native starch procurement between corn belt processors and North American quick-service chains. Three-tier pricing structure across pharmaceutical-grade, food-certified, and textile-native levels separates USP-NF compliant excipients from FSSAI-labeled food additives and unbranded sizing grades. Cost compression in textile-native tiers is intensifying because Bangladesh and Vietnam spinners prioritize unit economics over performance specifications. Quick-service restaurant chains exhibit lowest price sensitivity due to pre-approved ingredient mandates, while South Asian textile mills demonstrate highest sensitivity to basis volatility.
Supply Chain Analysis
The United States, China, and the Netherlands anchor global starch production through distinct feedstock specializations. Iowa and Illinois corn wet-milling clusters supply native and modified grades; Zhejiang and Guangdong provincial bases scale thermoplastic starch capacity; Dutch and French pea-potato integrated facilities serve European biopolymer demand. Raw material dependencies center on corn futures exposure, Black Sea wheat availability, and pea protein extraction co-production economics. Single-source vulnerability concentrates in enzymatic modification enzymes sourced from Danish and Japanese specialty suppliers. Distribution runs through bulk powder handling at corn belt elevators and Shanghai port terminals, with liquid dispersion requiring dedicated tanker logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, REACH, and NMPA compliance pathways fragments supplier tiers, creating acquisition opportunities for certification-capable mid-caps as multinational food processors consolidate pre-approved ingredient lists.
For Market Incumbents: Consolidate enzymatic modification capacity in Germany and the Netherlands to capture EU F-Gas Regulation-driven biopolymer substitution demand. Acquire South Asian ISO 22000-certified millers before audit cost barriers permanently exclude regional players from branded supply chains. Backward integration into pea protein extraction co-production facilities in France secures dual-revenue streams as wet-milling technology converges. For New Entrants and Emerging Players: Differentiate on precision fermentation-derived amylose for pharmaceutical-grade tablet binders, where batch-to-batch variability reduction commands premium positioning. Target Japan and South Korea clinical nutrition formulators with resistant starch fortification capabilities for glycemic management applications. Pursue toll manufacturing arrangements with Osaka-based contract manufacturers to bypass capital-intensive wet-milling infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic modification specialists serving EU packaging converters with multi-year F-Gas compliance contracts. Long-term viability favors integrated protein-starch co-production facilities over single-product native starch assets. Monitor thermoplastic starch capacity utilization rates in Zhejiang and Guangdong as inflection indicator for Chinese biodegradable packaging demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Capacity Expansion | Captures EU F-Gas Regulation-driven substitution of hydrofluorocarbon barrier films with thermoplastic starch blends. |
| Backward Integration into Pea Protein Extraction | Enables dual-revenue capture from wet-milling assets serving plant-based protein and specialty starch demand simultaneously. |
| ISO 22000 Certification Investment | Unlocks branded food supply chain access currently blocked to smaller South Asian and Indian millers. |
| Precision Fermentation Amylose Production | Reduces pharmaceutical dissolution testing failures through standardized inputs for tablet binders and capsule fillers. |
| Long-term Supply Agreement with Quick-Service Chains | Secures volume commitment from North American buying groups consolidating modified starch specifications. |
Research Approach
Findings reconcile primary fieldwork against secondary review of wet-milling asset disclosures, corn futures trade data, and EU regulatory filings. Primary interviews engaged plant managers at Iowa and Illinois processing clusters, procurement leads at German packaging converters, regulatory affairs specialists navigating REACH and FDA food additive pathways, and technical R&D directors at enzymatic modification facilities. Secondary validation drew from Chicago Board of Trade futures data, ECHA substance registrations, NMPA import specification databases, and SEC 10-K filings from integrated agribusiness conglomerates. Bottom-up capacity modeling triangulated against top-down demand segmentation across food, pharmaceutical, and biopolymer applications.
Segmentation dimensions modeled span product type, application, end-use industry, and form factor across the projection horizon. Analytical framework derived CAGRs through capacity-utilization sensitivity analysis and feedstock cost elasticity modeling. Industry-specific forecast inputs incorporated IRA biofuel incentive qualification rates for sustainable aviation fuel pathways and EU Green Deal procurement threshold adoption curves for paper coating operations.
The analysis sits within stated boundaries; outcomes outside sustained corn price volatility, accelerated cellulose ether substitution in construction binders, or rapid precision fermentation cost reduction would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance timelines and biopolymer substitution elasticity. Recalibration cycles align with material shifts in EU F-Gas implementation schedules and Black Sea grain corridor stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Blackcurrant Concentrate Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
Almond Flour Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Avocado Oil Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Orange Powder Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Carob Powder Market
Ingredients
Organic Edible Oil Market
Ingredients
Vitamin D Ingredients Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Cocoa Bean Extract Market