
 Holographic Imaging Market | 2026-2036
Holographic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic Imaging Market Analysis
Silicon photonics is restructuring cost structures across holographic display manufacturing. Leia Inc. leverages proprietary nanotechnology to dominate mobile holographic interfaces. Zebra Imaging anchors defense and architectural visualization through large-format printed holograms. RealView Imaging specializes in live holographic visualization for interventional cardiology procedures.
Holographic imaging captures and reconstructs three-dimensional light-field information through interference pattern recording, typically requiring coherent laser sources with wavelengths stabilized to within fractions of a nanometer for medical-grade precision. The technique enables volumetric visualization without stereoscopic eyewear, serving applications from intraoperative surgical guidance to holographic data archives. Digital holography leads product type adoption as CMOS sensor resolution improves and computational reconstruction algorithms reduce hardware footprint. Light field technology represents the fastest-expanding technology segment, driven by automotive head-up display programs and immersive entertainment installations. Display technologies command the largest application margin pool, though scientific research applications sustain premium pricing through specialized optics requirements.
FDA device classification rules shape commercialization timelines for holographic medical devices in the United States, while EU MDR conformity requirements govern European market access for diagnostic holography systems. ISO 10993 biocompatibility standards and IEC 60601 electrical safety frameworks further define product development boundaries for healthcare deployments. Stakeholders must monitor regulatory divergence between FDA's software-as-medical-device guidance and EMA's evolving position on AI-enabled holographic diagnostics when prioritizing geographic rollout sequencing.
Market Dynamics
Silicon photonics integration is collapsing the cost floor for coherent light sources, enabling medical-grade holographic systems to migrate from specialized laboratories into standard hospital imaging suites without sacrificing nanometer-scale wavelength stability.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's software-as-medical-device guidance for holographic visualization tools compresses premarket review timelines for surgical planning applications in the United States.
- CMOS sensor resolution gains:Sub-micron pixel architectures from semiconductor foundries are eliminating mechanical scanning requirements in digital holography systems.
- German precision optics clusters:Academic-industry partnerships in Jena and Oberkochen accelerate prototype-to-product cycles for medical holography hardware.
Market Restraints
- Coherent laser source cost volatility:Single-frequency diode-pumped solid-state lasers remain the dominant cost center, with germanium substrate prices fluctuating on spot markets.
- Specialized optical component concentration:Diffractive optical element manufacturing concentrates among a handful of Japanese and German suppliers, creating single-source vulnerability.
- EU MDR conformity friction:The Medical Device Regulation's clinical evidence requirements for holographic diagnostic systems extend European commercialization timelines by 18-24 months relative to previous directives.
Strategic Opportunities
- Interventional cardiology white space:Live holographic visualization during catheter-based procedures remains underpenetrated outside specialized cardiac centers in the United States and Germany.
- Automotive head-up display convergence:Light field technology integration with advanced driver-assistance systems creates dual-use manufacturing scale for holographic component suppliers.
- India's PLI scheme for photonics:Production-linked incentives for semiconductor and display manufacturing attract holographic hardware assembly to domestic tariff-protected zones.
Industry Challenges
- Computational holography talent scarcity:The intersection of wave optics physics and GPU-accelerated algorithm development commands premium compensation in Germany, Japan, and the United States.
- IEC 60601-1 third edition certification timelines:Electrical safety testing for holographic medical devices with embedded laser sources requires specialized notified body capacity that remains constrained.
- Legacy PACS integration complexity:Hospital radiology departments demand seamless data exchange between holographic visualization platforms and existing DICOM infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holographic Imaging Market |
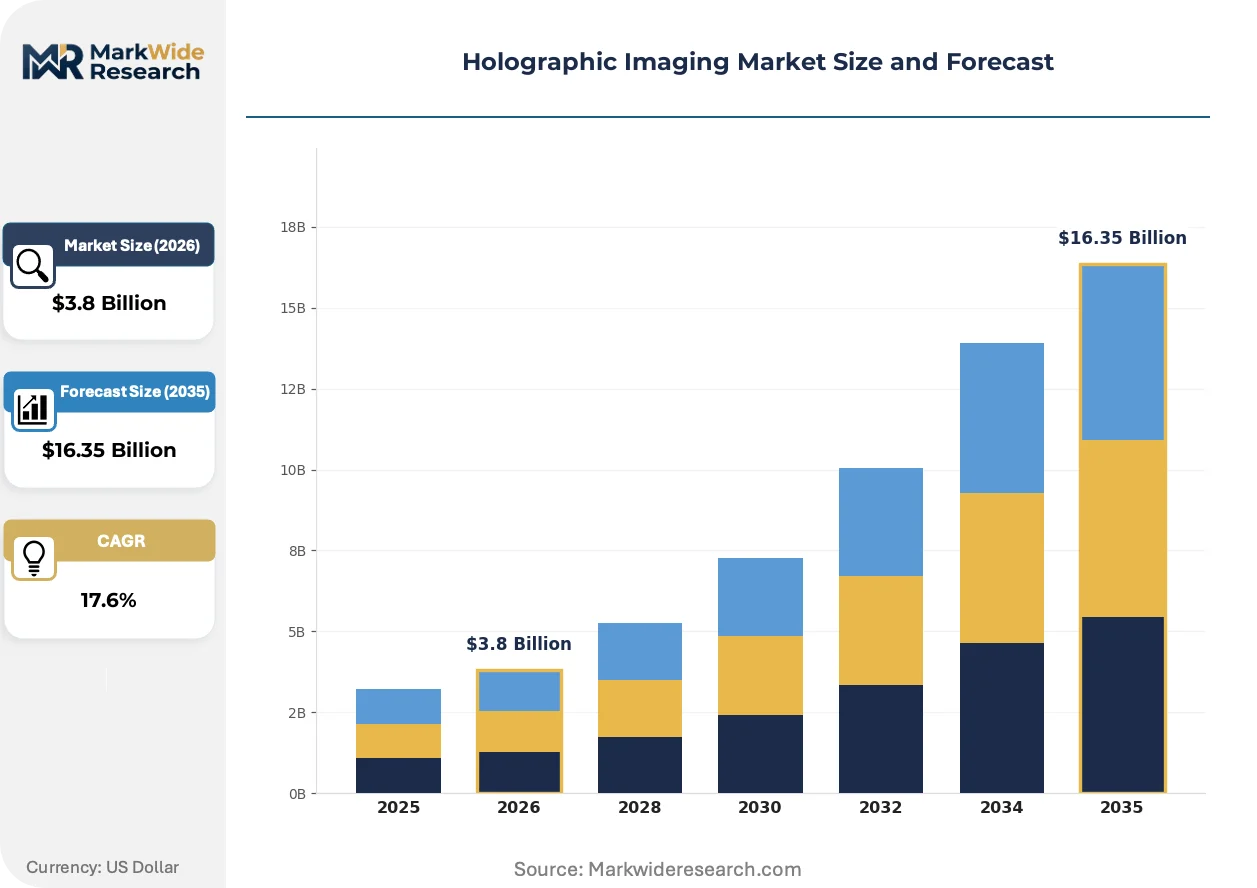
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Holography, Digital Holography, Volume Holography, Computer-Generated Holography End User: Healthcare, Automotive, Entertainment, Aerospace Technology: Electromagnetic Waves, Ultrasonic Waves, Optical Tweezers, Light Field Technology Application: Data Storage, Display Technologies, Security Features, Scientific Research |
| Companies Covered | Leia Inc., Zebra Imaging, RealView Imaging, Ovizio Imaging, Geola Digital UAB, EON Reality, Phase Holographic Imaging, Looking Glass Factory, Holoxica Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic Imaging Market Emerging Trajectories
Computational reconstruction algorithms are displacing optical hardware across holographic imaging architectures, collapsing system footprints while preserving volumetric fidelity for medical and industrial applications.
Deep learning-based phase retrieval is automating the conversion of raw holographic interference patterns into three-dimensional volumetric data without iterative algorithmic processing. Academic medical centers in the United States and university hospitals in Germany are deploying these neural-network pipelines for intraoperative surgical guidance. The technology is automating real-time depth extraction that previously required dedicated high-performance computing clusters, compressing hardware requirements by an order of magnitude.
REACH restrictions on hazardous substances in electronics manufacturing are forcing holographic display producers to reformulate photoresist materials and etching chemistries for diffractive optical elements. The European Chemicals Agency's authorization list now captures several legacy photopolymer compounds used in holographic recording media. Manufacturers serving EU medical device markets are accelerating substitution programs with bio-based photoresist alternatives sourced from specialized chemical suppliers in Switzerland and the Netherlands.
Hospital procurement departments are consolidating holographic visualization contracts under enterprise imaging agreements rather than standalone capital equipment purchases. Radiology and surgical service lines at major health systems in the United States now demand subscription-based software licensing with integrated hardware maintenance. This restructuring is most visible among integrated delivery networks in California and Texas, where chief information officers prioritize interoperability budgets over discrete modality acquisitions.
Holographic Imaging Market Segmentation
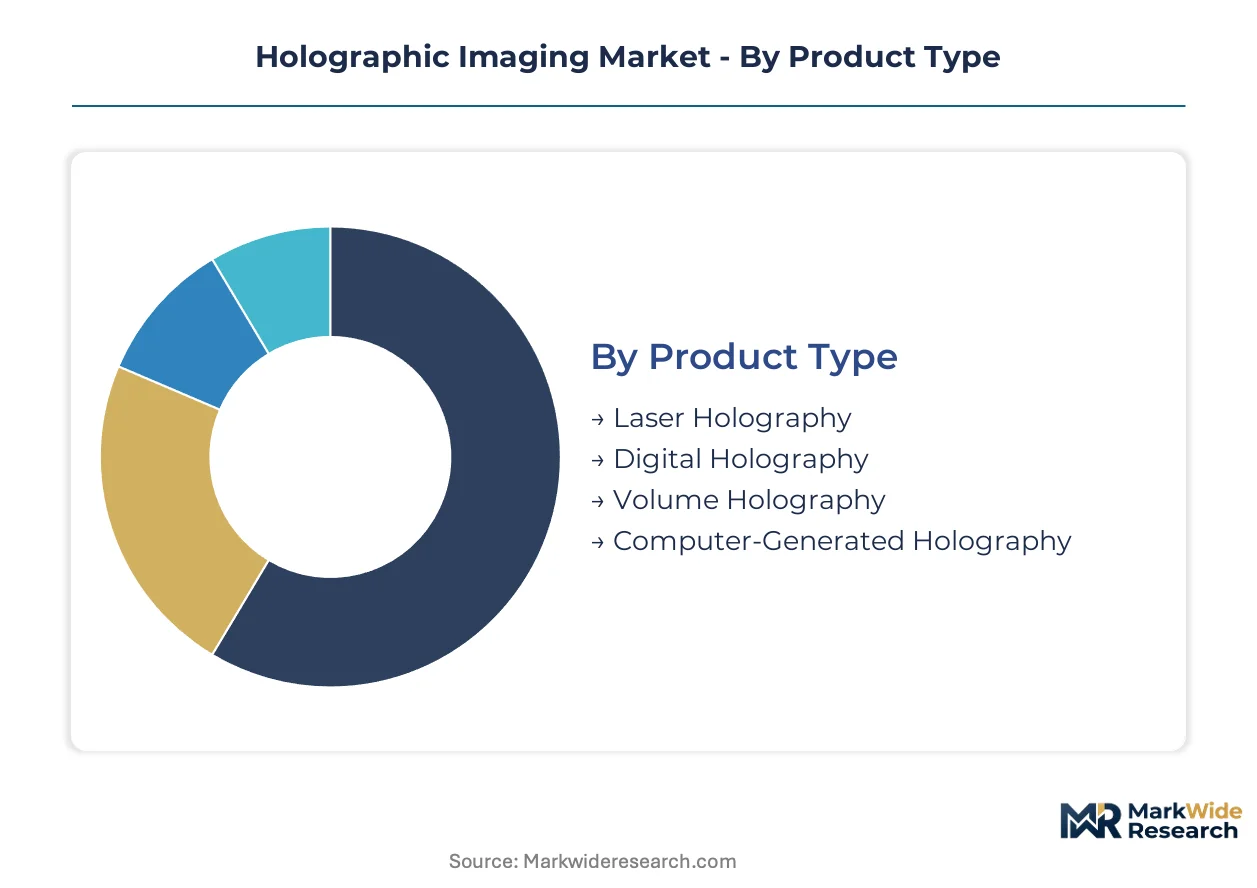
Segmentation in holographic imaging reveals how wavelength stability requirements and computational reconstruction capabilities reshape procurement priorities across medical, automotive, and entertainment verticals. Buyers prioritize different performance thresholds depending on whether volumetric fidelity or real-time processing dominates their use case.
Product Type:
Cost tier determines access — medical-grade wavelength stability commands premium positioning while consumer-facing applications absorb computational shortcuts.
- Digital Holography:CMOS sensor architectures capture interference patterns directly, eliminating wet-chemical processing. Hospital imaging departments in the United States prioritize this modality for intraoperative guidance where reconstruction speed outweighs absolute optical purity. Silicon photonics integration is collapsing hardware footprints while preserving nanometer-scale precision for FDA-cleared surgical applications.
- Computer-Generated Holography:Algorithmic wavefront synthesis bypasses physical recording entirely, enabling dynamic content without coherent illumination. Automotive HUD programs in Germany leverage this approach for real-time depth-graded instrument clusters that maintain legibility across varying ambient light. The technology sacrifices some volumetric authenticity for refresh rate and thermal budget compliance.
- Laser Holography:Traditional silver-halide or photopolymer recording with helium-neon or diode-pumped solid-state sources persists in archival and security printing applications where physical tamper evidence matters.
- Volume Holography:Thick recording media multiplex multiple gratings within a single substrate, serving wavelength-division filtering and holographic data storage niches requiring Bragg selectivity.
Volume sits with Digital Holography; growth tilts toward Computer-Generated Holography.
End User:
Application maturity separates immediate revenue from emerging deployment timelines.
- Healthcare:FDA 510(k) clearances and EU MDR conformity frameworks govern commercial entry for surgical planning and interventional guidance systems. German university hospitals and United States academic medical centers anchor current demand, with procurement consolidating under enterprise imaging agreements rather than standalone capital purchases. Biocompatibility testing per ISO 10993 and electrical safety certification under IEC 60601-1 constrain vendor selection.
- Automotive:Light field integration with advanced driver-assistance systems creates manufacturing scale that benefits holographic component suppliers across multiple end markets. German OEMs and their tier-one suppliers in Baden-Württemberg dominate current program awards, with head-up display convergence driving dual-use production economics.
- Entertainment:Immersive installation projects and location-based experiences absorb lower-fidelity holographic displays where spectator throughput outweighs individual image quality.
- Aerospace:Cockpit visualization and maintenance training applications demand environmental ruggedization that extends development cycles and sustains premium pricing.
Revenue concentrates in Healthcare; expansion accelerates fastest in Automotive.
Technology:
Physics modality determines supply chain concentration and regulatory exposure.
- Light Field Technology:Microlens arrays or multi-viewpoint capture reconstruct volumetric scenes without coherent sources. Automotive programs in Germany and immersive entertainment installations in the United States drive component demand. The approach trades absolute depth precision for eyebox tolerance and ambient light immunity, expanding addressable use cases beyond controlled laboratory environments.
- Electromagnetic Waves:Terahertz and millimeter-wave holography penetrates optically opaque materials for non-destructive testing and security screening. Industrial applications in Japan and Germany sustain specialized supplier ecosystems for high-power source components.
- Ultrasonic Waves:Acoustic holography serves medical imaging and industrial flaw detection where tissue or material penetration exceeds optical limits.
- Optical Tweezers:Focused laser trap arrays manipulate microscopic particles with holographic beam shaping, anchoring scientific instrumentation demand in research-intensive economies.
Deployment breadth favors Electromagnetic Waves; steepest expansion trajectory belongs to Light Field Technology.
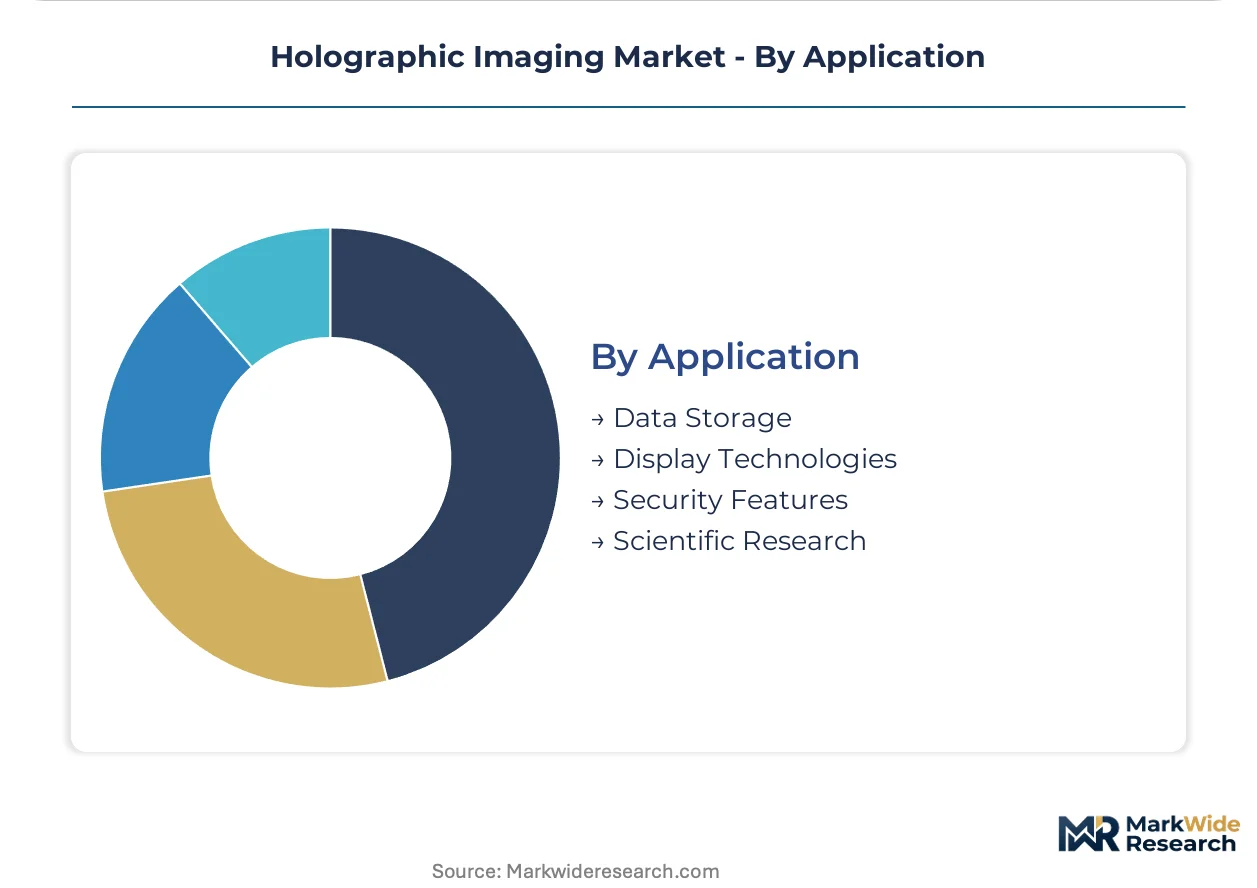
Application:
Margin structure separates commodity volume from premium pricing sustainability.
- Display Technologies:Direct-view holographic screens and projection systems command the largest revenue pool across consumer, professional, and industrial segments. Manufacturing scale in East Asian electronics clusters and German precision optics centers determines cost competitiveness. REACH restrictions on photoresist materials are forcing reformulation programs among EU-serving suppliers.
- Scientific Research:Specialized optics requirements and low production volumes sustain premium pricing that attracts component suppliers with captive fabrication capabilities. University procurement cycles and grant funding dependencies create demand lumpiness that rewards flexible manufacturing footprints.
- Data Storage:Holographic volumetric recording offers theoretical density advantages that remain commercially unrealized outside niche archival applications.
- Security Features:Overt and covert holographic authentication elements persist in currency, documents, and branded packaging despite digital substitution pressures.
Value concentrates in Display Technologies; pricing power endures strongest in Scientific Research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical imaging departments in the United States concentrate current demand for holographic surgical planning systems, while precision optics manufacturing clusters in Germany and emerging assembly incentives in India reshape supply-side geography.
United States
FDA 510(k) clearances for holographic visualization tools compress premarket timelines for surgical planning applications. Academic medical centers in California and Texas consolidate procurement under enterprise imaging agreements rather than standalone capital purchases. The Boston-Cambridge corridor anchors computational holography talent pipelines linking MIT and Harvard research labs to commercial spinouts.
Germany
EU MDR conformity requirements for holographic diagnostic systems extend commercialization timelines by 18-24 months relative to previous directives. The Jena and Oberkochen precision optics clusters accelerate prototype-to-product cycles through Fraunhofer Institute partnerships. Baden-Württemberg automotive OEMs drive light field technology integration with head-up display programs, creating dual-use manufacturing scale.
India
Production-linked incentive schemes for semiconductor and display manufacturing attract holographic hardware assembly to domestic tariff-protected zones. CDSCO medical device registration pathways for holographic surgical tools remain less streamlined than FDA equivalents, slowing hospital adoption. Bengaluru and Hyderabad photonics research parks house contract manufacturers serving export markets.
Japan
METI funding programs for next-generation display technologies sustain national holographic imaging R&D consortia. PMDA regulatory consultations for holographic interventional devices proceed through structured pre-submission meetings that reduce approval uncertainty. The Kansai region maintains specialized supplier ecosystems for diffractive optical element fabrication.
China
NMPA medical device classification rules for holographic diagnostic systems require domestic clinical trials that extend registration timelines for foreign manufacturers. MIIT industrial policy prioritizes domestic CMOS sensor and laser source production to reduce import dependency. Shenzhen and Shanghai electronics clusters integrate holographic display modules into consumer device supply chains.
Holographic Imaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with medical-grade wavelength stability requirements favoring captive fabrication capabilities while automotive and entertainment applications absorb outsourced component supply. The vendor base organizes around three archetypes: precision optics houses with semiconductor heritage, software-centric wavefront synthesis developers, and display-integrated platform builders. Consolidation pressures concentrate among diffractive optical element suppliers, while capacity expansion dominates CMOS sensor foundry relationships. Technology licensing agreements between German precision optics clusters and Asian electronics manufacturers accelerate geographic diversification of holographic component supply.
Within the software-centric tier, Leia Inc. and EON Reality occupy positions emphasizing computational reconstruction over optical hardware, while Zebra Imaging anchors the large-format printed hologram segment serving defense and architectural visualization. RealView Imaging exemplifies the medical specialization archetype, with Phase Holographic Imaging and Looking Glass Factory representing alternative technology pathways in live clinical visualization and immersive display platforms respectively. These companies illustrate how regulatory clearance strategies and end-market selection determine competitive positioning more than manufacturing scale alone.
| Leading Market Players |
|---|
| Leia Inc. |
| Zebra Imaging |
| RealView Imaging |
| Ovizio Imaging |
| Geola Digital UAB |
| EON Reality |
| Phase Holographic Imaging |
| Looking Glass Factory |
| Holoxica Limited |
| Others |
Supply Flow & Price Mechanics
Medical-grade wavelength stability requirements bifurcate holographic imaging into premium FDA-cleared surgical systems and cost-optimized automotive displays, with certification ladders in the United States and Germany dictating both margin structures and supplier qualification timelines. This tier divergence channels procurement toward captive fabrication for healthcare deployments while entertainment and automotive segments absorb outsourced CMOS sensor modules from East Asian foundries.
Pricing Analysis
Volume concentrates in display technologies while margins pool in scientific research and interventional cardiology systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared surgical planning platforms from automotive HUD components and consumer entertainment installations. Pricing pressure stems from silicon photonics integration collapsing coherent source costs in the United States and Germany. Hospital procurement committees exhibit lowest price sensitivity due to reimbursement pass-through mechanisms, while automotive tier-one suppliers negotiate aggressively on volume commitments.
Supply Chain Analysis
Workforce scarcity in computational holography and precision optics constrains expansion in Jena, Oberkochen, and the Boston-Cambridge corridor despite capital availability. Manufacturing gravity centers on Germany for diffractive optical elements, Japan for specialized laser sources, and Taiwan for CMOS sensor foundry capacity. Germanium substrate spot markets and photoresist feedstocks from Swiss and Dutch chemical suppliers anchor raw material dependencies. Single-source vulnerability concentrates in Japanese diffractive optical element suppliers. Distribution runs through direct hospital procurement in the United States and OEM tier-one integration in Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Holographic imaging vendors face a vertical-integration race to control coherent light source production and computational reconstruction IP, with silicon photonics expertise emerging as the decisive upstream lever for cost positioning.
For Market Incumbents: To counter silicon photonics cost compression from semiconductor foundries, deepen captive fabrication of single-frequency diode-pumped solid-state lasers and secure exclusive CMOS sensor allocation agreements with Taiwan foundries. Prioritize IEC 60601-1 third edition pre-certification to accelerate hospital procurement cycles. For New Entrants and Emerging Players: The premium-economy price gap in interventional cardiology visualization creates entry space for software-centric wavefront synthesis platforms targeting mid-tier cardiac centers outside specialized academic hospitals. Penetrate India's PLI-protected tariff zones for holographic hardware assembly serving export markets. Pursue automotive HUD convergence partnerships with Baden-Württemberg OEMs as manufacturing scale anchor. For Investors and Strategic Acquirers: Re-rating potential sits with precision optics houses possessing Fraunhofer Institute partnerships given EU MDR conformity acceleration and automotive dual-use demand. Long-term viability favors vertically integrated specialists controlling both diffractive optical element fabrication and computational algorithm IP. Monitor FDA 510(k) clearance velocity for holographic surgical planning tools as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Streamlines hospital procurement pathways for holographic surgical visualization platforms in the United States. |
| Silicon Photonics Integration | Collapses coherent source cost structures while preserving nanometer-scale wavelength stability for medical-grade systems. |
| Academic-Industry Partnership | Fraunhofer Institute collaborations in Jena and Oberkochen compress prototype-to-product cycles for precision optics. |
| Automotive HUD Convergence | Light field technology integration with advanced driver-assistance systems creates dual-use manufacturing scale. |
| Enterprise Imaging Agreement | Subscription-based software licensing with integrated hardware maintenance consolidates radiology and surgical procurement. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with holographic display engineers, hospital biomedical equipment managers, automotive tier-one procurement leads, and precision optics R&D directors provided qualitative calibration. FDA 510(k) databases, EU MDR notified body registers, PMDA consultation minutes, and CDSCO medical device registration logs supplied regulatory trajectory inputs. Bottom-up component demand modeling and top-down healthcare capital equipment spending analysis triangulated market sizing.
Data-stream reconciliation across hospital procurement databases, automotive program award tracking, and semiconductor foundry capacity disclosures stabilized volume projections. Segmentation modeling captured product type, end user, technology modality, application, and geographic regulatory cluster dimensions across the analysis window. CAGRs derived from installed base growth rates, replacement cycles, and penetration elasticity curves. Forecast inputs incorporated silicon photonics cost curves, REACH photoresist substitution timelines, and PLI scheme capacity buildouts.
Inputs from FDA pre-submission meeting records and Fraunhofer Institute partnership disclosures were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around near-term adoption velocity. Forecasts reflect documented assumptions regarding regulatory clearance timelines and automotive program award schedules. Material deviation in FDA software-as-medical-device guidance interpretation or EU MDR notified body capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Asia Pacific IP Camera Market
Imaging
AI Camera Market
Imaging
Photography Equipment Market
Imaging
Medical X-Ray Detectors Market
Imaging
Contact Image Sensor Market
Imaging
Global Digital Photography Market
Imaging
Middle East and Africa IP Camera Market
Imaging
Vintage Cameras Market
Imaging
Micro Computed Tomography Market
Imaging
3D Sensing and Imaging Market
Imaging
Facial Recognition Machine Market
Imaging
Computational Photography Market
Imaging
Global Panoramic Camera Market
Imaging
Global Pathology Imaging Systems Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
X Ray Tubes Market