
 Global Pathology Imaging Systems Market | 2026-2036
Global Pathology Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pathology Imaging Systems Market Intelligence
The move toward cloud-based deployment for image analysis software is consolidating value around subscription models and remote diagnostics. This shift favors vendors with strong software capabilities. Leica Biosystems leverages its hardware footprint to upsell integrated software. Koninklijke Philips N.V. specializes in platforms for large hospitals, while F. Hoffmann-La Roche Ltd. focuses on systems supporting its oncology research pipeline.
Pathology imaging systems are automated microscopy instruments that digitize glass tissue slides into high-resolution images, a process called whole slide imaging. These systems capture cellular-level detail at magnifications up to 40x for remote analysis. While digital slide scanners represent the core hardware for pathology labs, image analysis software is the fastest-growing product segment. Demand for AI-enabled software for cancer diagnosis is especially high among pharmaceutical companies and research institutions.
Market access is governed by stringent regulatory frameworks for medical devices. The FDA in the United States and the EMA in Europe mandate validation for systems used in primary diagnosis. In China, the NMPA sets standards for domestic and imported devices. A key decision for end-users remains the trade-off between on-premise data security and the scalability of cloud-based platforms.
Market Dynamics
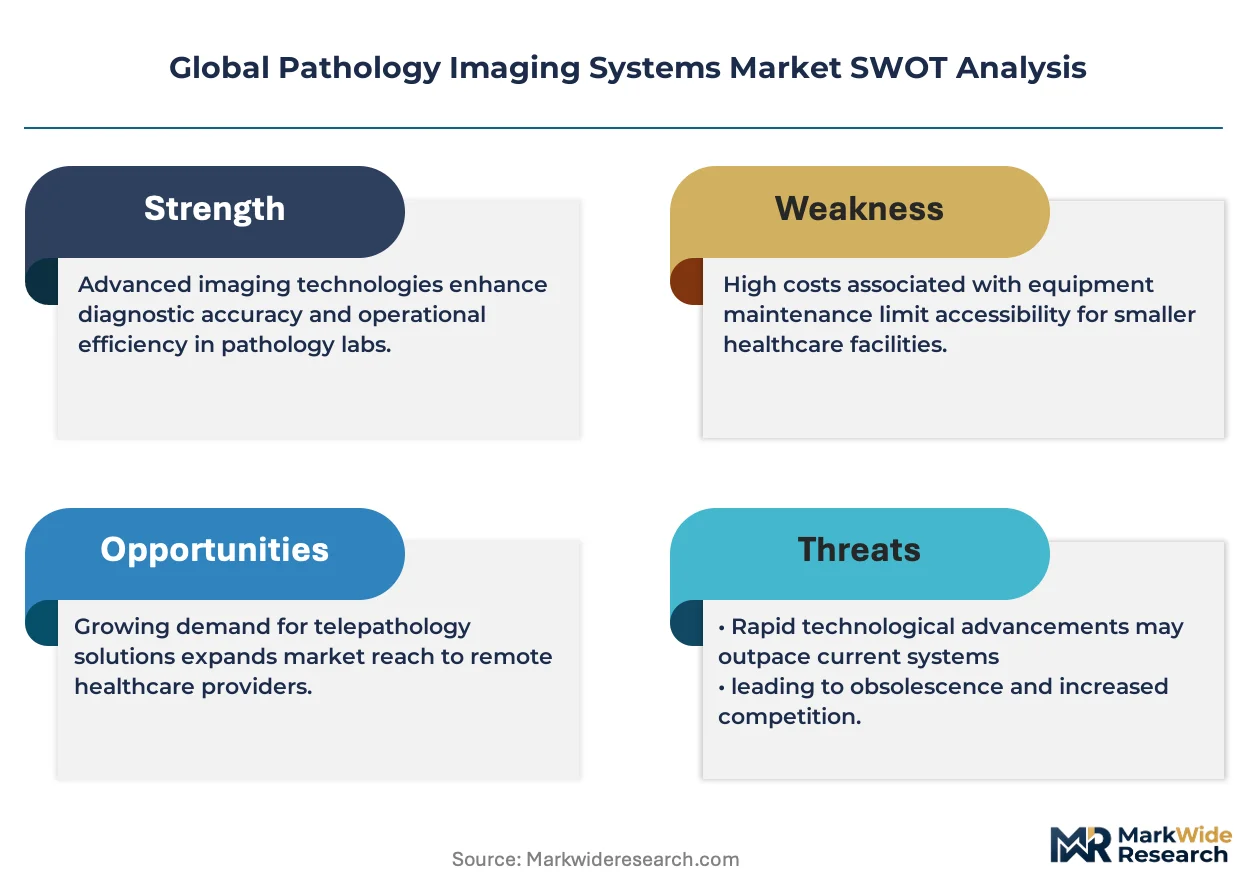
The integration of artificial intelligence into diagnostic workflows is the central force shaping the pathology imaging systems market. This shift moves systems beyond simple digitization, enabling computational pathology that extracts quantitative data from tissue slides, a development supported by evolving regulatory frameworks for AI in medical devices.
Growth Catalysts
- AI in Oncology:Demand from pharmaceutical companies for AI-enabled software to quantify biomarkers in oncology research and clinical trials accelerates system adoption for high-throughput analysis.
- Regulatory Clarity:Evolving guidelines from the FDA and EMA for the use of whole slide imaging in primary diagnosis are providing a clear validation pathway, encouraging labs to transition to digital workflows.
- Research Modernization:Government and academic research institutions in the United States and Germany are heavily investing in upgrading pathology departments with digital imaging capabilities to support advanced biomedical research.
Market Restraints
- High Capital Cost:The significant upfront investment required for whole slide scanners, high-performance computing, and data storage infrastructure remains a substantial barrier for smaller laboratories and hospitals.
- Data Management Burden:The massive file sizes of whole slide images create significant challenges for data storage, transfer, and management, requiring specialized IT infrastructure and expertise.
- Interoperability Standards:A lack of universal standardization across different vendor platforms hinders seamless data sharing and integration, creating friction for laboratories using equipment from multiple manufacturers.
Strategic Opportunities
- Cloud-Based PaaS:The development of Pathology-as-a-Service platforms presents an opportunity to lower adoption barriers by offering subscription-based access to scanning and analysis capabilities.
- Expansion in Emerging Markets:Modernizing pathology services in countries like China and India, supported by government healthcare initiatives, offers significant growth potential for system vendors.
- New Diagnostic Applications:Extending digital pathology beyond oncology into areas such as nephrology, neurology, and infectious disease diagnostics opens new revenue streams and clinical use cases.
Industry Challenges
- Specialized Talent Gap:A shortage of pathologists and technicians with expertise in digital pathology workflows, image analysis software, and IT management constrains the effective utilization of deployed systems.
- Legacy System Integration:The complexity of integrating digital pathology systems with existing and often fragmented Laboratory Information Systems (LIS) and hospital Electronic Health Records (EHR) is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pathology Imaging Systems Market |
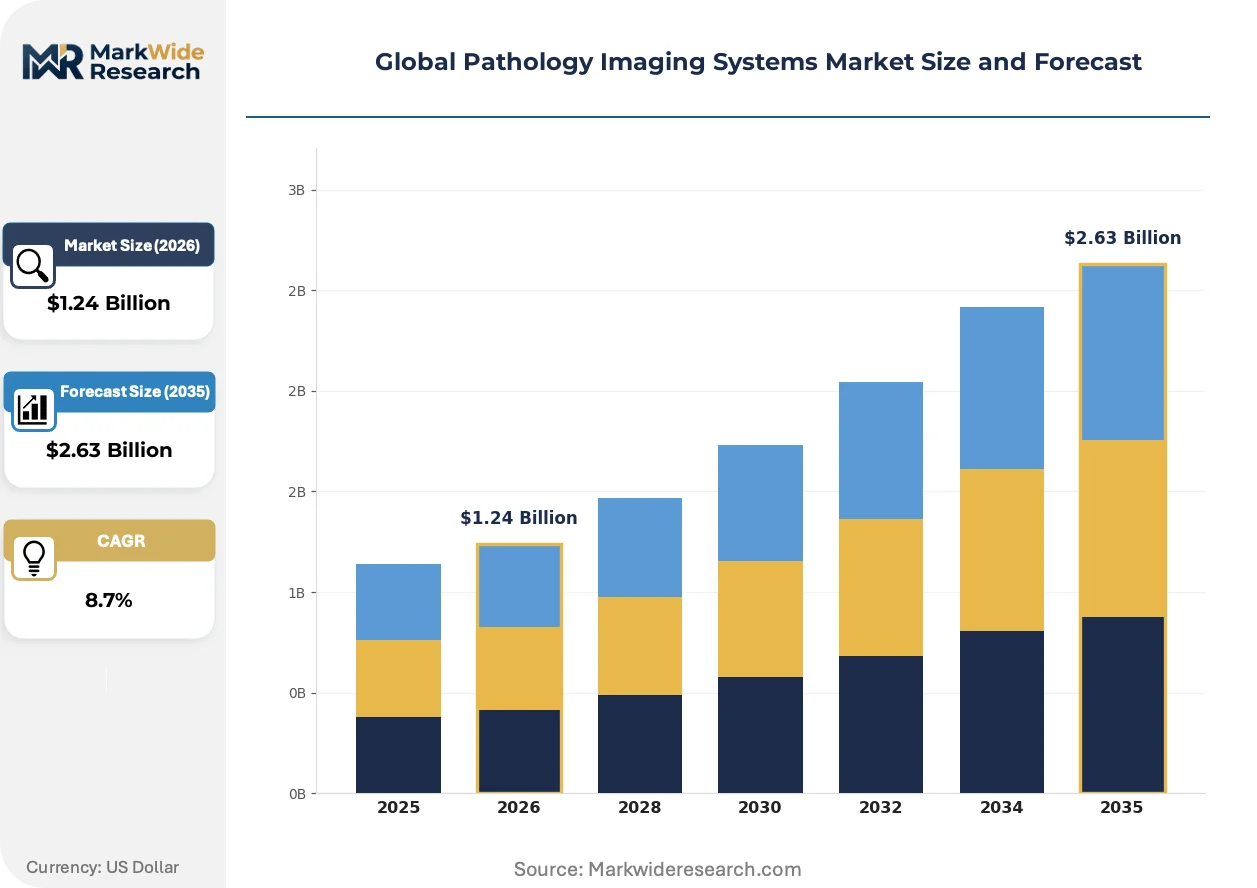
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.63 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Slide Scanners, Whole Slide Imaging, Image Analysis Software, Archiving Systems Application: Cancer Diagnosis, Tissue Analysis, Clinical Research, Educational Training, Quality Control End User: Pathology Labs, Research Institutions, Pharmaceutical Companies, Diagnostic Centers, Academic Centers Deployment: On-Premise, Cloud-Based, Hybrid, Remote Diagnostics |
| Companies Covered | Leica Biosystems, Hamamatsu Photonics K.K., Koninklijke Philips N.V., F. Hoffmann-La Roche Ltd., Olympus Corporation, Sakura Finetek, 3DHISTECH Ltd., PerkinElmer Inc., GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pathology Imaging Systems Market Strategic Shifts & Innovations
Data-driven diagnostics are becoming the standard of care, pushing the market beyond simple image capture toward integrated platforms for quantitative analysis. This evolution is defined by advancements in computational tools, clearer regulatory pathways, and new service delivery models that prioritize scalability and analytical power.
Multiplex imaging technologies are gaining traction in translational research. These systems permit the simultaneous detection and quantification of numerous biomarkers within a single tissue section, providing deep spatial context. Research institutions and pharmaceutical companies are adopting this technology to understand complex disease mechanisms, particularly in immuno-oncology, and it is absorbing the role of sequential single-marker analysis.
The EU's In Vitro Diagnostic Regulation (IVDR) is harmonizing the requirements for market access across member states. This regulation imposes stricter clinical evidence and post-market surveillance obligations on manufacturers of diagnostic software and hardware. As a result, the image analysis software segment is most affected, with vendors now investing more heavily in rigorous validation studies to secure CE marking.
A transition from one-time hardware sales to enterprise-level partnerships is altering commercial relationships. Customers are seeking integrated solutions that bundle scanners, software, and long-term service agreements, often through subscription models. This shift away from siloed procurement is most visible in large hospital networks in the United States, which prioritize vendor consolidation and platform standardization.
Global Pathology Imaging Systems Market Segmentation
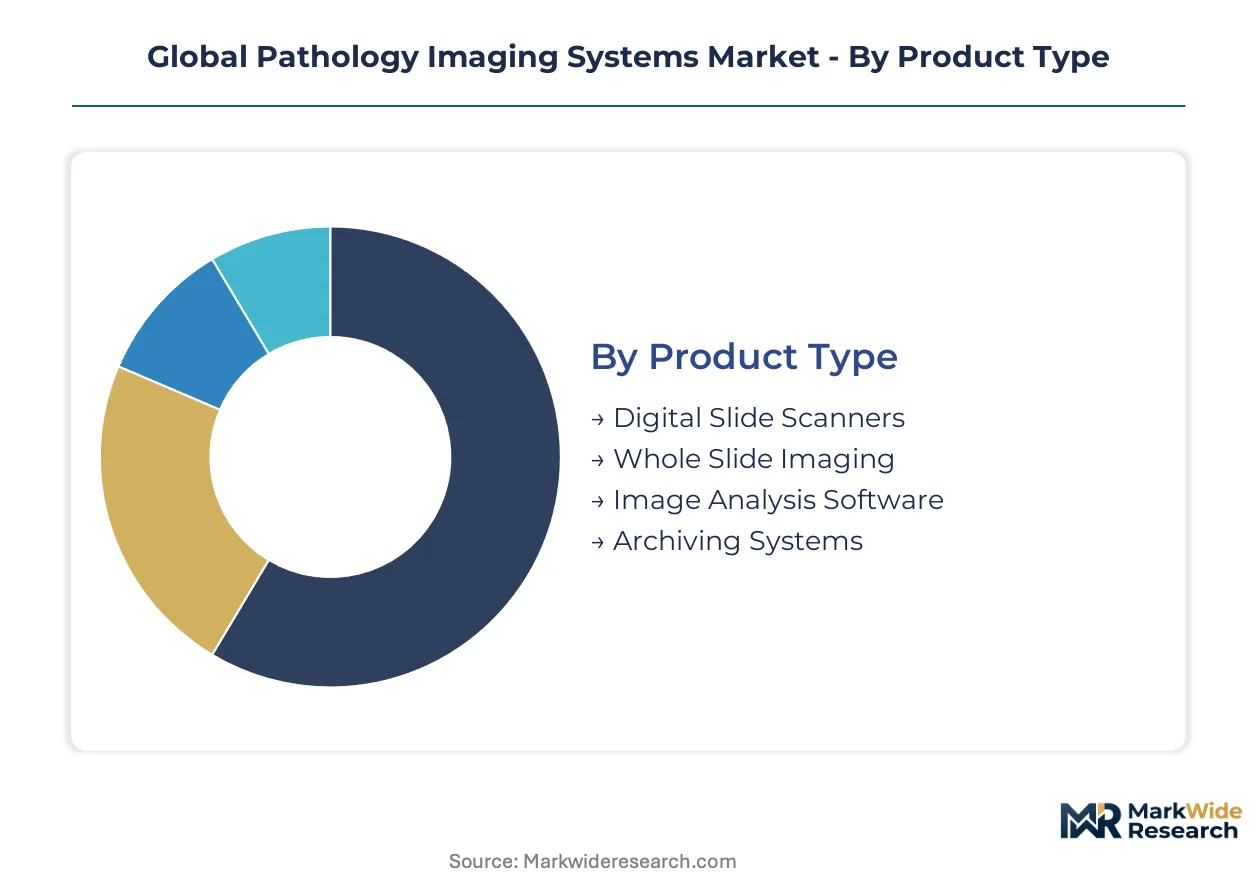
The Global Pathology Imaging Systems Market is delineated by distinct segments that reflect technological advancements, varied application needs, and diverse end-user requirements. Understanding these segmentations is crucial for identifying specific market opportunities and tailoring product development to meet evolving industry demands.
Product Type:
The choice of pathology imaging system product type often hinges on a laboratory's specific diagnostic needs and workflow integration requirements.
- Digital Slide Scanners:These instruments automate the process of converting glass microscope slides into high-resolution digital images. Demand is strong from diagnostic centers in Germany and research institutions in the United States, driven by the need for remote pathology consultation and efficient case management.
- Image Analysis Software:This software extracts quantitative data from digitized slides, often incorporating AI algorithms for pattern recognition and biomarker quantification. Pharmaceutical companies are heavily investing in these solutions for oncology research, accelerating drug discovery and clinical trial analysis.
- Whole Slide Imaging:This technology involves capturing an entire glass slide at high magnification, producing a single, comprehensive digital image.
- Archiving Systems:These platforms manage the storage, retrieval, and long-term preservation of massive digital slide image files for regulatory compliance and future reference.
Volume sits with Digital Slide Scanners; growth tilts toward Image Analysis Software.
Application:
Different end-user segments drive demand for pathology imaging systems across various applications, each prioritizing specific functional outcomes.
- Cancer Diagnosis:This application involves the primary diagnosis and grading of cancerous tissues from digital slides, replacing traditional microscopy in many settings. Regulatory clarity from the FDA and EMA is encouraging wider adoption in large hospital networks, improving diagnostic turnaround times.
- Clinical Research:Pathology imaging systems support drug development and biomarker discovery by enabling quantitative analysis of tissue samples in pharmaceutical and academic studies. Pharmaceutical companies utilize these systems for high-throughput analysis in oncology, accelerating therapeutic advancements.
- Tissue Analysis:This involves detailed examination of tissue morphology and cellular structures for various disease states beyond oncology.
- Educational Training:Digital slides provide standardized teaching materials for pathology residents and medical students across universities in the United States and Europe.
- Quality Control:Systems ensure consistency and accuracy in laboratory processes, verifying slide preparation and diagnostic output.
The steepest expansion trajectory is observed in Clinical Research, while Cancer Diagnosis represents foundational demand.
End User:
The scale of investment in pathology imaging systems varies significantly across end-user types, reflecting their operational models and research priorities.
- Pharmaceutical Companies:These entities leverage digital pathology for biomarker quantification, drug discovery, and toxicology studies, particularly in oncology pipelines. Their high demand for AI-enabled software drives significant system adoption for high-throughput analysis and data-driven insights.
- Diagnostic Centers:These facilities are upgrading their imaging capabilities to enhance efficiency, enable remote consultations, and integrate AI for improved diagnostic accuracy. Investment in digital slide scanners is strong in countries like the United States and Germany, driven by increasing patient volumes.
- Pathology Labs:These laboratories adopt digital systems for primary diagnosis, second opinions, and case archiving, modernizing traditional workflows.
- Research Institutions:Academic and government-funded research centers utilize these systems for advanced biomedical studies and translational research.
- Academic Centers:Universities and medical schools employ digital pathology for teaching, research, and clinical trials.
Growth is primarily driven by Pharmaceutical Companies, with Diagnostic Centers maintaining a stable baseline.
Deployment:
Data management considerations, particularly regarding security and scalability, heavily influence the preferred deployment model for pathology imaging systems.
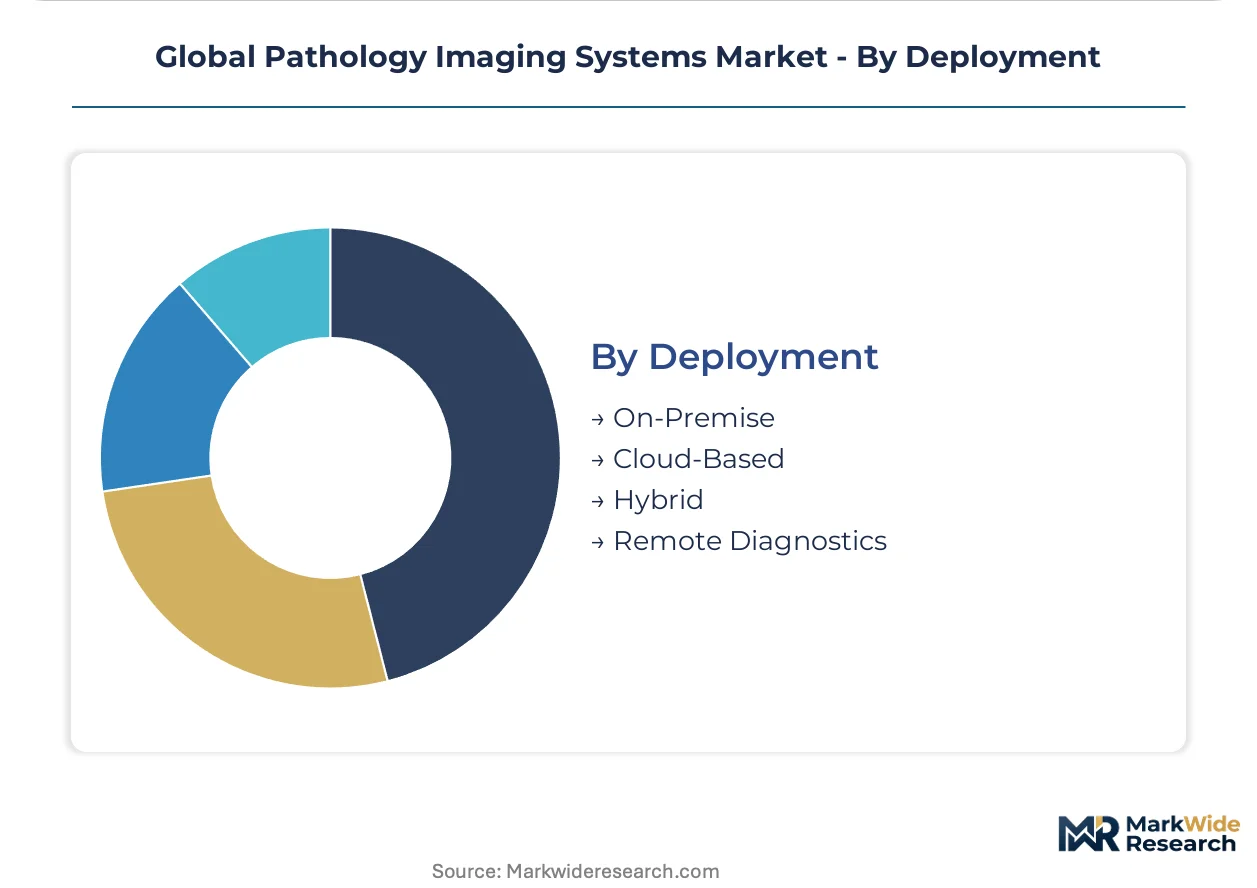
- Cloud-Based:This model offers subscription-based access to software and storage, enabling remote diagnostics and scalability without significant upfront IT infrastructure investment. Vendors with strong software capabilities are favored as laboratories seek flexible, accessible solutions for image analysis.
- On-Premise:Systems are hosted on local servers within the institution, providing maximum data control and security, which is critical for sensitive patient information. Large hospitals and research institutions often prefer this model for their established IT infrastructure and compliance needs.
- Hybrid:This approach combines local storage for critical data with cloud resources for scalability and remote access, balancing security with flexibility.
- Remote Diagnostics:This capability, often enabled by cloud or hybrid deployments, allows pathologists to analyze digital slides from any location, improving access to specialized expertise.
The market is shifting towards Cloud-Based for flexibility, while On-Premise remains critical for data sovereignty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Global Pathology Imaging Systems Market exhibits a distinct divide between regions driving technological innovation and those undergoing rapid infrastructure modernization. Highly developed economies often lead in advanced software adoption and research, while emerging markets focus on foundational digitization to expand healthcare access.
United States
Demand for pathology imaging systems in the United States stems from pharmaceutical companies for oncology research and diagnostic centers upgrading capabilities. FDA guidelines for primary diagnosis provide a clear validation pathway, encouraging digital workflow transitions. Major research institutions and diagnostic networks across states like California are heavily investing in these advanced systems.
Germany
Germany’s market demand is strong from diagnostic centers seeking efficient remote pathology consultation and academic research institutions modernizing their departments. The EMA’s evolving guidelines, alongside CE marking requirements for IVDR, influence system validation. Biomedical clusters in Bavaria and North Rhine-Westphalia are key hubs for pathology imaging system adoption and innovation.
China
China presents significant growth potential as government healthcare initiatives prioritize modernizing pathology services across its vast population. The NMPA sets stringent standards for domestic and imported medical devices, influencing market access. Major urban centers like Shanghai and Beijing are seeing substantial investments in digital pathology infrastructure to enhance diagnostic capabilities.
India
Modernizing pathology services in India, supported by government healthcare reforms, drives demand for digital imaging systems to improve diagnostic reach. The CDSCO oversees medical device regulations, ensuring quality and safety for imported and locally manufactured systems. Growing diagnostic networks and hospital chains in cities such as Mumbai and Bangalore are adopting digital pathology solutions.
United Kingdom
The United Kingdom sees demand from pharmaceutical companies for biomarker quantification in oncology and academic centers for advanced biomedical studies. The MHRA’s regulatory framework, often aligning with European standards, guides market entry. Bio-pharma clusters around London and Cambridge actively integrate these systems into their research pipelines.
Global Pathology Imaging Systems Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the Global Pathology Imaging Systems Market, creating a dynamic competitive environment. The market structure blends established hardware manufacturers with agile software developers specializing in image analysis. Strategic archetypes include integrated solution providers, specialized software developers, and platform providers for large institutions. Dominant competitive moves involve strategic partnerships to broaden portfolios and targeted M&A for acquiring AI capabilities.
Integrated solution providers like Leica Biosystems leverage their hardware footprint to upsell comprehensive software platforms, offering end-to-end digital pathology solutions. Koninklijke Philips N.V., a Netherlands-based electronics conglomerate, exemplifies a platform specialist, focusing on large hospital networks with extensive imaging requirements and interoperability needs. F. Hoffmann-La Roche Ltd., a Swiss pharmaceutical company, anchors the oncology research segment, offering systems tailored to its drug discovery and clinical trial pipeline, particularly for biomarker quantification. These entities represent distinct approaches to market engagement, from broad-spectrum offerings to highly specialized applications.
| Leading Market Players |
|---|
| Leica Biosystems |
| Hamamatsu Photonics K.K. |
| Koninklijke Philips N.V. |
| F. Hoffmann-La Roche Ltd. |
| Olympus Corporation |
| Sakura Finetek |
| 3DHISTECH Ltd. |
| PerkinElmer Inc. |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
The EU's In Vitro Diagnostic Regulation (IVDR) gates qualified supply and premium-tier pricing access for pathology imaging systems. This regulation mandates rigorous clinical evidence for digital pathology devices, influencing market entry and cost structures.
Pricing Analysis
Pricing pressure intensifies in the image analysis software segment as vendors compete for market share. Subscription models dominate, offering flexible access to advanced analytical tools. Price differentiation stems from the sophistication of AI algorithms and the level of regulatory validation, such as FDA clearance. Smaller diagnostic centers exhibit higher price sensitivity compared to large pharmaceutical companies seeking advanced oncology research solutions.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly common among pathology imaging system manufacturers. Geographic supply concentration for optical and sensor technologies centers in Japan, Germany, and the United States. The supply chain relies on specialized high-resolution optical components and high-performance computing chips. Single-source vulnerability for specialized optics presents a structural risk. Distribution runs through direct sales channels to large hospital networks and partnerships with regional distributors for smaller diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global pathology imaging systems market is undergoing consolidation, driven by the significant capital cost required for advanced digital infrastructure.
For Market Incumbents: To counter the threat from agile software developers specializing in AI, market incumbents must prioritize strategic acquisitions of AI-focused startups. Deepen vertical integration into image analysis software development, leveraging existing hardware footprints for platform lock-in. Invest heavily in R&D for advanced computational pathology algorithms to maintain technological leadership. Focus on securing long-term enterprise-level partnerships with large hospital networks.
For New Entrants and Emerging Players: Evolving IVDR guidelines in Europe open a window for new entrants offering rigorously validated AI-enabled software. Target cloud-based Pathology-as-a-Service (PaaS) platforms for smaller laboratories and specialized research institutions. Focus on new diagnostic applications beyond oncology, such as neurology or infectious disease. A subscription-based, lower upfront cost model provides an effective go-to-market angle.
For Investors and Strategic Acquirers: FDA or EMA approval of AI algorithms for primary diagnosis is the leading indicator that the pathology imaging market is maturing for investment. The long-term viability favors integrated platforms offering end-to-end digital pathology solutions. Acquire specialized AI-enabled software developers or cloud-based PaaS providers to gain analytical capabilities. Watch for a significant uptick in enterprise-level contracts from large diagnostic networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundles hardware and software, enhancing user experience and data flow for diagnostic centers. |
| Strategic Partnership | Combines hardware expertise with AI software capabilities, creating comprehensive solutions for pharmaceutical companies. |
| Acquisition of Specialist Firm | Accelerates access to cutting-edge AI algorithms, crucial for biomarker quantification in oncology research. |
| Geographic Expansion | Penetrates emerging markets like India and China, addressing unmet diagnostic needs with digital systems. |
| Regulatory Approval Pathway | Secures market access for AI-enabled diagnostics, building trust among clinicians and research institutions. |
Research Approach
Document review covered academic journals, regulatory filings from the FDA and EMA, and specialized industry reports, complemented by interviews with key stakeholders. Primary interviews engaged pathologists, laboratory managers, IT specialists, and pharmaceutical R&D leads to gather qualitative insights. This approach combined top-down market sizing with bottom-up validation from industry participants. Secondary data sources included clinical trial registries and government healthcare statistics.
The quantitative model produced volume and value forecasts across the analysis window. The analytical framework segmented the market by product type, application, end-user, deployment model, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data analysis, expert consensus, and projected technology adoption rates. Key forecast inputs included investment trends in research institutions and the integration rates of AI in diagnostic workflows.
The model assumes a particular technology adoption path; alternative pathways for AI integration would alter the outlook. Forecasts reflect assumptions regarding evolving regulatory frameworks and market acceptance of digital pathology solutions. Deviation in AI algorithm validation timelines or significant shifts in healthcare spending would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
AI-Based Fever Detection Camera Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Virtual Reality Camera Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Global Whole Slide Imaging Market
Imaging
Asia Pacific IP Camera Market
Imaging
IP Camera Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
Machine Vision Market
Imaging
Global Digital Photo Frame Market
Imaging
Global Image Sensors Market
Imaging
Pico Projector Market
Imaging
Facial Recognition Machine Market
Imaging
In Vivo Imaging Systems Market
Imaging
CMOS Smartphone Camera Lens Market