
 Global Panoramic Camera Market | 2026-2036
Global Panoramic Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global Panoramic Camera Market Outlook
Market Context
The gap between premium cinematic rigs and mass-market action cameras is expanding as resolution thresholds and software ecosystems diverge. Samsung Electronics leverages its semiconductor fabrication scale to control sensor supply chains for high-end spherical units. Insta360 specializes in compact multi-lens architectures that dominate consumer and prosumer channels. Canon anchors professional film production workflows with cinema-grade 360-degree systems and proprietary color science.
Technical Definition and Segments
Panoramic cameras capture seamless 360-degree fields of view through single-lens fisheye optics or synchronized multi-lens arrays, stitching frames via onboard sensor fusion algorithms to output equirectangular or cubic projection formats for immersive display. Spherical cameras lead professional virtual reality capture while integrated cameras with embedded data processing are gaining fastest in surveillance deployments where edge analytics reduce bandwidth loads. Multi-lens cameras command premium margins in film production where post-production flexibility determines equipment selection, whereas wireless connectivity technology is maturing into a baseline expectation across all price tiers.
Regulatory Outlook
The FCC governs wireless transmission protocols for panoramic devices operating in unlicensed spectrum bands, while GDPR and the EU AI Act impose constraints on biometric capture and automated facial analysis in public surveillance feeds. China's GB standards and MIIT certification requirements shape product compliance for manufacturers targeting domestic smart city tenders. Stakeholders must monitor evolving cross-border data localization mandates that determine where captured panoramic content can be processed and stored.
Market Dynamics
Algorithmic transparency mandates under the EU AI Act are forcing surveillance OEMs to reengineer embedded analytics architectures, compressing development timelines and reshaping competitive positioning across the imaging stack.
Growth Catalysts
- Smart city infrastructure mandates:China's municipal procurement cycles are accelerating deployments of 360-degree surveillance across transportation hubs and public squares, driven by dual carbon goals and urban digitalization targets.
- Edge computing convergence:Onboard sensor fusion is reducing bandwidth loads in commercial security networks, enabling real-time threat detection without cloud dependency.
- GDPR-compliant biometric frameworks:European public safety agencies are procuring panoramic units with privacy-preserving analytics to satisfy automated facial analysis restrictions while maintaining coverage density.
Market Restraints
- CMOS sensor supply concentration:Advanced backside-illuminated chips depend on fabrication capacity concentrated in Taiwan and South Korea, exposing procurement to geopolitical friction.
- FCC spectrum licensing costs:Unlicensed band congestion in dense urban deployments forces commercial users toward costly licensed spectrum or wired backhaul alternatives.
- Optical stitching complexity:Multi-lens arrays require sub-pixel calibration precision that elevates manufacturing yield losses and quality control overhead.
Strategic Opportunities
- India smart city expansion:The PLI scheme for electronics manufacturing is attracting component localization investments that reduce landed costs for municipal surveillance tenders.
- Immersive telepresence adoption:Corporate hybrid work policies are driving enterprise procurement of spherical capture systems for virtual meeting room deployments.
- 5G-Advanced broadcast integration:Mobile network operators in Germany and Japan are testing multicast delivery of live 360-degree content for sports and entertainment verticals.
Industry Challenges
- Computational photography talent scarcity:The intersection of optical engineering and machine learning optimization requires skill sets concentrated among semiconductor and smartphone camera veterans.
- Cross-border data localization compliance:Fragmented sovereignty requirements across the EU, China, and Middle Eastern markets force redundant cloud infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Panoramic Camera Market |
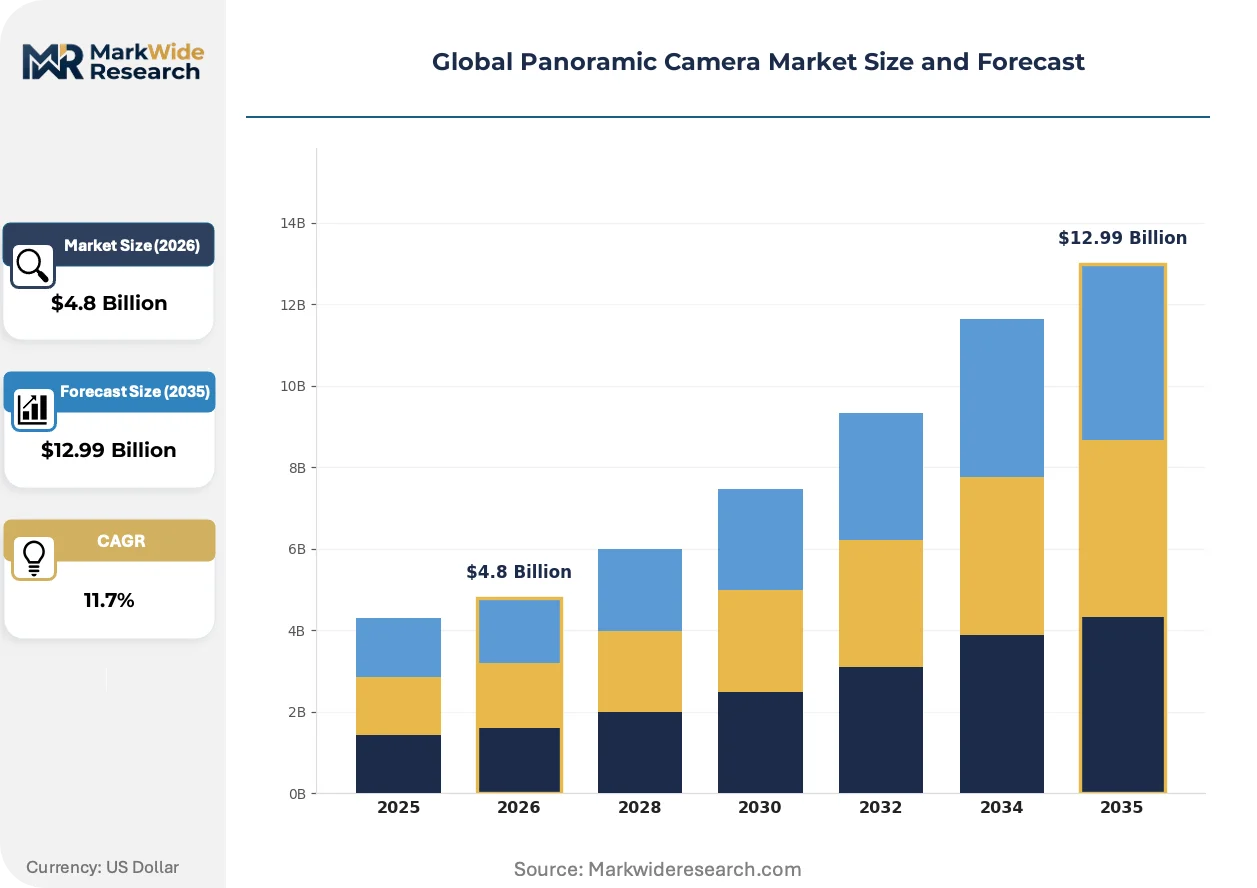
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spherical Cameras, 360-Degree Cameras, Multi-Lens Cameras, Integrated Cameras Application: Virtual Reality, Film Production, Real Estate, Surveillance End User: Content Creators, Interior Designers, Security Companies, Event Planners Technology: Digital Imaging, Wireless Connectivity, Data Processing, Sensor Fusion |
| Companies Covered | Samsung Electronics, Canon, Insta360, Panono, Sony, GoPro, Nikon, 360fly, Ricoh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Panoramic Camera Market Strategic Shifts
Computational imaging pipelines are displacing traditional optical complexity, enabling smaller form factors while software-defined architectures allow post-purchase feature activation that restructures hardware refresh cycles.
Sensor fusion chipsets is modularizing the boundary between lens modules and processing substrates. Automotive Tier 1 suppliers are adopting standardized camera heads with swappable compute backends to satisfy varying autonomy levels. This architecture is modularizing procurement decisions, allowing fleet operators to upgrade analytics capabilities without replacing optical hardware.
The EU AI Act's risk classification framework for biometric identification systems is compressing product development timelines for surveillance OEMs serving European public sector clients. Systems deployed in municipal spaces must now demonstrate algorithmic explainability and human oversight protocols before tender qualification. Professional security integrators in France and Germany are prioritizing vendors with pre-certified transparency documentation to accelerate deployment authorization.
Enterprise buyers are consolidating vendor relationships around full-stack solution providers capable of delivering capture hardware, cloud storage, and analytics subscriptions through single procurement frameworks. Systems integrators are displacing traditional distributor networks in North American commercial security channels, capturing margin through bundled installation and managed services. This concentration is most visible in United States healthcare campus deployments where HIPAA-compliant video retention requirements favor turnkey contracts over component sourcing.
Global Panoramic Camera Market Segmentation
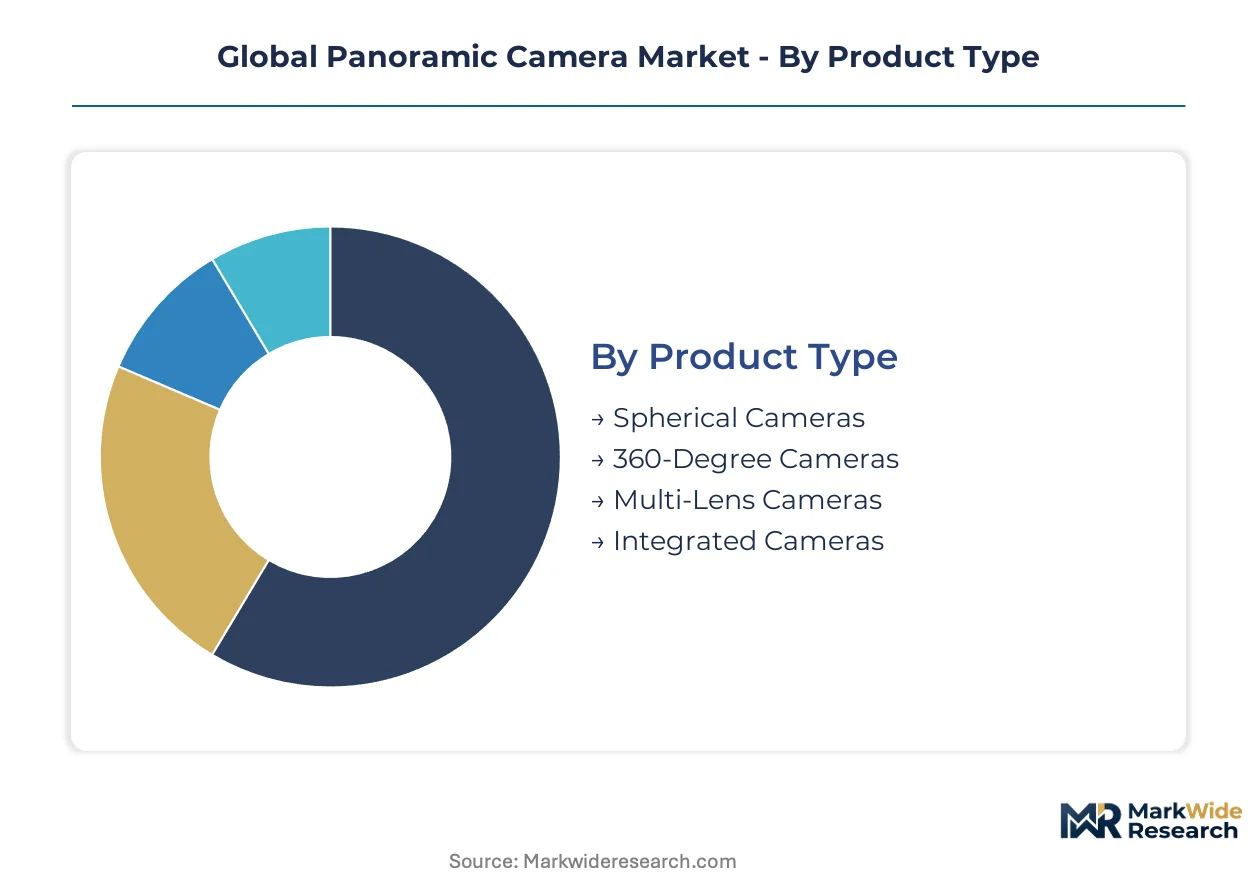
Panoramic camera segmentation reflects divergent integration architectures—standalone capture devices versus embedded vision systems—each demanding distinct supply chain partnerships and software ecosystems. Procurement patterns split sharply between professional film workflows requiring post-production flexibility and security deployments prioritizing edge analytics bandwidth reduction.
Product Type:
Integration depth separates standalone spherical units from embedded multi-lens arrays that fuse directly with processing substrates.
- Spherical Cameras:Single-lens fisheye optics capture complete hemispherical fields in one exposure, eliminating parallax errors during stitching. Demand concentrates in Los Angeles and London film production hubs where proprietary color science determines equipment selection. Virtual reality content pipelines require these units for immersive capture workflows.
- Multi-Lens Cameras:Synchronized sensor arrays achieve sub-pixel calibration precision for cinematic resolution. German broadcasters and Japanese sports networks drive procurement for live 360-degree event coverage where post-production flexibility justifies premium hardware investment.
- 360-Degree Cameras:Consumer-grade dual-lens architectures dominate prosumer channels with compact form factors.
- Integrated Cameras:Embedded sensor-fusion modules reduce to chip-scale for automotive and surveillance OEM integration.
Spherical cameras lead volumes today; integrated cameras are gaining share fastest.
Application:
Cost tier stratification separates premium cinematic workflows from mass-market security deployments.
- Surveillance:Municipal procurement across Shenzhen and Dubai transportation hubs drives volume for edge-analytics-enabled units that process threat detection onboard. GDPR-compliant biometric frameworks in France and Germany accelerate privacy-preserving panoramic deployment in public squares.
- Film Production:Hollywood studios and Bollywood post-houses command premium margins for cinema-grade spherical systems with RAW output and genlock synchronization. Color science IP determines vendor selection in professional workflows.
- Virtual Reality:Meta and Pico platform content requirements shape hardware specifications for immersive capture.
- Real Estate:Matterport-compatible capture drives compact multi-lens adoption for property virtualization.
Surveillance leads volumes today; film production commands the steepest expansion trajectory in value terms.
End User:
Customer type determines procurement channel structure—direct enterprise sales versus distributor networks versus platform-integrated hardware.
- Security Companies:Fleet deployments across commercial properties in Texas and Florida favor turnkey contracts bundling hardware, cloud storage, and managed analytics services. HIPAA-compliant video retention requirements in United States healthcare campuses consolidate vendor relationships around full-stack providers.
- Content Creators:YouTube and TikTok native formats drive compact wireless-enabled unit sales through direct-to-consumer channels. Insta360 and GoPro ecosystem lock-in shapes repeat purchase patterns.
- Interior Designers:Matterport and Cupix platform subscriptions drive hardware attachment rates for spatial documentation.
- Event Planners:Corporate hybrid work policies in Germany and Japan spur immersive telepresence procurement for virtual meeting room deployments.
Security companies lead volumes today; content creators are expanding most quickly in unit shipments.
Technology:
Supply concentration in CMOS fabrication and wireless chipsets shapes competitive positioning across the imaging stack.
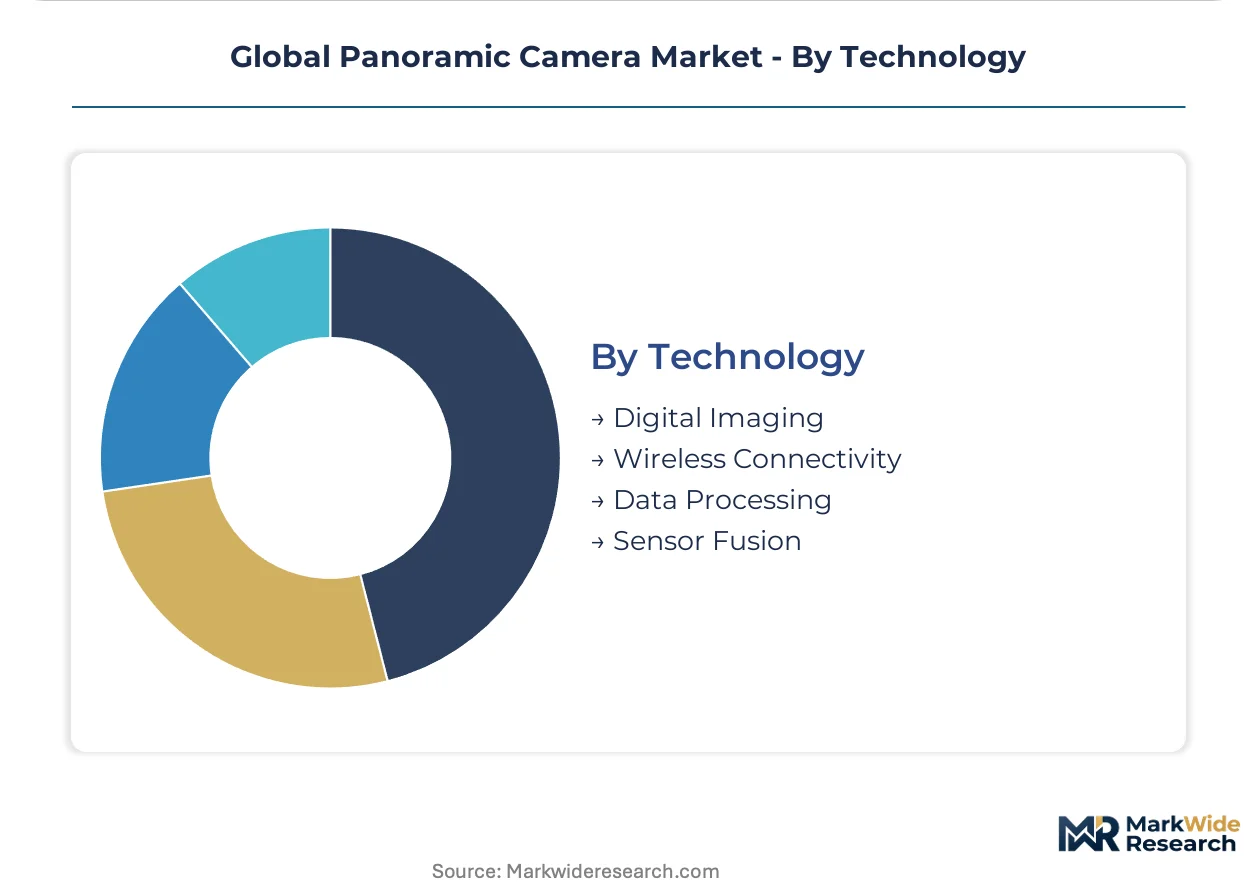
- Sensor Fusion:Onboard algorithms stitching multi-lens feeds into equirectangular projection reduce cloud dependency for real-time applications. Taiwan Semiconductor fabrication capacity backs advanced backside-illuminated chip supply for high-end spherical units.
- Wireless Connectivity:5G-Advanced multicast trials by Deutsche Telekom and NTT Docomo enable live 360-degree sports broadcast delivery. FCC unlicensed band congestion in dense Manhattan deployments pushes commercial users toward licensed spectrum alternatives.
- Digital Imaging:Computational photography pipelines displace optical complexity for smaller form factors.
- Data Processing:Edge AI chipsets from Qualcomm and Ambarella enable embedded analytics without cloud round-trips.
Digital imaging leads volumes today; sensor fusion is climbing the fastest in security-integrated applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computational photography talent clusters in Shenzhen, Los Angeles, and Tokyo anchor geographic specialization across the imaging stack. Sensor fabrication engineers concentrate in Hsinchu and Seoul, while post-production workflows gravitate toward London and Mumbai. Regulatory divergence across GDPR jurisdictions, China's MIIT certification, and FCC spectrum governance fragments compliance architectures.
China
Municipal procurement in Shenzhen and Shanghai drives fleet deployments of 360-degree surveillance units across transportation hubs and public squares. MIIT certification requirements and GB standards shape product compliance for manufacturers targeting domestic smart city tenders. Yangtze River Delta fabrication clusters supply backside-illuminated CMOS chips for high-end spherical units.
United States
Hollywood studios and Texas healthcare campuses command premium margins for cinema-grade spherical systems and HIPAA-compliant video retention. FCC unlicensed band congestion in Manhattan forces commercial security users toward licensed spectrum alternatives. Greater Los Angeles post-houses determine equipment selection through proprietary color science requirements.
Germany
Deutsche Telekom's 5G-Advanced multicast trials enable live 360-degree sports broadcast delivery across Bavaria and North Rhine-Westphalia. The EU AI Act's algorithmic transparency mandates compress development timelines for surveillance OEMs serving French and German public sector clients. Berlin-Brandenburg security integrators prioritize vendors with pre-certified transparency documentation.
Japan
NTT Docomo tests multicast delivery of immersive content for sports verticals in Tokyo and Osaka metropolitan areas. METI industrial policy supports domestic sensor fusion chipset development for automotive Tier 1 adoption. Kansai broadcasters drive procurement for live event coverage where post-production flexibility justifies premium hardware investment.
India
The PLI scheme for electronics manufacturing attracts component localization investments that reduce landed costs for municipal surveillance tenders in Maharashtra and Karnataka. CDSCO and BIS compliance frameworks shape product specifications for security deployments. Delhi-NCR smart city expansions accelerate procurement cycles for edge-analytics-enabled panoramic units.
Global Panoramic Camera Market Competitive Environment
Top-tier vendors anchor professional film and enterprise security segments, while mid-tier specialists dominate prosumer and content creator channels. The vendor base stratifies across semiconductor-scale fabricators, optical system integrators, and software-defined camera platforms. Three archetypes predominate: sensor supply chain controllers, multi-lens architecture specialists, and full-stack solution providers bundling hardware with cloud analytics. Competitive moves center on strategic partnerships for edge AI chipsets and geographic expansion through systems integrator networks.
Within the full-stack solution tier, Samsung Electronics exemplifies semiconductor-scale control over sensor supply chains, while Canon occupies a position anchoring professional film production workflows. Insta360 represents the compact multi-lens architecture specialists dominating consumer and prosumer channels. These three companies illustrate how competitive positioning diverges across resolution thresholds and software ecosystems.
| Leading Market Players |
|---|
| Samsung Electronics |
| Canon |
| Insta360 |
| Panono |
| Sony |
| GoPro |
| Nikon |
| 360fly |
| Ricoh |
| Others |
Value Chain & Pricing Dynamics
Computational imaging pipelines are displacing traditional optical complexity across spherical and multi-lens architectures, simultaneously collapsing manufacturing yields for legacy glass-heavy designs while concentrating value capture among semiconductor-scale fabricators with captive sensor supply. This dual transition compresses margins for pure-play optical houses while elevating pricing power for vendors controlling backside-illuminated CMOS fabrication.
Pricing Analysis
Bundled hardware-analytics-subscription contracts dominate enterprise security procurement, while unbundled transactional sales persist in prosumer channels. Three-tier pricing structure across premium cinema-grade, standard commercial surveillance, and economy consumer levels tracks resolution thresholds and software ecosystem depth. Cost compression in the economy tier intensifies because sensor fusion chipsets commoditize at volume, though HIPAA-compliant healthcare campuses and EU AI Act-mandated municipal tenders sustain premium pricing for certified transparency documentation. Security integrators exhibit lowest price sensitivity; content creators driving compact wireless unit sales show highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from automotive Tier 1 suppliers and municipal procurement frameworks in China and Germany mandate multi-supplier qualification for sensor fusion chipsets and lens modules. Taiwan, South Korea, and Japan anchor advanced CMOS fabrication and optical component supply. Raw material dependencies span rare-earth dopants for lens coatings, high-purity silicon wafers, and specialized epoxy compounds for sensor packaging. Single-source vulnerability concentrates in Taiwan Semiconductor's leading-edge node capacity for backside-illuminated chips. Distribution runs through systems integrator networks in North American healthcare and European public safety verticals, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Panoramic Camera Market functions as a stable compounder anchored by smart city infrastructure mandates that institutionalize recurring procurement cycles across municipal transportation and public safety verticals.
For Market Incumbents: Cement sensor supply chain control through backward integration into backside-illuminated CMOS fabrication or exclusive foundry partnerships with Yangtze River Delta clusters. Lock in systems integrator channel dominance via pre-certified EU AI Act transparency documentation that accelerates French and German municipal tender qualification. Prioritize edge AI chipset partnerships with Qualcomm and Ambarella to defend against software-defined camera platforms threatening hardware refresh cycles. For New Entrants and Emerging Players: Systems integrators in India's PLI-attracted electronics manufacturing corridor represent the most penetrable channel partner type for component localization plays targeting Maharashtra and Karnataka municipal surveillance tenders. White-space opportunities concentrate in GDPR-compliant biometric frameworks for European public squares and immersive telepresence deployments for German-Japanese corporate hybrid work policies. Pursue white-label sensor fusion module supply to automotive Tier 1 suppliers adopting standardized camera heads with swappable compute backends. For Investors and Strategic Acquirers: Roll-up economics work for regional security integrators because fragmented compliance architectures across GDPR, China's MIIT certification, and FCC spectrum governance force redundant cloud infrastructure investments that favor consolidated full-stack providers. Five-to-ten year viability hinges on algorithmic transparency certification assets and edge analytics IP portfolios. Acquisition targets should demonstrate pre-certified EU AI Act documentation and established relationships with Shenzhen or Los Angeles post-house ecosystems. Watch Deutsche Telekom and NTT Docomo 5G-Advanced multicast trial outcomes as inflection indicators for live immersive broadcast adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chipset Partnership | Qualcomm and Ambarella collaborations enable real-time threat detection without cloud dependency for municipal surveillance. |
| EU AI Act Pre-Certification | Algorithmic transparency documentation accelerates deployment authorization across French and German public sector tenders. |
| India PLI Localization Investment | Component manufacturing in Maharashtra and Karnataka reduces landed costs for smart city procurement cycles. |
| 5G-Advanced Multicast Integration | Deutsche Telekom and NTT Docomo trials enable live 360-degree sports and entertainment content delivery. |
| Systems Integrator Channel Consolidation | Full-stack bundling of hardware, cloud storage, and managed analytics captures margin in Texas healthcare campuses. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with security fleet deployment managers, film production equipment rental houses, municipal procurement officers in Shenzhen and Berlin, automotive Tier 1 supplier engineers, and computational photography software architects with secondary validation against SEC filings from semiconductor fabricators, MIIT certification databases, EU AI Act implementation guidance, and smart city infrastructure investment disclosures from Chinese provincial governments. Bottom-up unit shipment modeling and top-down value chain sizing triangulated to produce segment-level outputs.
Segment-weighting approaches distributed value across spherical cameras, multi-lens arrays, integrated sensor-fusion modules, and consumer-grade 360-degree units, with application splits across surveillance, film production, virtual reality, and real estate verticals. Technology dimensions incorporated sensor fusion, wireless connectivity, digital imaging, and edge data processing. CAGRs derived from regression analysis against municipal infrastructure spend, content platform investment cycles, and automotive autonomy level adoption curves, with cross-referencing to CMOS fabrication capacity expansion announcements and FCC spectrum allocation proceedings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical friction affecting Taiwan semiconductor supply, EU AI Act enforcement variance across member states, and 5G-Advanced multicast standardization timelines. Deviation in CMOS fabrication capacity allocation or cross-border data localization mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Automotive 3D Imaging Market
Imaging
Latin America IP Camera Market
Imaging
Live Cell Imaging Market
Imaging
Holotomographic Imaging Market
Imaging
Smartphone with Periscope Lens Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Thermal Camera Market
Imaging
Gel Imaging Documentation Market
Imaging
APAC Thermal Imaging Systems Market
Imaging
Photography Ring Flash Market
Imaging
Global Document Scanner Market
Imaging
Frame Grabber Market
Imaging
Virtual Reality Camera Market
Imaging
Camera Technology Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
CMOS X-Ray Detectors Market