
 Microscopic Camera Market | 2026-2036
Microscopic Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Microscopic Camera Market Analytics
Software-defined image processing is expanding the attach rate of computational microscopy modules to hardware sales. Leica Microsystems leverages its optical heritage to anchor premium positioning in life science workflows. Nikon Corporation sustains R&D intensity across confocal and super-resolution platforms. Hamamatsu Photonics specializes in photon-counting sensors that differentiate its scientific camera portfolio.
A microscopic camera captures magnified visual data from specimens using specialized sensors paired with objective lenses, typically achieving spatial resolutions below the diffraction limit through electron or structured illumination techniques. These instruments serve semiconductor defect analysis, cellular biology, and materials characterization by converting photon or electron signals into digital images for quantitative measurement. Digital microscopes command the largest installed base among product types due to their integration with automated laboratory information systems. Fluorescent technology leads growth in biological research applications where multiplexed protein detection requires spectral unmixing capabilities. Quality control applications in electronics manufacturing concentrate margin pools where throughput and repeatability specifications are most stringent.
FDA clearance requirements for diagnostic imaging devices shape product development timelines for healthcare-facing camera systems, while ISO 10993 biocompatibility standards govern materials used in surgical microscopy environments. REACH compliance in Europe restricts certain optical coatings and sensor substrate materials, forcing reformulation of legacy supply chains. Stakeholders must monitor how AI-enabled image analysis algorithms trigger new regulatory classifications that could reshape competitive access across major economies.
Market Dynamics
Semiconductor wafer inspection is compressing development cycles for high-resolution imaging systems, forcing sensor manufacturers to synchronize roadmaps with foundry process nodes while East Asian manufacturing clusters absorb capacity expansion.
Growth Catalysts
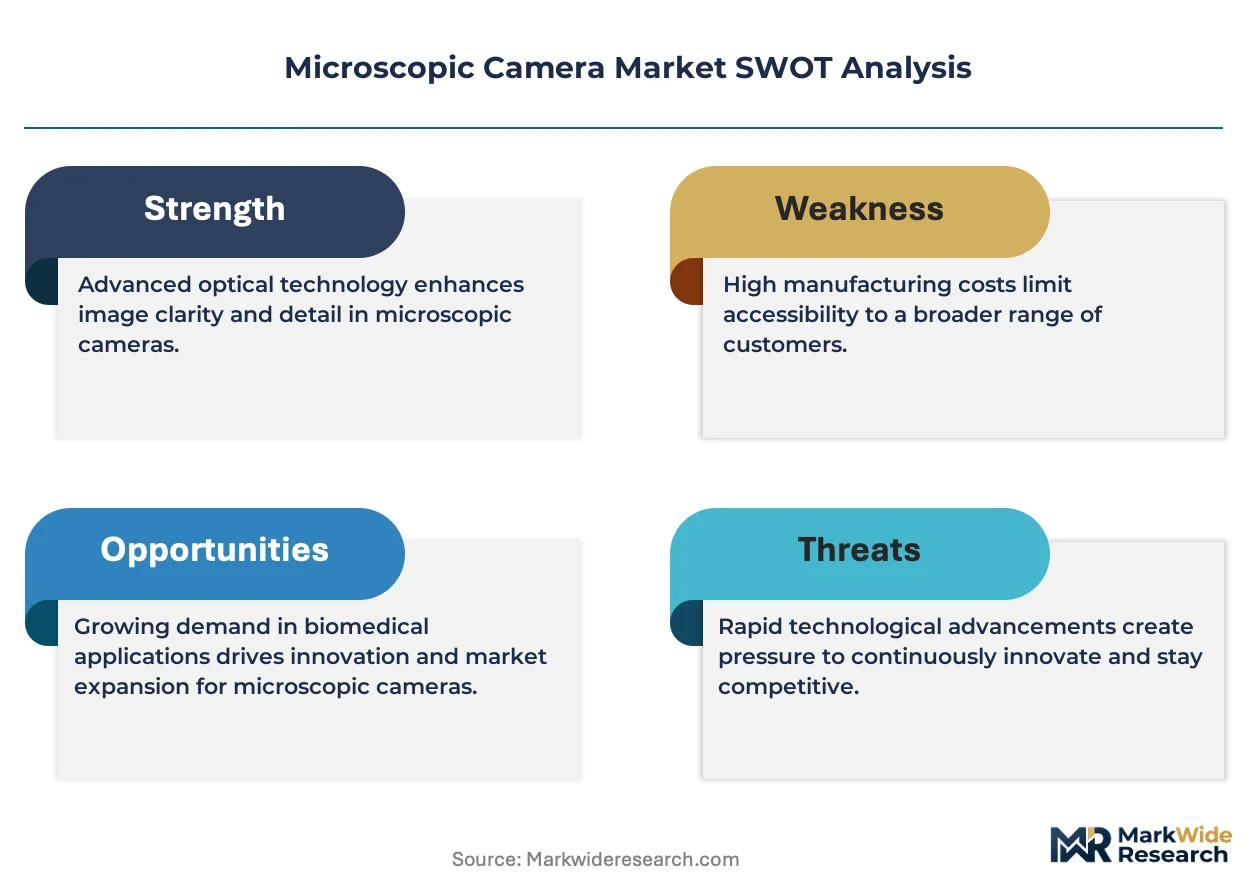
- CMOS sensor fabrication advances:Quantum efficiency improvements in backside-illuminated architectures are expanding addressable applications in low-light biological imaging. Unit cost curves are steepening as 300mm wafer-scale production achieves economies previously reserved for consumer electronics.
- Japan's METI semiconductor revitalization:Domestic production subsidies for advanced imaging equipment are strengthening local supply chains for scientific-grade sensors. Equipment procurement mandates for national research institutions are creating guaranteed demand pools.
- Structured illumination microscopy:Super-resolution techniques are displacing electron microscopy in live-cell applications where specimen viability constraints previously limited observation windows.
Market Restraints
- Specialized glass substrate concentration:German and Japanese suppliers control 85% of low-thermal-expansion optical glass, creating input cost volatility when energy prices fluctuate.
- Cleanroom infrastructure requirements:Sensor assembly demands ISO Class 5 environments that concentrate production in capital-rich manufacturing zones.
- Electron microscopy substitution:Scanning electron systems retain resolution advantages below 10 nanometers for materials characterization applications.
Strategic Opportunities
- India's PLI scheme for electronic components:Manufacturing-linked incentives are attracting camera module assembly investments targeting domestic pharmaceutical quality control demand.
- AI-accelerated image reconstruction:Deep learning denoising algorithms are converging with photon-counting sensors to enable shorter exposure protocols in clinical diagnostics.
- Cloud-native microscopy platforms:Remote specimen review is opening subscription revenue streams in veterinary pathology where specialist geographic distribution is uneven.
Industry Challenges
- Computational optics talent scarcity:The intersection of wave optics physics and machine learning engineering commands premium compensation that mid-tier manufacturers struggle to match.
- FDA 510(k) pathway complexity:Diagnostic camera clearances require predicate device demonstrations that extend development timelines for novel sensor architectures.
- Legacy LIMS integration friction:Automated microscopy systems face protocol translation costs when interfacing with decade-old laboratory information management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microscopic Camera Market |
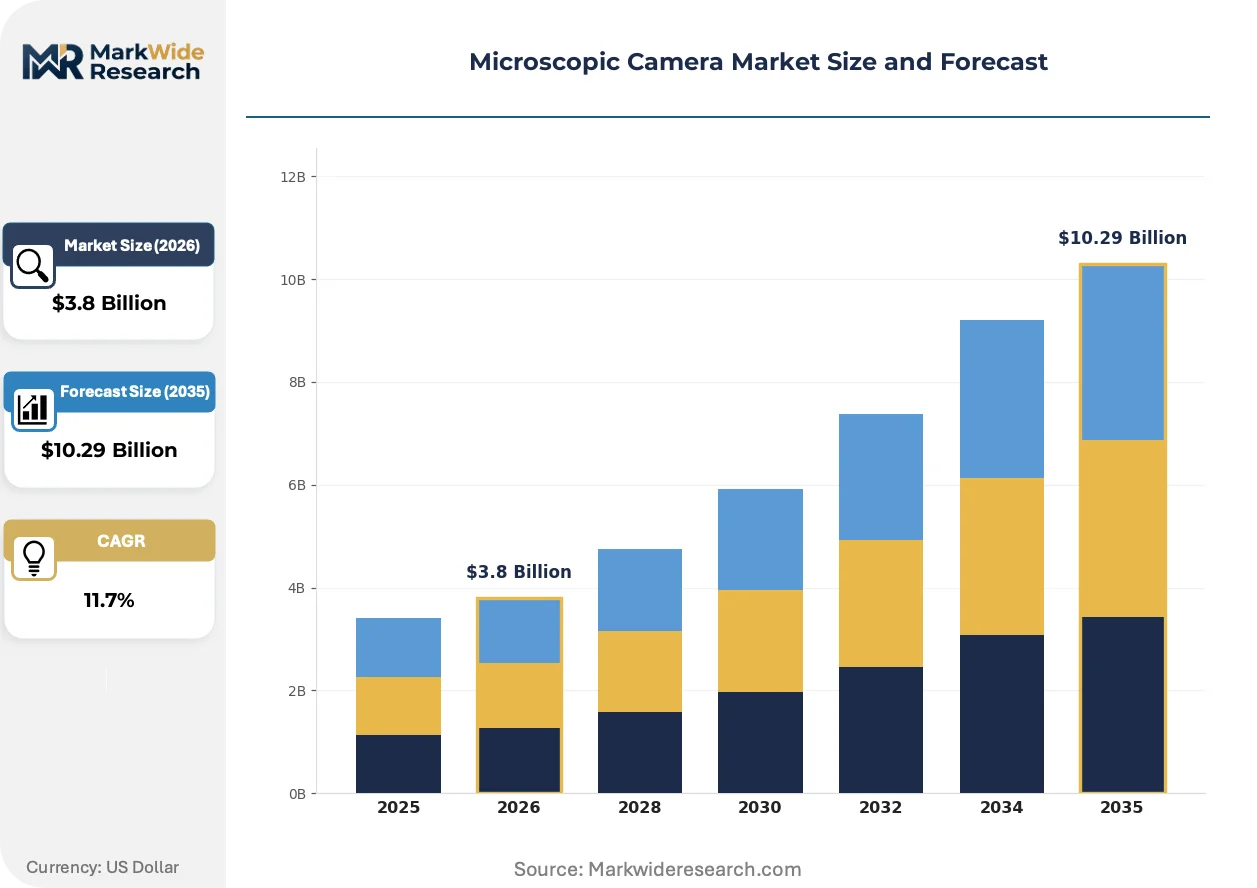
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Microscopes, Digital Microscopes, Webcam Microscopes, Optical Microscopes Technology: Confocal, Fluorescent, Electron, Optical End User: Research Laboratories, Educational Institutions, Healthcare Facilities, Industrial Applications Application: Biological Research, Material Science, Quality Control, Forensics |
| Companies Covered | Leica Microsystems, Nikon Corporation, Carl Zeiss AG, Teledyne Technologies, EVIDENT, Hamamatsu Photonics, Basler AG, Jenoptik AG, Excelitas Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microscopic Camera Market Evolving Landscape
Computational methods are displacing hardware complexity across imaging workflows, compressing the traditional trade-off between optical performance and system cost while redistributing value capture toward software layers.
Deep learning-based autofocus and exposure optimization is automating routine microscopy operations that previously demanded trained operator judgment. Pharmaceutical quality control departments are adopting these modules fastest, driven by batch consistency mandates and 24/7 production schedules. The technology is automating technician labor arbitrage that previously favored low-cost geography sourcing.
REACH restrictions on cadmium and lead in optical coatings are forcing reformulation of legacy sensor packaging materials across European supply chains. Manufacturers are accelerating transitions to indium phosphide alternatives despite refractive index penalties. Medical device camera segments face the steepest compliance cost absorption where biocompatibility certification cycles compound material change validation.
Equipment-as-a-service contracts are displacing capital purchase models in contract research organizations facing uncertain funding cycles. Leica Microsystems and Nikon Corporation have established subscription programs bundling hardware, maintenance, and software updates. North American academic medical centers are adopting these arrangements fastest where endowment investment returns pressure operating budget flexibility.
Microscopic Camera Market Segmentation
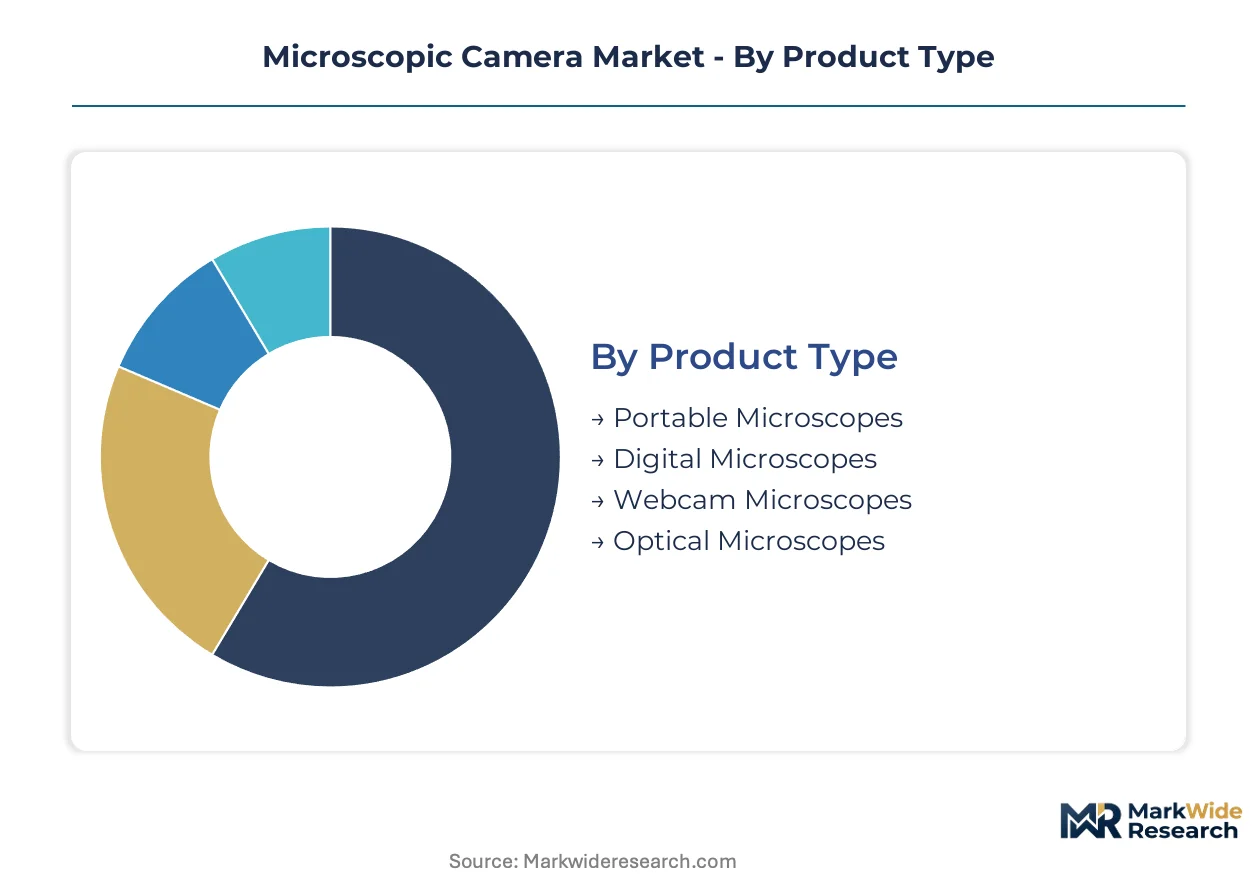
Segmentation in microscopic cameras reveals how technical specifications align with procurement budgets across scientific and industrial workflows. Product architecture, imaging modality, and end-use environment each create distinct competitive arenas with divergent margin structures and replacement cycles.
Product Type:
Volume deployment concentrates in entry-level instruments for education and routine inspection, while premium positioning anchors on research-grade optical performance and software integration depth.
- Digital Microscopes:These systems integrate CMOS or CCD sensors directly with optical paths, enabling real-time display and automated measurement without eyepiece intermediation. Research laboratories in Japan and South Korea are standardizing on these platforms for semiconductor failure analysis, driven by foundry demands for traceable documentation. Mature deployment sits with Digital Microscopes. Newer deployment is concentrated in Webcam Microscopes.
- Portable Microscopes:Battery-powered units with simplified optics serve field applications where laboratory infrastructure is unavailable. Environmental monitoring agencies in Taiwan are procuring these for on-site contamination assessment, constrained by IP65 sealing requirements that add unit cost. These units are gaining share fastest in veterinary and agricultural extension services where mobility overrides resolution specifications.
- Webcam Microscopes:USB-connected devices leverage consumer sensor economics for sub-$500 price points. Remote learning programs in Indian universities are absorbing volume, though thermal drift limits continuous observation protocols.
- Optical Microscopes:Traditional eyepiece-based systems retain installed base in histopathology workflows where pathologist preference resists display-mediated diagnosis.
Procurement patterns bifurcate between capital-intensive research platforms and consumables-adjacent teaching tools.
Technology:
Resolution requirements and specimen preparation constraints determine modality selection, with live-cell applications favoring photon-based methods over vacuum-environment techniques.
- Fluorescent:Excitation-emission filtering enables multiplexed protein detection in cellular biology. Pharmaceutical discovery groups in Cambridge, Massachusetts and Basel, Switzerland are driving attach rates for spectral unmixing software modules. Demand concentrates where CRISPR validation requires co-localization imaging. Mature deployment sits with Optical. Newer deployment is concentrated in Confocal.
- Confocal:Pinhole apertures eliminate out-of-focus light for optical sectioning in thick specimens. Neuroscience departments at Max Planck Institutes are upgrading to resonant-scanning variants for calcium imaging throughput, limited by photobleaching rates in extended time-lapse studies.
- Electron:Beam-based imaging achieves sub-nanometer resolution for materials crystallography. Battery materials startups in Shenzhen are contracting electron microscopy services rather than owning capacity, due to seven-figure capital requirements and specialist operator scarcity.
- Optical:Brightfield and phase contrast techniques dominate histology quality control where staining protocols are standardized and throughput priorities exceed resolution demands.
Margin concentration follows specimen preparation complexity, with live-cell modalities commanding premium pricing against fixed-sample alternatives.
End User:
Funding stability and procurement sophistication vary sharply across institutional categories, shaping payment terms and service contract attach rates.
- Research Laboratories:Academic and government facilities prioritize optical modularity and software openness for custom workflow integration. National institutes in Tsukuba, Japan are consolidating vendor relationships under framework agreements, pressuring mid-tier suppliers on service response times. Mature deployment sits with Research Laboratories. Newer deployment is concentrated in Healthcare Facilities.
- Healthcare Facilities:Diagnostic pathology and surgical microscopy applications demand FDA or PMDA clearance, extending product development timelines. Hospital networks in Texas and Bavaria are leasing rather than purchasing high-end confocal systems to manage capital allocation flexibility.
- Educational Institutions:Secondary and undergraduate programs prioritize durability and theft resistance over optical performance. State procurement boards in Maharashtra, India are specifying minimum five-year warranty terms that filter out import-dependent suppliers.
- Industrial Applications:Electronics manufacturing quality control mandates throughput metrics and Gage R&R repeatability documentation. Contract manufacturers in Dongguan, China are integrating camera outputs directly with MES systems for real-time defect routing.
Customer concentration is steepest in industrial procurement where single OEM accounts represent annual volume commitments.
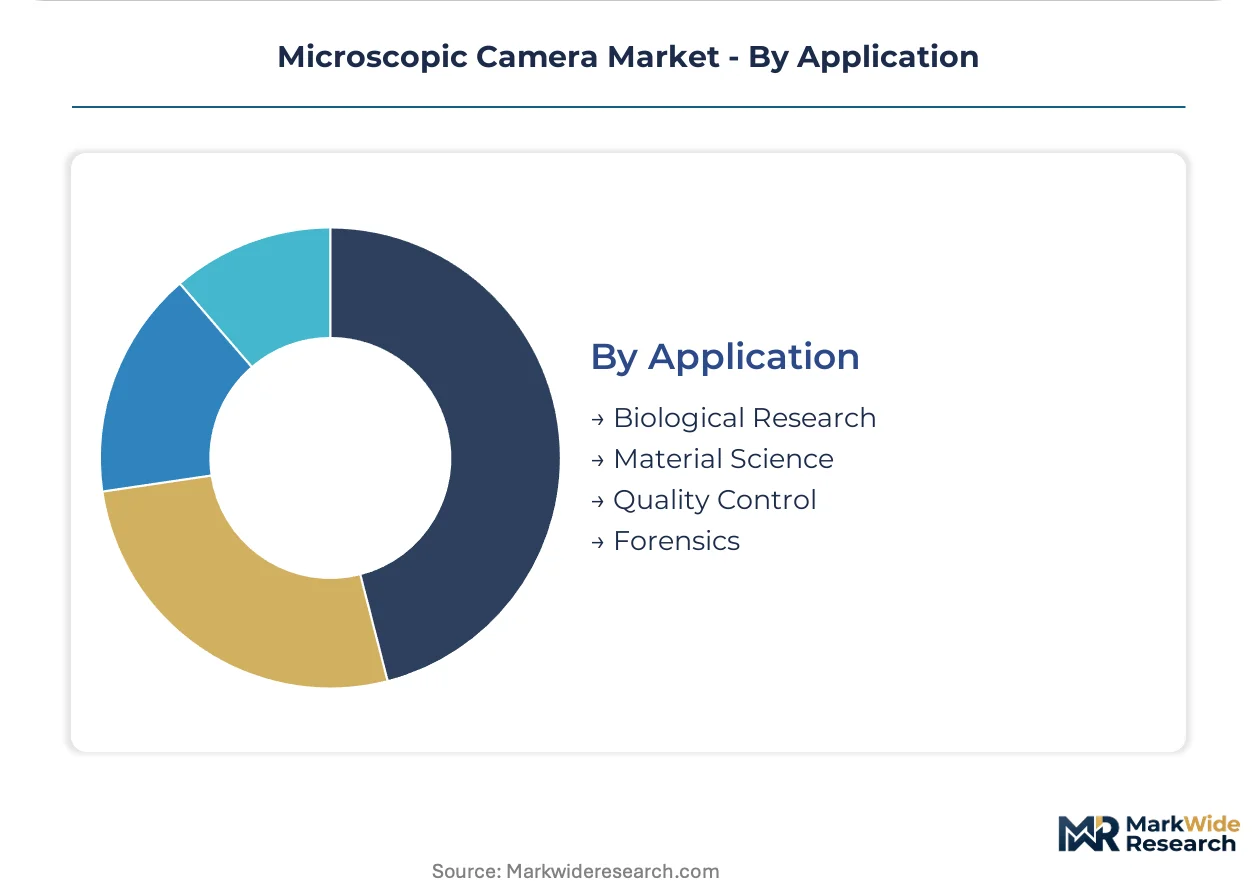
Application:
Scientific output requirements versus regulatory compliance burdens create divergent specification priorities across use cases.
- Biological Research:Live-cell imaging and super-resolution techniques drive sensor sensitivity requirements. Structural biology consortia in Heidelberg, Germany are standardizing on sCMOS backside-illuminated sensors for single-molecule localization microscopy, constrained by data storage infrastructure for terabyte-scale acquisition files. Mature deployment sits with Biological Research. Newer deployment is concentrated in Quality Control.
- Quality Control:Semiconductor wafer and pharmaceutical batch inspection demand measurement repeatability and audit trails. Foundries in Hsinchu, Taiwan are specifying camera systems with embedded edge detection algorithms to reduce host computer processing load.
- Material Science:Fractography and grain structure analysis require polarization and differential interference contrast capabilities. Aerospace suppliers in Toulouse, France are upgrading from film-based documentation to digital systems for AS9100 compliance traceability.
- Forensics:Trace evidence and questioned document examination prioritize chain-of-custody documentation and courtroom presentation clarity. State crime laboratories in California are consolidating on integrated camera-microscope systems with embedded GPS timestamping.
Specification intensity is highest where measurement uncertainty directly affects regulatory submission or liability exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian sensor foundries while consumption spreads across pharmaceutical hubs and semiconductor clusters in North America and Europe. Japan and South Korea dominate CMOS fabrication for scientific imaging. Germany and the United States anchor demand for research-grade microscopy systems.
Japan
Domestic foundry investments and METI semiconductor subsidies are expanding scientific sensor capacity. PMDA clearance requirements shape diagnostic camera development timelines for healthcare applications. Tsukuba's research corridor hosts concentrated demand from national institutes consolidating under framework procurement agreements.
South Korea
Memory and logic foundry investments are pulling advanced inspection equipment into Samsung and SK Hynix supply chains. MFDS regulates medical device cameras for diagnostic pathology applications. Seoul's Pangyo cluster anchors startup activity in AI-accelerated image reconstruction for semiconductor defect analysis.
Germany
Automotive battery materials research and pharmaceutical quality control are driving confocal and super-resolution adoption. REACH restrictions on optical coatings are forcing material reformulations across European supply chains. Baden-Württemberg's precision optics corridor around Oberkochen maintains concentration in high-end objective lens manufacturing.
United States
FDA 510(k) pathways for diagnostic devices extend development timelines for novel sensor architectures. NIH funding stability supports academic laboratory procurement of research-grade platforms. Cambridge, Massachusetts and San Diego anchor pharmaceutical discovery demand for multiplexed fluorescence imaging systems.
India
PLI scheme incentives for electronic components are attracting camera module assembly investments. CDSCO regulates medical device imports while domestic manufacturing scales for pharmaceutical quality control. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune is absorbing volume for batch inspection automation.
Microscopic Camera Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the microscopic camera value chain. Sensor foundries in East Asia absorb the bulk of fabrication investment while European and Japanese specialists concentrate on optical system integration. The market structures around three archetypes: integrated optical heritage houses, precision sensor specialists, and industrial camera module suppliers. Consolidation moves through vertical integration into sensor fabrication and strategic partnerships for AI software stacks.
Among German optical heritage houses, Leica Microsystems and Carl Zeiss AG exemplify premium-tier positioning anchored in century-long microscope manufacturing traditions. Nikon Corporation represents the Japanese integrated model spanning optical design, sensor coordination, and life science workflow software. These three occupy positions where brand reputation in scientific publishing and clinical validation creates defensive moats against modular competitors.
| Leading Market Players |
|---|
| Leica Microsystems |
| Nikon Corporation |
| Carl Zeiss AG |
| Teledyne Technologies |
| EVIDENT |
| Hamamatsu Photonics |
| Basler AG |
| Jenoptik AG |
| Excelitas Technologies |
| Others |
Value Network & Pricing Analysis
East Asian foundry procurement departments concentrate purchasing power for CMOS sensors, locking in contract-based long-term offtake agreements that compress margin pools for modular camera assemblers outside the region.
Pricing Analysis
Margin tightening in research-grade systems reflects CMOS sensor cost-down curves from 300mm wafer-scale production. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic tiers from educational instruments. Price differentiation traces to certification grade and volume scale. Healthcare facilities show lowest price sensitivity due to reimbursement pass-through mechanisms, while Indian educational procurement boards enforce aggressive cost compression.
Supply Chain Analysis
Dual-sourcing mandates from Japanese and South Korean OEMs now require qualified secondary suppliers for backside-illuminated sensors. Production draws from Japan, South Korea, and Taiwan. Critical inputs include low-thermal-expansion optical glass, indium phosphide substrates, and photon-counting sensor arrays. Single-source vulnerability concentrates in German and Japanese optical glass suppliers controlling specialty substrate supply. Distribution runs through direct OEM relationships and national research institution framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as computational optics talent scarcity forces mid-tier manufacturers into strategic exits or acquisition.
For Market Incumbents: Deepen backward integration into CMOS sensor fabrication to secure supply allocation during foundry capacity crunches. Lock in exclusive photon-counting sensor partnerships with Hamamatsu Photonics to defend against modular competitors. Prioritize FDA 510(k) pathway investments to extend regulatory moats. For New Entrants and Emerging Players: Begin with India's PLI scheme for electronic components to capture pharmaceutical quality control demand in Maharashtra's manufacturing belt. Target veterinary pathology cloud-native platforms where specialist geographic distribution creates subscription revenue white space. Lead with AI-accelerated image reconstruction as differentiation. For Investors and Strategic Acquirers: The window for entry favors precision sensor specialists with captive photon-counting technology and established PMDA relationships. Long-term viability hinges on software attach rates outpacing hardware commoditization. Watch for FDA reclassification of AI-enabled diagnostic algorithms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fabrication Backward Integration | Captive CMOS supply secures allocation priority at TSMC and Samsung foundries. |
| AI-Enabled Diagnostic Clearance | FDA 510(k) submissions for deep learning reconstruction open reimbursement pathways. |
| Cloud-Native Microscopy Platform | Subscription models penetrate veterinary pathology uneven specialist distribution. |
| Optical Glass Supplier Partnership | Long-term offtake with Schott AG mitigates REACH reformulation cost volatility. |
| Computational Optics Talent Acquisition | Machine learning engineering hires accelerate photon-counting algorithm development. |
Research Methodology
Multi-period observation of CMOS sensor roadmaps, foundry capacity announcements, and PMDA clearance timelines anchored the trend analysis, supplemented by interviews with biomedical engineers at academic medical centers, GPO contracts managers at hospital networks, procurement leads at semiconductor foundries, and optical system integration specialists. Secondary validation drew from FDA 510(k) filings, METI subsidy disclosures, CDSCO medical device registrations, and SEC filings of listed precision optics manufacturers. Bottom-up segment sizing triangulated against top-down semiconductor equipment spending forecasts.
Input-output matrix modeling connected sensor unit economics to system-level pricing across product architecture, imaging modality, and end-use environment dimensions. CAGRs derived from regression analysis of historical replacement cycles and projected adoption curves for super-resolution techniques. Industry-specific forecast inputs included foundry process node transitions and AI algorithm regulatory classification timelines.
Underlying measurement precision varies by segment; semiconductor wafer inspection and healthcare facility applications carry tighter precision than educational institution procurement. Forecasts reflect documented assumptions on CMOS cost curves and regulatory clearance velocity. Deviation in FDA AI-enabled device reclassification or METI subsidy renewal would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Camera with Flip Screen Market
Imaging
Vision Processing Unit Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
AI Camera Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Global Microscopy Market
Imaging
Thermal Imaging Camera Market
Imaging
Short-Wave Infrared Imaging Market
Imaging
Global Cell Imagers Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Photography Equipment Market
Imaging
Smart Camera Market
Imaging
APAC Image Sensors Market
Imaging
Cooled IR Camera Market
Imaging
Document Imaging Market
Imaging
X-Ray Systems Market