
 Asia Pacific IP Camera Market | 2026-2036
Asia Pacific IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific IP Camera Market Insights
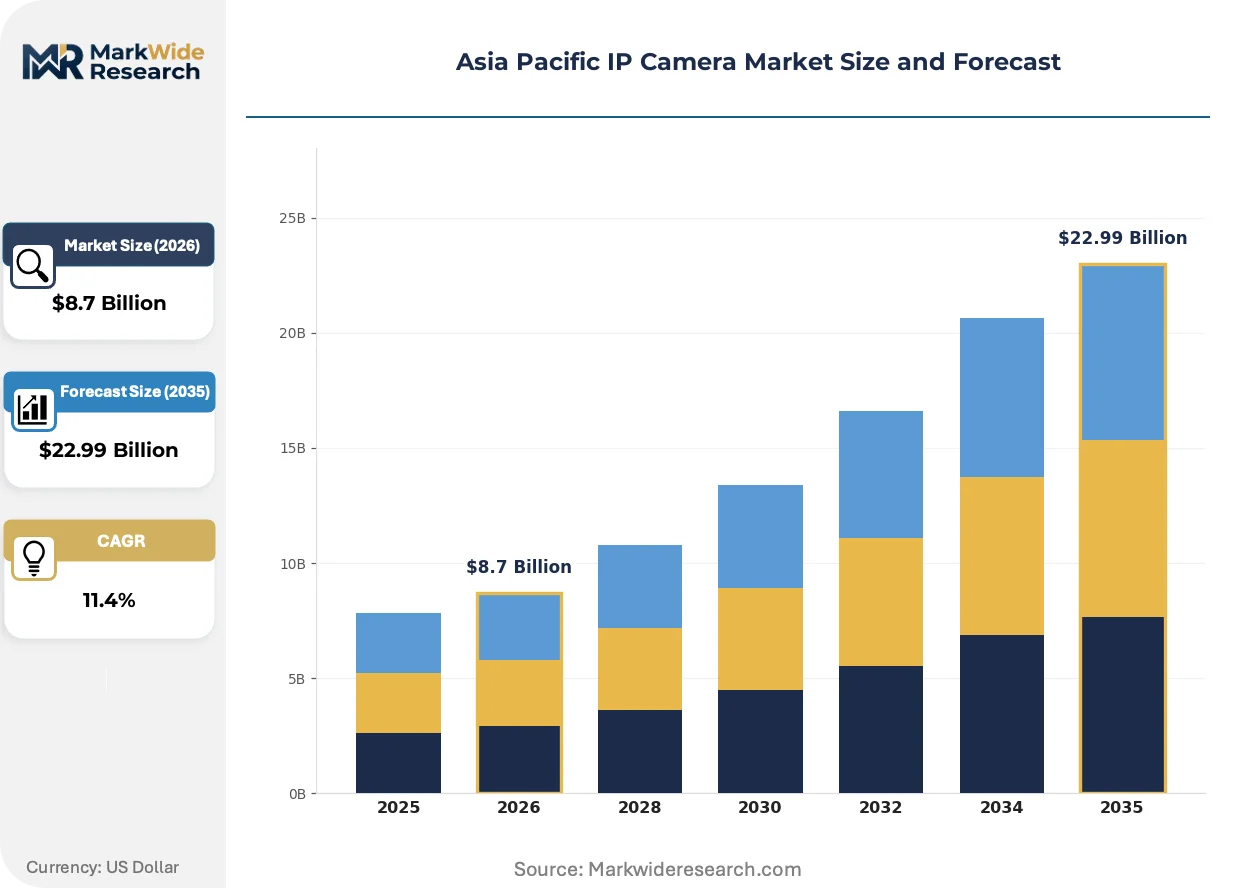
Subscription-based video-surveillance-as-a-service financing is reconfiguring capital deployment across the Asia Pacific IP Camera Market, allowing mid-sized system integrators to bypass heavy upfront hardware investments. Hangzhou Hikvision Digital Technology Co., Ltd leverages its captive chip foundry partnerships to sustain margin control across dome and bullet camera lines. Dahua Technology Co., Ltd anchors its position through deep vertical integration into image sensor assembly. Samsung Electronics Co., Ltd competes on wireless chipset interoperability with South Korean telecom infrastructure standards.
An IP camera is a networked digital video device that captures and transmits footage over Internet Protocol networks, typically encoding streams via H.265 or H.264 compression at resolutions from 2MP to 8MP for centralized monitoring and analytics. Its primary commercial purpose spans security surveillance, traffic management, and operational oversight across retail, transportation, and institutional facilities. Dome cameras lead indoor installations across Asian retail chains where discreet ceiling-mounted positioning reduces tamper risk. Cloud-based technology segments are expanding fastest as Indian and Vietnamese end users shift from on-premise NVR storage to hybrid architectures. Wired technology still dominates transportation sector tenders where latency tolerance near zero is non-negotiable.
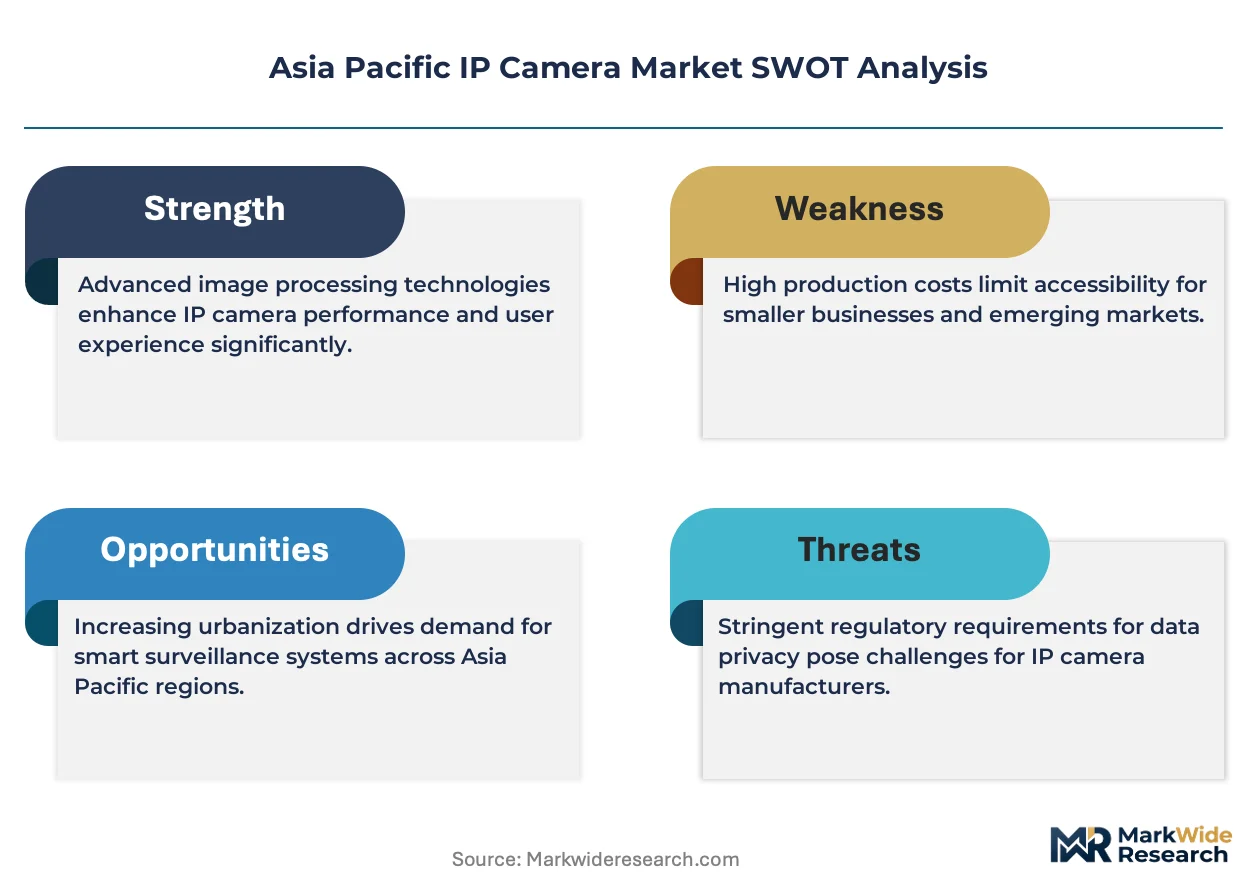
China's MIIT enforces GB/T 28181 protocol compliance for all networked video devices deployed in public security projects, effectively filtering non-certified imports from government procurement channels. India's BIS certification mandate for electronic safety equipment and TRAI's data localization guidance for cloud-stored surveillance footage are raising compliance barriers for foreign manufacturers. South Korea's MFDS-aligned cybersecurity standards for connected devices add another certification layer for vendors targeting institutional buyers. Stakeholders must monitor which regulatory framework their target country adopts as the dominant compliance benchmark before committing manufacturing or partnership resources.
Market Dynamics
China's GB/T 28181 protocol mandate and India's BIS certification requirements are restructuring competitive access across the Asia Pacific IP Camera Market, filtering non-compliant imports from government procurement channels while elevating domestic manufacturers with captive certification capabilities.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian municipal governments in Vietnam, Indonesia, and Thailand are embedding networked surveillance into urban planning frameworks, creating sustained demand for IP camera deployments in traffic management and public safety systems.
- TRAI data localization guidance:India's cloud-stored surveillance footage requirements are accelerating hybrid architecture adoption, pushing end users toward domestic data center partnerships and compliant hardware vendors.
- H.265 compression adoption:Bandwidth efficiency gains from advanced encoding standards are enabling 4K and 8MP stream transmission over existing network infrastructure, reducing upgrade costs for institutional buyers.
Market Restraints
- Image sensor supply concentration:Foundry capacity constraints in Taiwan and South Korea are creating input volatility for camera module assembly, compressing margins for non-vertically integrated assemblers.
- Cybersecurity certification layering:South Korea's MFDS-aligned standards and China's MIIT security reviews are extending product approval timelines by 6-12 months for foreign entrants.
- Legacy analog substitution ceiling:Price-sensitive small retailers in rural India and Indonesia continue deploying coaxial-based systems, slowing IP camera penetration in the long-tail commercial segment.
Strategic Opportunities
- Vietnamese manufacturing zones:Industrial park surveillance upgrades in Bac Ninh and Hai Phong are creating demand for explosion-proof and thermal imaging IP cameras in hazardous environment applications.
- Video-analytics-as-a-service convergence:Edge AI chip integration with cloud-based analytics platforms is opening recurring revenue streams for system integrators serving retail loss-prevention and warehouse safety verticals.
- India's Safe City Mission expansion:Tier-two municipal police modernization budgets in Lucknow, Jaipur, and Kochi are unlocking procurement channels previously concentrated in Delhi, Mumbai, and Bangalore.
Industry Challenges
- Multi-protocol integration complexity:System integrators face mounting technical debt reconciling ONVIF, GB/T 28181, and proprietary vendor protocols within unified command center deployments.
- Edge AI firmware talent scarcity:Shortage of embedded systems engineers capable of optimizing neural network inference on camera SoCs is delaying product development cycles for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific IP Camera Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, Bullet, PTZ, Box Technology: Wired, Wireless, Cloud-Based, Hybrid End User: Retail, Residential, Transportation, Education Installation Type: Indoor, Outdoor, On-wall, Ceiling-Mounted |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd, Dahua Technology Co., Ltd, Bosch Security Systems GmbH, Honeywell International, Inc., Panasonic Corporation, Samsung Electronics Co., Ltd, D-Link Corporation, Sony Corporation, Hanwha Vision Co., Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific IP Camera Market Trends and Innovations
Edge computing architectures and AI-enabled video analytics are compressing the value chain between capture and insight, eliminating latency-dependent centralized processing while creating new competitive battlegrounds in on-camera inference capability.
Multi-sensor fusion cameras integrating visible-light, thermal, and radar sensing into single housings are rendering obsolete single-modality devices in perimeter security applications. Airport authorities and critical infrastructure operators across Singapore, Australia, and Japan are specifying these units for 24-hour coverage requirements. The technology is rendering obsolete the traditional practice of deploying parallel camera networks for day and night operations.
India's BIS certification mandate for electronic safety equipment, effective across all imported and domestically manufactured surveillance hardware, is forcing component traceability documentation through three-tier supply chains. Foreign manufacturers are responding by establishing local testing partnerships and pre-certification staging facilities in Chennai and Pune. The regulation most impacts mid-range dome and bullet camera categories where price competition previously dominated procurement criteria.
Municipal police departments and transportation authorities are consolidating vendor relationships around full-stack service contracts encompassing hardware, connectivity, cloud storage, and analytics software. System integrators in Australia and South Korea are displacing pure equipment resellers by absorbing operational risk through uptime guarantees. This consolidation is most visible in Australian state-level road authority tenders where single-vendor accountability is replacing multi-supplier fragmentation.
Asia Pacific IP Camera Market Segmentation
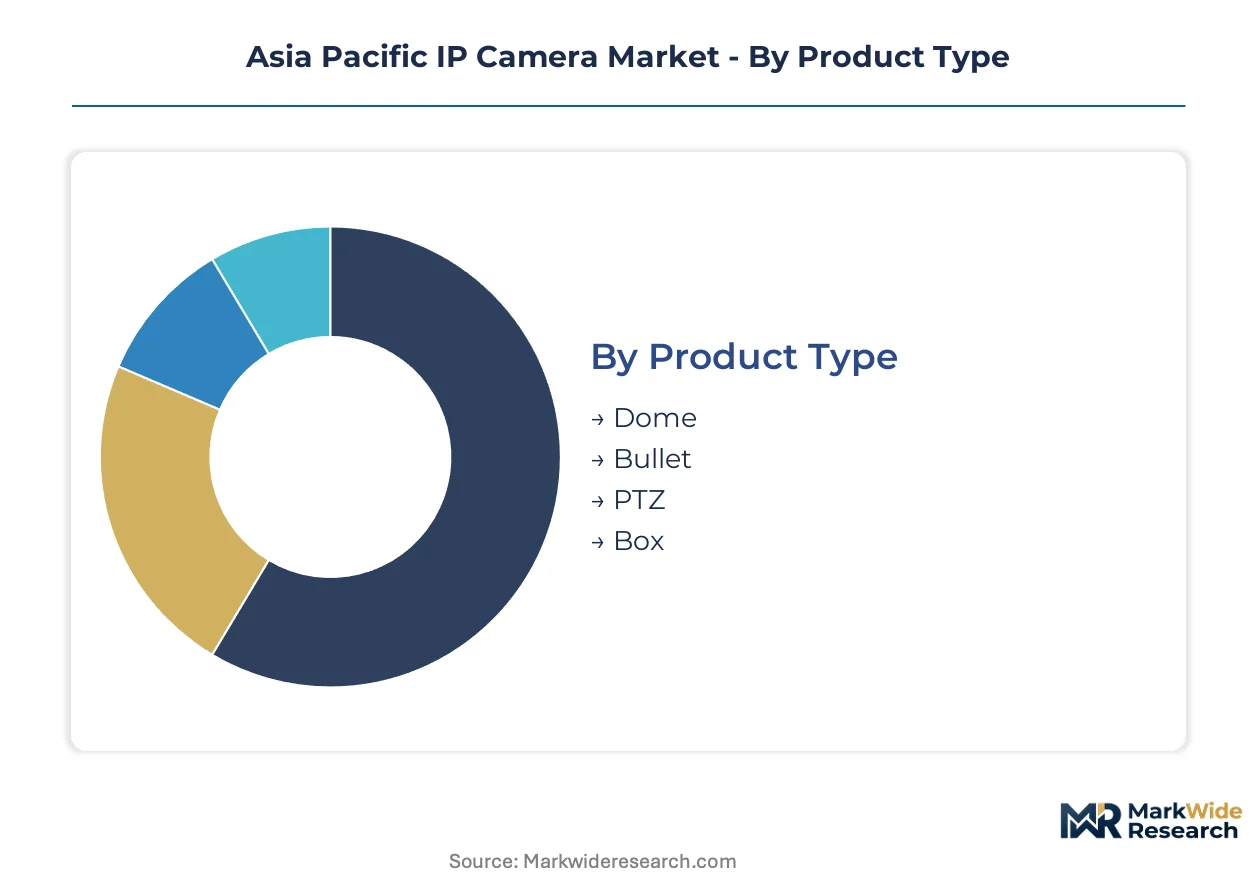
Product architecture, connectivity protocols, and mounting configurations shape procurement patterns across Asia Pacific surveillance deployments. End-user verticals impose distinct performance requirements that filter through to component selection and system integration decisions.
Product Type:
Cost tier differentiation separates indoor discrete positioning from outdoor ruggedized housings and motorized tracking systems.
- Dome:Hemispherical enclosures with vandal-resistant polycarbonate housings and 360-degree coverage capability. Asian retail chains in Singapore and Bangkok specify these for ceiling-mounted loss-prevention networks where tamper resistance outweighs range requirements. Discreet positioning reduces customer perception of surveillance intensity while maintaining coverage density.
- Bullet:Cylindrical weather-sealed housings with integrated IR illuminators and fixed focal lenses. Highway authorities across Vietnam and Indonesia deploy these for license plate recognition corridors where directional positioning and long-range night vision are mandatory. Exposed mounting simplifies maintenance access for roadside infrastructure teams.
- PTZ:Motorized pan-tilt-zoom mechanisms with preset patrol patterns and operator-controlled tracking.
- Box:Modular camera bodies accepting interchangeable C/CS-mount lenses for specialized optics.
Dome holds installed capacity. PTZ is rotating up the share rankings.
Technology:
Application latency tolerance and infrastructure legacy determine connectivity architecture selection across deployment scenarios.
- Cloud-Based:Direct-to-cloud streaming architectures bypassing on-premise recording hardware through edge gateway compression. Indian municipal police in Lucknow and Kochi are migrating toward these configurations under TRAI data localization guidance mandating domestic data center partnerships. Bandwidth efficiency from H.265 encoding enables 4K transmission over existing fiber backbones.
- Hybrid:Local edge storage with cloud tiering for forensic retention and centralized analytics. Australian transportation authorities favor this architecture for tollway monitoring where sub-second local retrieval coexists with centralized traffic pattern analysis. Dual-redundancy addresses liability concerns for incident evidence preservation.
- Wired:Ethernet or coax-over-IP transmission with Power-over-Ethernet supply.
- Wireless:Wi-Fi 6 or cellular LTE/5G backhaul for retrofit deployments lacking structured cabling.
Wired maintains volume concentration in transportation tenders. Cloud-Based is climbing the fastest as Indian and Vietnamese end users abandon on-premise NVR dependencies.
End User:
Customer type procurement maturity spans from price-sensitive residential installers to specification-driven institutional tenders.
- Transportation:Mission-critical deployments requiring zero-latency failover and environmental sealing against vibration, temperature extremes, and electromagnetic interference. Metro rail operators in Seoul and Sydney specify EN50155-compliant units with redundant power inputs. Procurement runs through multi-year framework agreements with uptime penalty clauses.
- Retail:Multi-site rollouts prioritizing discrete aesthetics, POS integration, and cloud-managed fleet visibility. Southeast Asian mall operators in Jakarta and Manila standardize on dome configurations with edge analytics for occupancy counting and queue management. Loss-prevention teams demand mobile app accessibility for regional security managers.
- Residential:Consumer-grade Wi-Fi cameras with app-based configuration and subscription cloud storage.
- Education:Campus-wide coverage with centralized command center integration and emergency lockdown system interfacing.
Transportation anchors premium pricing. Retail is gaining share fastest through subscription financing penetration.
Installation Type:
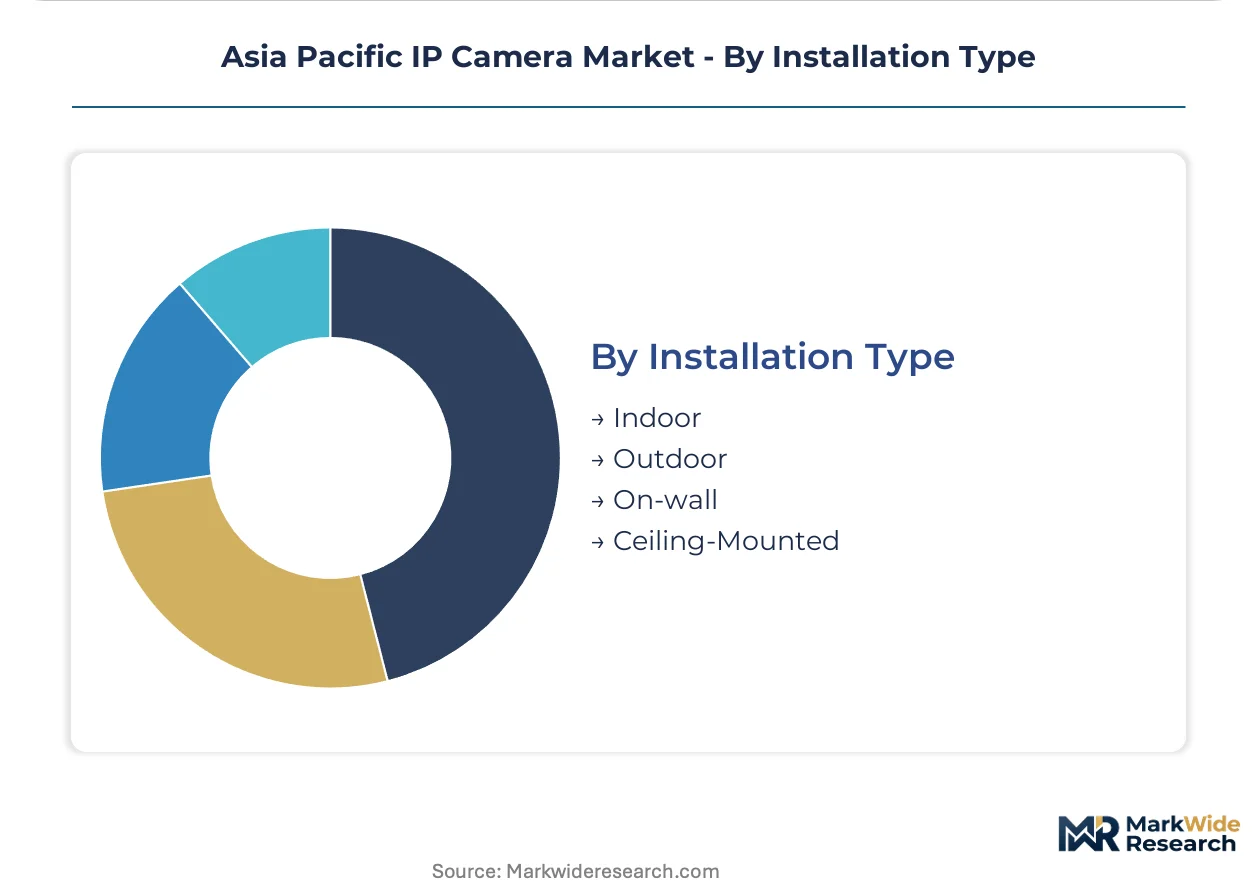
Volume deployment patterns concentrate in ceiling-mounted indoor positioning, with outdoor expansion driven by smart city infrastructure mandates.
- Ceiling-Mounted:Recessed or surface-mounted positioning optimized for wide-angle coverage and gravity-assisted cable management. Indian retail chains and Australian office complexes specify these for lobby and corridor monitoring where field-of-view maximization reduces camera count per floor plate. Installation labor efficiency favors standardized drop-ceiling bracket systems.
- Outdoor:IP66/IP67-rated housings with integrated heater/blower modules and sunshield shrouds. Vietnamese industrial park operators in Bac Ninh and Hai Phong deploy explosion-proof variants for petrochemical perimeter monitoring. Corrosion-resistant coatings address coastal humidity degradation in Singapore and Manila port facilities.
- Indoor:Climate-controlled environment positioning without weather sealing requirements.
- On-wall:Vertical surface mounting with articulated arm brackets for corner coverage optimization.
Ceiling-Mounted dominates indoor specification. Outdoor is expanding most quickly through Southeast Asian smart city procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for image sensors and SoC modules shapes trade flows across Asia Pacific, with domestic assembly operations in China and Vietnam offsetting reliance on Taiwanese and South Korean foundry output. Export competitiveness hinges on GB/T 28181 and BIS certification alignment.
China
MIIT's GB/T 28181 protocol mandate filters non-certified imports from government procurement, privileging domestic vendors with captive compliance capabilities. Yangtze River Delta manufacturing clusters in Hangzhou and Shenzhen anchor dome and bullet camera assembly operations. Smart city tenders in Chengdu and Xi'an specify edge-AI-enabled units for traffic management corridors.
India
BIS certification requirements and TRAI data localization guidance are restructuring hardware procurement toward domestic testing partnerships. Safe City Mission budgets concentrate in Delhi-NCR, Mumbai, and Bangalore, with tier-two expansion into Lucknow and Jaipur. Chennai and Pune host pre-certification staging facilities established by foreign manufacturers seeking market entry.
South Korea
MFDS-aligned cybersecurity standards extend product approval timelines for connected surveillance devices targeting institutional buyers. Seoul Capital Area metro operators specify EN50155-compliant PTZ units with redundant power inputs under multi-year framework agreements. Busan-Ulsan industrial zones drive demand for explosion-proof thermal imaging in petrochemical perimeter applications.
Vietnam
Industrial park surveillance upgrades in Bac Ninh and Hai Phong create demand for hazardous-environment IP cameras in manufacturing and logistics facilities. Cloud-based architectures gain traction as Vietnamese end users abandon on-premise NVR dependencies. Ho Chi Minh City smart city initiatives embed networked surveillance into urban planning frameworks for traffic and public safety systems.
Australia
State-level road authority tenders favor full-stack service contracts with uptime guarantees, displacing multi-supplier fragmentation in transportation surveillance. New South Wales and Victoria transportation authorities specify hybrid architectures for tollway monitoring requiring sub-second local retrieval. Sydney and Melbourne airport authorities specify multi-sensor fusion cameras for 24-hour perimeter coverage requirements.
Asia Pacific IP Camera Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling image sensor and SoC supply. The vendor base stratifies across three tiers: vertically integrated domestic champions with captive foundry access, multinational electronics conglomerates leveraging wireless chipset interoperability, and mid-sized system integrators financing through subscription-based service models. Competitive moves concentrate on certification pre-positioning in India and Vietnam, plus edge-AI firmware development for on-camera inference capability.
Within the domestic champion archetype, Hangzhou Hikvision Digital Technology Co., Ltd and Dahua Technology Co., Ltd exemplify vertically integrated positioning through upstream control over chip foundry partnerships and image sensor assembly. Samsung Electronics Co., Ltd occupies a position on the wireless interoperability vector, aligning with South Korean telecom infrastructure standards. These three anchors represent distinct competitive postures: captive supply chain control, deep backward integration, and standards-aligned ecosystem positioning.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd |
| Dahua Technology Co., Ltd |
| Bosch Security Systems GmbH |
| Honeywell International, Inc. |
| Panasonic Corporation |
| Samsung Electronics Co., Ltd |
| D-Link Corporation |
| Sony Corporation |
| Hanwha Vision Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Regulatory chokepoint exposure through China's MIIT GB/T 28181 protocol mandate and India's BIS certification requirements determines both pricing tier spreads and supply chain shape across the Asia Pacific IP Camera Market. Foreign manufacturers face extended approval timelines that compress margins on mid-range dome and bullet camera lines while elevating certified domestic vendors to premium positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade alignment with GB/T 28181 and BIS standards, plus volume scale for municipal police framework agreements. Cost compression in the economy tier is intensifying because small retailers in rural India and Indonesia persist with analog coaxial systems. Price sensitivity peaks among residential installers and rural commercial deployers, while transportation authorities and airport operators exhibit minimal elasticity.
Supply Chain Analysis
Export-control regime friction around semiconductor manufacturing equipment limits foundry capacity expansion in Taiwan and South Korea, constraining image sensor and SoC module flows. Component assembly draws from Chinese Yangtze River Delta clusters, Vietnamese Bac Ninh industrial zones, and South Korean Busan-Ulsan corridors. Single-source vulnerability concentrates in Taiwanese foundry output for advanced image sensors. Distribution runs through system integrators absorbing operational risk via full-stack service contracts with uptime guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific IP Camera Market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning. Certification pre-positioning and captive compliance capabilities constitute the primary structural advantage.
For Market Incumbents: Pre-empt margin erosion in mid-range dome and bullet lines by deepening backward integration into image sensor assembly and establishing pre-certification staging facilities in Chennai and Pune before BIS mandates tighten. Counter emerging cloud-native entrants by bundling edge-AI firmware development with hybrid architecture deployment expertise. Certification investment represents the critical defensive lever.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asian manufacturing zones represent the most penetrable entry point, specifically explosion-proof and thermal imaging specifications for Bac Ninh and Hai Phong petrochemical perimeter applications. Tier-two Indian municipal police modernization in Lucknow, Jaipur, and Kochi offers procurement channels less saturated than Delhi-NCR and Mumbai. A subscription-based video-surveillance-as-a-service financing model bypasses capital intensity barriers for mid-sized system integrators.
For Investors and Strategic Acquirers: India's TRAI data localization guidance reshapes the acquisition landscape by privileging domestic data center partnerships and compliant hardware vendors. Long-term viability centers on edge-AI inference capability and multi-protocol integration expertise. Target acquisition archetypes include mid-tier manufacturers with embedded systems engineering talent and established BIS certification workflows. The signal to watch is tier-two Safe City Mission budget allocation announcements.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | MIIT GB/T 28181 and BIS compliance filters non-certified imports from government procurement channels. |
| Edge-AI Firmware Development | Neural network inference optimization on camera SoCs creates recurring analytics revenue streams. |
| Hybrid Architecture Deployment | Local edge storage with cloud tiering addresses TRAI data localization for Indian municipal police. |
| Backward Integration | Upstream control over image sensor assembly insulates margins from Taiwanese foundry volatility. |
| Subscription Service Model | Video-surveillance-as-a-service financing allows mid-sized integrators to bypass hardware capital intensity. |
Research Methodology
Initial hypotheses were tested against primary input from system integration specialists, municipal police procurement officers, semiconductor foundry planning executives, and cloud infrastructure architects, then refined through secondary validation. Primary fieldwork encompassed stakeholder interviews across Hangzhou, Shenzhen, Chennai, and Singapore. Secondary sources included MIIT regulatory filings, BIS certification databases, TRAI guidance documents, and customs trade data for image sensor and SoC module flows. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation dimensions spanned product architecture, connectivity protocol, mounting configuration, and end-user vertical maturity. CAGRs were derived from installed base growth rates, replacement cycle compression, and smart city infrastructure mandate acceleration. Industry-specific inputs included H.265 compression adoption curves, edge-AI chip integration timelines, and municipal police modernization budget trajectories.
Macroeconomic conditions sit as an overlay; deviation in fiber backbone investment cycles, semiconductor foundry utilization rates, or regional currency volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and certification timeline stability. Material shifts in GB/T 28181 protocol revisions or BIS testing capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Middle East and Africa Image Sensors Market
Imaging
Photoacoustic Microscope Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Camera with Flip Screen Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Camera Lens Market
Imaging
Fiducial Markers Market
Imaging
Computer Aided Detection Market
Imaging
Webcam Market
Imaging
Holotomographic Imaging Market
Imaging
US Near Infrared Imaging Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Global Label-Free Array Systems Market
Imaging
Global Image Signal Processor Market
Imaging
Global Document Scanner Market