
 Computational Photography Market | 2026-2036
Computational Photography Market Size, Share, and Industry Trends Forecast 2026-2036
Computational Photography Market Intelligence
The integration of multi-frame processing for super resolution is redrawing the boundaries of image quality achievable in consumer electronics. Apple Inc. leverages its A-series chip architecture to optimize on-device image pipelines. Qualcomm Technologies Inc. competes by embedding advanced spectral ISP capabilities into its Snapdragon platforms. Adobe Inc. specializes in cloud-based processing, offering sophisticated editing tools for content creators.
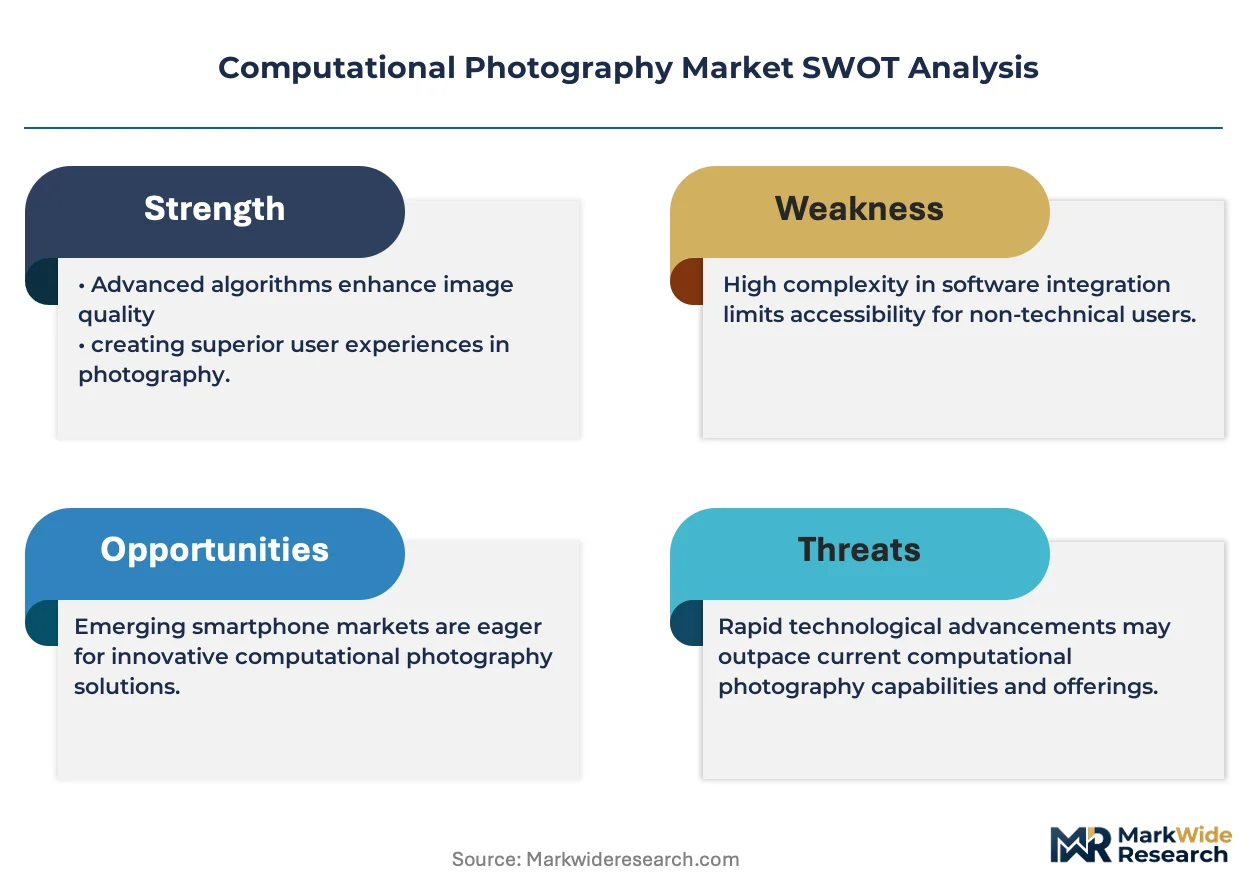
Computational photography uses digital processing algorithms to overcome the physical limitations of traditional camera optics and sensors. It merges data from multiple frames or sensors to enable functionalities like High Dynamic Range (HDR) and synthetic depth of field. While the smartphones segment is the largest application, autonomous vehicles and drones show significant growth. On-device processing leads for real-time uses, with cloud-based processing expanding in professional post-production.
Data privacy regulations like Europe's GDPR and China's Personal Information Protection Law shape how image data is handled by personal devices and security systems. Frameworks such as the EU AI Act will also influence the development of underlying algorithms. The critical decision for developers involves balancing on-device, edge, and cloud processing to meet performance needs and ensure compliance.
Market Dynamics
The market's trajectory is defined by the escalating demand for real-time environmental perception in autonomous systems. This requires a tight integration of advanced sensor fusion, specialized processors, and sophisticated depth-sensing algorithms to ensure functional safety and reliability.
Growth Catalysts
- Multi-Camera Arrays:The proliferation of multi-camera systems in smartphones and vehicles enables advanced functionalities like synthetic zoom and 3D mapping, driving algorithm development and hardware requirements.
- Autonomous Vehicle Safety:Advanced driver-assistance systems and autonomous vehicles rely on computational imaging for object detection and pedestrian recognition, creating significant demand for robust processing pipelines.
- Chinese Manufacturing Ecosystem:China's dominance in smartphone and electric vehicle production creates a concentrated demand center, accelerating the integration of computational photography features to gain a competitive edge.
Market Restraints
- High Silicon Cost:The requirement for specialized image signal processors and neural processing units adds significant cost and power consumption, limiting adoption in entry-level devices.
- Data Throughput Bottlenecks:Processing vast amounts of data from high-resolution, multi-sensor arrays in real-time creates significant data throughput and thermal management challenges for on-device hardware.
- Data Privacy Compliance:Stringent regulations like Europe's GDPR and China's PIPL create complexity in managing and processing image data, particularly for cloud-based services, slowing development cycles.
Strategic Opportunities
- Agricultural Drones:Deploying computational imaging on agricultural drones for crop monitoring, pest detection, and yield analysis represents a significant, underpenetrated application vertical beyond consumer electronics.
- Edge AI Integration:Combining on-device AI processing with computational photography allows for new intelligent features like predictive scene analysis and automated content creation, opening new product categories.
- Medical Imaging Applications:Applying techniques like super-resolution and HDR to medical diagnostics, such as endoscopy and digital pathology, offers a high-value opportunity to enhance image quality and diagnostic accuracy.
Industry Challenges
- Algorithm Specialization Gap:A scarcity of engineers with dual expertise in both optical physics and machine learning creates a significant talent bottleneck, slowing down innovation and product development timelines.
- Lack of Interoperability:The absence of standardized data formats and APIs for multi-sensor fusion complicates integration for system developers, increasing development costs and time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computational Photography Market |
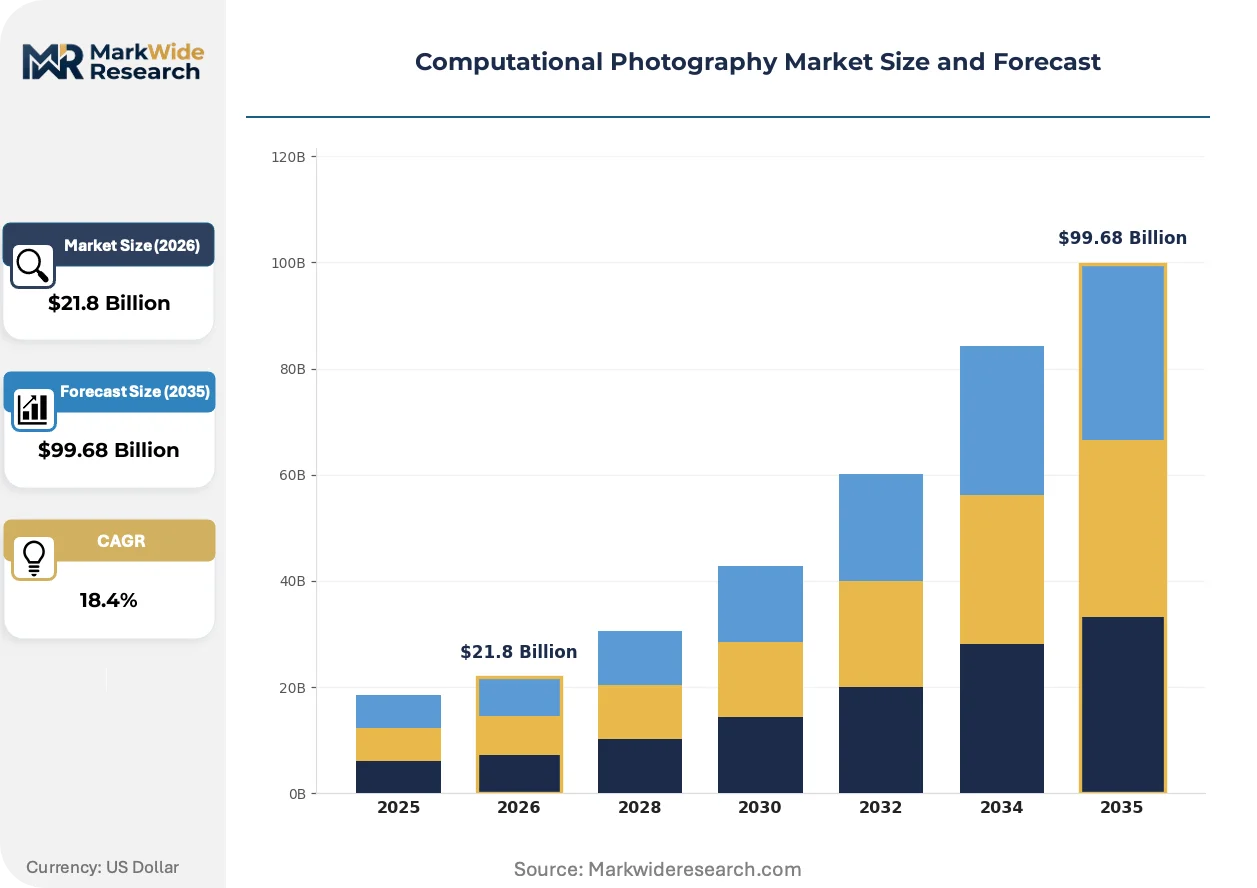
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $99.68 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: HDR Imaging, Light Field, Depth Sensing, Multi-frame Processing, Super Resolution, Low-Light Enhancement Application: Smartphones, Autonomous Vehicles, Drones, Virtual Reality, Security Systems, Wearable Cameras End User: Content Creators, Surveillance Agencies, Automotive Manufacturers, Film Studios, Research Institutions, Advertising Agencies Deployment: On-device Processing, Cloud-based Processing, Hybrid Processing, Edge Computing |
| Companies Covered | Apple Inc., Alphabet Inc., Samsung Electronics Co. Ltd., Qualcomm Technologies Inc., Adobe Inc., Sony Group Corporation, Nvidia Corporation, Canon Inc., CEVA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computational Photography Market Strategic Shifts & Innovations
The evolution of computational photography is marked by a fundamental shift from post-capture software enhancements to real-time, hardware-accelerated sensor fusion. This transition prioritizes on-device intelligence and multi-modal data synthesis over traditional optical performance alone.
Multi-frame processing combines data from a rapid burst of images to improve detail, reduce noise, and expand dynamic range beyond a single sensor's capability. The technique sees rapid adoption in both flagship and mid-range smartphones to achieve super-resolution zoom and enhanced low-light performance. This software-defined approach is fragmenting the traditional market hierarchy based purely on lens and sensor size, allowing smaller devices to compete on image quality.
Forthcoming regulations like the EU AI Act introduce a risk-based framework for artificial intelligence systems, including those used for biometric identification and public surveillance. Its mandates on transparency, data governance, and human oversight directly impact the design of computational photography algorithms used in security and autonomous systems. Developers in the automotive and smart city sectors are most affected, now needing to build explainable AI models and conduct rigorous conformity assessments.
A demand-side shift towards authenticity is emerging, with users in social media and content creation seeking less processed, more natural-looking images. This challenges the prevailing trend of aggressive HDR and color saturation, creating a niche for camera systems that offer more subtle, optically-driven aesthetics. The preference is most visible in the professional and prosumer photography segments, influencing software presets and default camera settings.
Computational Photography Market Segmentation
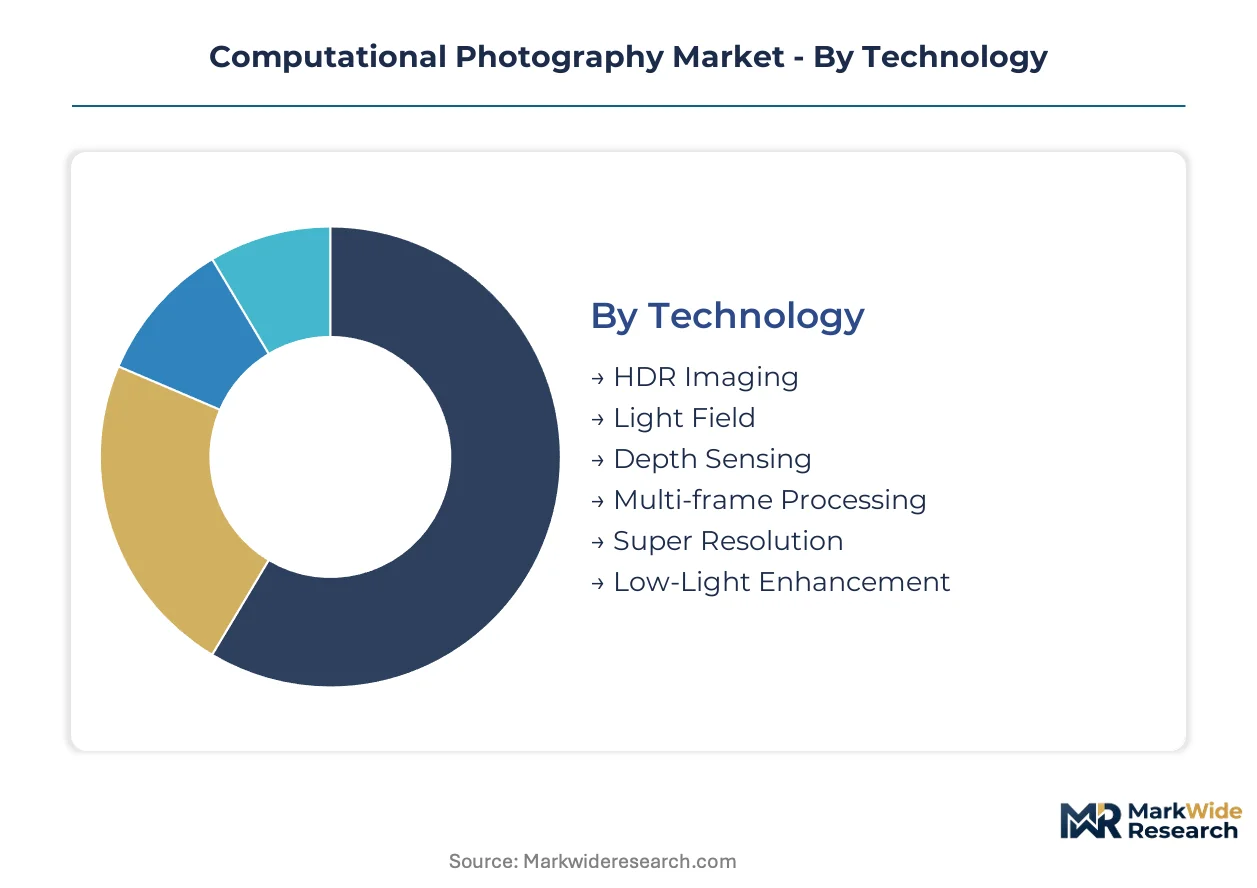
The computational photography market segments illuminate the diverse technological approaches and application landscapes driving innovation and commercial value. Understanding these distinct categories provides clarity on where development efforts concentrate and where market opportunities are most abundant.
Technology:
Margin pools within computational photography technology often sit with proprietary algorithms and specialized hardware integrations.
- Multi-frame Processing:This technique combines data from a rapid sequence of images to enhance detail, reduce noise, and expand dynamic range beyond the capabilities of a single sensor. Smartphones widely adopt multi-frame processing for super-resolution zoom and improved low-light performance.
- Depth Sensing:Depth sensing technologies, including structured light, time-of-flight, and stereo vision, capture precise 3D spatial information about a scene. Autonomous vehicles utilize depth sensing for real-time environmental perception and obstacle avoidance, ensuring functional safety.
- HDR Imaging:High Dynamic Range (HDR) imaging merges multiple exposures to create a single image with a broader range of luminosity, preserving detail in both highlights and shadows.
- Light Field:Light field technology captures directional information of light rays in a scene, enabling post-capture refocusing and synthetic aperture effects.
- Super Resolution:Super resolution algorithms reconstruct higher-resolution images from lower-resolution inputs, often using multi-frame techniques or deep learning models.
- Low-Light Enhancement:These techniques use computational methods to improve image quality in dim conditions by reducing noise and boosting detail, critical for security systems.
The dominant share belongs to Multi-frame Processing, while Depth Sensing is closing the gap fastest.
Application:
Cost tier differentiation significantly influences application segment adoption across the computational photography market.
- Smartphones:Smartphones integrate advanced computational photography features to overcome physical sensor limitations, offering capabilities like enhanced zoom, portrait mode, and improved low-light performance. This segment represents the largest volume market for computational photography due to widespread consumer adoption and rapid innovation cycles.
- Autonomous Vehicles:Autonomous vehicles rely on computational imaging for robust environmental perception, including object detection, lane keeping, and pedestrian recognition, crucial for safety and navigation. This application demands high reliability and real-time processing capabilities for critical decision-making.
- Drones:Drones leverage computational photography for aerial mapping, surveillance, and agricultural monitoring, enhancing image clarity and data collection efficiency.
- Virtual Reality:Virtual reality systems use computational photography to capture and render immersive 3D environments, improving realism and user experience.
- Security Systems:Security systems employ computational photography for facial recognition, anomaly detection, and improved surveillance in challenging lighting conditions.
- Wearable Cameras:Wearable cameras integrate computational photography for hands-free image capture and augmented reality applications, enabling on-the-go content creation.
Smartphones command the largest segment share, with Autonomous Vehicles expanding most quickly.
End User:
Volume consumption patterns dictate the revenue distribution within the end-user segments.
- Automotive Manufacturers:Automotive manufacturers integrate computational photography into advanced driver-assistance systems (ADAS) and fully autonomous vehicles for critical environmental sensing and safety features. These companies drive significant demand for specialized processors and sensor fusion technologies.
- Content Creators:Content creators, including professional photographers and videographers, utilize advanced computational photography tools for post-production editing, special effects, and image enhancement. Adobe Inc. provides sophisticated cloud-based processing tools for this segment.
- Surveillance Agencies:Surveillance agencies deploy computational photography in security cameras and monitoring systems for enhanced object identification and real-time threat detection.
- Film Studios:Film studios employ computational photography techniques for visual effects, virtual production, and high-fidelity scene reconstruction in cinematic productions.
- Research Institutions:Research institutions use computational photography for scientific imaging, medical diagnostics, and developing new algorithms for various applications.
- Advertising Agencies:Advertising agencies leverage computational photography for high-quality product imagery and immersive brand experiences across digital platforms.
Automotive Manufacturers represent a substantial demand base, as Content Creators are gaining share fastest.
Deployment:
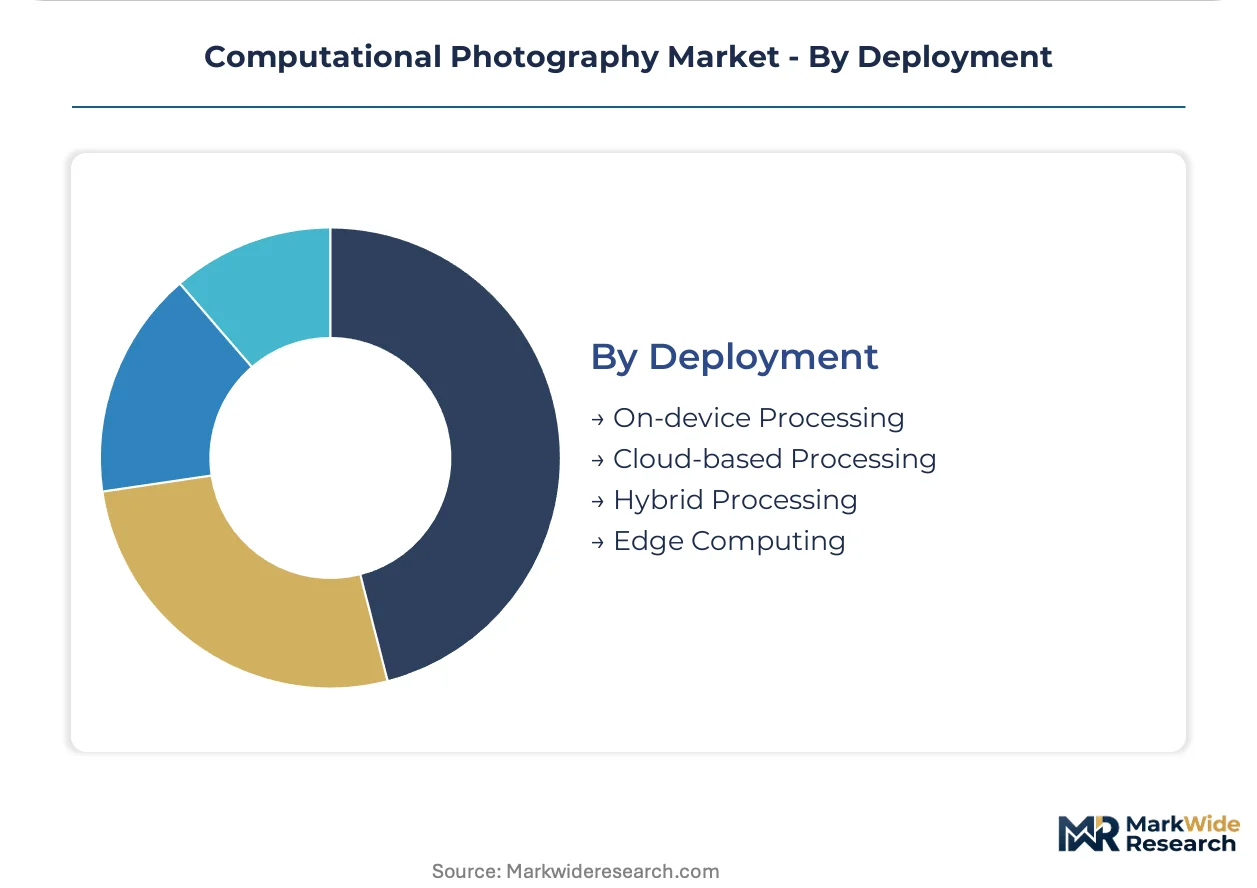
Maturity levels of deployment models influence their current market penetration and future growth trajectories.
- On-device Processing:On-device processing executes computational photography algorithms directly on the camera hardware or integrated system-on-chip (SoC), enabling real-time functionalities and low latency. Apple Inc. optimizes its A-series chip architecture for on-device image pipelines.
- Cloud-based Processing:Cloud-based processing offloads complex computational photography tasks to remote servers, offering scalable resources for high-fidelity rendering and extensive data analytics. Adobe Inc. specializes in these sophisticated editing tools for content creators.
- Hybrid Processing:Hybrid processing combines on-device and cloud-based approaches, performing time-critical tasks locally while leveraging cloud resources for more intensive computations.
- Edge Computing:Edge computing processes image data closer to the source, reducing latency and bandwidth requirements for applications like autonomous systems and smart city infrastructure.
On-device Processing holds the largest market share, while Edge Computing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computational photography market dynamics show a complex interplay between technology development and end-user demand across major economies. Key regions drive innovation while also serving as significant consumption hubs for advanced imaging solutions. This creates varying regional investment priorities and regulatory landscapes influencing market expansion.
China
Demand for computational photography in China is driven by its massive smartphone manufacturing base and rapid expansion of electric vehicles. The Personal Information Protection Law (PIPL) influences data handling practices for image processing applications. Major tech hubs like Shenzhen and Shanghai lead in developing multi-camera systems and AI-powered imaging algorithms.
United States
The United States sees strong demand from autonomous vehicle development and a thriving content creation industry leveraging advanced imaging tools. Regulations like HIPAA impact medical imaging applications of computational photography, ensuring data privacy. Silicon Valley and Detroit are key centers for innovation in sensor fusion and real-time processing for automotive and consumer applications.
Germany
Germany's automotive industry drives significant adoption of computational photography for advanced driver-assistance systems and future autonomous platforms. The EU AI Act introduces a risk-based framework for AI systems, directly affecting algorithm development in this sector. Munich and Stuttgart serve as critical automotive and engineering clusters, fostering innovation in sensor technologies.
Japan
Consumer electronics and automotive sectors in Japan contribute to the demand for computational photography, particularly for high-resolution imaging and depth sensing. The Ministry of Economy, Trade and Industry (METI) supports research and development in advanced optical technologies. Tokyo and Nagoya are prominent innovation centers for camera technology and automotive integration.
South Korea
South Korea's robust smartphone industry and growing electric vehicle production fuel demand for computational photography. Regulations from the Korea Communications Commission (KCC) impact the integration of advanced imaging features in mobile devices. Seoul and Gyeonggi Province are major hubs for electronics manufacturing and R&D in AI-powered imaging solutions.
Computational Photography Market Key Industry Players
Concentration sits with integrated technology giants that control both hardware and software ecosystems, alongside specialized semiconductor companies. The market structure is tiered, featuring large platform providers, dedicated chip designers, and niche software innovators. Competitive moves often involve strategic partnerships to integrate advanced imaging capabilities and significant portfolio diversification into new application verticals.
Among the key players, Apple Inc. and Qualcomm Technologies Inc. exemplify hardware-software integration, optimizing on-device image pipelines for consumer electronics. Adobe Inc. anchors the professional content creation segment, providing sophisticated cloud-based processing tools for post-production. These entities represent distinct approaches to leveraging computational photography, from embedded system design to expansive software ecosystems.
| Leading Market Players |
|---|
| Apple Inc. |
| Alphabet Inc. |
| Samsung Electronics Co. Ltd. |
| Qualcomm Technologies Inc. |
| Adobe Inc. |
| Sony Group Corporation |
| Nvidia Corporation |
| Canon Inc. |
| CEVA Inc. |
| Others |
Cost & Logistics Intelligence
The EU AI Act’s mandates on explainable AI gate both algorithm development qualification and tiered pricing for compliant computational photography solutions. This regulatory framework influences how specialized processors and software licenses are valued across different application segments, particularly in safety-critical systems.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing for specialized computational photography solutions. Price differentiation stems from performance tiers, customization levels for specific sensor arrays, and bundled after-sales integration support. Pricing pressure stems from the high silicon cost of advanced image signal processors, though it is offset by the increasing demand for sophisticated, safety-critical features. Consumer electronics OEMs, particularly in the smartphone segment, exhibit high price sensitivity, while automotive manufacturers prioritize reliability and functionality over lowest cost.
Supply Chain Analysis
Port congestion and container availability along key Asian trade lanes directly influence the cost and lead times for computational photography components. The supply chain concentrates heavily in East Asia, with Taiwan dominating advanced semiconductor manufacturing and China serving as a major hub for camera module assembly and optical components. Key dependencies include specialized image signal processors, neural processing units, and high-quality optical lenses. Single-source vulnerability for advanced silicon components represents a structural risk. Distribution runs through direct sales channels to large OEMs for integrated solutions, complemented by a network of specialized distributors for smaller system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The computational photography market operates as a platform-economics inflection, where the integration of multi-modal sensor data and standardized APIs for advanced driver-assistance systems defines competitive advantage.
For Market Incumbents: Fortify IP portfolios through aggressive patenting of novel algorithms and specialized hardware architectures. This defends against emerging AI-first startups threatening core image processing capabilities. Deepen R&D in edge AI integration and sensor fusion to maintain a technological lead in real-time applications, leveraging existing chip architectures.
For New Entrants and Emerging Players: Anchor in niche application verticals like agricultural drones or medical imaging, which remain underpenetrated by established players. Target these segments with specific computational needs for enhanced clarity or diagnostic accuracy. A key go-to-market angle involves partnering with specialized hardware providers for integrated, purpose-built solutions, bypassing general consumer markets.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized algorithm developers and niche hardware integrators possessing strong intellectual property. Long-term viability is strongest in high-value, safety-critical applications such as automotive and medical diagnostics. The increasing standardization of multi-sensor data formats and APIs serves as a critical signal to watch for market consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AI Algorithm R&D | Enhances image quality and enables new features for competitive differentiation in consumer and automotive sectors. |
| Secure Advanced Silicon Supply | Ensures access to critical image signal processors and neural processing units, mitigating supply chain risks. |
| Standardize Sensor Data Interfaces | Facilitates easier integration of diverse camera and depth sensors, accelerating development for system integrators. |
| Target Medical Imaging Vertical | Captures high-value applications where enhanced image quality directly improves diagnostic accuracy and patient outcomes. |
| Expand Edge AI Capabilities | Enables real-time, on-device processing for autonomous systems and smart devices, reducing latency and bandwidth needs. |
Research Approach
A spread of perspectives from semiconductor engineers, automotive R&D leads, smartphone product managers, and content creation software developers converged on the working assumptions for this study. Primary interviews with these industry stakeholders, combined with secondary validation from company financial reports, technical journals, industry association publications, and patent databases, informed the analysis. The research employed both bottom-up and top-down triangulation to ensure data consistency.
The segmentation dimensions modeled included technology, application, end-user, deployment model, and regional regulatory compliance. The analytical framework projected market growth across the analysis window, deriving compound annual growth rates from historical trends and anticipated technological advancements. Key industry-specific forecast inputs included silicon manufacturing capacity and autonomous vehicle production forecasts.
Material uncertainties — unforeseen regulatory changes, major technological breakthroughs, or geopolitical shifts impacting supply chains — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Wide Field Imaging Devices Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Hybrid Imaging Systems Market
Imaging
Gel Imaging Documentation Market
Imaging
Photography Ring Flash Market
Imaging
Global Digital Photo Frame Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Holotomographic Imaging Market
Imaging
Borescope Market
Imaging
Industrial Camera Market
Imaging
Machine Vision System and Services Market
Imaging
Hyperspectral Imaging Market
Imaging
PET Imaging Systems Market
Imaging
Microwave Imaging Market
Imaging
Live Cell Imaging Market
Imaging
Global CBCT/Cone Beam Imaging Market