
 Vertical Lifts Market | 2026-2036
Vertical Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Lifts Market Analytics
Steel-reinforced polymer composites is expanding their share in vertical lift car structures, cutting weight by approximately one-third versus traditional steel cabs while maintaining EN 81 load ratings. Kardex Group leverages in-house production of automated storage modules to control lead times for industrial clients. Hänel Storage Systems competes through R&D intensity in micro-load vertical lift systems for cleanroom pharmaceutical applications. SSI SCHÄFER anchors its position via manufacturing scale across European distribution hubs.
Vertical lifts are electromechanical or hydraulic transport systems designed to move goods or passengers between fixed levels, with rated speeds typically ranging from 0.15 m/s for freight units to 2.5 m/s for high-rise passenger elevators, governed by EN 81 and ASME A17.1 safety codes. Their primary commercial purpose centers on optimizing vertical circulation in dense built environments, from automated warehouses to multi-story healthcare facilities. Freight elevators and platform lifts dominate installed base volume, though wheelchair lifts represent the fastest-growing product category as accessibility mandates tighten across public infrastructure. Electric drive systems command the largest share of new installations, while hydraulic systems retain share in low-rise industrial settings where load capacity exceeds 5,000 kg.
The EU Machinery Directive and EN 81-20/50 standards shape product design and market access for equipment sold across Europe, while OSHA and ASME A17.1 govern installation safety and worker protection in the United States. China's GB 7588 standard and SAMR certification requirements create a parallel compliance track for manufacturers targeting domestic projects. Stakeholders must monitor divergence between regional safety codes and energy-efficiency benchmarks as modular lift designs aim for cross-border standardization.
Market Dynamics
Warehouse automation adoption by e-commerce fulfillment centers is compressing installation timelines and forcing vertical lift manufacturers to pre-certify modular configurations under EN 81-20/50 standards before shipment.
Growth Catalysts
- E-commerce fulfillment density:Automated storage and retrieval systems in Germany and the Netherlands are pulling demand for high-speed freight elevators with integrated shuttle interfaces.
- EN 81-20/50 harmonization:Unified European safety standards are reducing recertification costs for cross-border projects, accelerating replacement cycles in multi-story industrial facilities.
- Steel-reinforced polymer composites:Lightweight cab materials are cutting installation crane requirements and enabling retrofits in structurally constrained buildings.
Market Restraints
- Copper and rare-earth magnet costs:Permanent magnet synchronous motors depend on neodymium supply concentrated in Chinese processing facilities, exposing OEMs to input price volatility.
- Certification timeline friction:EU Machinery Directive compliance requires third-party notified body review averaging 14-18 months for novel drive configurations, delaying revenue recognition.
- Escalator substitution in retail:Shopping centers below four stories increasingly specify inclined moving walks rather than vertical lifts for passenger circulation, capping addressable volume in commercial real estate.
Strategic Opportunities
- Cleanroom pharmaceutical micro-load systems:Hänel Storage Systems has validated designs for ISO 14644-1 Class 5 environments, opening specification pathways in biotechnology manufacturing clusters.
- US accessibility mandate expansion:ADA Title III enforcement is widening wheelchair lift requirements in public transit infrastructure and educational facilities.
- Predictive maintenance convergence:IoT sensor integration with existing building management systems is creating aftermarket service attach rates in installed base populations.
Industry Challenges
- Mechatronics technician scarcity:Installation and commissioning of electromechanical drive systems requires cross-trained electricians with PLC programming competency, a skill set in short supply across European construction labor markets.
- Legacy hydraulic system integration:Retrofit projects in industrial buildings often encounter undocumented 1970s-era shaft configurations, forcing costly site surveys and custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Lifts Market |
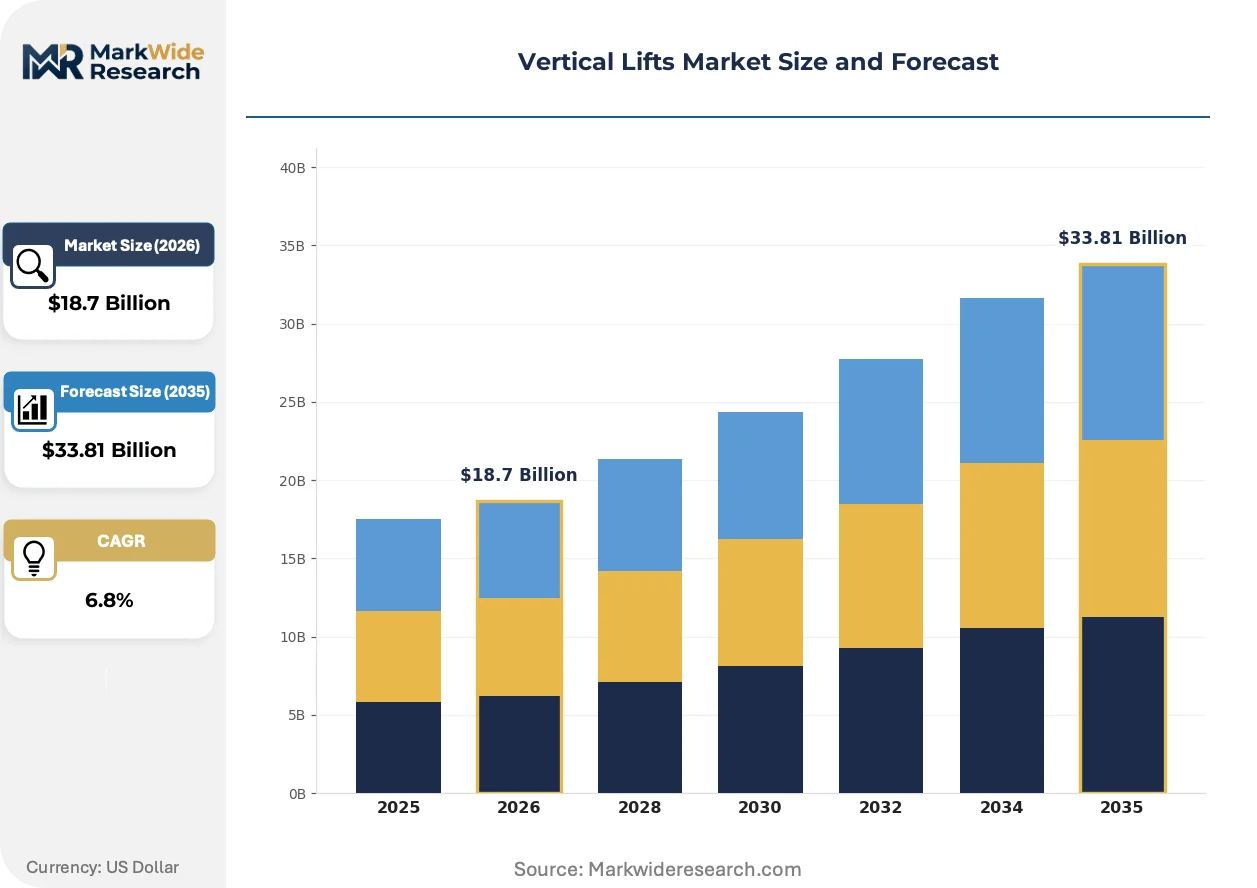
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freight Elevators, Passenger Elevators, Wheelchair Lifts, Platform Lifts End User: Residential, Commercial, Industrial, Healthcare Installation Type: New Installation, Modernization, Maintenance, Repair Drive Type: Hydraulic, Electric, Vacuum, Pneumatic |
| Companies Covered | Kardex Group, Hänel Storage Systems, Ferretto Group, Modula Inc., AutoCrib Inc., SSI SCHÄFER, ICAM S.p.A., Mecalux S.A., Weland Lagersystem AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Lifts Market Evolving Landscape
Digitalization of lift control systems is enabling real-time performance monitoring and predictive intervention, compressing maintenance response windows from scheduled intervals to condition-triggered dispatches.
Machine learning-based traffic analysis is absorbing passenger flow patterns in high-rise commercial buildings to optimize dispatch algorithms and reduce average wait times. Property managers in Frankfurt and Singapore are deploying these systems during peak occupancy periods. The technology is absorbing demand for traditional static zoning configurations by dynamically reallocating cab assignments based on historical and real-time lobby queue data.
REACH restrictions on persistent organic pollutants are phasing out certain hydraulic fluids containing short-chain chlorinated paraffins in European installations. Lift OEMs are reformulating oil specifications and accelerating electromechanical alternatives for low-rise industrial applications. The regulation is most affecting food processing and cold storage facilities in Germany, where contamination risk drives specification preferences toward dry screw or belt-drive alternatives.
Consolidated procurement by facility management platforms is unbundling after-sales service contracts from initial equipment purchases. Institutional buyers in healthcare and logistics are negotiating multi-site maintenance agreements with independent service providers rather than OEM-captive networks. This pattern is most pronounced in the United Kingdom, where NHS estates teams are centralizing vertical transport asset management across hospital trusts.
Vertical Lifts Market Segmentation
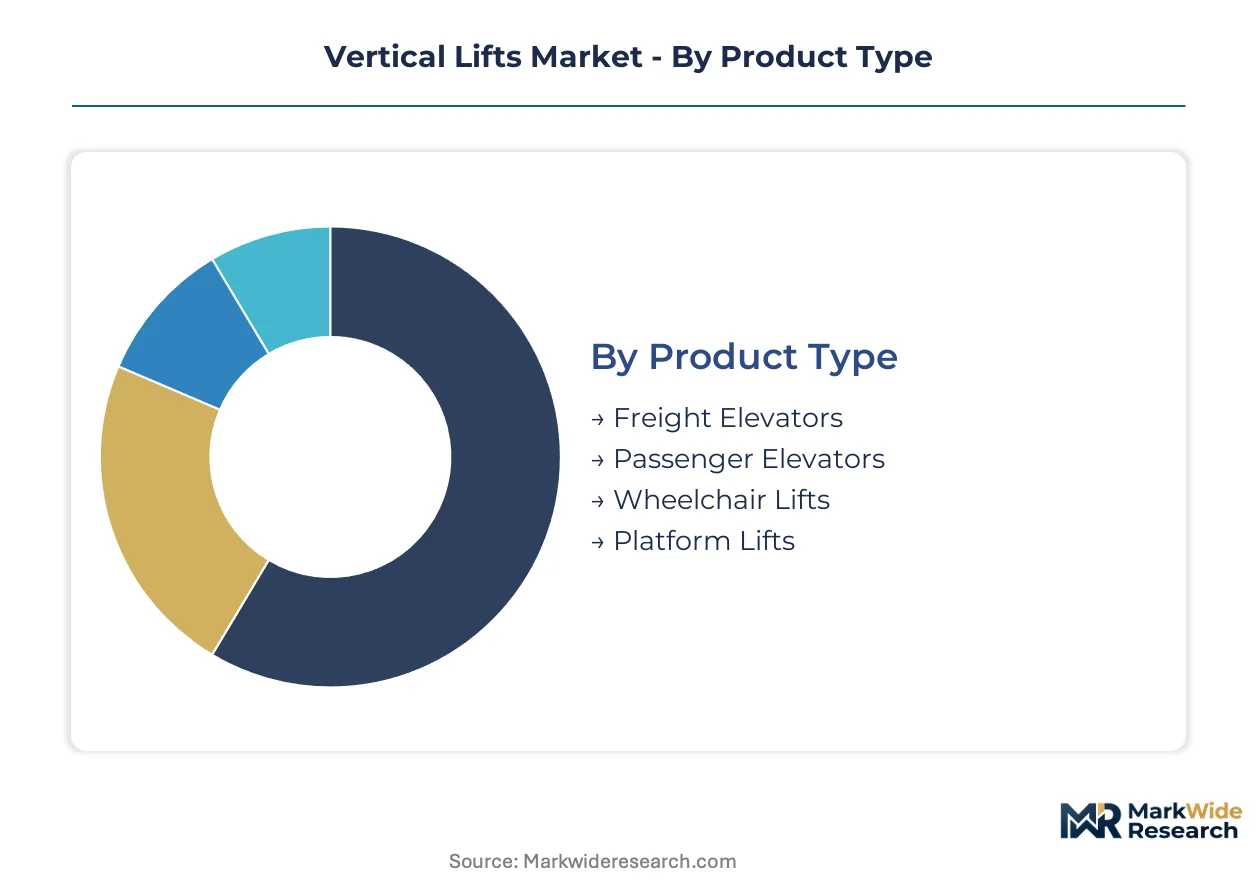
Vertical lift procurement patterns diverge sharply across building typologies and operational lifecycles. Specification decisions hinge on load ratings, shaft constraints, and regulatory compliance windows rather than unit economics alone.
Product Type:
Rated speed and cab configuration define the technical specification axis across vertical lift categories.
- Freight Elevators:These units handle rated loads from 500 kg to over 10,000 kg with door openings engineered for pallet jack and forklift access. Demand concentrates in German automotive parts distribution centers where EN 81-20 compliance for heavy-duty cycle counts drives specification. The shift toward automated storage and retrieval system integration is compressing lead times for cab dimensions matching shuttle robot footprints.
- Passenger Elevators:Traction drive systems dominate this category with rated speeds spanning 1.0 m/s for mid-rise to 2.5 m/s for high-rise applications. Installation clusters in Frankfurt and Singapore commercial towers where machine learning dispatch algorithms are displacing traditional static zoning configurations.
- Wheelchair Lifts:Platform dimensions governed by ADA and EN 81-70 accessibility mandates characterize these low-rise units. Public infrastructure projects in US transit authorities and EU municipal buildings are expanding specification volume.
- Platform Lifts:These vertical lifting platforms serve short-rise applications under 3 meters, common in heritage building retrofits where shaft construction is structurally prohibited.
Mature deployment sits with passenger elevators in commercial high-rises. Newer deployment is concentrated in wheelchair lifts as accessibility mandates tighten across public infrastructure.
End User:
Building occupancy patterns and duty cycle requirements shape procurement specifications across customer categories.
- Residential:Home elevator installations emphasize space-efficient designs with machine-room-less configurations. Demand clusters in multi-generational housing retrofits across suburban US markets and luxury apartment developments in Mumbai.
- Commercial:Office towers and retail complexes specify high-speed traction systems with destination control dispatch. Frankfurt property managers are deploying predictive maintenance IoT integration to compress service response windows.
- Industrial:Automated warehouses and manufacturing facilities prioritize freight elevators with integrated conveyor interfaces. E-commerce fulfillment centers in the Netherlands are pulling demand for high-cycle-duty units with shuttle robot compatibility.
- Healthcare:Hospitals and long-term care facilities require stretcher-compatible cabs with antimicrobial surface specifications. NHS estates teams in the United Kingdom are centralizing vertical transport asset management across hospital trusts.
Industrial end users are expanding fastest on warehouse automation adoption. Healthcare represents the most specification-intensive segment on infection control and emergency evacuation requirements.
Installation Type:
Asset lifecycle position determines procurement modality and margin structure for vertical lift suppliers.
- New Installation:Greenfield projects allow optimized shaft design for destination control and regenerative drive systems. German industrial developments are specifying pre-certified modular configurations to compress EN 81-20/50 compliance timelines.
- Modernization:Control system upgrades and drive replacements extend service life in structurally sound shafts. Undocumented 1970s-era configurations in European industrial buildings frequently trigger costly site surveys and custom engineering.
- Maintenance:Scheduled inspection and component replacement contracts generate recurring revenue streams. Consolidated procurement by UK facility management platforms is unbundling service contracts from initial equipment purchases.
- Repair:Breakdown response and emergency component replacement address unplanned outages. IoT sensor integration is shifting some repair volume toward predictive intervention before failure.
Maintenance commands the largest installed base revenue pool. Modernization is climbing fastest on REACH hydraulic fluid phase-out and electromechanical conversion demand.
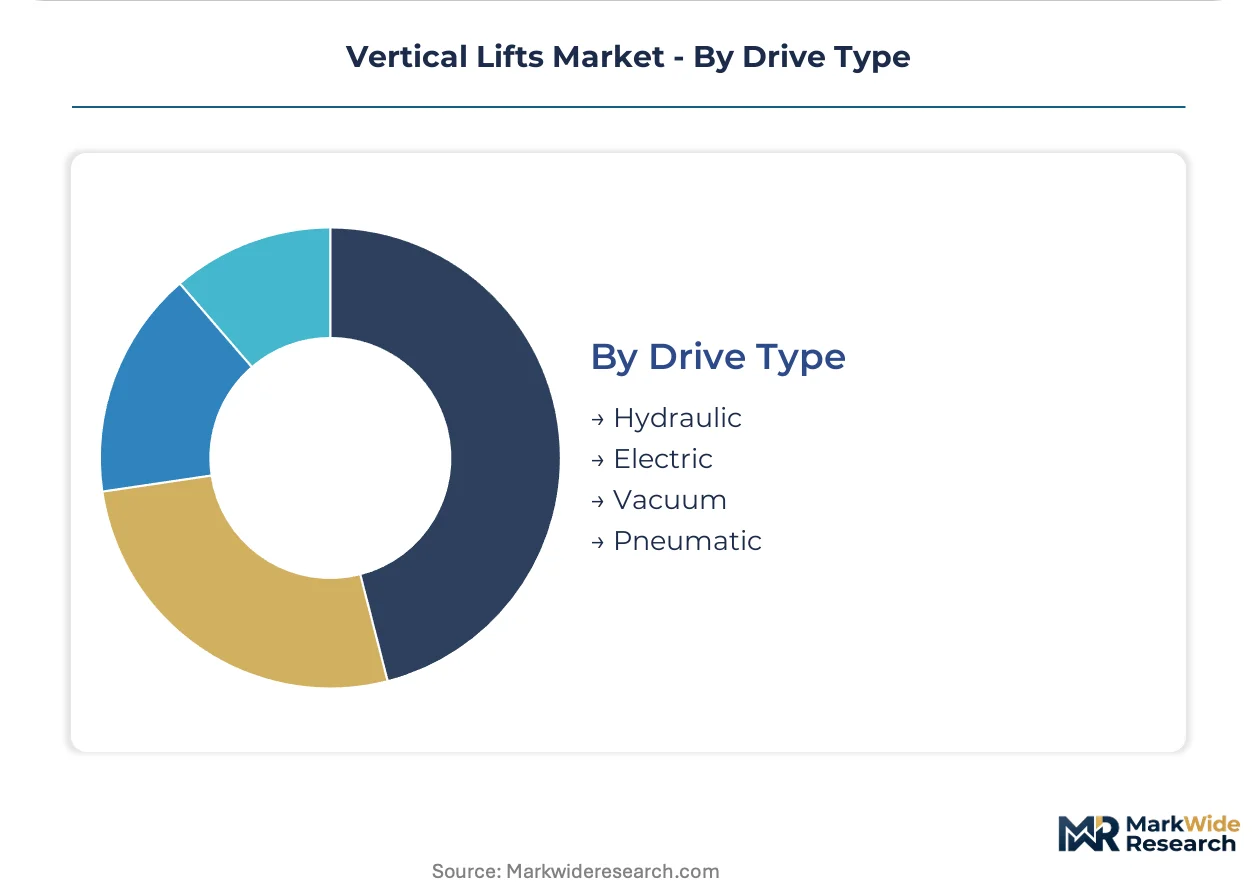
Drive Type:
Power transmission architecture determines efficiency profiles, shaft space requirements, and regulatory exposure.
- Hydraulic:Piston-and-cylinder systems retain share in low-rise industrial settings where load capacity exceeds 5,000 kg. Cold storage facilities in Germany are accelerating conversion to dry alternatives on contamination risk and REACH restrictions on chlorinated paraffin fluids.
- Electric:Traction and gearless drive systems command the largest share of new installations across passenger and freight categories. Permanent magnet synchronous motors depend on neodymium supply concentrated in Chinese processing facilities.
- Vacuum:Air pressure differential systems enable shaft-less installation in residential and heritage applications. These units remain niche on limited travel height and cab capacity constraints.
- Pneumatic:Compressed air drive systems serve specialized cleanroom and explosion-proof environments where electrical spark risk is prohibited.
Electric drives anchor new installation specifications. Hydraulic systems are losing share fastest on energy efficiency benchmarking and fluid regulation tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for vertical lifts concentrates in industrialized economies with dense warehousing infrastructure and stringent accessibility mandates. Germany, the United States, China, Japan, and the Netherlands anchor specification volume through divergent regulatory and operational drivers.
Germany
Automotive parts distribution centers and pharmaceutical manufacturing clusters pull demand for EN 81-20 certified heavy-duty freight elevators. REACH restrictions on chlorinated paraffin hydraulic fluids are accelerating electromechanical conversions in cold storage facilities. Production gravity concentrates in Baden-Württemberg and Bavaria, where Kardex and Hänel anchor automated storage module manufacturing.
United States
ADA Title III enforcement is widening wheelchair lift specifications across public transit infrastructure and educational facilities. OSHA and ASME A17.1 govern installation safety and worker protection, compressing compliance timelines for modular configurations. E-commerce fulfillment density in the Midwest and Southeast is pulling demand for high-cycle-duty freight elevators with shuttle robot interfaces.
China
GB 7588 standards and SAMR certification requirements create a parallel compliance track for domestic projects. Dual carbon goals are tightening energy-efficiency benchmarks for new installations in commercial high-rises. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are absorbing demand for machine-room-less traction systems in luxury residential developments.
Japan
METI efficiency standards and aging building stock are accelerating modernization cycles in Tokyo and Osaka commercial towers. JIS certification requirements shape product design for earthquake-resistant installations. Predictive maintenance IoT integration is compressing service response windows in high-rise residential complexes across the Kanto region.
Netherlands
Automated storage and retrieval system adoption in Rotterdam and Eindhoven distribution hubs is pulling demand for high-speed freight elevators with integrated conveyor interfaces. EU Machinery Directive harmonization reduces recertification costs for cross-border projects serving German and Belgian industrial clients. REACH compliance is phasing out legacy hydraulic fluids in food processing facilities.
Vertical Lifts Market Competitive Landscape
Modular configuration pre-certification dominates the current landscape as manufacturers compress EN 81-20/50 compliance timelines before shipment. The vendor base organizes around three archetypes: diversified industrial automation conglomerates with captive lift divisions, specialized vertical storage system fabricators with in-house module production, and independent service providers unbundling maintenance from equipment sales. Competitive positioning hinges on M&A activity targeting predictive maintenance capabilities and strategic partnerships with e-commerce fulfillment platform operators.
Among European-based specialists, Kardex Group, Hänel Storage Systems, and SSI SCHÄFER occupy positions across the automated storage and retrieval system value chain. Kardex exemplifies the integrated module producer archetype through captive manufacturing of storage components. Hänel represents the R&D-intensive specialist tier with validated designs for cleanroom pharmaceutical environments. SSI SCHÄFER anchors the scale-driven distribution hub operator model across European logistics clusters. These three entities collectively illustrate how geographic proximity to German industrial demand shapes competitive configuration in this market.
| Leading Market Players |
|---|
| Kardex Group |
| Hänel Storage Systems |
| Ferretto Group |
| Modula Inc. |
| AutoCrib Inc. |
| SSI SCHÄFER |
| ICAM S.p.A. |
| Mecalux S.A. |
| Weland Lagersystem AB |
| Others |
Value Network & Pricing Analysis
E-commerce fulfillment platform operators concentrate procurement power through consolidated multi-site contracts, compressing margin structures toward three-tier pricing stratification across premium EN 81-20 certified, standard compliance-grade, and economy modular configurations.
Pricing Analysis
Volume-driven freight elevator sales sacrifice margin for installed base capture, while wheelchair lift specifications command premium pricing on ADA and EN 81-70 certification tiers. Price differentiation rests on EN 81-20/50 compliance grade and after-sales service bundling. Cost compression in standard-tier units is intensifying because copper and rare-earth magnet inputs face Chinese processing concentration. Public infrastructure procurement teams exhibit highest price sensitivity; pharmaceutical cleanroom buyers show lowest.
Supply Chain Analysis
Container freight volatility from Asia to European distribution hubs shapes landed cost structures for electromechanical drive components. Manufacturing gravity centers on Germany, China, and Japan for traction systems and control modules. Neodymium magnet supply draws from Chinese rare-earth processing facilities. Single-source vulnerability in permanent magnet synchronous motor inputs exposes OEMs to input disruption. Distribution runs through authorized dealer networks serving industrial facility managers and construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertical lifts market operates as a cost-of-compliance story where EN 81-20/50 certification timelines averaging 14-18 months erect formidable barriers against non-compliant competitors, entrenching pre-certified modular suppliers with established notified body relationships.
For Market Incumbents: Cement market position by accelerating in-house production of steel-reinforced polymer composite cabs to control lead times against emerging Asian module suppliers. Deepen captive supply of automated storage components to defend against independent service providers unbundling maintenance contracts from equipment sales. For New Entrants and Emerging Players: Independent facility management platforms in the United Kingdom represent the most penetrable channel, consolidating NHS estates and logistics asset management decisions away from OEM-captive networks. Target predictive maintenance IoT integration partnerships to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: The window for entry favors specialized cleanroom micro-load system fabricators with validated ISO 14644-1 Class 5 designs ahead of biotechnology manufacturing cluster expansion. Watch REACH regulatory enforcement intensity as the inflection signal for electromechanical conversion demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Configuration Pre-Certification | Compresses EN 81-20/50 compliance timelines before shipment to e-commerce fulfillment centers. |
| Predictive Maintenance Platform Integration | Creates aftermarket service attach rates via IoT sensor convergence with building management systems. |
| Cleanroom Pharmaceutical System Validation | Opens specification pathways in biotechnology manufacturing clusters requiring ISO 14644-1 Class 5 compliance. |
| Steel-Reinforced Polymer Composite Production | Reduces installation crane requirements through one-third weight reduction versus traditional steel cabs. |
| Independent Service Provider Network Expansion | Captures unbundled maintenance contracts from consolidated UK facility management platform procurement. |
Research Methodology
Multi-period observation of EN 81-20/50 certification timelines, neodymium price volatility, and e-commerce fulfillment center buildout rates anchored the trend analysis, supplemented by interviews with maintenance directors at German automotive distribution centers, plant engineers at Dutch logistics hubs, procurement leads at UK NHS estates teams, and aftermarket service heads at independent facility management platforms. Secondary validation drew from EU Machinery Directive implementation records, REACH restriction enforcement databases, OSHA incident reporting, and customs trade data on elevator component imports. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across warehouse, healthcare, and commercial building typologies.
Input-output matrices modeled demand drivers across product type, end user, installation modality, and drive architecture dimensions throughout the forecast period. CAGRs were derived from segmented growth rate differentials applied to base-year value estimates. Industry-specific forecast inputs included automated storage and retrieval system adoption curves in German and Netherlands distribution clusters, plus ADA Title III enforcement intensity trajectories in US public infrastructure.
Caveats apply where EN 81-20/50 regulatory divergence, rare-earth supply disruption, or e-commerce capital expenditure cycles could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Sorting Equipment Market