
 Air Classifying Mill Market | 2026-2036
Air Classifying Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Air Classifying Mill Market Outlook
The gap between premium precision-class systems and commodity grinding equipment is expanding as pharmaceutical and specialty chemical buyers demand validated particle-size distributions while bulk mineral processors prioritize throughput economics. Hosokawa Alpine leverages its jet-milling expertise to dominate high-value pharmaceutical contracts in Europe. Bühler Group anchors its position through integrated process lines that couple milling with real-time particle analysis. Prater Industries competes on customization depth for mid-tier food and chemical applications.
An air classifying mill integrates a grinding chamber with an internal air classifier, using high-velocity airflow to separate particles by size while recirculating oversized material for further reduction, typically achieving cut points between 5 and 150 microns depending on rotor speed and air volume. The unit serves primary industrial purpose in controlled comminution where narrow particle distribution directly affects product performance, such as inhalable drug powders or functional food ingredients. Dry grinding systems lead installed base owing to lower capital and operating costs, though wet grinding configurations capture margin pools in heat-sensitive and nanomaterial applications. Jet milling technology occupies the premium tier for ultrafine pharmaceutical and ceramic powder production, while impact milling dominates volume in chemical and plastics processing where broader distributions prove acceptable.
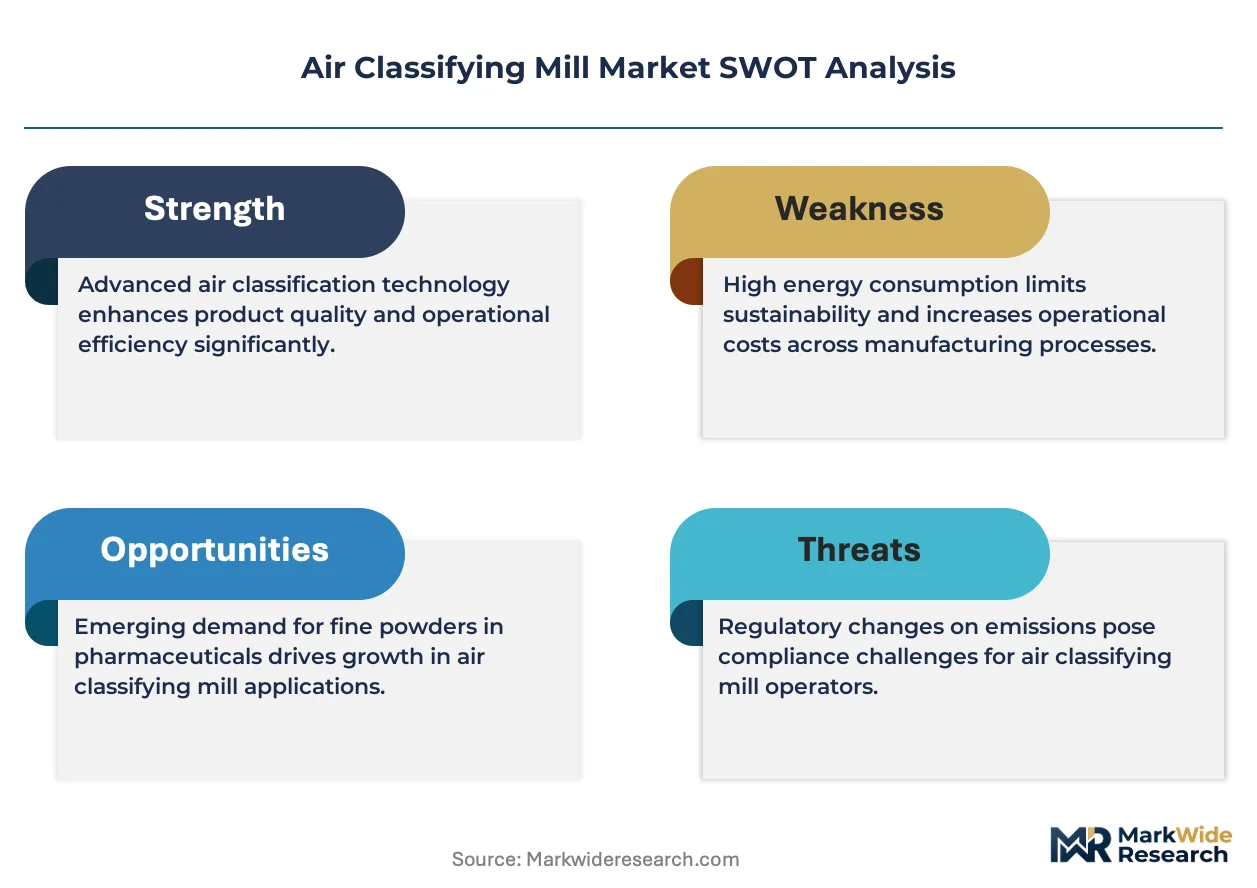
FDA cGMP guidelines and EU MDR conformity requirements shape equipment validation protocols, compelling manufacturers to document particle consistency, contamination control, and cleanability for pharmaceutical market access. ISO 9001 quality management and ATEX explosion-protection standards further constrain design choices for chemical and food-processing deployments. Stakeholders must monitor evolving FDA guidance on continuous manufacturing and EU Green Deal energy-efficiency mandates as these frameworks will determine next-generation equipment specifications and competitive differentiation.
Market Dynamics
Precision particle sizing requirements from pharmaceutical formulators are compressing tolerance bands for air classifying mills, forcing equipment suppliers to validate tighter cut-point distributions while maintaining throughput economics.
Growth Catalysts
- EU MDR conformity mandates:Medical device powder manufacturers must document particle consistency under stricter validation protocols, expanding demand for certified milling systems across European contract manufacturing organizations.
- Inhalable drug delivery expansion:Dry powder inhaler formulations require narrow distributions in the 1-5 micron range, pulling specialized jet-milling configurations into respiratory therapy supply chains.
- Functional food ingredient processing:Probiotic encapsulation and bioactive compound stabilization in Germany and Switzerland drives adoption of cryogenic-compatible air classifying configurations.
Market Restraints
- Specialized alloy input volatility:Wear-resistant grinding rotors and classifier wheels require nickel-based superalloys and tungsten carbide, exposing equipment margins to aerospace-driven metal price swings.
- Validation documentation burden:FDA cGMP compliance timelines extend pharmaceutical equipment sales cycles by 8-14 months, compressing working capital efficiency for mill suppliers.
- Ultrasonic milling substitution:Liquid-processing applications in nanomaterial synthesis increasingly favor wet bead mills that achieve sub-micron cuts without thermal degradation risks.
Strategic Opportunities
- Continuous manufacturing alignment:FDA guidance on real-time release testing creates openings for integrated milling-classification-analyzer skids that eliminate batch-to-batch variability.
- India pharmaceutical expansion:CDSCO harmonization with ICH Q13 guidelines positions domestic generic API producers to upgrade from commodity grinders to validated air classifying systems.
- Carbon-negative process integration:EU Green Deal efficiency benchmarks reward heat-recovery designs and regenerative blower configurations that cut specific energy consumption per kilogram processed.
Industry Challenges
- Multiphysics simulation expertise scarcity:Computational fluid dynamics modeling for classifier rotor optimization requires rare combinations of particle mechanics and turbulence engineering skills.
- Legacy DCS integration friction:Brownfield chemical plants running proprietary distributed control systems demand costly protocol gateways to connect smart mill diagnostics to existing automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Classifying Mill Market |
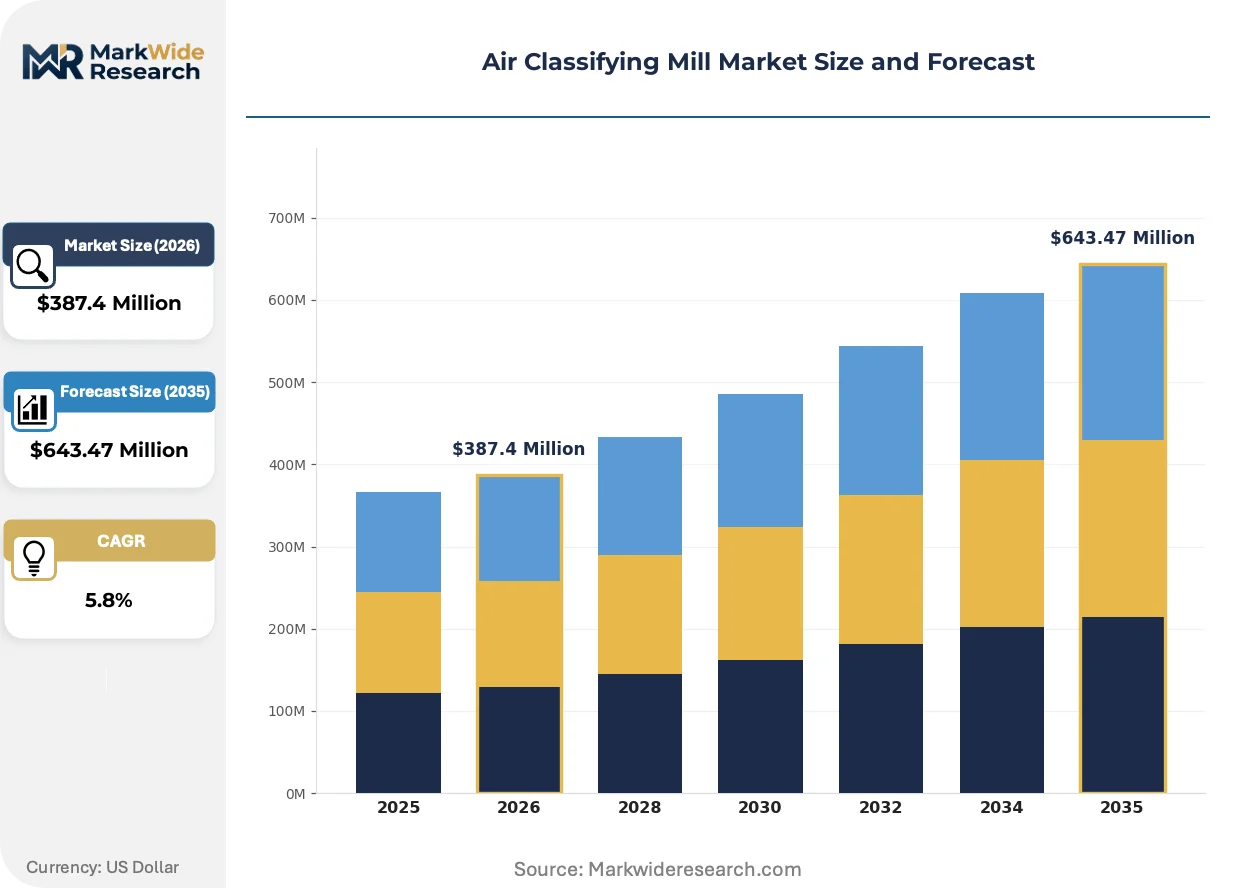
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $643.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Grinding, Wet Grinding, Laboratory Mills, Custom Mills Application: Pharmaceuticals, Food Processing, Chemicals, Plastics End User: Manufacturers, Research Institutions, Food Service Providers, Laboratories Technology: Impact Milling, Jet Milling, Pin Milling, Ball Milling |
| Companies Covered | Prater Industries, Bühler Group, Hosokawa Alpine, Sturtevant Inc., Fitzpatrick, Hosokawa Micron, Schutte-Buffalo Hammermill, Kason Corporation, NETZSCH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Classifying Mill Market Strategic Shifts
Real-time particle analysis hardware is embedding directly into milling circuits, collapsing the feedback loop between size measurement and process adjustment that previously required offline laboratory testing.
In-line laser diffraction sensors are integrating with air classifier discharge streams to enable closed-loop rotor speed modulation. Pharmaceutical manufacturers in Germany and Switzerland are deploying these configurations for inhalable powder batches. The technology is integrating quality-by-design principles into continuous processing lines, reducing rejected batches and regrind volumes.
REACH authorization requirements for cobalt-containing hardfacing alloys are compelling redesigns of classifier wear components. Equipment suppliers are qualifying ceramic-matrix composites and nitride coatings as alternatives. European chemical processors face the steepest transition costs, with some deferring capacity expansions until alternative materials complete 18-month validation cycles.
Equipment-as-service contracts are displacing capital purchase models among mid-tier food ingredient processors. Dutch and Belgian contract manufacturers now specify throughput-based pricing with guaranteed particle distribution bands. This shift concentrates performance risk on mill suppliers while accelerating technology refresh cycles in mature installed bases.
Air Classifying Mill Market Segmentation
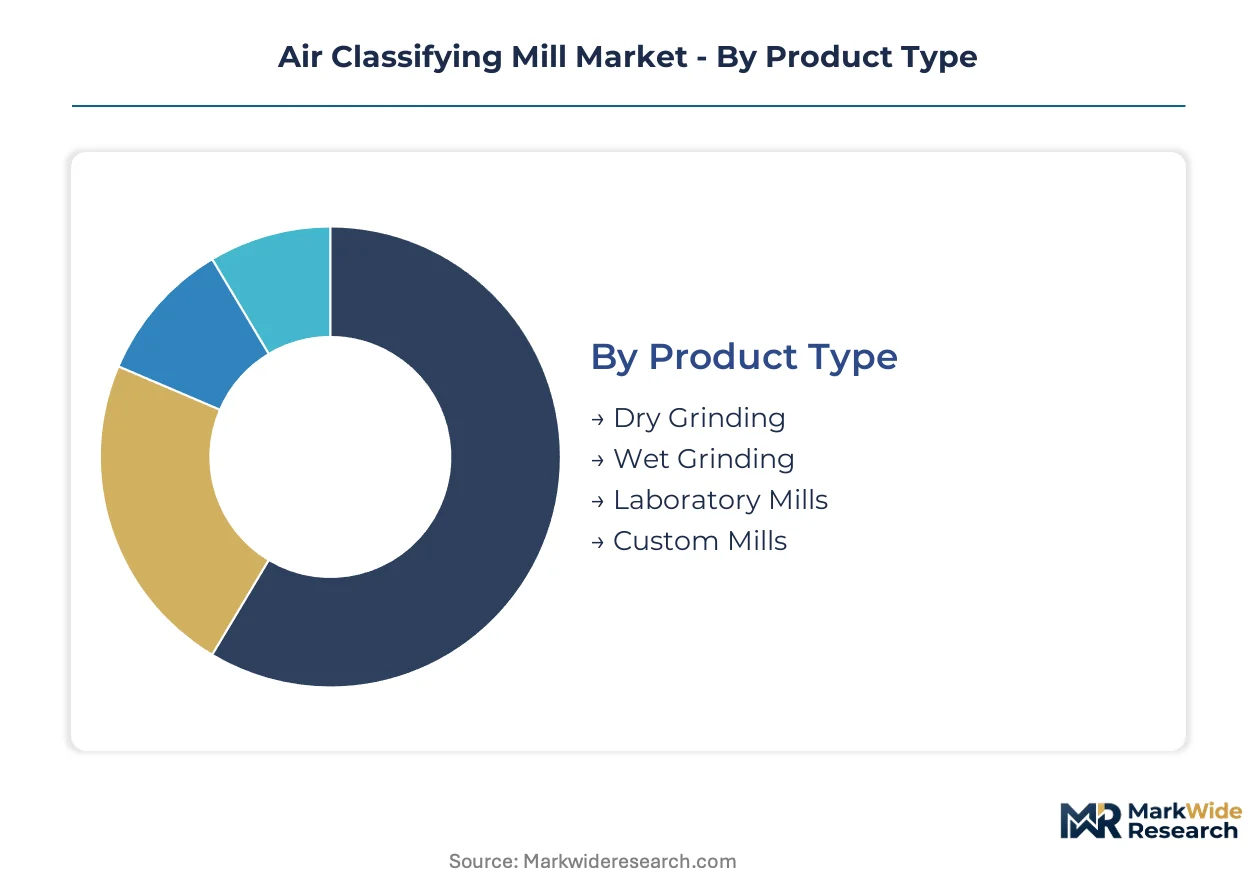
Air classifying mill buyers exhibit sharply divergent technical requirements across end-use contexts. Pharmaceutical formulators prioritize validated particle distributions and cleanability, while bulk chemical processors optimize for throughput economics and wear resistance.
Product Type:
Buyers in this category separate by thermal sensitivity of feedstocks and capital deployment capacity.
- Dry Grinding:Systems process heat-stable powders using ambient airflow for size reduction and classification in a single vessel. Food ingredient processors in Germany and Switzerland deploy these configurations for functional powder production, driven by lower operating costs and simpler material handling.
- Wet Grinding:Liquid-suspension processing prevents thermal degradation of heat-sensitive APIs and enables nanomaterial synthesis. Specialty chemical manufacturers favor these units where sub-micron cuts are required without risk of particle fusion.
- Laboratory Mills:Bench-scale units enable formulation scientists to validate particle specifications before production scale-up.
- Custom Mills:Engineered-to-order systems address exotic material abrasiveness or containment requirements for potent compound handling.
Dry grinding configurations lead volumes today; wet grinding systems are gaining share fastest in pharmaceutical applications.
Application:
End-use concentration determines validation burden and equipment specification tier.
- Pharmaceuticals:Inhalable drug powders and controlled-release formulations demand narrow particle distributions with documented consistency. FDA cGMP and EU MDR compliance requirements force buyers toward premium equipment tiers with full qualification documentation.
- Food Processing:Probiotic encapsulation and bioactive stabilization applications in Germany drive cryogenic-compatible air classifying configurations. Clean-in-place protocols and allergen containment distinguish this segment from industrial chemical processing.
- Chemicals:Bulk mineral and specialty chemical processors prioritize throughput economics over tight distribution tolerances.
- Plastics:Polymer powder production for rotational molding and additive manufacturing tolerates broader particle ranges.
Pharmaceutical applications command the highest equipment margins; food processing is climbing fastest as functional ingredient markets expand.
End User:
Procurement sophistication and technical specification authority vary sharply across buyer types.
- Manufacturers:Integrated production facilities specify equipment for continuous operation with minimal operator intervention. These buyers dominate installed base volume and drive standardization around ISO 9001 quality frameworks.
- Research Institutions:Academic and government laboratories prioritize flexibility for multiple feedstock types over production throughput.
- Food Service Providers:Contract manufacturers specify throughput-based performance guarantees with distribution band commitments.
- Laboratories:Analytical and QC labs require rapid batch turnaround with minimal cross-contamination risk.
Manufacturers represent the dominant buyer type today; contract food service providers are expanding procurement most aggressively.
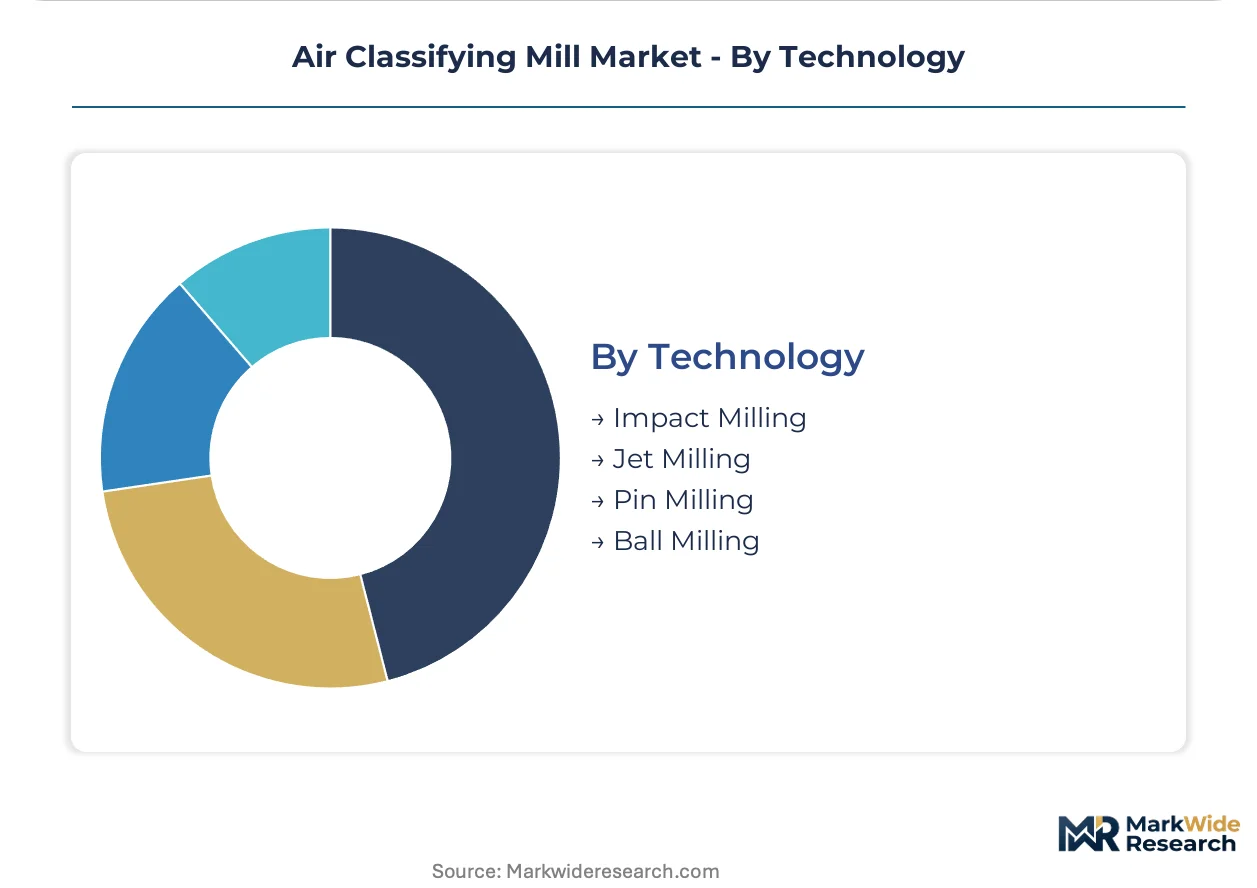
Technology:
Milling mechanism selection trades cut-point precision against energy intensity and capital cost.
- Impact Milling:High-speed rotor impactors achieve rapid size reduction for friable materials. Chemical and plastics processors favor these systems where broader distributions prove acceptable and capital constraints limit equipment budgets.
- Jet Milling:Compressed gas acceleration delivers ultrafine cuts without mechanical wear contamination. Pharmaceutical manufacturers in Germany and Switzerland deploy these configurations for inhalable powder production, pulled by EU MDR validation requirements.
- Pin Milling:Intermeshing pin rotors handle fibrous and heat-sensitive materials with controlled temperature rise.
- Ball Milling:Tumbling media grinding serves nanomaterial synthesis and ceramic powder production where extended residence times are acceptable.
Impact milling dominates unit shipments today; jet milling is expanding most quickly in respiratory therapy supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in southern Germany and Switzerland anchor precision milling innovation, while pharmaceutical manufacturing expansion in India and contract food processing growth in the Benelux reshape demand geography.
Germany
Inhalable drug powder production and probiotic encapsulation drive equipment upgrades in Bavaria and Baden-Württemberg. EU MDR conformity mandates tighten validation protocols for medical device powder manufacturers. Stuttgart and Augsburg host advanced manufacturing clusters where Hosokawa Alpine and Bühler Group anchor integrated milling-classification-analyzer skids for continuous pharmaceutical processing.
United States
Specialty chemical nanomaterial synthesis and respiratory therapy supply chains pull wet-grinding configurations into New Jersey and North Carolina research corridors. FDA cGMP guidelines extend equipment sales cycles by 8-14 months, compressing working capital efficiency. Greater Boston and Research Triangle Park concentrate contract manufacturing organizations adopting real-time particle analysis hardware for quality-by-design compliance.
India
Generic API producers in Maharashtra and Gujarat upgrade from commodity grinders to validated air classifying systems as CDSCO harmonizes with ICH Q13 continuous manufacturing guidelines. Domestic pharmaceutical expansion creates demand for certified milling systems with full qualification documentation. Hyderabad and Mumbai pharmaceutical clusters drive fastest procurement growth among emerging markets.
Switzerland
Bioactive compound stabilization and functional food ingredient processing in Basel-Land and Zurich cantons favor cryogenic-compatible air classifying configurations. Swissmedic oversight aligns with EU MDR standards for medical device powder consistency. Basel's pharmaceutical corridor couples precision milling with real-time particle analysis for inhalable drug delivery formulations.
Netherlands
Contract food ingredient processors in Noord-Brabant and Zuid-Holland specify throughput-based equipment-as-service contracts with guaranteed particle distribution bands. REACH authorization requirements for cobalt-containing hardfacing alloys compel redesigns of classifier wear components. Eindhoven and Rotterdam manufacturing hubs concentrate performance risk on mill suppliers through outcome-based pricing models.
Air Classifying Mill Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the air classifying mill market, with integrated process line builders holding margin advantages over component specialists. The vendor base stratifies into three tiers: premium precision-class system builders serving pharmaceutical validation requirements, mid-tier customization shops addressing food and chemical flexibility needs, and commodity grinding equipment manufacturers competing on throughput economics. Dominant competitive moves include integrated sensor-analyzer bundling that collapses feedback loops, and equipment-as-service contract structures that shift performance risk from processors to mill suppliers.
Within the premium precision tier, Hosokawa Alpine and Bühler Group exemplify integrated process line builders, with the former representing jet-milling expertise for pharmaceutical applications and the latter anchoring positions through coupled milling-classification-analyzer configurations. Prater Industries occupies a mid-tier customization position, serving food and chemical processors requiring engineered-to-order flexibility without full pharmaceutical validation documentation. These three company structures illustrate the market's fundamental segmentation between validated pharmaceutical systems and adaptable industrial configurations.
| Leading Market Players |
|---|
| Prater Industries |
| Bühler Group |
| Hosokawa Alpine |
| Sturtevant Inc. |
| Fitzpatrick |
| Hosokawa Micron |
| Schutte-Buffalo Hammermill |
| Kason Corporation |
| NETZSCH |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal energy-efficiency benchmarks gate qualified supply and premium-tier pricing access by mandating heat-recovery designs and regenerative blower configurations that only certified European suppliers can deliver. Pharmaceutical buyers in Germany and Switzerland pay substantial premiums for validated milling-classification-analyzer skids that satisfy FDA cGMP and EU MDR documentation requirements, while commodity chemical processors in India and China source standard impact mills through price-competitive tender processes.
Pricing Analysis
Bundled equipment-as-service contracts now command 15-25% lifetime premiums over unbundled capital purchases among Dutch and Belgian contract food manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical systems with full qualification documentation from mid-tier customizable units and basic throughput-focused grinders. Cost compression in the standard tier is intensifying because nickel-based superalloy input volatility exposes equipment margins to aerospace-driven metal price swings. Contract food service providers exhibit highest price sensitivity, while respiratory therapy formulators demonstrate lowest sensitivity due to narrow particle distribution mandates.
Supply Chain Analysis
Freight cost differentials between precision-machined classifier rotors sourced from southern Germany and commodity grinding components manufactured in China create significant landed cost gaps for North American buyers. Supply concentrates in Germany, Switzerland, and Japan for wear-resistant grinding rotors requiring tungsten carbide and ceramic-matrix composites. Raw material dependencies include nickel-based superalloys, cobalt-containing hardfacing alloys facing REACH authorization restrictions, and precision bearings from Japanese specialty manufacturers. Single-source vulnerability around computational fluid dynamics simulation expertise for classifier optimization creates bottlenecks. Distribution runs through OEM direct sales for pharmaceutical tiers and regional industrial distributors for commodity chemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier pharmaceutical systems where EU MDR validation requirements and cobalt-alloy substitution costs create pricing power, while equipment-as-service contracts generate recurring revenue streams that offset capital purchase cyclicality.
For Market Incumbents: Deepen integration of real-time particle analysis hardware into milling circuits to collapse feedback loops that ultrasonic wet-bead mills exploit as substitute threats. Invest in ceramic-matrix composite validation programs to preempt REACH-driven cobalt alloy obsolescence. Expand heat-recovery design capacity in Baden-Württemberg to capture EU Green Deal efficiency mandate premiums before mid-tier competitors qualify alternative configurations. For New Entrants and Emerging Players: Capture contract manufacturing organization procurement in India where CDSCO harmonization with ICH Q13 guidelines forces generic API producers to upgrade from commodity grinders. Target Maharashtra and Gujarat pharmaceutical clusters with validated air classifying systems priced below Hosokawa Alpine and Bühler Group premiums. Lead with equipment-as-service contracts that shift performance risk to suppliers and accelerate technology refresh cycles in underpenetrated installed bases. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier customization specialists because pharmaceutical validation documentation burdens extend sales cycles 8-14 months, creating scale advantages for consolidated players that amortize compliance costs across broader revenue bases. Prioritize targets with installed bases in functional food ingredient processing where cryogenic-compatible configurations command pricing premiums. Watch FDA guidance on continuous manufacturing as the inflection signal that determines whether integrated milling-classification-analyzer skids capture share from batch-oriented legacy equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Sensor-Analyzer Bundling | Collapses feedback loops between Hosokawa Alpine milling circuits and real-time particle measurement for pharmaceutical quality-by-design compliance. |
| Equipment-as-Service Contract Expansion | Shifts performance risk to Bühler Group and concentrates procurement growth among Dutch contract food manufacturers seeking guaranteed distribution bands. |
| Ceramic-Matrix Composite Qualification | Addresses REACH authorization requirements for cobalt-containing hardfacing alloys in European chemical processor classifier wear components. |
| Heat-Recovery Design Investment | Captures EU Green Deal efficiency benchmarks through regenerative blower configurations that cut specific energy consumption per kilogram processed. |
| Continuous Manufacturing Alignment | Positions integrated milling-classification-analyzer skids for FDA real-time release testing guidance in respiratory therapy supply chains. |
Study Parameters
Direct dialogue with pharmaceutical process engineers, food ingredient plant managers, chemical procurement leads, and aftermarket service heads grounded qualitative findings in operational realities. Secondary validation drew from FDA cGMP guidance documents, EMA MDR conformity assessments, EU Green Deal efficiency benchmark publications, and SEC filings from disclosed precision equipment manufacturers. Bottom-up and top-down triangulation cross-checked unit shipment estimates against capital expenditure disclosures and regional import data.
Bottom-up modeling aggregated segment-level demand across product type, application, and technology dimensions, while top-down validation tested aggregate figures against macroeconomic drivers and regional production indices. Analytical framework approach over the projection horizon modeled pharmaceutical validation tier, food processing cryogenic compatibility, chemical throughput economics, and plastics powder tolerance as core segmentation dimensions. CAGRs were derived from fitted growth curves incorporating equipment replacement cycles, regulatory phase-in schedules, and regional manufacturing expansion patterns. Industry-specific forecast inputs included inhalable drug delivery pipeline data and functional food ingredient market trajectories.
Regulatory timeline acceleration, raw material substitution cost volatility, and continuous manufacturing adoption rates are the dominant revision risks that could shift equipment demand timing and tier mix. Forecasts reflect assumptions about validation burden persistence and energy efficiency mandate stringency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Autonomous Material Handling Equipment Market