
 Canada Metal Fabrication Equipment Market | 2026-2036
Canada Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Metal Fabrication Equipment Market Outlook
Precision component suppliers serving aerospace and defense programs is rotating toward automated fabrication systems as labor scarcity intensifies across Ontario and Quebec. TRUMPF Canada Inc. leverages its laser cutting portfolio to anchor high-value contracts with tier-one aerospace manufacturers in Montreal and Toronto. AMADA Canada Ltd. sustains competitive positioning through specialized press brake and turret punch press lines calibrated for thin-gauge aluminum processing. Lincoln Electric Canada dominates the welding equipment segment with deep channel control across independent distributor networks serving Prairie province energy projects.
Canada metal fabrication equipment encompasses CNC-controlled machine tools, robotic welding cells, laser and plasma cutting systems, and hydraulic press brakes engineered to transform raw steel, aluminum, and specialty alloys into precision-machined components, structural assemblies, and finished metal products. These systems operate at tolerances ranging from ±0.001 inch for aerospace-grade laser cutting to ±0.010 inch for heavy structural welding, serving as the production backbone for durable goods manufacturing across transportation, energy, and construction sectors. Laser cutters lead product type demand as aluminum-intensive aerospace programs and electric vehicle chassis fabrication drive fiber laser adoption over CO2 systems. CNC technology anchors the technology dimension with multi-axis machining centers displacing manual equipment in high-mix, low-volume job shops across the Golden Horseshoe manufacturing belt.
Health Canada coordinates with CSA Group to enforce machinery safety standards under the Canadian Electrical Code and CSA Z432 safeguarding requirements, compelling equipment retrofit cycles and certified control system upgrades. The Canadian Environmental Protection Act and provincial emissions regulations in Ontario and British Columbia restrict solvent-based cutting fluids and particulate discharge from plasma cutting operations, redirecting procurement toward closed-loop coolant systems and fume extraction integration. Stakeholders must monitor evolving carbon border adjustment mechanisms and domestic content thresholds in federal defense and infrastructure procurement to align fabrication capacity with preferential sourcing rules.
Market Dynamics
Fiber laser adoption is bifurcating fabrication workflows across Ontario and Quebec as aerospace and electric vehicle manufacturers demand aluminum-optimized cutting systems that displace legacy CO2 installations.
Growth Catalysts
- CSA Z432 Safeguarding Mandates:Health Canada's machinery safety alignment is compelling certified control system upgrades and accelerating equipment retrofit cycles among Ontario job shops.
- Electric Vehicle Chassis Fabrication:Battery enclosure and structural aluminum demand from Greater Toronto Area automotive suppliers is pulling fiber laser and robotic welding cell procurement.
- Defense Procurement Localization:Federal domestic content thresholds for military and infrastructure contracts are redirecting capital investment toward Canadian-based fabrication capacity expansion.
Market Restraints
- Specialized Steel Input Volatility:Aerospace-grade aluminum and high-strength alloy pricing fluctuations compress margin visibility for precision component suppliers locked into long-term OEM contracts.
- Equipment Import Concentration:Critical laser source and CNC control system supply chains route through German and Japanese manufacturing bases, exposing Prairie province fabricators to extended lead times.
- Technical Labor Scarcity:Multi-axis CNC programming and robotic cell integration expertise pools concentrate in Montreal and Toronto, constraining expansion capacity in secondary manufacturing clusters.
Strategic Opportunities
- Western Canada Energy Infrastructure:Alberta and Saskatchewan carbon capture and hydrogen project pipelines are creating demand for heavy structural fabrication equipment serving pressure vessel and pipeline component programs.
- Closed-Loop Coolant Integration:British Columbia and Ontario emissions regulations restricting solvent-based cutting fluids are opening procurement channels for integrated fume extraction and fluid recycling system bundles.
- Hybrid Laser-Arc Welding Convergence:Maritime defense and shipbuilding programs in Nova Scotia and British Columbia are piloting combined laser and GMAW processes for thick-section aluminum joining.
Industry Challenges
- CSA Certification Timeline Compression:Electrical and machinery safety approval cycles for imported European and Asian equipment create deployment delays that misalign with customer delivery commitments.
- Legacy Pneumatic System Integration:Established Ontario job shops face capital and downtime burdens retrofitting hydraulic press brake and turret punch press fleets with servo-electric drives for energy compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Metal Fabrication Equipment Market |
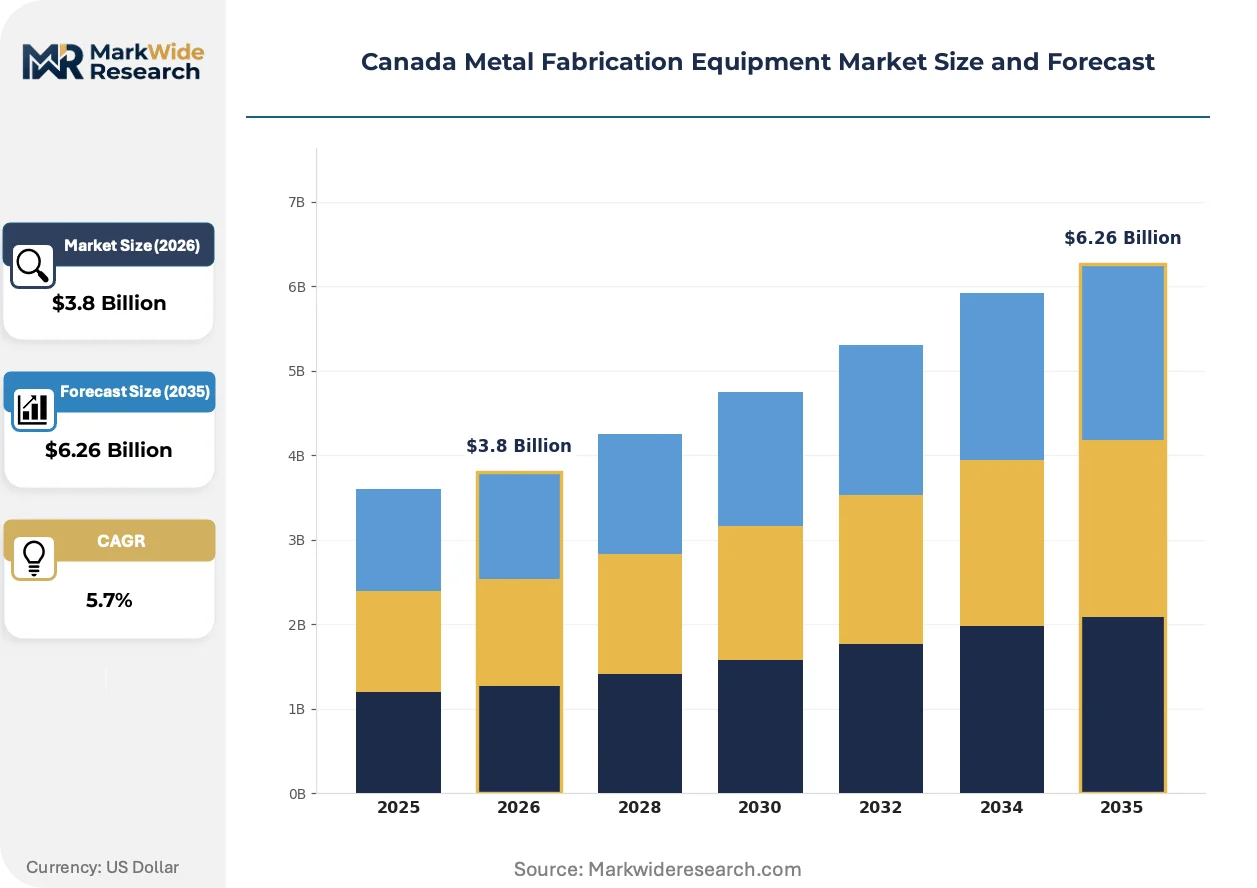
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lathes, Welders, Laser Cutters, Press Brakes Technology: CNC, Robotics, Plasma Cutting, Manual End User: Aerospace, Construction, Automotive, Marine Industry Vertical: Manufacturing, Metalworking, Energy, Defense |
| Companies Covered | Lincoln Electric Canada, Sandvik Mining & Rock Solutions Canada, TRUMPF Canada Inc., FANUC Canada, Bystronic Canada, AMADA Canada Ltd., Atlas Copco Manufacturing Canada, Haas Automation Canada, DMG MORI Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Metal Fabrication Equipment Market Strategic Shifts
Automation architectures are fragmenting procurement patterns across Canadian fabrication, with distinct technology stacks emerging for high-mix job shops versus dedicated aerospace production lines.
Fiber laser cutting technology is bifurcating equipment procurement between high-power systems for thick-section structural steel and specialized mid-power units optimized for thin-gauge aluminum aerospace components. Tier-one Montreal and Toronto aerospace suppliers are standardizing on 6-8 kilowatt fiber platforms with automated material handling, while Golden Horseshoe job shops retain hybrid CO2-fiber fleets for customer flexibility. This technology split is compressing residual values for pure CO2 systems and redirecting distributor inventory toward aluminum-calibrated cutting heads and nitrogen assist gas integration.
Health Canada's coordination with CSA Group on machinery safeguarding standards is mandating certified safety control upgrades that extend equipment commissioning timelines. The Canadian Electrical Code alignment with European CE functional safety categories is forcing retrofit of legacy relay-based interlock systems with programmable safety PLCs. Quebec aerospace fabricators are responding fastest due to existing Airbus and Bombardier supplier quality frameworks, while independent Ontario shops face steeper compliance cost absorption.
Buyer concentration among tier-one automotive and defense primes is consolidating equipment specification authority away from independent job shops. Original equipment manufacturers in the Greater Toronto Area are mandating approved vendor lists and standardized machine platforms that lock out smaller fabricators from qualification. This channel compression is most visible in Ontario's precision manufacturing corridor, where multi-year framework agreements between TRUMPF Canada and major automotive suppliers are displacing competitive bidding for laser cutting capacity.
Canada Metal Fabrication Equipment Market Segmentation
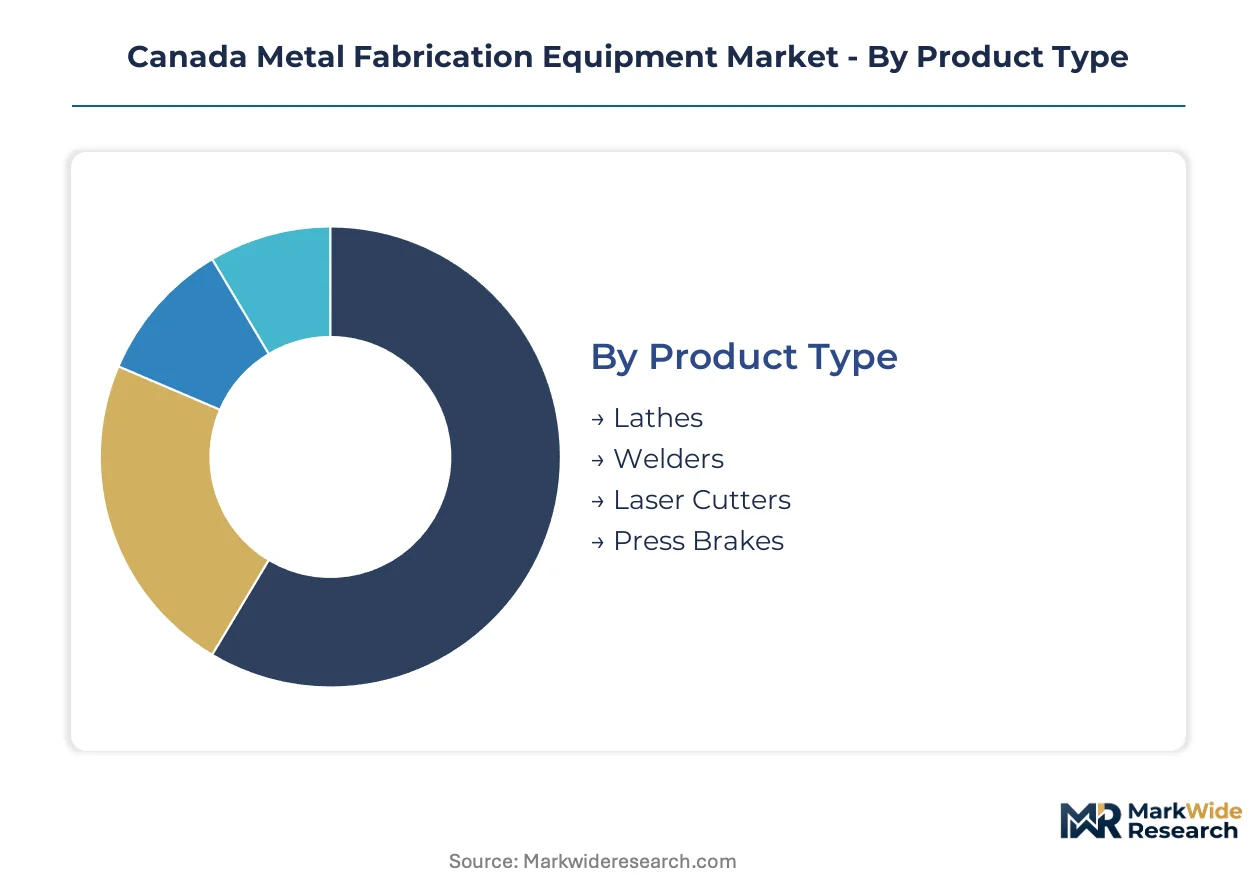
Canada's metal fabrication equipment market fragments across four distinct segmentation axes that govern procurement patterns and channel economics. Equipment specification authority concentrates with tier-one aerospace and automotive primes in Ontario and Quebec, while independent job shops across the Prairie provinces operate on different technology and financing timelines.
Product Type:
Channel flow varies sharply by equipment category: laser cutters and press brakes route through manufacturer-direct sales teams serving aerospace programs, while lathes and welders distribute through independent dealer networks with regional service footprints.
- Laser Cutters:Fiber laser platforms dominate capital expenditure among Greater Toronto Area automotive suppliers and Montreal aerospace fabricators processing thin-gauge aluminum. Battery enclosure programs for electric vehicle manufacturers are pulling 6-8 kilowatt fiber systems with automated material handling, displacing legacy CO2 installations in tier-one supplier facilities.
- Welders:Robotic welding cells anchor high-volume automotive chassis fabrication in Ontario, while manual MIG and TIG equipment serves Prairie province energy infrastructure through distributor channels. Health Canada's CSA Z432 safeguarding mandates are accelerating certified control system retrofits across existing arc welding fleets.
- Press Brakes:Servo-electric drives are displacing hydraulic systems in Ontario job shops facing energy compliance pressures and precision requirements from defense component programs.
- Lathes:Multi-axis CNC turning centers serve precision aerospace fastener and hydraulic fitting manufacturers in Quebec, with smaller bench lathes flowing through general industrial distributors.
By volume, welders lead through broad distributor penetration. By growth pace, laser cutters are climbing the fastest on aluminum-intensive aerospace and electric vehicle demand.
Technology:
Cost tier stratification separates premium automated systems from entry-level manual equipment, with mid-range CNC platforms capturing the largest addressable base among independent fabricators.
- CNC:Multi-axis machining centers displace manual equipment in high-mix, low-volume job shops across the Golden Horseshoe manufacturing belt. Programming expertise scarcity in secondary markets constrains deployment outside Montreal and Toronto clusters.
- Robotics:Welding cell integration accelerates among Ontario automotive suppliers facing labor availability constraints in precision fabrication roles.
- Plasma Cutting:Heavy structural fabricators in Alberta and Saskatchewan retain plasma systems for thick-section carbon steel, though fume extraction upgrades add compliance cost.
- Manual:Entry-level equipment persists in small job shops and vocational training institutions, with procurement concentrated through regional industrial supply distributors.
CNC technology holds the largest installed base. Robotics is gaining share fastest on labor substitution economics in high-volume production environments.
End User:
Application-specific requirements drive specification divergence: aerospace demands ±0.001 inch tolerances with full traceability, while construction tolerances relax to ±0.010 inch with cost prioritization.
- Aerospace:Montreal and Toronto tier-one suppliers mandate approved vendor lists and standardized machine platforms, locking out smaller fabricators from qualification. Fiber laser and robotic welding procurement concentrates with Bombardier and Airbus supplier networks.
- Automotive:Greater Toronto Area battery enclosure and structural aluminum fabrication is pulling fiber laser and robotic welding cell investment from tier-one suppliers.
- Construction:Heavy structural steel fabrication for commercial and infrastructure projects operates through lower-margin job shops with hybrid equipment fleets.
- Marine:Nova Scotia and British Columbia shipbuilding programs are piloting hybrid laser-arc welding for thick-section aluminum joining in defense applications.
Aerospace commands the highest equipment specification and margin levels. Automotive is expanding most quickly on electric vehicle chassis fabrication demand.
Industry Vertical:
Customer type segmentation separates capital-rich primes with multi-year framework agreements from price-sensitive independent shops purchasing on project cycles.
- Manufacturing:Durable goods producers across transportation and machinery sectors anchor equipment demand, with procurement authority consolidating among original equipment manufacturers.
- Metalworking:Independent job shops in Ontario's precision manufacturing corridor face channel compression as tier-one primes mandate approved equipment platforms.
- Energy:Alberta and Saskatchewan carbon capture and hydrogen project pipelines are creating demand for heavy structural fabrication equipment serving pressure vessel programs.
- Defense:Federal domestic content thresholds are redirecting capital investment toward Canadian-based fabrication capacity expansion for military procurement.
Manufacturing represents the largest equipment installed base. Energy is accelerating fastest on Western Canada infrastructure project commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Canada Highway and CN rail network underpin Ontario's fabrication equipment density, while the Port of Vancouver anchors British Columbia's marine and energy infrastructure demand. Provincial industrial strategies and federal procurement rules reshape capital allocation across Canada's manufacturing belt.
Ontario
Greater Toronto Area battery enclosure programs for electric vehicle manufacturers are pulling fiber laser and robotic welding cell investment from tier-one automotive suppliers. Health Canada's CSA Z432 safeguarding mandates are compelling certified control system upgrades across existing equipment fleets in Windsor and Hamilton precision manufacturing corridors.
Quebec
Montreal aerospace fabricators are standardizing on automated fiber laser platforms with automated material handling to meet Airbus and Bombardier supplier quality frameworks. The province's coordination with CSA Group on machinery safety standards is accelerating programmable safety PLC retrofits ahead of Ontario job shops.
Alberta
Carbon capture and hydrogen project pipelines are creating demand for heavy structural fabrication equipment serving pressure vessel and pipeline component programs in Calgary and Edmonton energy corridors. Federal domestic content thresholds for infrastructure contracts are redirecting capital investment toward Canadian-based fabrication capacity expansion.
British Columbia
Provincial emissions regulations restricting solvent-based cutting fluids are opening procurement channels for integrated fume extraction and fluid recycling system bundles in Vancouver and Victoria manufacturing clusters. Nova Scotia and British Columbia shipbuilding programs are piloting hybrid laser-arc welding for thick-section aluminum joining in defense applications.
Prairie Provinces
Saskatchewan and Manitoba fabricators face extended lead times on critical laser source and CNC control systems routing through German and Japanese manufacturing bases. Technical labor scarcity in multi-axis CNC programming and robotic cell integration expertise constrains expansion capacity outside Montreal and Toronto clusters.
Canada Metal Fabrication Equipment Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and regional service coverage. The vendor base concentrates around German and Japanese parent companies operating Canadian subsidiaries, with independent distributors retaining share in welding equipment and manual machine tools. Three archetypes dominate: integrated systems houses with full automation portfolios, specialized cutting equipment vendors with laser-centric offerings, and broad-line distributors with deep Prairie province service networks. Competitive moves center on multi-year framework agreements with tier-one primes and certified technician training programs to address labor scarcity.
Among Germany-based fabricators, TRUMPF Canada Inc. and DMG MORI Canada occupy positions as integrated systems anchors in Ontario and Quebec aerospace corridors. AMADA Canada Ltd. exemplifies the specialized cutting equipment archetype with its established presence in thin-gauge aluminum processing. Lincoln Electric Canada sits within the broad-line distributor tier, leveraging deep channel control across independent networks serving Prairie province energy projects.
| Leading Market Players |
|---|
| Lincoln Electric Canada |
| Sandvik Mining & Rock Solutions Canada |
| TRUMPF Canada Inc. |
| FANUC Canada |
| Bystronic Canada |
| AMADA Canada Ltd. |
| Atlas Copco Manufacturing Canada |
| Haas Automation Canada |
| DMG MORI Canada |
| Others |
Value Chain & Pricing Dynamics
Equipment utilization rates at Ontario aerospace tier-one suppliers establish scale thresholds that compress per-unit fixed cost absorption and elevate price floors for independent job shops lacking comparable throughput volumes. This capacity concentration reinforces manufacturer-direct sales channels for high-value laser and robotic systems while channeling mid-tier equipment through distributor networks with thinner margin structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement patterns, with premium tiers commanded by CSA-certified fiber laser platforms and economy tiers occupied by manual welding equipment. Price differentiation rests on certification grade alignment with Health Canada machinery directives and after-sales service bundling including technician training programs. Cost compression in standard-tier CNC press brakes is intensifying because independent Ontario job shops face margin pressure from tier-one automotive supplier consolidation. Independent Prairie province fabricators exhibit highest price sensitivity due to project-cycle purchasing patterns, while Montreal aerospace primes demonstrate lowest sensitivity given approved vendor list lock-in.
Supply Chain Analysis
Strategic stockpile preferences dominate among Alberta energy corridor fabricators securing heavy structural equipment ahead of carbon capture project ramps, while Ontario automotive suppliers maintain just-in-time coordination with TRUMPF Canada and AMADA Canada for fiber laser delivery. Critical laser source and CNC control system supply chains draw from Germany, Japan, and South Korea, exposing Canadian fabricators to extended lead times. Single-source vulnerability concentrates in fiber laser resonator components and multi-axis CNC control modules. Distribution runs through manufacturer-direct sales teams for aerospace programs and independent dealer networks serving Prairie province energy infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada metal fabrication equipment functions as a service-attach opportunity where certified technician training programs and aftermarket parts contracts expand faster than hardware revenue as CSA compliance mandates accelerate retrofit demand.
For Market Incumbents: Compound service revenue through captive technician certification programs addressing CSA Z432 safeguarding mandates while retrofitting legacy installed bases with programmable safety PLCs. Threat substitution emerges from Chinese laser manufacturers penetrating mid-tier job shop segments through aggressive financing. Channel control over independent Prairie province distributor networks represents the critical defensive lever against margin erosion. For New Entrants and Emerging Players: Lead with closed-loop coolant system integration targeting British Columbia and Ontario fabricators facing emissions regulations restricting solvent-based cutting fluids. White-space concentrates in Saskatchewan and Manitoba secondary manufacturing clusters where technical labor scarcity has constrained incumbent expansion. Go-to-market positioning through equipment-as-a-service models lowers capital barriers for price-sensitive independent job shops. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized automation integrators with proprietary robotic welding cell software and established CSA certification pathways. Long-term viability over a five-to-ten year window hinges on fiber laser platform transition completion and aluminum processing specialization. Acquisition target archetype: regional service-intensive distributors with deep technician training infrastructure. The signal to watch is federal defense procurement domestic content threshold enforcement accelerating Canadian-based capacity investment.| Strategic Initiative | Industry Significance |
|---|---|
| CSA Certification Fast-Track Program | Accelerates Health Canada machinery safety compliance for Ontario aerospace supplier networks. |
| Technician Training Infrastructure Expansion | Addresses multi-axis CNC programming scarcity constraining Prairie province fabricator growth. |
| Closed-Loop Coolant System Bundling | Captures British Columbia emissions regulation-driven procurement for fluid recycling integration. |
| Western Canada Service Network Buildout | Reduces lead time exposure from German and Japanese laser source supply chains. |
| Hybrid Laser-Arc Welding Pilot Investment | Positions for Nova Scotia and British Columbia maritime defense aluminum joining programs. |
Study Parameters
A standing panel of plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors provided ongoing calibration across primary fieldwork and secondary validation cycles. Input combined structured interviews with fabrication equipment end-users and distributor channel partners against customs trade data, Industry Canada manufacturing surveys, CSA standards documentation, and provincial emissions regulatory filings. Bottom-up equipment shipment tallies and top-down capital expenditure estimates were triangulated to anchor market sizing.
Consistency checks validated volume and value outputs against external benchmarks including machinery import statistics and regional industrial production indices. The analytical framework modeled segmentation across product type, technology tier, end-user application, and industry vertical throughout the projection horizon. CAGRs were derived from equipment replacement cycle analysis, regulatory compliance-driven retrofit demand, and electric vehicle program capital commitment trajectories. Forecast inputs incorporated fiber laser adoption curves and CSA Z432 implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained federal defense procurement localization or accelerated carbon capture project execution would require recalibration. Forecasts reflect assumptions regarding Health Canada machinery directive enforcement continuity and aluminum-intensive aerospace program stability. Revision becomes warranted when German or Japanese laser source supply chain disruption crosses operational continuity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market