
 Industrial Parts Feeders Market | 2026-2036
Industrial Parts Feeders Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Parts Feeders Market Insights
Smart sensor integration and IoT-enabled predictive maintenance is tilting the technology stack toward data-driven feeding architectures. Performance Feeders, Inc. leverages embedded diagnostics to reduce unplanned downtime in high-speed automotive cells. ATS Automation Tooling Systems Inc. anchors its position through deep backward integration into feeder control software and vision systems. Syntron Material Handling competes on brute-force electromechanical scale, dominating bulk-material handling configurations where throughput trumps precision.
Industrial parts feeders are automated material handling devices that orient, singulate, and transport discrete components to downstream assembly or packaging stations using controlled vibration, centrifugal force, or pneumatic actuation, typically achieving feed rates from tens to thousands of parts per minute depending on geometry and surface finish. Their primary industrial purpose is to eliminate manual loading, reduce cycle time variance, and ensure repeatable presentation orientation for robotic pick-and-place operations. Vibratory feeders retain the largest installed base across automotive powertrain and electronics connector applications, though custom feeders command the richest margin pools where tool-less changeover and quick-release bowl designs justify engineering premiums. Optical technology is displacing legacy mechanical orientation methods in pharmaceutical tablet and capsule feeding, where vision-based rejection of damaged or misaligned units replaces hard tooling.
ISO 12100 machinery risk assessment and IEC 60204-1 electrical safety standards govern feeder design and installation across EU manufacturing sites, forcing retrofit upgrades on pre-2010 equipment. The US OSHA machinery guarding regulations and FDA cGMP requirements for pharmaceutical contact surfaces shape North American product specifications and material certifications. Stakeholders must monitor how the EU Machinery Regulation revision and emerging AI Act conformity obligations will recalibrate control system architectures and documentation burdens for electromechanical and optical feeder categories.
Market Dynamics
Electrification of automotive powertrains is restructuring demand for precision feeding systems, as battery cell assembly and electric motor manufacturing require higher throughput tolerances than legacy internal combustion component handling.
Growth Catalysts
- IEC 60204-1 machinery safety standards:European manufacturers are retrofitting pre-2010 feeder installations to meet tightened electrical safety protocols, generating replacement demand across Germany, Italy, and France.
- Optical-sensor-integrated linear feeders:Electronics contract manufacturers in China's Yangtze River Delta are retrofitting legacy lines with vision-based orientation systems for micro-connector handling.
- Pharmaceutical tablet feeding:Vision-based rejection systems for damaged or misaligned units are replacing hard tooling in FDA-regulated oral solid dosage production.
Market Restraints
- Specialized bowl fabrication:Custom tooled vibratory bowls require 8-12 week lead times from concentrated tool-and-die shops in the US Midwest and southern Germany.
- Copper and rare-earth magnet costs:Electromechanical drive coils depend on copper windings and neodymium magnets, exposing feeder OEMs to commodity price swings.
- ISO 12100 compliance documentation:Risk assessment protocol requirements add engineering hours to EU-bound shipments, compressing margins on standard catalog units.
Strategic Opportunities
- Tool-less quick-release bowl designs:Automotive tier-1 suppliers are specifying changeover-under-15-minutes architectures to support mixed-model electric powertrain lines.
- EU AI Act conformity pathways:Vision-system feeders with embedded classification algorithms face emerging documentation obligations that first-movers can productize as competitive differentiation.
- India's electronics manufacturing clusters:Noida and Sri City contract manufacturers are greenfield-deploying feeders for smartphone component assembly, bypassing legacy mechanical orientation entirely.
Industry Challenges
- Controls software integration:Feeder OEMs must maintain compatibility with Rockwell, Siemens, and Mitsubishi PLC ecosystems simultaneously, fragmenting R&D resources.
- Vision system calibration expertise:Optical feeder deployments require machine vision specialists that automotive and pharmaceutical end-users rarely retain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Parts Feeders Market |
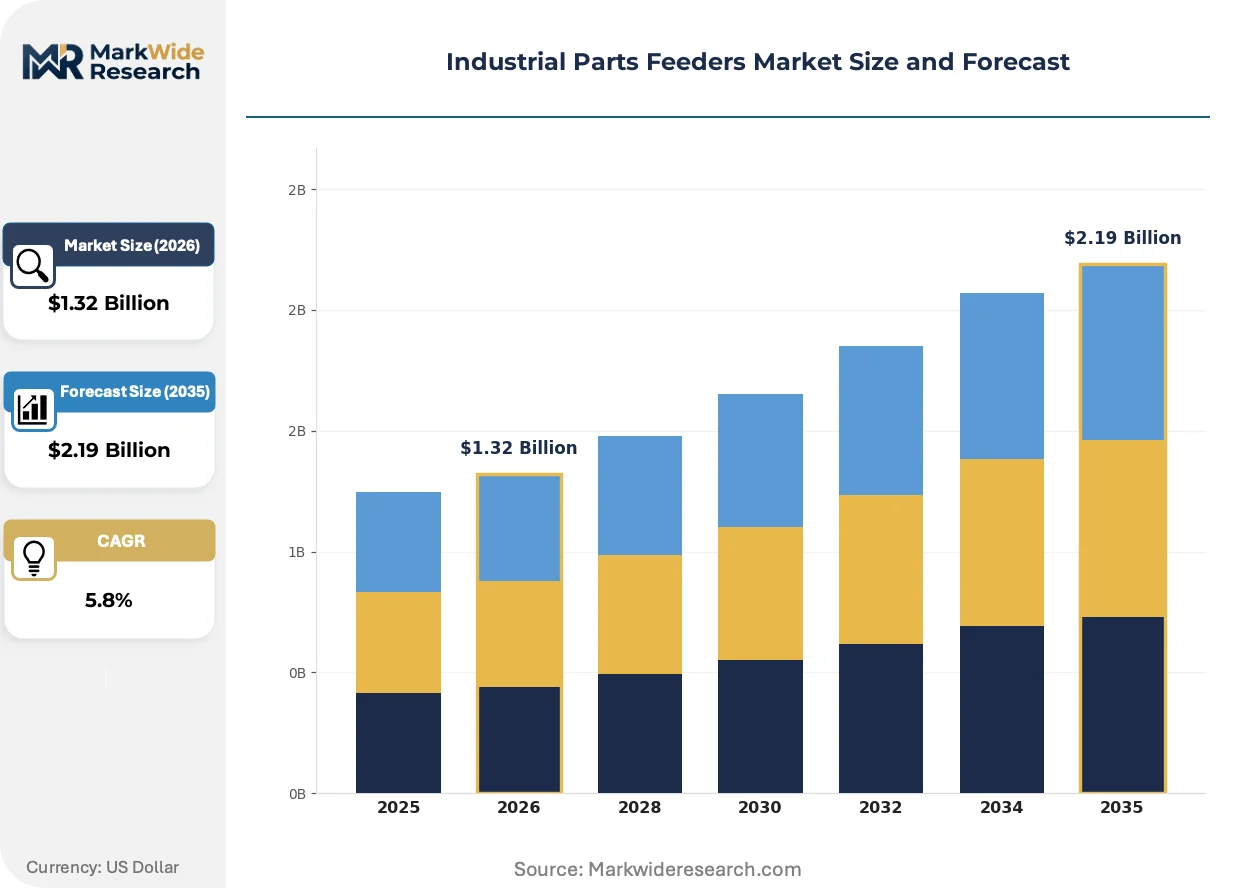
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibratory Feeders, Linear Feeders, Centrifugal Feeders, Custom Feeders Technology: Electromechanical, Pneumatic, Mechanical, Optical End User: Automotive, Electronics, Packaging, Pharmaceuticals Installation: Automated, Manual, Semi-Automated, Portable |
| Companies Covered | Performance Feeders, Inc., ATS Automation Tooling Systems Inc., Syntron Material Handling, Fortville Feeders, Hoosier Feeder Company, Graco Inc., Orientech Automation Solutions Inc., RNA Automation Ltd., Cleveland Vibrator Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Parts Feeders Market Trends and Innovations
Feeder architectures are pivoting from isolated electromechanical units to data-connected nodes within plant-wide manufacturing execution systems, with predictive maintenance algorithms and edge-based orientation verification becoming baseline expectations.
AI-driven adaptive vibration control is collapsing the traditional trade-off between feed rate and part damage rates. Pharmaceutical packagers in Switzerland and Germany are deploying machine-learning-tuned drive frequencies that self-adjust to tablet coating variations in real time. The technology compresses the specification gap between dedicated pharmaceutical feeders and general-purpose industrial units.
REACH substance restrictions and the EU Machinery Regulation revision are forcing material recertification across feeder contact surfaces. Stainless steel 316L specifications for pharmaceutical applications now require documented absence of SVHC candidates, extending supplier qualification timelines. German and Italian OEMs are responding with captive metallurgical testing to preserve shipment velocity.
Buyer consolidation among automotive tier-1 suppliers is compressing procurement cycles and unbundling after-sales service contracts. Continental, Bosch, and Denso are negotiating feeder purchases on three-year enterprise agreements with penalty clauses for unplanned downtime, shifting risk to equipment vendors. The model is most visible in German and Japanese powertrain component plants where line stoppage costs exceed six figures hourly.
Industrial Parts Feeders Market Segmentation
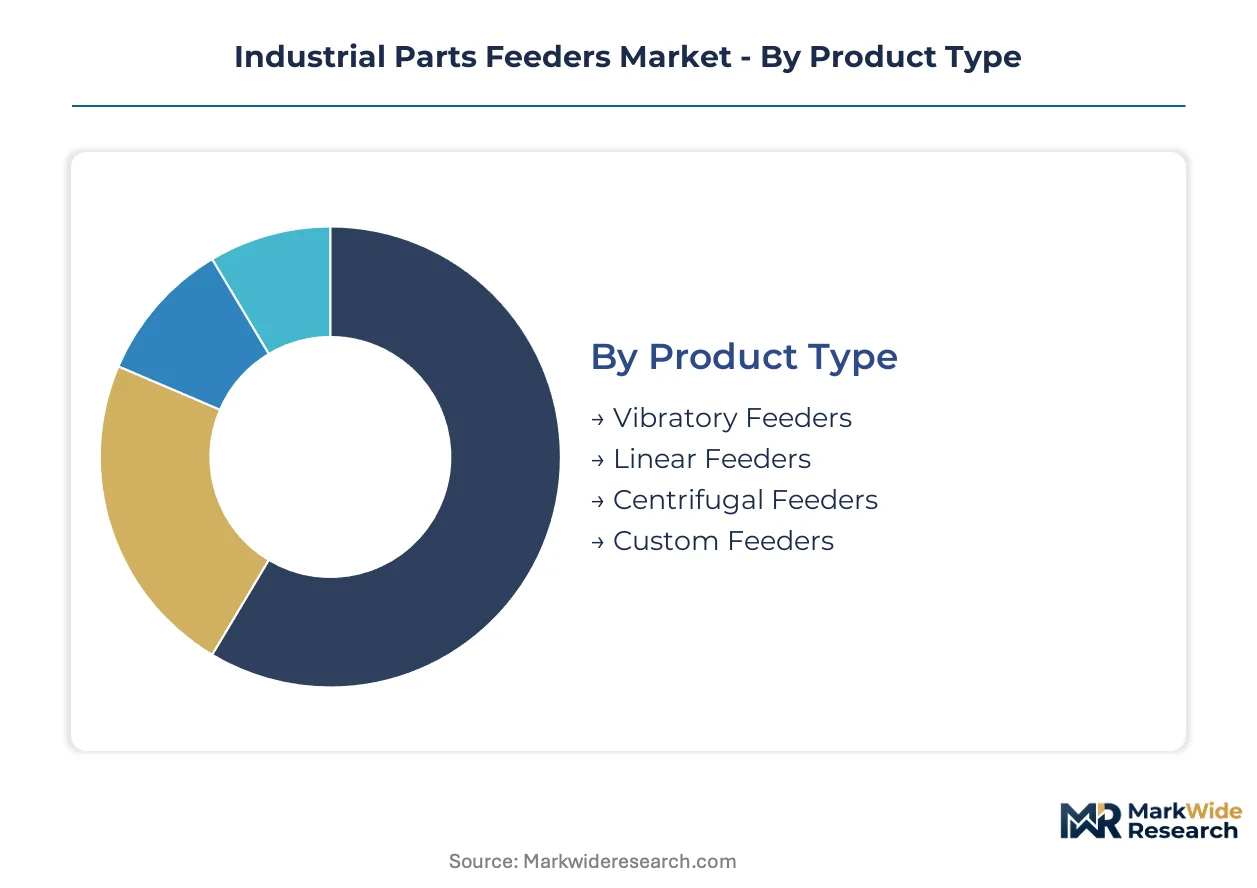
Segmentation in industrial parts feeders reveals how technology choices map directly to throughput requirements, precision tolerances, and regulatory exposure across discrete manufacturing environments. Product architecture, drive mechanism, end-use application, and deployment mode each create distinct margin profiles and competitive dynamics.
Product Type:
Feeder architectures span from standardized electromechanical platforms to engineered-to-order solutions, with selection driven by part geometry complexity, changeover frequency, and total cost of ownership calculations.
- Vibratory Feeders:Bowl and linear configurations use electromagnetic or piezoelectric drives to impart controlled vibration for part orientation and transport. Automotive powertrain plants in Germany and Japan deploy these for electric motor lamination stacks and battery cell components where feed rates exceed 200 parts per minute.
- Linear Feeders:Track-based systems provide precise singulation and spacing for downstream robotic handling, with China's Yangtze River Delta electronics manufacturers retrofitting legacy lines with optical-sensor-integrated variants for micro-connector applications.
- Centrifugal Feeders:Rotating disk mechanisms leverage centrifugal force for high-speed bulk feeding of symmetrical components in packaging operations.
- Custom Feeders:Engineered solutions with tool-less quick-release bowl designs command premium pricing where automotive tier-1 suppliers require changeover-under-15-minutes for mixed-model electric powertrain lines.
Established volume favors vibratory feeders; emerging adoption favors custom feeders.
Technology:
Drive and control methodologies differentiate on energy efficiency, precision, and data integration capabilities, with migration paths from purely mechanical to sensor-augmented architectures.
- Electromechanical:Electromagnetic coil drives with variable frequency control dominate installed base across automotive and electronics applications, though copper winding and neodymium magnet costs expose OEMs to commodity volatility.
- Pneumatic:Compressed air actuation suits explosive environments and cleanroom pharmaceutical operations where electrical spark risks are prohibitive.
- Mechanical:Cam-driven and gravity-fed systems persist in low-speed, high-volume bulk material handling where precision requirements are relaxed.
- Optical:Vision-based orientation and rejection systems are displacing hard tooling in FDA-regulated pharmaceutical tablet feeding and quality-critical electronics assembly.
Electromechanical retains the broadest installed base; optical is climbing the fastest on AI-enabled adaptive control adoption.
End User:
Industry-specific throughput demands, regulatory frameworks, and automation maturity shape feeder specification and procurement patterns.
- Automotive:Electric powertrain assembly lines in Germany and Japan require precision feeders for battery cell stacking, motor lamination handling, and inverter component placement with sub-millimeter tolerances.
- Electronics:Contract manufacturers in China's Yangtze River Delta and India's Noida and Sri City clusters deploy feeders for smartphone component assembly, with greenfield sites bypassing legacy mechanical orientation entirely.
- Packaging:High-speed container and cap feeding operations prioritize throughput over precision, favoring centrifugal and vibratory configurations.
- Pharmaceuticals:FDA cGMP and Swissmedic requirements for oral solid dosage production drive vision-based tablet feeding with documented absence of REACH SVHC candidates in contact surfaces.
Automotive commands the highest engineering premiums; pharmaceuticals shows the steepest technology upgrade trajectory.
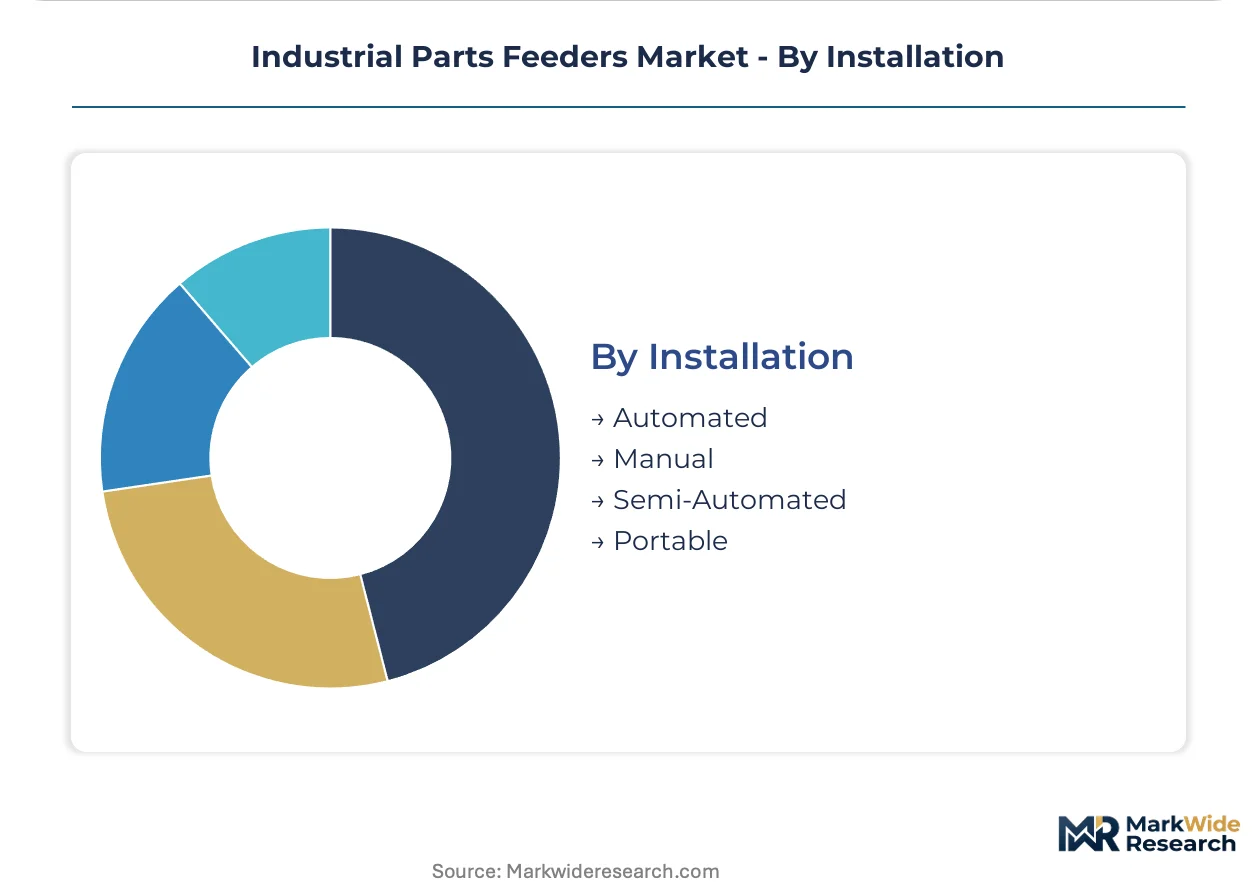
Installation:
Deployment mode reflects capital intensity, line flexibility requirements, and workforce availability across manufacturing footprints.
- Automated:Fully integrated feeders with PLC connectivity to Rockwell, Siemens, or Mitsubishi ecosystems dominate high-volume automotive and electronics lines where unplanned downtime costs exceed six figures hourly.
- Manual:Operator-loaded systems persist in low-volume specialty manufacturing and prototype environments.
- Semi-Automated:Hybrid configurations balance labor cost and capital investment for mid-tier contract manufacturers.
- Portable:Mobile feeder units support job-shop environments and rapid line reconfiguration needs.
Automated installations dominate revenue concentration; portable configurations are gaining share fastest in flexible manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive tier-1 suppliers and electronics contract manufacturers concentrate procurement authority in Germany, Japan, and China, with regulatory compliance costs reshaping vendor selection criteria across these buyer archetypes.
Germany
Electric powertrain assembly lines at Continental and Bosch facilities drive precision feeder demand for battery cell stacking and motor lamination handling. IEC 60204-1 machinery safety standards and ISO 12100 risk assessment protocols force retrofit investments on pre-2010 equipment. The Baden-Württemberg and Bavaria industrial corridors host concentrated feeder deployments for automotive powertrain automation.
China
Electronics contract manufacturers in the Yangtze River Delta retrofit legacy lines with optical-sensor-integrated linear feeders for micro-connector handling. MIIT industrial automation directives and GB standards for machinery safety tighten compliance documentation for EU-bound exports. Noida and Sri City clusters in India attract greenfield feeder deployments as contract manufacturers bypass legacy mechanical orientation entirely.
Japan
Denso and Toyota-affiliated suppliers specify sub-millimeter tolerance feeders for electric motor manufacturing and inverter component placement. METI industrial competitiveness programs subsidize smart factory retrofits including IoT-enabled predictive maintenance architectures. The Chubu region around Nagoya anchors precision feeder demand for hybrid and electric vehicle powertrains.
United States
OSHA machinery guarding regulations and FDA cGMP requirements for pharmaceutical contact surfaces shape feeder specifications across automotive and life sciences manufacturing. The US Midwest retains concentrated tool-and-die capacity for custom vibratory bowl fabrication with 8-12 week lead times. Michigan and Ohio automotive plants deploy feeders for mixed-model electric powertrain lines requiring changeover-under-15-minutes architectures.
Switzerland
Pharmaceutical packagers deploy machine-learning-tuned vibratory drive frequencies that self-adjust to tablet coating variations in real time. Swissmedic requirements for oral solid dosage production and REACH SVHC substance restrictions extend supplier qualification timelines for contact surface materials. The Basel pharmaceutical manufacturing cluster drives premium-tier demand for vision-based tablet feeding systems.
Industrial Parts Feeders Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven electromechanical manufacturers, precision automation integrators, and vision-system specialists occupy distinct competitive positions. The market fragments across three strategic archetypes: brute-force bulk material handlers, software-anchored automation platforms, and custom-engineered precision specialists. Dominant competitive moves include backward integration into feeder control software and captive metallurgical testing to preserve shipment velocity under REACH compliance timelines.
Among North American automation specialists, Performance Feeders, Inc. and ATS Automation Tooling Systems Inc. occupy positions emphasizing embedded diagnostics and control software integration respectively. Syntron Material Handling represents the scale-driven electromechanical archetype dominating bulk-material configurations. These three companies exemplify how competitive differentiation converges on predictive maintenance capabilities, regulatory documentation depth, and changeover speed specifications rather than hardware performance alone.
| Leading Market Players |
|---|
| Performance Feeders, Inc. |
| ATS Automation Tooling Systems Inc. |
| Syntron Material Handling |
| Fortville Feeders |
| Hoosier Feeder Company |
| Graco Inc. |
| Orientech Automation Solutions Inc. |
| RNA Automation Ltd. |
| Cleveland Vibrator Company |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp freight corridor's container cost dynamics compress margins for feeder OEMs shipping electromechanical drive assemblies from German tool-and-die shops to Yangtze River Delta electronics plants, while simultaneously amplifying price differentiation between premium custom-engineered units and catalog-standard vibratory platforms.
Pricing Analysis
Cost-plus contracts with copper and neodymium magnet indexation dominate procurement between automotive tier-1 suppliers and feeder OEMs. Three-tier pricing structure across premium, standard, and economy levels separates tool-less quick-release bowl designs from fixed-configuration vibratory units from basic electromagnetic platforms. Pricing pressure stems from buyer consolidation among Continental, Bosch, and Denso negotiating enterprise agreements with downtime penalty clauses. Contract manufacturers in India's Noida cluster exhibit highest price sensitivity; Swiss pharmaceutical packagers show least.
Supply Chain Analysis
Supplier-financing facilities extended by Syntron Material Handling and ATS Automation Tooling Systems to Midwest tool-and-die shops alleviate 8-12 week bowl fabrication bottlenecks. Electromechanical drive coil production concentrates in Germany, China, and Japan. Copper windings, neodymium magnets, and optical sensor arrays constitute critical input dependencies. Single-source vulnerability runs through concentrated US Midwest bowl fabrication capacity. Distribution runs through direct OEM sales teams for automotive tier-1 accounts and regional distributor networks for mid-tier electronics contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: IEC 60204-1 and ISO 12100 compliance documentation burdens create switching costs that lock in incumbent feeder OEMs with established EU certification pathways.
For Market Incumbents: Entrench position through captive metallurgical testing capabilities that preserve shipment velocity under REACH SVHC timelines, and backward integration into feeder control software to maintain simultaneous Rockwell, Siemens, and Mitsubishi PLC compatibility. The threat of vision-system specialists with AI-enabled adaptive vibration algorithms demands defensive R&D allocation toward edge-based orientation verification. For New Entrants and Emerging Players: Pursue white-space opportunities in India's greenfield electronics manufacturing clusters at Noida and Sri City, where contract manufacturers bypass legacy mechanical orientation entirely. Optical-sensor-integrated linear feeders for micro-connector handling represent the most penetrable segment. Go-to-market angle: machine-vision-as-a-service partnerships that eliminate end-user calibration expertise gaps. For Investors and Strategic Acquirers: The EU Machinery Regulation revision reshapes the acquisition landscape by elevating documentation-heavy feeder OEMs with established conformity assessment pathways above asset-light competitors. Long-term viability centers on 5-10 year regulatory compliance moats rather than hardware performance differentiation. Target acquisition archetype: precision automation integrators with captive vision system calibration expertise. Signal to watch: METI subsidy disbursement velocity for Japanese smart factory retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feeder Control Software | ATS Automation Tooling Systems anchors competitive position through proprietary PLC ecosystem compatibility. |
| Captive Metallurgical Testing Investment | German and Italian OEMs preserve REACH SVHC shipment velocity against extended supplier qualification timelines. |
| Tool-less Quick-release Bowl Design Development | Automotive tier-1 suppliers specify changeover-under-15-minutes architectures for mixed-model electric powertrain lines. |
| Machine Vision-as-a-Service Partnership | Emerging entrants eliminate pharmaceutical and automotive end-user calibration expertise gaps through outsourced deployment. |
| EU AI Act Conformity Pathway Productization | First-movers in vision-system feeders with embedded classification algorithms capture competitive differentiation through documentation depth. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and feeder control software developers and secondary validation through SEC 10-K filings, customs trade data, and IEC standard revision documentation anchors the qualitative findings. Bottom-up unit deployment estimates triangulate against top-down manufacturing automation capex allocations across automotive, electronics, and pharmaceutical end-use segments.
Calibration against historical feeder shipment patterns by product architecture, drive mechanism, and installation mode shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include feeder type, technology category, end-use industry, and geographic production cluster. CAGRs derive from fitted growth curves applied to disclosed automation equipment procurement cycles. Industry-specific forecast inputs encompass electric vehicle powertrain transition timelines and pharmaceutical oral solid dosage capacity expansion announcements.
Sensitivities concentrate around copper and rare-earth magnet commodity volatility, EU Machinery Regulation revision implementation schedules, and automotive tier-1 supplier consolidation velocity. Forecasts reflect documented assumptions regarding regulatory compliance cost trajectories and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Loader Bucket Attachments Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market