
 Smart Garage Door Opener and Controller Market | 2026-2036
Smart Garage Door Opener and Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Garage Door Opener and Controller Market Insights
Homeowner buying patterns are restructuring as single-family residential demand fragments across DIY installers, smart home integrators, and new construction developers. The Chamberlain Group LLC leverages its MyQ ecosystem to control connected garage access across North American households. Hormann Group anchors European demand through industrial-grade automation scaled down for residential use. Vivint, Inc. competes by bundling garage controllers into monitored security subscriptions.
Smart garage door openers and controllers are electromechanical devices integrating motor drives, wireless transceivers, and position sensors to enable remote operation, status monitoring, and automated scheduling of overhead and sectional door systems. Units typically incorporate rolling-code encryption, torque-sensing obstruction detection, and dual-band Wi-Fi or Bluetooth Low Energy connectivity for integration with home automation platforms. Wi-Fi Enabled products dominate volume due to cloud connectivity and voice assistant compatibility, while Smart Sensors command margin pools through predictive maintenance and environmental monitoring add-ons. IoT technology leads installation growth as interoperability standards consolidate around Matter protocol adoption.
FCC Part 15 rules govern radio frequency emissions for wireless garage controllers sold in the United States, while UL 325 mandates entrapment protection and force limitation on motorized door operators. CE marking requirements under EU machinery directives shape European product design and market access protocols. Stakeholders must monitor evolving cybersecurity labeling programs and interoperability certification timelines as regulatory scope expands beyond physical safety into data privacy and network resilience.
Market Dynamics
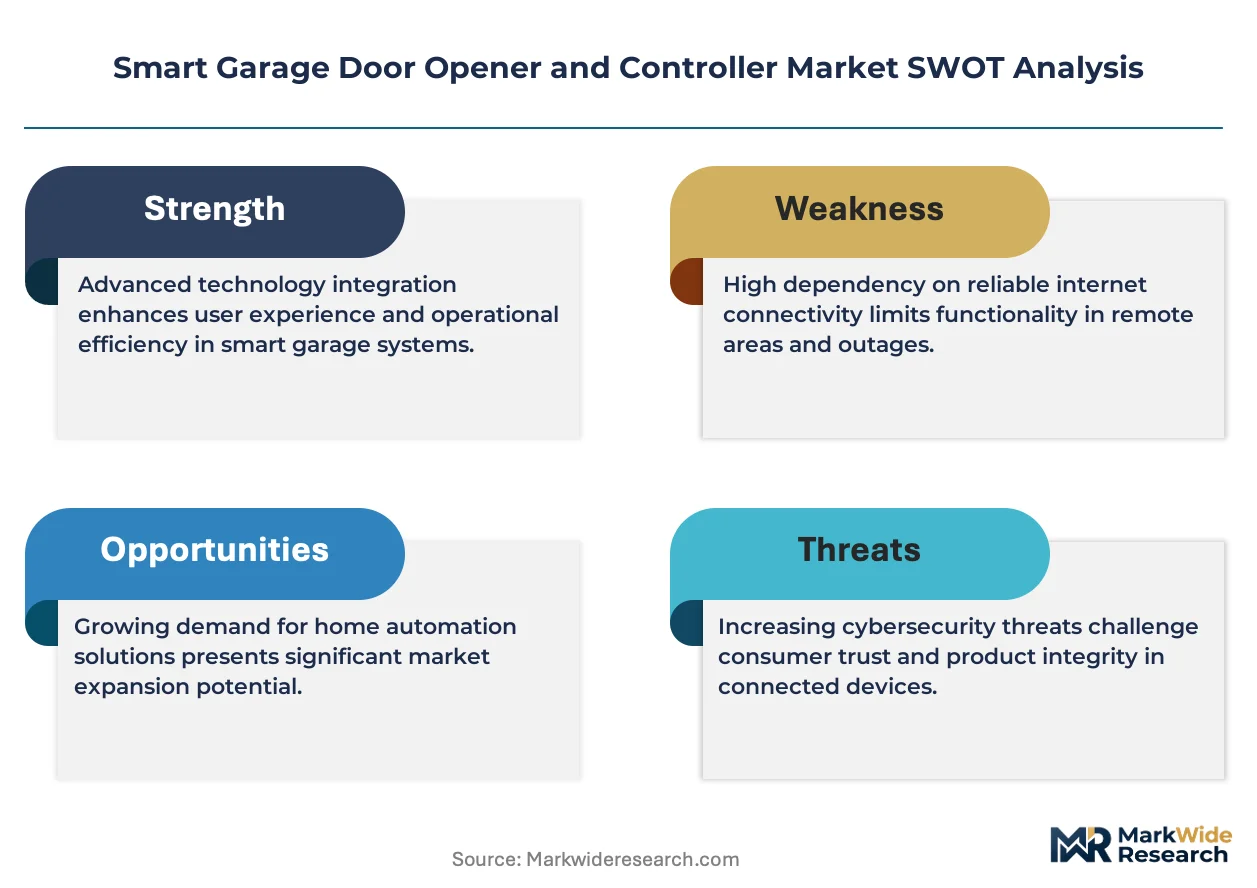
The Smart Garage Door Opener and Controller Market is being fundamentally restructured by Matter protocol consolidation, which is collapsing proprietary ecosystem walls and forcing hardware manufacturers toward interoperable chipsets and unified firmware stacks.
Growth Catalysts
- UL 325 Safety Standard Evolution:Updated entrapment protection mandates in the United States are accelerating replacement cycles for legacy motorized operators as homeowners face insurance compliance deadlines.
- Single-Family Residential Fragmentation:DIY installers, smart home integrators, and new construction developers are creating parallel demand channels that expand addressable household penetration beyond traditional retrofit markets.
- Voice Assistant Integration:Amazon Alexa and Google Home compatibility is absorbing garage controllers into centralized home automation routines, driving attach rates among ecosystem-committed buyers.
Market Restraints
- Semiconductor Supply Concentration:Wi-Fi and Bluetooth Low Energy chip fabrication concentrates in Taiwanese foundries, exposing manufacturers to geopolitical disruption and allocation constraints.
- Cybersecurity Labeling Friction:Emerging FCC cybersecurity certification timelines are extending product launch windows and increasing pre-market testing expenditures for smaller vendors.
- Copper and Rare Earth Magnet Costs:Motor drive assemblies face input price volatility as permanent magnet materials fluctuate with export restriction policies in supplier nations.
Strategic Opportunities
- Texas Suburban Cluster Penetration:New construction velocity in Dallas-Fort Worth and Houston exurbs offers embedded installation partnerships with regional homebuilders before retail competition establishes.
- Predictive Maintenance Sensor Bundles:Environmental monitoring and torque degradation algorithms create recurring revenue streams through subscription firmware tiers attached to hardware sales.
- IRA Energy Efficiency Incentives:Smart home device tax credits under the Inflation Reduction Act are compressing payback periods for buyers evaluating connected garage upgrades.
Industry Challenges
- Matter Certification Timeline Compression:Interoperability testing backlog at authorized labs is delaying product launches as manufacturers queue for protocol compliance validation.
- Legacy Radio Frequency Integration:Rolling-code encryption migration from proprietary 300-400 MHz systems to dual-band Wi-Fi architectures requires firmware engineering capacity that concentrates at larger OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Garage Door Opener and Controller Market |
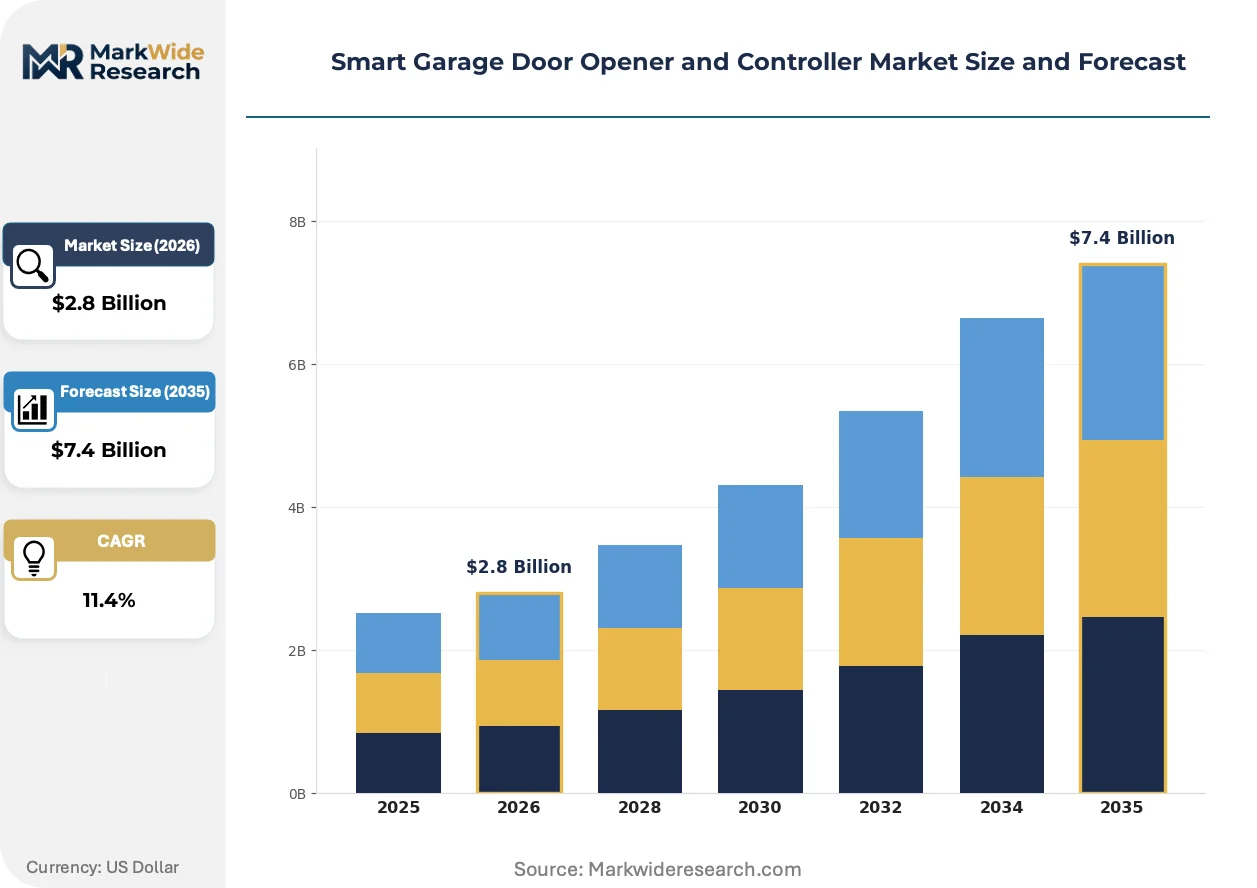
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Enabled, Bluetooth Enabled, Smart Sensors, Remote Controls Technology: IoT, Cloud-Based, Home Automation, Mobile App Controlled End User: Residential, Commercial, Industrial, Contractors Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | The Chamberlain Group LLC, The Genie Company, Hormann Group, Vivint, Inc., Asante Inc., Nexx Garage, Meross Technology Limited, Marantec Marienfeld GmbH & Co. KG, LiftMaster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Garage Door Opener and Controller Market Trends and Innovations
Three distinct vectors are compressing product development cycles and redrawing competitive boundaries across hardware, software, and distribution layers simultaneously.
Edge computing architectures are absorbing garage controller intelligence locally, reducing cloud dependency for latency-critical safety functions like obstruction detection. New construction developers in Florida are specifying on-device processing to meet hurricane-resilient connectivity requirements. This shift is absorbing margin from subscription-dependent business models toward silicon-integrated value capture.
FCC Part 15 equipment authorization rules are tightening emission testing documentation for Wi-Fi enabled garage controllers sold in the United States. Manufacturers must now submit expanded spectral analysis data, extending pre-market approval timelines by several months. Mid-tier vendors without dedicated regulatory affairs staff are outsourcing compliance to specialized testing houses in California and Texas.
Smart home integrators are displacing big-box retail as the primary influence channel for premium garage controller selection among affluent suburban homeowners. These installers bundle garage access into whole-home automation specifications, capturing specification authority before end-users evaluate individual brands. This channel rotation is most pronounced in California's Silicon Valley and Orange County markets where integrator density exceeds national averages.
Smart Garage Door Opener and Controller Market Segmentation
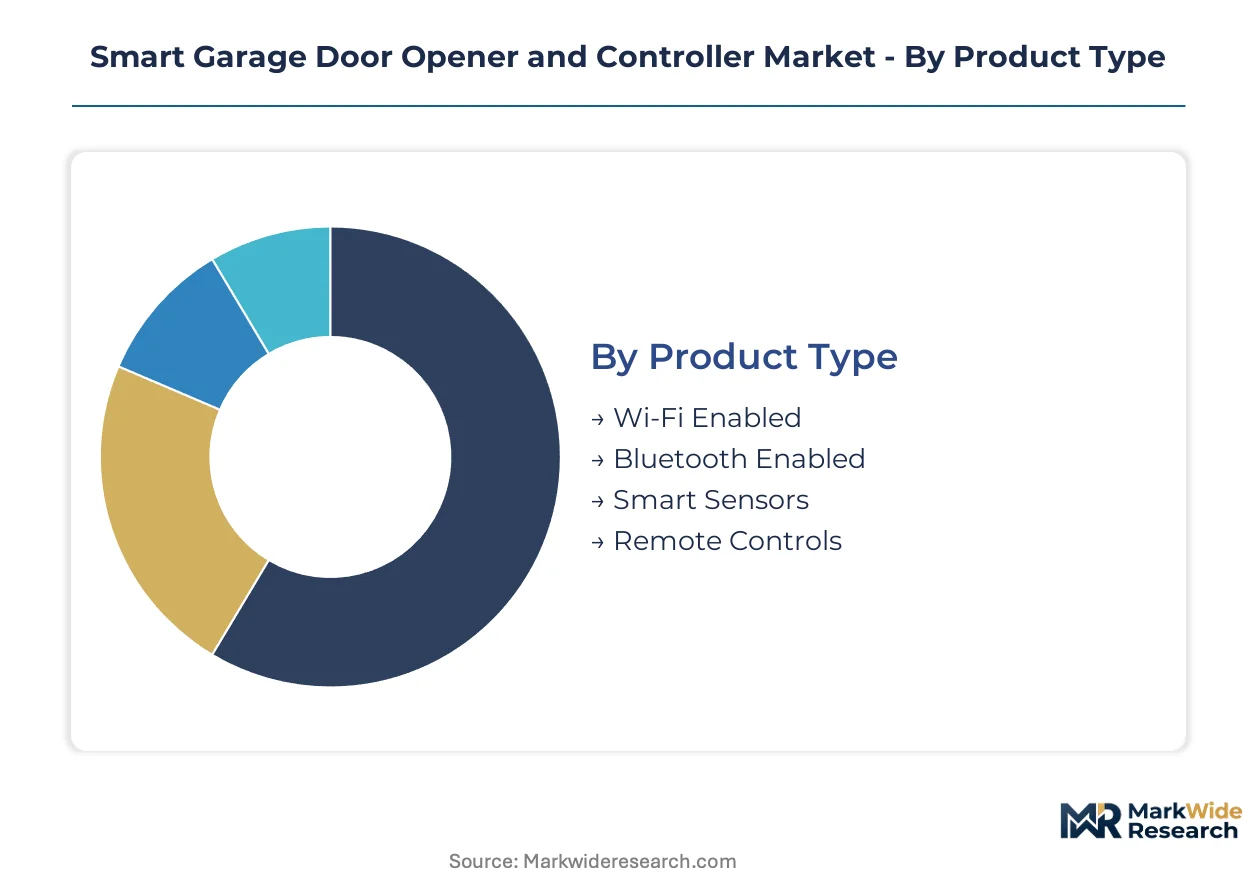
Smart garage door opener and controller manufacturers face divergent engineering requirements across connectivity protocols, deployment environments, and procurement channels. Segmentation reveals where standardization yields scale economies versus where customization commands premium positioning.
Product Type:
Standardization dominates at the connectivity layer while modular sensor architectures enable tiered feature differentiation.
- Wi-Fi Enabled:Dual-band 2.4/5 GHz transceivers integrate cloud gateways for voice assistant compatibility and remote status monitoring. Demand clusters among suburban homeowners in Texas and Florida seeking hurricane-resilient connectivity independent of local network infrastructure.
- Smart Sensors:Torque degradation algorithms and environmental monitors enable predictive maintenance subscriptions. These units capture margin pools in California's Silicon Valley where integrator-specified whole-home automation bundles predominate.
- Bluetooth Enabled:Low Energy 5.0 protocols suit proximity-based operation without router dependency.
- Remote Controls:Rolling-code 300-400 MHz transmitters persist as backup interfaces for legacy system compatibility.
Mature deployment sits with Remote Controls. Newer deployment is concentrated in Smart Sensors.
Technology:
Architecture decisions determine whether intelligence resides at the edge, in cloud relays, or distributed across home automation hubs.
- IoT:Matter protocol interoperability consolidates previously fragmented ecosystem integrations. Edge computing absorption of safety-critical functions reduces latency for obstruction detection while meeting FCC Part 15 emission constraints through localized processing.
- Cloud-Based:Firmware-over-the-air update pipelines and usage analytics platforms generate recurring revenue attachment. These systems face cybersecurity labeling friction under emerging FCC certification timelines that extend pre-market approval windows.
- Home Automation:Hub-agnostic operation via standardized APIs enables integrator specification authority.
- Mobile App Controlled:Native iOS and Android interfaces with biometric authentication layers address UL 325 compliance documentation.
Volume concentration rests with Cloud-Based systems. Steepest expansion trajectory belongs to IoT architectures.
End User:
Procurement authority fragments across DIY retail selection, integrator specification, and developer pre-installation decisions.
- Residential:Single-family homeowners in Dallas-Fort Worth and Houston exurbs drive new construction embedded installation partnerships. This segment splits between retrofit retail purchasers and new build specifications where regional homebuilders lock in supplier relationships before occupancy.
- Commercial:Multi-tenant parking facilities and retail loading docks require centralized access logging and scheduled operation protocols. Demand concentrates in Florida's commercial construction corridors where hurricane-rated equipment mandates shape procurement.
- Industrial:High-cycle overhead door systems in logistics facilities specify heavy-duty motor drives with continuous duty ratings.
- Contractors:Electrical and garage door installation trades source through wholesale distributors with volume pricing tiers.
Established penetration characterizes Industrial applications. Residential retrofit channels are climbing the fastest.
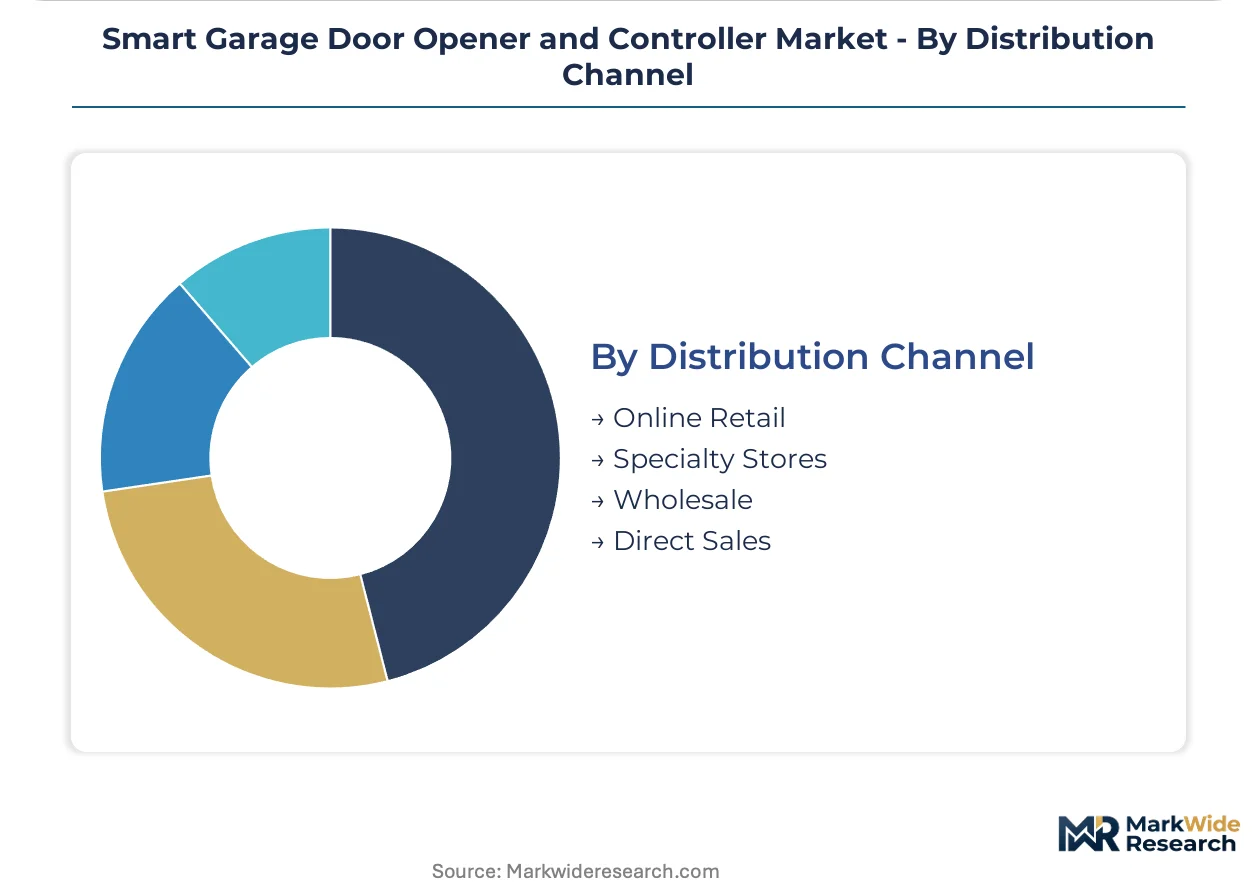
Distribution Channel:
Channel selection determines margin capture, specification influence, and installation support obligations.
- Online Retail:Amazon and direct-to-consumer platforms enable DIY installer self-selection with video tutorial support. These channels absorb volume in price-sensitive segments while surrendering specification authority to integrator and contractor channels.
- Specialty Stores:Smart home boutiques and security system dealers bundle garage controllers into monitored service subscriptions. California integrator density exceeds national averages here, capturing affluent suburban households before brand evaluation occurs.
- Wholesale:Regional distributors serve contractor trades with inventory financing and same-day availability.
- Direct Sales:Manufacturer field teams engage national homebuilders and property management portfolios.
Traditional strength persists in Wholesale. Direct Sales partnerships with Texas and Florida developers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing in China and copper refining in Chile supply motor assemblies for garage automation hardware worldwide. Regional demand concentrates where single-family construction velocity intersects with smart home infrastructure buildout. Regulatory frameworks diverge sharply between FCC-governed North American markets and CE-marked European jurisdictions.
United States
Suburban expansion in Dallas-Fort Worth and Houston exurbs drives embedded installation partnerships with regional homebuilders. FCC Part 15 equipment authorization rules tighten emission testing documentation, extending pre-market approval timelines. California's Silicon Valley and Orange County markets exhibit integrator density exceeding national averages, capturing specification authority before end-user brand evaluation.
Germany
Industrial-grade automation expertise scales down into residential garage systems through precision engineering clusters. CE marking requirements under EU machinery directives shape product design protocols for European market access. North Rhine-Westphalia and Baden-Württemberg manufacturing corridors concentrate component fabrication for continental distribution.
China
Domestic smart home adoption accelerates through MIIT-coordinated IoT standardization and dual carbon goals driving energy-efficient motor designs. GB standards compliance shapes local product specifications distinct from Western regulatory frameworks. Yangtze River Delta electronics manufacturing hubs supply Wi-Fi and Bluetooth Low Energy chipsets for global garage controller assembly.
United Kingdom
Post-Brexit regulatory divergence creates parallel certification pathways for radio equipment alongside retained EU machinery directives. London and Southeast England smart home retrofit demand concentrates among affluent homeowners pursuing whole-home automation integration. Midlands manufacturing bases serve as distribution nodes for European continental supply chains.
Canada
ISED radio equipment certification runs parallel to FCC frameworks, creating streamlined North American market access for qualified manufacturers. Ontario and Quebec residential construction corridors absorb Wi-Fi enabled garage controllers through new build specifications and retail retrofit channels. Health Canada product safety oversight aligns with UL 325 entrapment protection standards for cross-border equipment harmonization.
Smart Garage Door Opener and Controller Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue voice assistant integration and predictive maintenance subscriptions. The vendor base stratifies across three tiers: diversified industrial automation conglomerates with residential product lines, pure-play smart home specialists, and security system bundlers capturing recurring revenue attachment. Two strategic archetypes dominate: ecosystem integrators leveraging proprietary cloud platforms, and hardware-agnostic manufacturers adopting Matter protocol interoperability. Competitive moves concentrate on M&A absorption of sensor technology startups and capacity expansion into Texas and Florida developer partnerships.
Within the ecosystem-integrator tier, The Chamberlain Group LLC and Vivint, Inc. exemplify divergent strategic positioning. Chamberlain anchors North American volume through MyQ cloud infrastructure penetration. Vivint occupies the security-bundling vector, embedding garage controllers within monitored service subscriptions. Hormann Group represents European industrial heritage scaled into residential automation, while Meross Technology Limited and Nexx Garage sit within the hardware-agnostic cohort pursuing cross-platform compatibility. These five entities collectively illustrate the competitive tension between proprietary ecosystem lock-in and open-protocol interoperability that the Matter standard is collapsing.
| Leading Market Players |
|---|
| The Chamberlain Group LLC |
| The Genie Company |
| Hormann Group |
| Vivint, Inc. |
| Asante Inc. |
| Nexx Garage |
| Meross Technology Limited |
| Marantec Marienfeld GmbH & Co. KG |
| LiftMaster |
| Others |
Pricing and Supply Chain Analysis
Rare earth magnet costs from Chinese processing facilities cascade through motor drive assemblies into three-tier pricing structures across premium, standard, and economy levels, with copper price volatility from Chilean refineries compressing margins at the mid-market tier where Texas homebuilders negotiate volume contracts.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium IoT-enabled units from unbundled standard Wi-Fi products and economy remote-control systems. Price differentiation rests on UL 325 certification grade and Matter protocol interoperability, with California integrator-specified installations commanding service-inclusive premiums. Cost compression in the economy tier is intensifying because of raw material volatility, while DIY retail purchasers exhibit highest price sensitivity and new construction developers in Florida show lowest sensitivity due to embedded installation partnerships.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from national homebuilders, while wholesale distributors serve contractor trades with inventory financing. Wi-Fi and Bluetooth Low Energy chip fabrication concentrates in Taiwan, China, and South Korea, drawing from copper motor windings, rare earth permanent magnets, and polymer housing materials. Single-source vulnerability in Taiwanese foundries exposes manufacturers to geopolitical disruption. Distribution runs through regional distributors in Texas and Florida, direct sales to developers, and online retail for DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor allocation constraints at Taiwanese foundries prop pricing power for manufacturers with secured wafer supply, creating a supply-constrained market structure favoring incumbents with established supplier relationships.
For Market Incumbents: Deepen backward integration into motor drive assembly production to offset rare earth magnet cost volatility, while expanding Matter certification investment to defend against hardware-agnostic challengers eroding ecosystem lock-in. Secure capacity allocation agreements with Yangtze River Delta chipset suppliers before smaller competitors queue for protocol compliance validation. For New Entrants and Emerging Players: Capture predictive maintenance subscription revenue in California's integrator-channel by bundling environmental sensors with firmware-tier pricing, targeting the white-space between Chamberlain's cloud infrastructure and Vivint's security bundling. Penetrate Texas new construction partnerships through regional homebuilder direct sales before retail competition establishes. For Investors and Strategic Acquirers: Matter certification timeline compression at authorized testing labs is the leading indicator that interoperability engineering capacity will concentrate among scaled OEMs, favoring acquisition targets with in-house firmware stacks over pure-play hardware vendors. Target sensor technology startups with torque degradation algorithms and edge computing architectures. Monitor FCC cybersecurity labeling program implementation as the signal for regulatory compliance cost barriers rising.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification Investment | Accelerates product launch timelines by clearing interoperability testing backlog at FCC-authorized labs. |
| Predictive Maintenance Sensor Acquisition | Captures recurring revenue streams through subscription firmware tiers attached to hardware sales. |
| Texas Developer Partnership Expansion | Locks in embedded installation specifications with Dallas-Fort Worth and Houston homebuilders before retail competition. |
| Edge Computing Architecture Migration | Reduces cloud dependency for latency-critical UL 325 safety functions while meeting FCC Part 15 emission constraints. |
| Cybersecurity Labeling Pre-Compliance | Shortens pre-market approval windows under emerging FCC certification timelines before smaller vendors face testing expenditure barriers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with smart home integrators, regional homebuilder procurement directors, garage door installation contractors, and FCC regulatory affairs specialists. FCC Part 15 equipment authorization databases, UL certification registries, and semiconductor import manifests provided validation layers. Bottom-up household penetration modeling and top-down construction spending analysis were triangulated against manufacturer shipment data.
Data-stream reconciliation across connectivity protocol adoption curves, new construction permitting velocity, and replacement cycle timing generated volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user procurement authority, and distribution channel influence. CAGRs were derived from fitted growth curves applied to installed base expansion and attach rate evolution, with Matter protocol adoption timelines and IRA incentive qualification thresholds serving as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply disruption, cybersecurity regulatory expansion, and smart home platform consolidation dynamics. Forecasts reflect documented assumptions regarding single-family construction velocity, voice assistant ecosystem loyalty, and UL 325 compliance deadline enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Signage Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Residential Electric Underfloor Heating Market