
 Single-Use Syringe Market | 2026-2036
Single-Use Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Use Syringe Market Analytics
Aftermarket service revenue is rewriting profit dynamics in the single-use syringe industry. Becton, Dickinson and Company leverages its integrated manufacturing footprint across multiple continents to sustain pricing power. Terumo Corporation anchors its position through deep specialization in precision polymer molding for safety-engineered devices.
A single-use syringe is a disposable, barrel-and-plunger medical instrument typically manufactured from medical-grade polypropylene or polyethylene, designed to deliver measured fluid doses or extract biological specimens with sterility assurance. Safety syringes command expanding share as needlestick prevention regulations harden, while pre-filled syringes attract biologics manufacturers seeking dose accuracy and reduced contamination risk. Polypropylene dominates material selection due to chemical inertness and compatibility with gamma sterilization protocols.
FDA enforcement of the Needlestick Safety and Prevention Act shapes product design requirements in the United States, while EMA medical device regulations and ISO 7886 standards govern dimensional accuracy and performance testing across European markets. China's NMPA implements national standards for disposable injection equipment that align with international sterilization benchmarks. Stakeholders must monitor evolving safety device mandates and polymer supply chain certifications to maintain market access and avoid qualification delays.
Market Dynamics
The single-use syringe market pivots on the collision between safety-engineered device mandates and the cost pressures of high-volume immunization programs, with polymer supply chain certification emerging as the decisive gatekeeper for market access.
Growth Catalysts
- FDA Needlestick Safety Act enforcement:United States healthcare facilities face mandatory conversion to retractable or shielded needle designs, accelerating replacement cycles across acute care networks.
- Biologics manufacturing expansion:Pre-filled syringe formats attract pharmaceutical fill-finish operations seeking reduced contamination risk and precise dosing for temperature-sensitive therapeutics.
- India's domestic production scaling:Government immunization programs and export manufacturing hubs concentrate injection device output in Gujarat and Hyderabad clusters.
Market Restraints
- Medical-grade polypropylene concentration:Three Southeast Asian resin suppliers control gamma-stabilized polymer certification, creating input bottlenecks during sterilization protocol audits.
- Safety mechanism cost premiums:Retractable needle assemblies add 40-60% to unit manufacturing cost versus conventional designs, compressing margins in price-sensitive tender markets.
- ISO 7886 dimensional tolerances:Luer lock interchangeability standards impose precision molding investments that exclude smaller tool-and-die operations from qualification.
Strategic Opportunities
- Home infusion therapy expansion:Subcutaneous biologic administration outside acute settings creates demand for patient-friendly safety syringes with integrated needle shields.
- EMA MDR Article 10.4 technical documentation:Stricter clinical evidence requirements for Class IIa devices favor manufacturers with established post-market surveillance infrastructure.
- Connected device convergence:RFID-enabled syringes for medication tracking pair with hospital inventory management systems in German and Dutch pilot deployments.
Industry Challenges
- Cleanroom molding technician scarcity:ISO 14644 Class 7 environment operation requires specialized polymer processing skills concentrated in Swiss and German training pipelines.
- Gamma sterilization validation timelines:Sterility assurance level documentation for new polymer grades extends regulatory submission cycles by 8-14 months.
- Legacy assembly line retrofit costs:Converting high-speed syringe production to integrated safety mechanisms demands capital outlays that strain mid-cap manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Use Syringe Market |
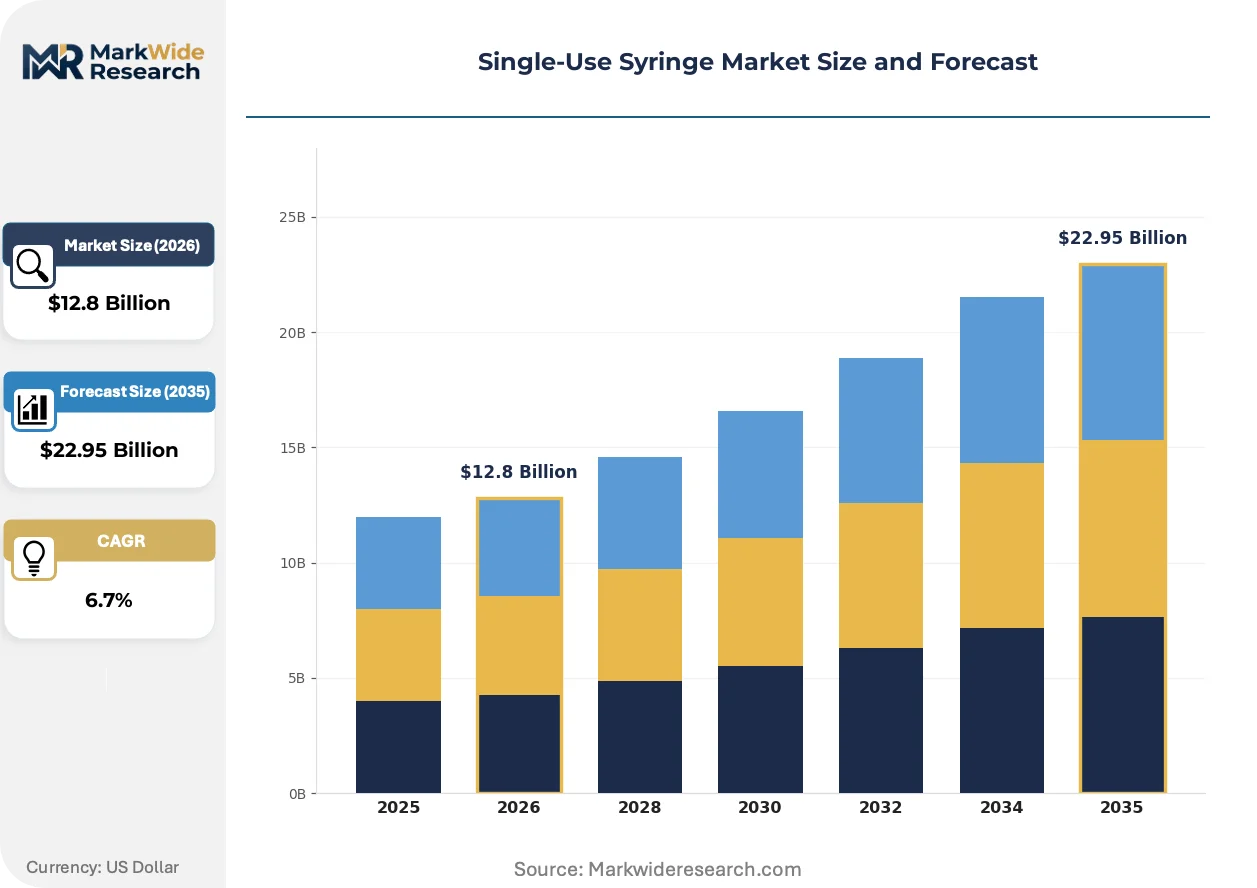
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Safety Syringes, Pre-filled Syringes, Custom Syringes Material: Polypropylene, Polyethylene, Glass, Rubber End User: Hospitals, Clinics, Home Care, Laboratories Application: Vaccination, Insulin Delivery, Anesthesia, Blood Collection |
| Companies Covered | Becton, Dickinson and Company, B. Braun Melsungen AG, Terumo Corporation, Nipro Corporation, Gerresheimer AG, Cardinal Health, Hindustan Syringes & Medical Devices, Schott AG, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Use Syringe Market Evolving Landscape
Active needlestick prevention mechanisms and polymer formulation advances are compressing the performance gap between safety-engineered and conventional syringes while reshaping procurement qualification criteria.
Dual-barrel safety syringe architecture is hybridizing passive and active protection features. German hospital procurement consortiums specify devices combining automatic needle retraction with rigid needle shields. Becton, Dickinson and Company and Terumo Corporation have accelerated mold qualification for these hybrid designs. The technology is hybridizing safety performance tiers that previously separated premium from standard product lines.
EMA Medical Device Regulation Annex I general safety requirements are hardening clinical evidence expectations for injection devices. Manufacturers must now submit biocompatibility testing under ISO 10993 series standards for all patient-contacting materials. European notified bodies have extended review timelines for syringe variants with novel safety actuation mechanisms. German and French hospital groups are consolidating supplier lists to vendors with MDR Article 10 technical files already validated.
Consolidated procurement through regional hospital purchasing cooperatives is displacing fragmented individual facility ordering. Nordic county council procurement organizations centralize syringe tenders across 40-60 hospitals, compressing supplier margins while demanding extended payment terms. Safety-engineered device categories attract 3-5 qualified vendors versus 12-15 for conventional syringes. Denmark and Sweden exhibit the most advanced cooperative purchasing concentration.
Single-Use Syringe Market Segmentation
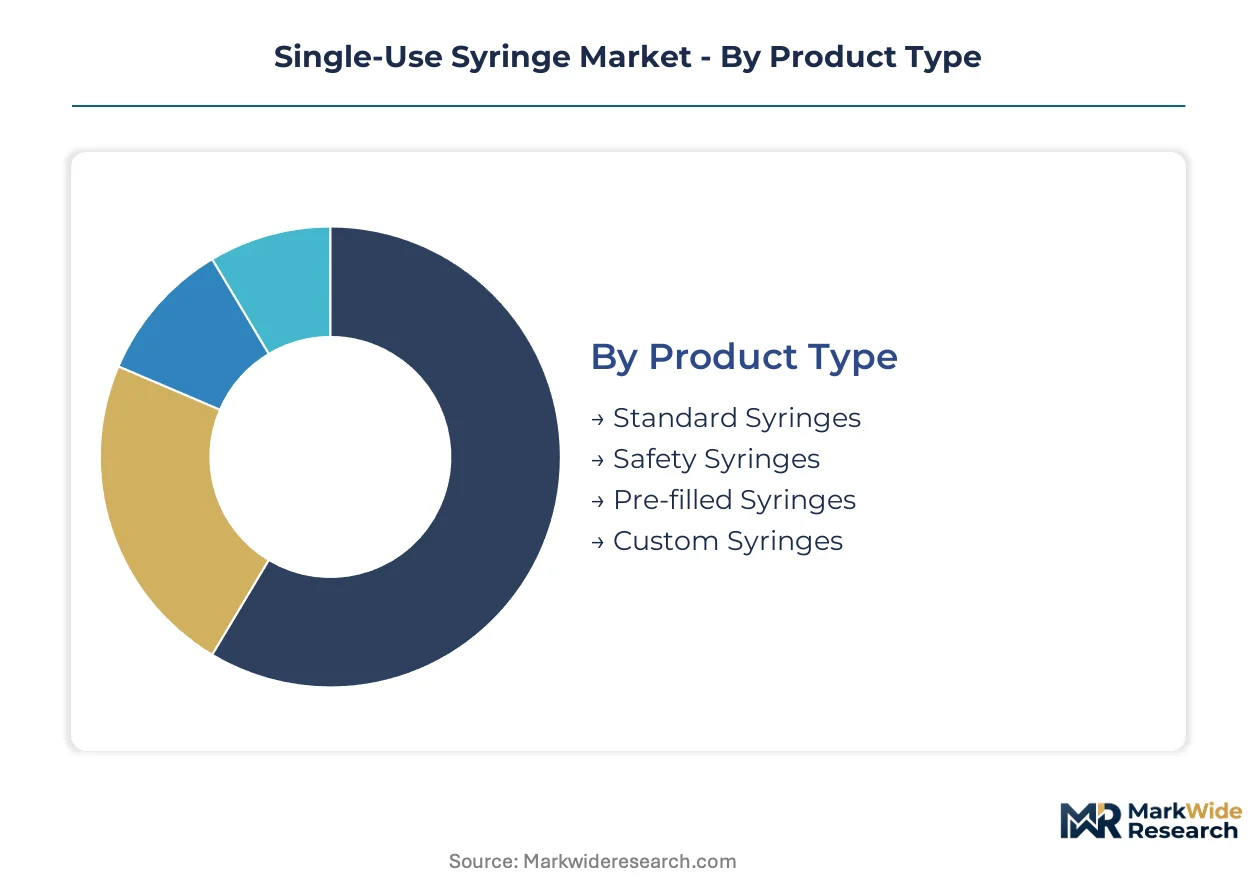
Segmentation in the single-use syringe market determines aftermarket service intensity, polymer certification requirements, and regulatory pathway complexity. Product type and material selection drive sterilization validation timelines and cleanroom molding investments.
Product Type:
Safety-engineered devices generate recurring calibration and training service revenue that standard designs cannot capture, while pre-filled formats shift liability toward pharmaceutical partners.
- Safety Syringes:Retractable or shielded needle mechanisms incorporate passive or active needlestick prevention features molded from gamma-stabilized polypropylene. Demand concentrates in United States acute care networks under FDA Needlestick Safety and Prevention Act enforcement, where mandatory conversion cycles accelerate replacement purchasing.
- Pre-filled Syringes:Sterile drug-product containers integrate barrel, plunger, and needle into single units filled by pharmaceutical manufacturers under aseptic processing protocols. Biologics fill-finish operations in German and Swiss manufacturing clusters favor these formats for temperature-sensitive therapeutics requiring dose precision.
- Standard Syringes:Conventional barrel-and-plunger designs without integrated safety features serve high-volume immunization programs in India and tender markets where unit cost dominates procurement decisions.
- Custom Syringes:Specialty dimensions or Luer configurations address niche anesthesia or diagnostic applications requiring non-standard needle gauges or barrel capacities.
Safety Syringes hold the largest share; momentum sits with Pre-filled Syringes.
Material:
Polymer selection governs gamma sterilization compatibility, dimensional stability under ISO 7886 tolerances, and resin supplier certification bottlenecks.
- Polypropylene:Medical-grade homopolymer dominates injection molding for barrel and plunger components due to chemical inertness, clarity, and compatibility with gamma irradiation sterilization protocols. Gamma-stabilized grades from Southeast Asian resin suppliers face certification audit backlogs that delay new product launches.
- Polyethylene:Lower-density formulations appear in plunger tip and gasket applications requiring flexibility and compression set resistance.
- Glass:Borosilicate barrels serve pre-filled syringe formats for parenteral drugs requiring oxygen barrier properties and extended shelf stability.
- Rubber:Elastomeric plunger stoppers and needle shields provide seal integrity and resealability for multi-dose vial access.
Polypropylene commands volume leadership; Glass gains share fastest in biologics containment.
End User:
Customer type determines batch size requirements, safety device specification stringency, and direct-to-patient packaging complexity.
- Hospitals:Acute care networks purchase through consolidated procurement cooperatives in Denmark and Sweden, specifying hybrid safety devices with automatic retraction and rigid shields under EMA MDR technical documentation requirements.
- Home Care:Subcutaneous biologic administration outside facilities demands patient-friendly safety syringes with integrated needle shields and intuitive activation mechanisms.
- Clinics:Outpatient settings balance safety compliance with inventory turnover constraints, favoring single-use disposable formats over reusable alternatives.
- Laboratories:Research and diagnostic applications require precise volumetric graduation and Luer lock interchangeability for analytical instrument compatibility.
Hospitals represent the largest procurement volume; Home Care expands most quickly.
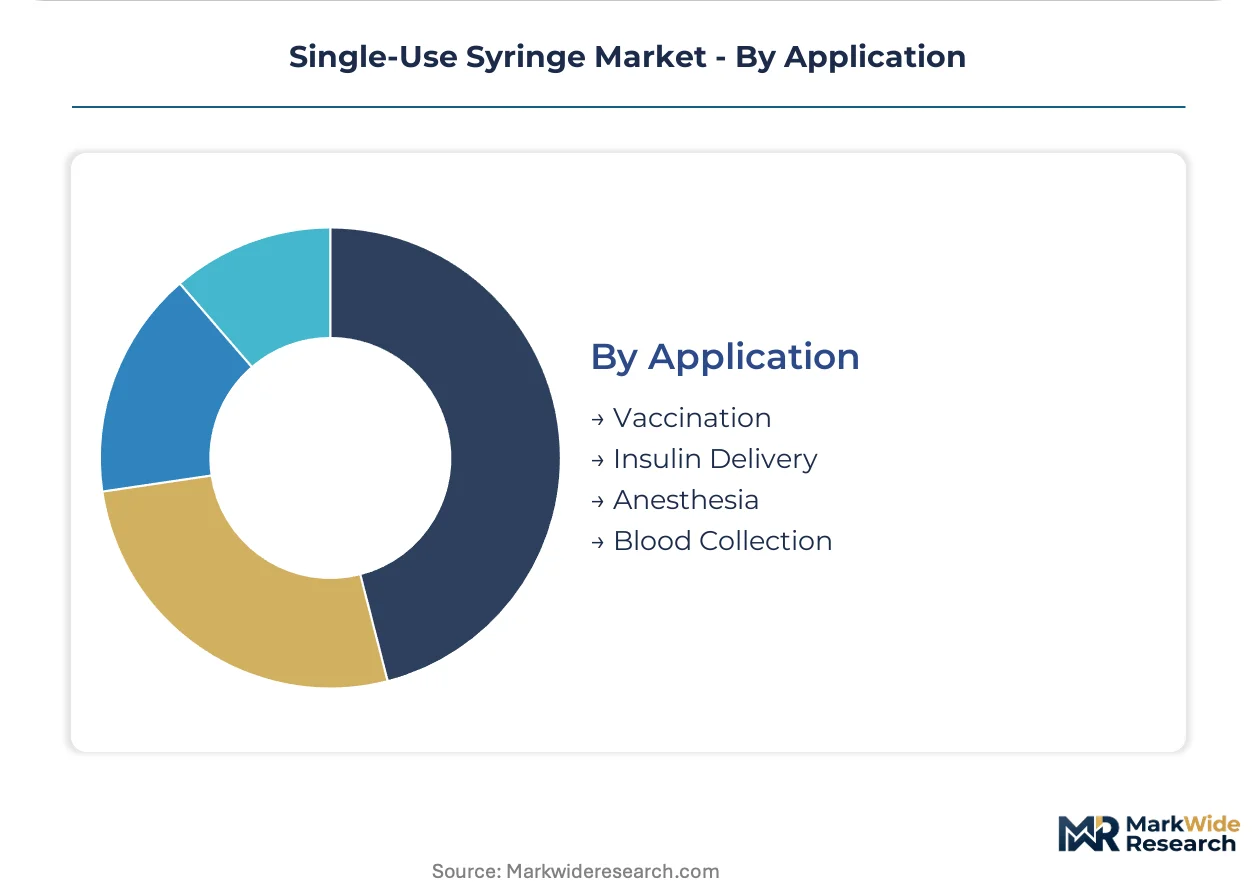
Application:
Clinical use case dictates needle gauge range, barrel capacity distribution, and contamination risk tolerance.
- Vaccination:High-volume immunization programs in India and China drive demand for standard syringes in 0.5mL and 1mL capacities, with safety conversions accelerating under national needlestick prevention initiatives.
- Insulin Delivery:Diabetes management requires ultra-fine needles in 31-32 gauge ranges with unit-dose graduation for precise glycemic control.
- Anesthesia:Operating room applications specify Luer lock compatibility with stopcock manifolds and glass compatibility with certain pharmaceutical formulations.
- Blood Collection:Venipuncture and capillary sampling applications integrate vacuum tube compatibility or micro-collection reservoirs.
Vaccination anchors volume demand; Insulin Delivery shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China exhibit extreme price elasticity in tender-driven immunization procurement, while German and United States acute care networks absorb 40-60% cost premiums for safety-engineered devices without volume reduction. This demand bifurcation shapes divergent manufacturing strategies across geographies.
United States
FDA enforcement of the Needlestick Safety and Prevention Act compels acute care networks toward retractable needle designs. Hospital procurement cooperatives in the Northeast and Midwest specify hybrid safety mechanisms combining automatic retraction with rigid shields. Becton, Dickinson and Company maintains integrated manufacturing across multiple states to serve these consolidated buyers.
Germany
EMA Medical Device Regulation Annex I requirements harden clinical evidence standards for Class IIa injection devices. Hospital procurement consortiums in Bavaria and North Rhine-Westphalia centralize tenders across 40-60 facilities, compressing supplier lists to vendors with validated Article 10 technical files. German notified bodies extend review timelines for novel safety actuation mechanisms.
India
Government immunization programs drive high-volume demand for standard syringes in 0.5mL and 1mL capacities. CDSCO implements national standards for disposable injection equipment aligned with international sterilization benchmarks. Manufacturing clusters in Gujarat and Hyderabad scale domestic production to serve both national programs and export markets.
China
NMPA national standards for disposable injection equipment align with international sterilization protocols. Domestic manufacturing scales to serve massive immunization programs while safety conversions accelerate under national needlestick prevention initiatives. Production concentrates in Yangtze River Delta and Pearl River Delta manufacturing hubs.
Switzerland
Swissmedic oversight of Class IIa devices maintains stringent biocompatibility testing requirements under ISO 10993 series standards. Precision polymer molding capabilities concentrate in Swiss training pipelines for ISO 14644 Class 7 cleanroom operations. German and French hospital groups source safety-engineered devices through validated Swiss suppliers.
Single-Use Syringe Market Competitive Landscape
Vertically integrated multinationals and specialized regional fabricators split the market between premium safety-device segments and price-sensitive immunization tenders. Consolidated procurement through hospital cooperatives favors suppliers with established regulatory dossiers across multiple geographies. Two archetypes dominate: integrated polymer-to-device manufacturers controlling resin certification, and precision molders specializing in safety mechanism integration. Competitive moves concentrate on backward integration into gamma-stabilized resin supply and strategic partnerships with pharmaceutical fill-finish operators.
Within the integrated multinational tier, Becton, Dickinson and Company and Terumo Corporation exemplify archetypes spanning safety-engineered device design and precision polymer processing. B. Braun Melsungen AG occupies a position representing European-based manufacturing with deep specialization in medical device fabrication. These anchors demonstrate how geographic manufacturing footprints and regulatory dossier breadth determine access to consolidated procurement channels.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Nipro Corporation |
| Gerresheimer AG |
| Cardinal Health |
| Hindustan Syringes & Medical Devices |
| Schott AG |
| Smiths Medical |
| Others |
Value Network & Pricing Analysis
Gujarat and Hyderabad manufacturing clusters concentrate global syringe output capacity, creating asymmetric bargaining power that tilts procurement leverage toward large-volume tenders and compresses margins for mid-scale producers serving fragmented buyers.
Pricing Analysis
Aftermarket service revenue from calibration contracts and safety device training programs drives lifetime value capture beyond unit sales. Three-tier pricing structure across premium, standard, and economy levels separates safety-engineered devices with MDR-validated technical files from conventional designs and tender-optimized standard syringes. Cost compression in the economy tier is intensifying because India's domestic production scaling floods tender markets with certified-low-cost supply. Government immunization programs exhibit extreme price sensitivity, while German hospital cooperatives absorb premiums for hybrid safety mechanisms without volume reduction.
Supply Chain Analysis
Tariff exposure between Southeast Asian resin suppliers and European device fabricators dominates supply chain risk calculus for gamma-stabilized polypropylene certification. Manufacturing capacity concentrates in India, China, and Germany, with cleanroom molding operations drawing from medical-grade polymer feedstocks, elastomeric plunger components, and precision Luer lock fittings. Single-source vulnerability sits with three Southeast Asian suppliers controlling gamma-stabilized resin certification audits. Distribution runs through regional hospital purchasing cooperatives in the Nordics and consolidated procurement networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Needlestick Safety Act enforcement and EMA MDR technical documentation requirements constitute dual regulatory inflections accelerating safety syringe conversion cycles and consolidating supplier access to premium procurement channels.
For Market Incumbents: Insulate market position through backward integration into gamma-stabilized polypropylene supply chains and captive cleanroom molding capacity expansion in Swiss and German training pipelines. Certification investment for MDR Article 10.4 clinical evidence dossiers defends against emerging regional fabricators from India and China seeking European market entry. Channel control through long-term service contracts with consolidated hospital cooperatives locks out mid-cap competitors lacking post-market surveillance infrastructure. For New Entrants and Emerging Players: Build out specialty capabilities in patient-friendly safety syringes for home infusion therapy, where subcutaneous biologic administration outside acute settings remains underpenetrated by incumbent device portfolios. White-space targets include RFID-enabled connected syringes for medication tracking in German and Dutch pilot deployments, and custom Luer configurations for niche anesthesia applications. A go-to-market angle pairing with pharmaceutical fill-finish operators seeking pre-filled syringe partnerships bypasses direct hospital procurement consolidation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because safety-engineered device mandates harden entry barriers and concentrate procurement access among dossier-validated suppliers. Acquisition target archetype: precision polymer molders with ISO 14644 Class 7 cleanroom certifications and existing gamma sterilization validation timelines. The signal to watch is EMA notified body queue extension for novel safety actuation mechanisms, which lengthens competitive qualification cycles for unvalidated entrants.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Article 10 Technical File Validation | EMA notified body approval unlocks consolidated procurement access across German and French hospital consortiums. |
| Backward Integration into Resin Supply | Captive gamma-stabilized polypropylene certification insulates against Southeast Asian supplier audit backlogs. |
| Home Care Safety Syringe Development | Patient-friendly designs with integrated needle shields capture subcutaneous biologic administration outside facilities. |
| Pharmaceutical Fill-Finish Partnership | Pre-filled syringe collaborations shift liability toward drug manufacturers while securing volume offtake commitments. |
| RFID-Enabled Connected Device Pilot | German and Dutch hospital inventory management integration creates differentiation in procurement qualification criteria. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists and secondary validation through FDA 510(k) filings, EMA medical device databases, hospital procurement contract disclosures, and ISO certification registries anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down macroeconomic healthcare expenditure trends to isolate syringe-specific consumption patterns.
Calibration against historical safety device conversion cycles and immunization program procurement data informs the analytical framework across the projection horizon. Segmentation dimensions include product type, material selection, end user category, and application area, with regional regulatory cluster effects modeled separately. CAGRs derive from compound growth trajectory analysis applied to baseline volume and value estimates, incorporating polymer supply certification timelines and safety mechanism adoption curves as industry-specific forecast inputs.
Stress conditions across gamma sterilization validation delays, resin supplier audit backlogs, and hospital cooperative consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and procurement centralization trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Wash Bottle Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Skin Tac Market
Medical Supplies
US N95 Mask Market