
 Ostomy Care Market | 2026-2036
Ostomy Care Market Size, Share, and Industry Trends Forecast 2026-2036
Ostomy Care Market Outlook
A shift from hospital-centric procurement to diversified multi-source contracting is realigning how ostomy care products reach end users. Coloplast A/S leverages direct-to-patient subscription models to sustain recurring revenue streams across European and North American markets. Hollister Incorporated anchors its competitive position through specialized silicone-adhesive formulations that reduce peristomal skin complications. ConvaTec Group plc differentiates via hospital group purchasing organization contracts that control bulk institutional supply chains.
Ostomy care encompasses the management of surgically created stomas through adhesive pouching systems, skin barriers, and drainage collection devices typically constructed from medical-grade polymers, hydrocolloid adhesives, and odor-filtering films designed to maintain seal integrity against bodily fluids while protecting peristomal dermis. Colostomy bags occupy the largest volume share within product type segmentation due to the prevalence of colorectal cancer interventions and diverticulitis surgeries. Homecare end users represent the fastest-expanding demand channel as discharge protocols accelerate and patients manage pouch changes independently outside clinical settings.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation govern adhesive biocompatibility, bacterial filtration efficiency, and wear-time durability claims for ostomy appliances. The EPA monitors volatile organic compound emissions from hydrocolloid manufacturing processes, while ISO 13485 quality management standards shape supplier audit requirements for raw material traceability. Stakeholders must monitor evolving MDR post-market surveillance obligations in Europe and state-level Medicaid reimbursement rate adjustments in the United States that directly influence patient out-of-pocket affordability and brand switching behavior.
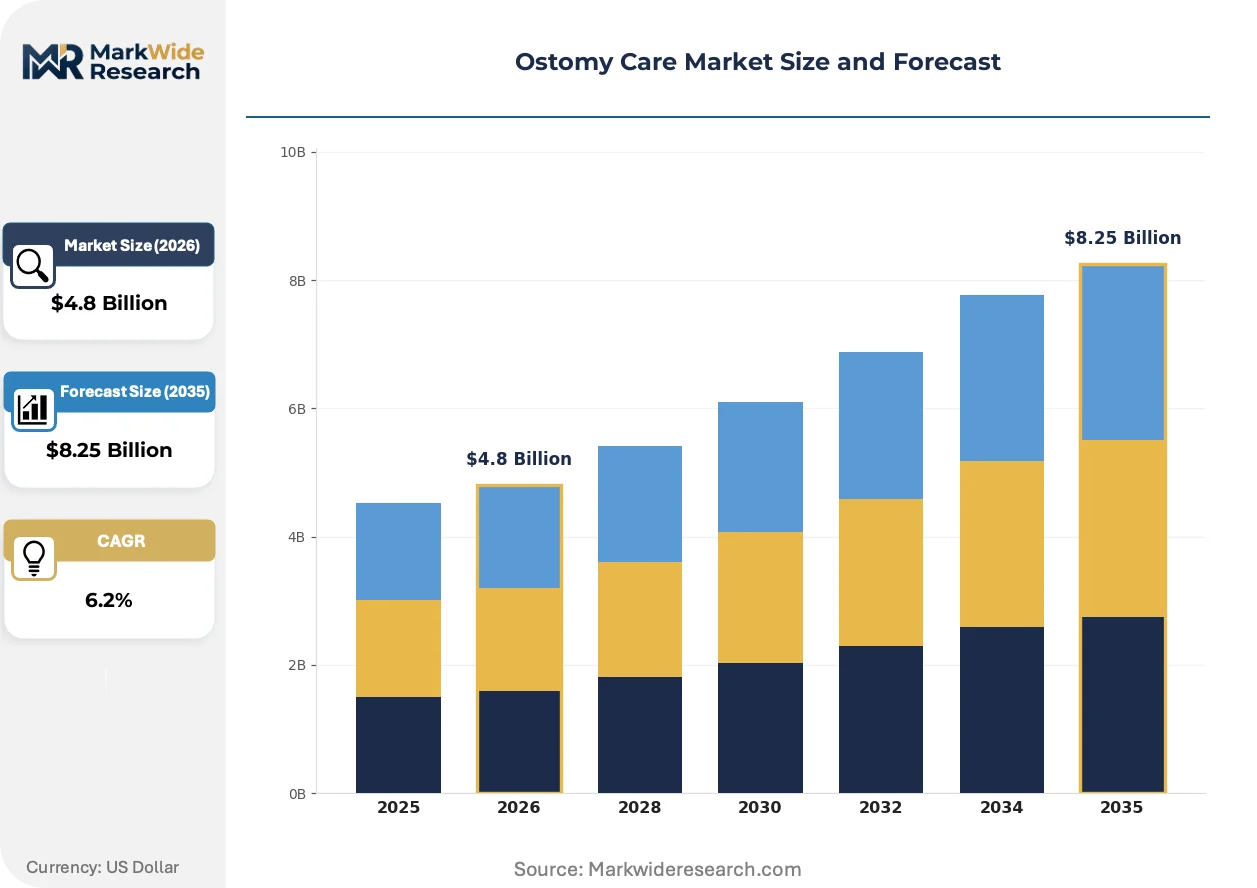
Market Dynamics
The Ostomy Care Market pivots on accelerated discharge protocols that relocate routine pouch management from inpatient wards to domestic environments, compressing traditional hospital procurement cycles while elevating patient self-sufficiency requirements.
Growth Catalysts
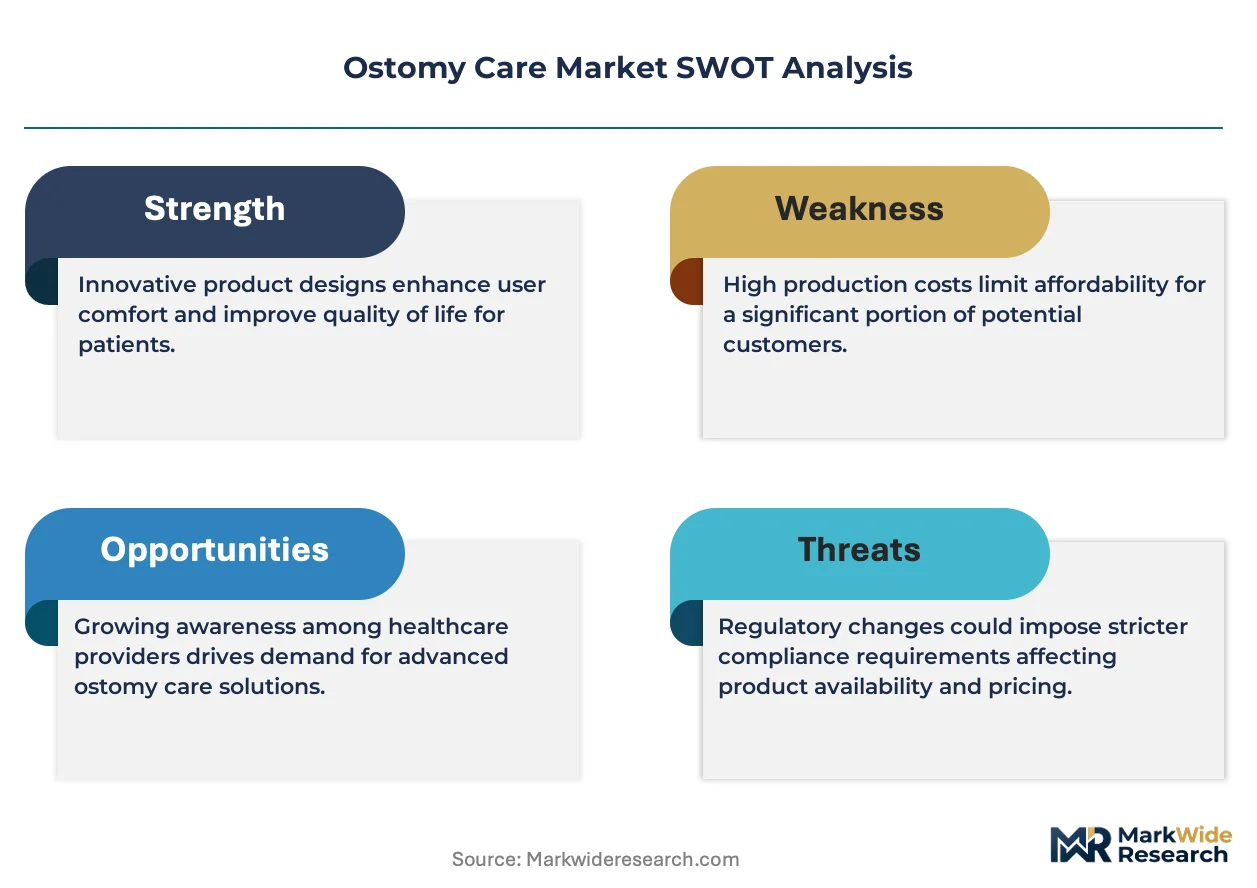
- FDA 510(k) Streamlining:Expedited clearance pathways for hydrocolloid barrier improvements accelerate time-to-market for next-generation skin-protective adhesives, reducing clinical validation burdens for manufacturers targeting US distribution.
- Homecare Channel Expansion:Post-acute care networks in Germany and Japan now bundle ostomy supplies with nursing visit reimbursements, creating pull-through demand for extended-wear pouching systems designed for independent patient handling.
- Silicone-Adhesive Chemistry:Advanced soft-silicone formulations reduce peristomal dermatitis incidence, expanding addressable patient populations previously intolerant to traditional acrylic-based barriers.
Market Restraints
- Medical-Grade Polymer Feedstock Volatility:Specialized polyethylene and odor-barrier film resins concentrate among Asian petrochemical suppliers, exposing converters to input cost swings and freight margin erosion.
- EU MDR Compliance Burden:Enhanced post-market surveillance obligations under the Medical Device Regulation extend certification timelines and inflate notified body audit costs for European market access.
- Reusable Appliance Substitution:Closed-system irrigation accessories and continent ostomy alternatives divert select patient segments away from conventional drainable pouch dependency.
Strategic Opportunities
- India Outpatient Penetration:Underdeveloped homecare infrastructure and rising colorectal surgical volumes create first-mover advantage for direct-to-patient subscription models bypassing fragmented hospital procurement.
- Digital Remote Monitoring Integration:Convergence of wearable moisture sensors with telehealth platforms enables proactive leakage alerts, differentiating premium-tier offerings through outcomes data capture.
- US Medicaid Reimbursement Expansion:State-level coverage liberalization for extended-wear barriers and accessory seals reduces out-of-pocket friction for economically constrained patient populations.
Industry Challenges
- Specialized Wound-Ostomy-Continence Nurse Scarcity:Certified clinician shortages constrain patient education capacity, elevating product return rates and brand-switching incidence among inadequately trained homecare users.
- ISO 13485 Supplier Audit Complexity:Raw material traceability requirements for hydrocolloid adhesive sourcing fragment qualified vendor pools, elongating qualification cycles for formulation modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ostomy Care Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colostomy Bags, Ileostomy Bags, Urostomy Bags, Accessories End User: Hospitals, Homecare, Clinics, Long-Term Care Facilities Distribution Channel: Retail Pharmacies, Online Stores, Direct Sales, Medical Supply Companies Application: Surgical Recovery, Chronic Disease Management, Incontinence Support, Wound Care |
| Companies Covered | Coloplast A/S, ConvaTec Group plc, Hollister Incorporated, B. Braun Melsungen AG, 3M Company, Smith & Nephew Plc, Alcare Co., Ltd., Welland Medical Limited, Nu-Hope Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ostomy Care Market Strategic Shifts
Material science convergence with digital health infrastructure is redefining competitive differentiation, shifting value capture from commodity pouch manufacturing toward integrated skin health management ecosystems.
Moldable skin barrier technology is consolidating market preference around customized peristomal seal formation without cutting templates. Homecare patients and outpatient clinics adopt these systems at accelerating velocity, displacing traditional flat barrier segments. The technology is consolidating procurement decisions toward single-source adhesive ecosystem contracts rather than discrete component purchasing.
EU MDR post-market clinical follow-up requirements now mandate systematic peristomal complication registries from CE-marked manufacturers. This obligation forces restructuring of quality management systems and elevates documentation costs disproportionately for mid-tier suppliers serving European hospital group purchasing organizations. German and French notified bodies apply the strictest interpretation, compressing competitive viability for non-vertically integrated market entrants.
Direct-to-patient e-commerce channels disintermediate traditional durable medical equipment distributors across North American and Western European markets. Subscription-based replenishment models capture recurring revenue through auto-ship algorithms calibrated to individual wear-time patterns. This behavioral shift concentrates most visibly among working-age ostomates in the United States seeking discretion and schedule flexibility incompatible with brick-and-counter pickup workflows.
Ostomy Care Market Segmentation
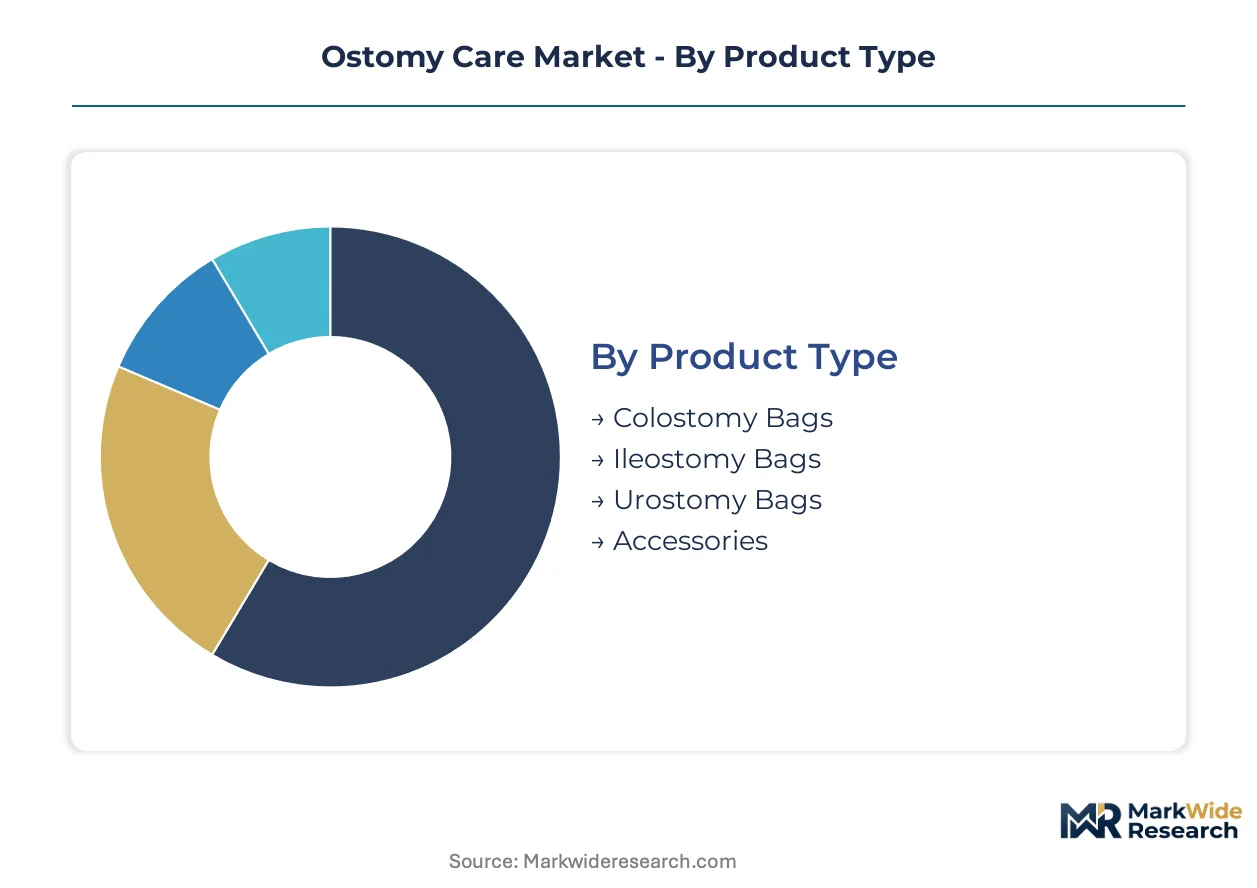
Segmentation in ostomy care reveals how reimbursement pathways, patient autonomy levels, and clinical acuity reshape procurement economics across adhesive pouching systems and drainage appliances. Manufacturers calibrate portfolio depth against channel-specific margin structures that diverge sharply between institutional contracting and direct-to-patient subscription models.
Product Type:
Procurement volume and margin capture diverge based on surgical indication complexity and wear-time durability requirements across pouching system categories.
- Colostomy Bags:Drainable and closed-end pouches constructed from multilayer odor-barrier films and hydrocolloid faceplates dominate hospital formulary placement due to colorectal cancer resection volumes in the United States and Germany. Reimbursement bundling with surgical episodes sustains high-volume contracting through group purchasing organizations.
- Ileostomy Bags:High-output pouches with integrated gas filters and extended-wear adhesives command premium positioning among Crohn's disease and ulcerative colitis patient populations in Japan. Output management complexity drives accessory attachment rates and recurring seal replacement purchases.
- Urostomy Bags:Night drainage adapters and anti-reflux valve configurations serve urinary diversion patients post-bladder cancer surgery.
- Accessories:Skin barrier pastes, adhesive removers, and pouch deodorants complete peristomal care regimens.
Volume sits with colostomy systems; growth tilts toward ileostomy configurations.
End User:
Site-of-care economics determine whether procurement flows through centralized hospital supply chains or fragmented retail reimbursement pathways.
- Homecare:Independent pouch change protocols and Medicare durable medical equipment billing codes in the United States accelerate demand for extended-wear barriers and discreet disposal systems. Patient self-sufficiency requirements elevate educational content and telehealth integration as competitive differentiators.
- Hospitals:Inpatient wards and ambulatory surgery centers prioritize standardization through formulary committees that negotiate bulk adhesive contracts based on peristomal complication rates.
- Clinics:Outpatient wound-ostomy-continence nurse consultations drive trial-size sampling and conversion to homecare replenishment.
- Long-Term Care Facilities:Skilled nursing staff ratios influence one-piece versus two-piece system selection.
Revenue concentrates in hospital procurement; expansion accelerates most quickly in homecare channels.
Distribution Channel:
Channel selection reflects patient mobility, insurance portability, and the urgency of supply continuity following discharge.
- Online Stores:Subscription algorithms and auto-ship replenishment capture working-age ostomates in the United States seeking discretion and schedule flexibility. Direct-to-patient platforms disintermediate traditional durable medical equipment distributors through insurance pre-authorization integration.
- Retail Pharmacies:Immediate availability for emergency pouch replacement sustains foot traffic in Germany and Japan where pharmacy networks maintain ostomy supply inventories.
- Direct Sales:Manufacturer field representatives serve hospital group purchasing organization contract negotiations.
- Medical Supply Companies:Local distributors handle Medicaid billing complexity and same-day delivery.
Transaction volume flows through retail pharmacies; digital channels gain share fastest.
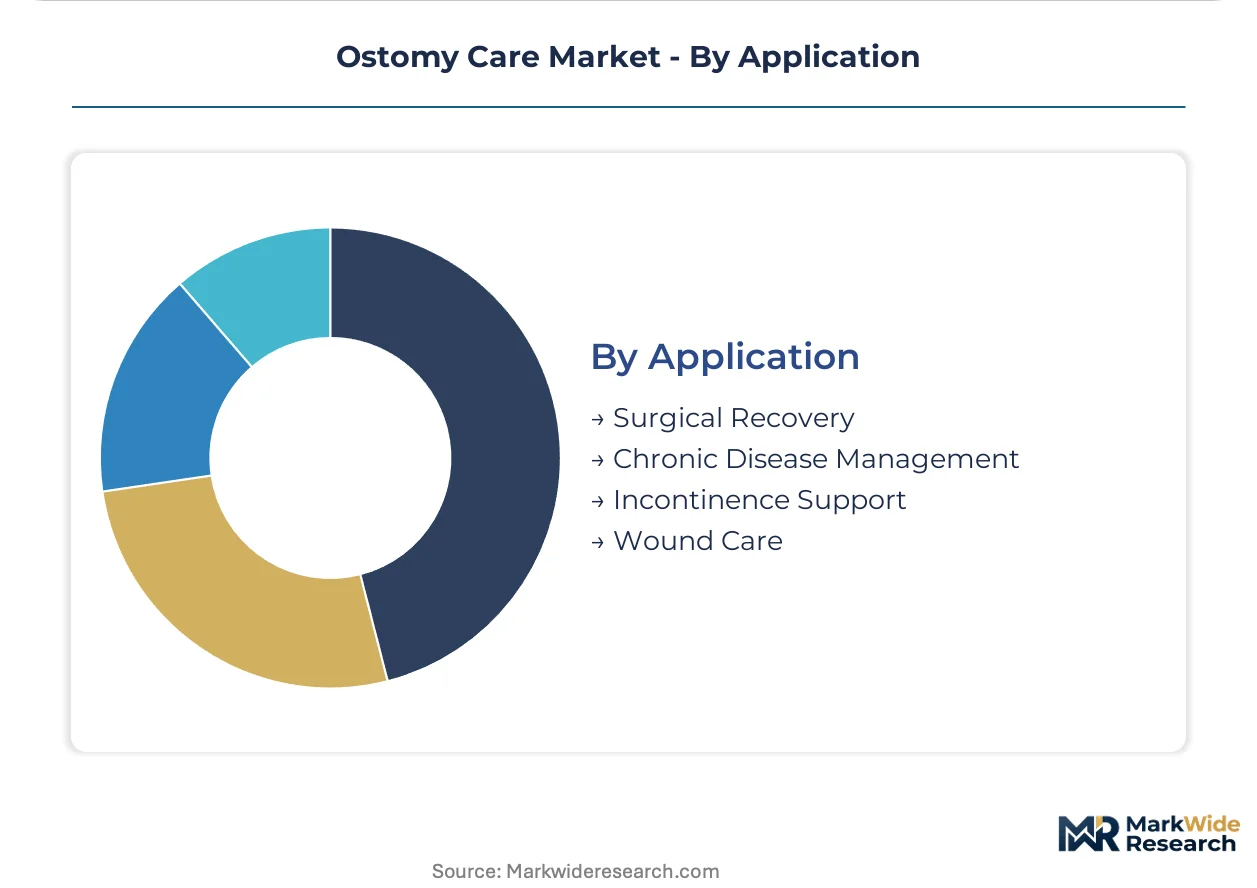
Application:
Clinical indication determines reimbursement coding, wear-time performance requirements, and the intensity of peristomal skin management protocols.
- Chronic Disease Management:Inflammatory bowel disease and familial adenomatous polyposis patients require indefinite pouching system utilization with quarterly barrier replacement cycles. Outcomes data linking adhesive biocompatibility to dermatitis prevention influences payer coverage policies in Germany.
- Surgical Recovery:Post-operative stoma maturation periods drive initial appliance sizing and cut-to-fit barrier demand until peristomal contour stabilizes.
- Incontinence Support:Fecal management systems in acute care settings address temporary diversion needs.
- Wound Care:Fistula and complex abdominal wound applications utilize high-capacity pouches with vacuum-assisted closure compatibility.
Utilization duration extends furthest in chronic disease management; surgical recovery applications demonstrate steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer feedstock concentration in South Korean and Japanese petrochemical corridors anchors Asia-Pacific supply chains for hydrocolloid adhesive production, while finished appliance manufacturing clusters in Denmark, the United States, and Germany shape end-market access patterns.
United States
Medicare durable medical equipment billing codes and state-level Medicaid reimbursement liberalization sustain homecare channel expansion for extended-wear barriers. FDA 510(k) clearance pathways govern silicone-adhesive biocompatibility claims for domestic distribution. Minneapolis and Chicago host specialized wound-ostomy-continence nurse training centers that elevate patient education capacity.
Germany
Statutory health insurance bundling of ostomy supplies with post-acute nursing visits accelerates outpatient procurement migration. EU MDR post-market surveillance obligations under German notified body interpretation compress certification timelines for mid-tier entrants. Hamburg and Frankfurt concentrate hospital group purchasing organization negotiation headquarters.
Japan
Aging demographics and ulcerative colitis prevalence drive ileostomy pouch demand with integrated gas filtration. PMDA medical device approvals align with MHLW reimbursement pricing for extended-wear systems. Osaka and Tokyo medical device clusters specialize in high-output appliance manufacturing for Crohn's disease populations.
India
Rising colorectal surgical volumes and underdeveloped homecare infrastructure create subscription model opportunities bypassing fragmented hospital procurement. CDSCO medical device rules govern adhesive biocompatibility for domestic market entry. Mumbai and Bengaluru emerge as direct-to-patient platform development hubs.
United Kingdom
NHS supply chain centralization through national procurement frameworks standardizes colostomy bag formulary placement. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment requirements. Leeds and Manchester concentrate clinical nurse specialist training programs.
Ostomy Care Market Competitive Environment
Global majors compete with regional champions across adhesive chemistry specialization and distribution channel control, producing a tiered structure where scale-driven conglomerates, mid-cap silicone-formulation specialists, and direct-to-patient platform operators occupy distinct competitive spaces. Market consolidation concentrates around hospital group purchasing organization contract capture and homecare subscription retention. Three archetypes dominate: vertically integrated polymer-to-pouch manufacturers, pure-play adhesive technology licensors, and digital-first patient-direct platforms. Capacity expansion in medical-grade film extrusion and strategic partnerships with telehealth providers represent the dominant competitive moves reshaping positioning.
Within the vertically integrated tier, Coloplast A/S and ConvaTec Group plc occupy positions anchoring European and North American supply security through captive hydrocolloid production. Hollister Incorporated exemplifies the adhesive-specialist archetype, with its Incorporated suffix indicating US corporate structure. B. Braun Melsungen AG represents German-engineered diversification across surgical and chronic care portfolios. These three named entities illustrate how geographic origin and corporate form factor into procurement committee evaluation criteria without specifying individual product configurations or financial performance.
| Leading Market Players |
|---|
| Coloplast A/S |
| ConvaTec Group plc |
| Hollister Incorporated |
| B. Braun Melsungen AG |
| 3M Company |
| Smith & Nephew Plc |
| Alcare Co., Ltd. |
| Welland Medical Limited |
| Nu-Hope Laboratories, Inc. |
| Others |
Value Chain & Pricing Dynamics
Medical-grade polymer resin costs cascade through three pricing tiers as hydrocolloid adhesive formulations move from South Korean petrochemical corridors to finished pouching systems in hospital group purchasing organization contracts and direct-to-patient subscription platforms.
Pricing Analysis
Warranty and leakage-prevention service bundling separates premium-tier silicone-adhesive systems from unbundled economy alternatives where patients bear replacement costs for seal failures. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification grade, and after-sales telehealth integration depth. Cost compression in the economy tier is intensifying because Medicaid reimbursement rate ceilings constrain out-of-pocket flexibility. Homecare patients dependent on Medicare durable medical equipment billing codes exhibit highest price sensitivity; hospital formulary committees negotiating bulk contracts demonstrate lowest sensitivity due to complication-rate guarantees.
Supply Chain Analysis
Product return flows for seal-failure claims and peristomal dermatitis complaints reverse through manufacturer quality management systems, creating feedback loops that reformulate adhesive chemistry at Danish and German production clusters. Raw material sourcing draws from South Korea and Japan for odor-barrier polyethylene films, Malaysia for hydrocolloid gum base, and Germany for silicone medical-grade polymers. Single-source vulnerability concentrates in Asian petrochemical suppliers of specialized barrier resins. Distribution runs through hospital group purchasing organization warehouses for institutional procurement and direct-to-patient fulfillment centers for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified hydrocolloid adhesive production capacity constraints prop pricing power for manufacturers with captive polymer-to-pouch capabilities, insulating premium tiers from economy-segment margin erosion.
For Market Incumbents: Cement adhesive chemistry leadership through backward integration into medical-grade silicone polymer production and ISO 13485-certified barrier manufacturing. Defend against direct-to-patient platform disintermediation by embedding telehealth nurse consultation into subscription auto-ship algorithms. Prioritize capacity addition in Denmark and Minnesota to secure FDA 510(k) cleared supply for US hospital formulary contracts.
For New Entrants and Emerging Players: Capture white-space opportunity in India's underdeveloped homecare infrastructure where fragmented hospital procurement delays patient discharge continuity. Target working-age ostomates in Germany's statutory health insurance system seeking discretion through digital-first subscription models. Deploy direct-to-patient platform architecture with integrated insurance pre-authorization to bypass established distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap silicone-formulation specialists with EU MDR certification progress and Indian distribution licenses over capital-intensive polymer producers. Long-term viability rests on adhesive biocompatibility data assets and telehealth platform integration depth rather than commodity pouch manufacturing scale. Monitor state-level Medicaid reimbursement rate liberalization for extended-wear barriers as inflection signal for homecare channel profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance compliance unlocks German hospital group purchasing organization contract eligibility. |
| Hospital System Partnership | Formulary placement with US academic medical centers validates silicone-adhesive biocompatibility claims for downstream expansion. |
| Software Companion Development | Wearable moisture sensor integration with telehealth platforms differentiates premium-tier offerings through proactive leakage alerts. |
| Reimbursement Strategy | Medicaid coverage expansion for extended-wear barriers reduces out-of-pocket friction in economically constrained patient populations. |
| FDA Submission | 510(k) clearance for next-generation skin-protective adhesives accelerates time-to-market in the United States distribution channel. |
Study Parameters
Independent corroboration across wound-ostomy-continence nurse specialists, hospital purchasing committee directors, biomedical engineers, and durable medical equipment distributor executives underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare durable medical equipment billing code records, EU MDR notified body certification registries, and hospital procurement contract disclosures establishes quantitative anchors. Bottom-up patient population modeling and top-down adhesive polymer consumption analysis triangulate market sizing.
Comparable-period anchoring to historical discharge protocol acceleration and homecare channel migration patterns shaped the projection horizon calibration. Segmentation dimensions modeled include product type, end-user site-of-care economics, distribution channel control points, and application clinical indication complexity across the analysis window. CAGRs derive from adhesive formulation innovation cycles, regulatory certification timeline compression, and reimbursement pathway evolution. Peristomal dermatitis incidence rates and patient self-sufficiency training completion metrics inform demand elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR post-market surveillance obligation enforcement intensity and state-level Medicaid reimbursement rate volatility. Forecasts reflect documented assumptions regarding polymer feedstock cost trajectories and certified nurse educator capacity expansion. Practitioners should monitor silicone-adhesive biocompativity claim litigation trends and telehealth platform reimbursement coding decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Breast Shells Market
Medical Supplies
Medical Disposables Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
Surgical Dressings and Disposables Market