
 Global Transcatheter Pulmonary Valve Market | 2026-2036
Global Transcatheter Pulmonary Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transcatheter Pulmonary Valve Market Foresight
The transcatheter pulmonary valve category is recalibrating around a widening split between premium balloon-expandable systems and commodity-oriented self-expanding alternatives. Medtronic leverages its integrated structural heart platform to dominate complex congenital repair workflows. Edwards Lifesciences Corporation anchors its position through sustained R&D intensity in catheter-based valve engineering. Boston Scientific Corporation competes by extending its interventional portfolio across pediatric and adult congenital segments.
A transcatheter pulmonary valve is a bioprosthetic or mechanical valve delivered via catheter to the right ventricular outflow tract without open-heart surgery, typically constructed from bovine or porcine pericardial tissue mounted on a metallic or polymeric frame and crimped for deployment through 18-26 French delivery sheaths. Its primary purpose is to restore pulmonary valve competence in patients with congenital heart disease who face right ventricular dysfunction from chronic regurgitation or stenosis. Balloon expandable valves capture the dominant margin pool due to precise placement control in calcified conduits, while self-expanding valves represent the fastest-growing segment for native outflow tract anatomy where radial force requirements differ. Hybrid valves occupy a narrower niche bridging surgical and percutaneous approaches for complex anatomies.
FDA premarket approval and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for transcatheter pulmonary valve manufacturers. ISO 5840 cardiovascular implant standards and Japan PMDA sakigake designation pathways further condition market access across major jurisdictions. Stakeholders must monitor evolving pediatric labeling expansions and real-world evidence mandates that will determine competitive positioning in this high-growth structural heart segment.
Market Dynamics
Pediatric cardiology units are consolidating around catheter-based pulmonary valve replacement as surgical volume thresholds rise and reimbursement frameworks favor same-day discharge protocols. This procedural shift is compressing the addressable patient pool for open-heart surgical centers while expanding interventional cardiology service lines.
Growth Catalysts
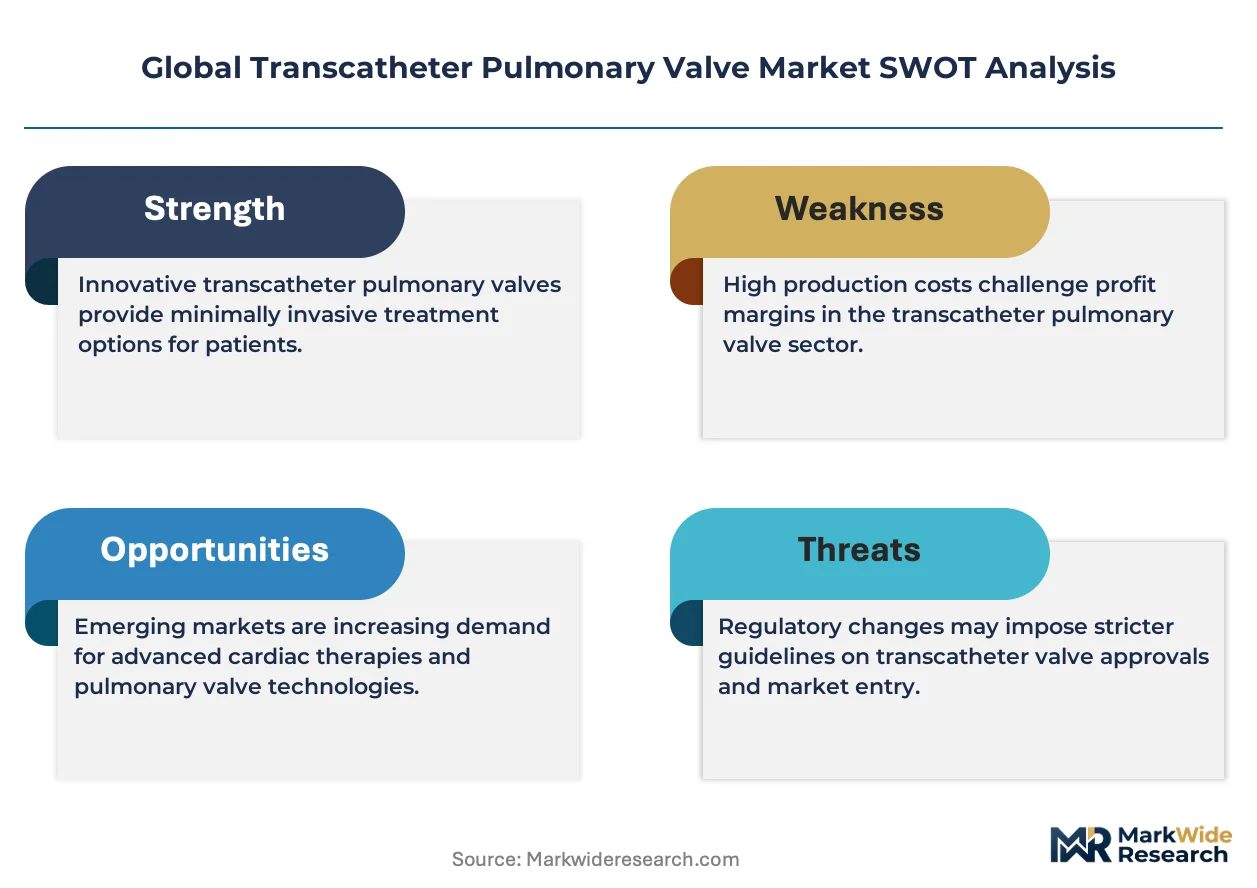
- FDA premarket approval streamlining:Expedited pathways for breakthrough device designation accelerate clinical trial timelines and reduce regulatory capital requirements for novel valve platforms.
- Pediatric congenital heart defect prevalence:Tetralogy of Fallot and other right ventricular outflow tract anomalies generate recurring valve replacement need across adolescent and adult survivor populations.
- Bioprosthetic tissue processing advances:Decellularization and anti-calcification treatments extend valve durability beyond ten years, reducing reintervention burden.
Market Restraints
- Bovine pericardial tissue supply concentration:Three specialized tissue processors control raw material qualification for major valve manufacturers, creating single-source vulnerability.
- EU MDR conformity assessment bottlenecks:Notified body capacity constraints extend CE marking timelines to 18-24 months, delaying European commercialization.
- Surgical valve durability benchmarks:Established mechanical and bioprosthetic surgical alternatives offer proven 15-20 year track records that catheter-based systems must match.
Strategic Opportunities
- Japan PMDA sakigake designation:Priority review status for pediatric orphan indications enables six-month approval timelines and premium reimbursement positioning.
- Native right ventricular outflow tract expansion:Anatomically tailored self-expanding frames address the 40% of candidates lacking prior surgical conduit.
- Remote proctoring networks:Real-time surgical support via augmented reality platforms extends procedural capability to community cardiac centers.
Industry Challenges
- Pediatric interventional cardiology fellowship scarcity:Training program expansion lags procedural volume growth, constraining qualified operator supply.
- ISO 5840 cardiovascular implant testing complexity:Fatigue and hydrodynamic validation requirements demand 12-18 month preclinical timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transcatheter Pulmonary Valve Market |
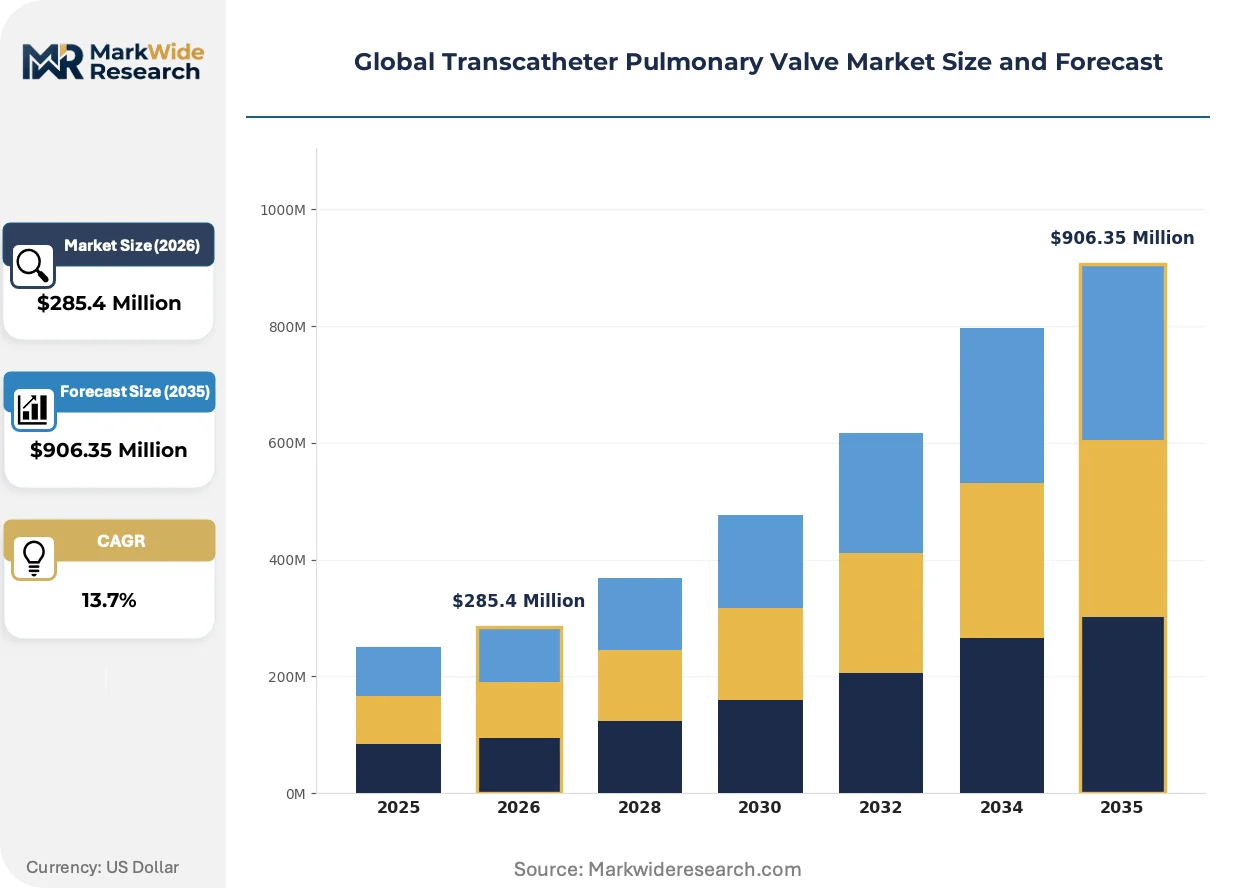
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Expandable Valves, Self-Expanding Valves, Hybrid Valves, Mechanical Valves Therapy Area: Pulmonary Stenosis, Pulmonary Regurgitation, Tetralogy of Fallot, Right Ventricular Outflow Tract Dysfunction End User: Cardiac Surgery Centers, Catheterization Laboratories, Specialized Cardiology Clinics, Pediatric Cardiology Units Delivery Mode: Transfemoral, Transjugular, Transapical, Transsubclavian |
| Companies Covered | Medtronic, Edwards Lifesciences Corporation, Boston Scientific Corporation, Abbott, Artivion, Inc, JenaValve Technology, Inc, LivaNova PLC, Venus Medtech, Braile Biomedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transcatheter Pulmonary Valve Market Shifts & Advancements
Transcatheter pulmonary valve engineering is pivoting from conduit-dependent designs toward native anatomy solutions, with three interconnected developments reshaping competitive positioning and clinical adoption curves.
Polymeric valve leaflet materials are decentralizing tissue sourcing dependencies for manufacturers historically tethered to pericardial supply chains. Synthetic polymers with equivalent hemodynamic performance eliminate batch-to-batch biological variability and enable just-in-time manufacturing models. Pediatric centers in Germany and Japan are piloting these platforms for compassionate use cases where tissue valve availability constrains scheduling.
CE marking under the EU MDR is forcing systematic post-market clinical follow-up infrastructure investments. Manufacturers must now maintain active implant registries with 10-year follow-up protocols to maintain conformity. This surveillance mandate disproportionately burdens mid-tier competitors lacking integrated electronic health record connectivity, accelerating consolidation toward platforms with embedded digital infrastructure.
Hospital procurement committees are unbundling valve hardware from procedural service contracts previously bundled under device-plus-physician payment models. Cardiac centers in the United States now negotiate valve pricing separately from catheterization laboratory staffing allocations, exposing manufacturers to direct price competition. This disaggregation is most advanced in academic medical centers with dedicated structural heart purchasing committees.
Global Transcatheter Pulmonary Valve Market Segmentation
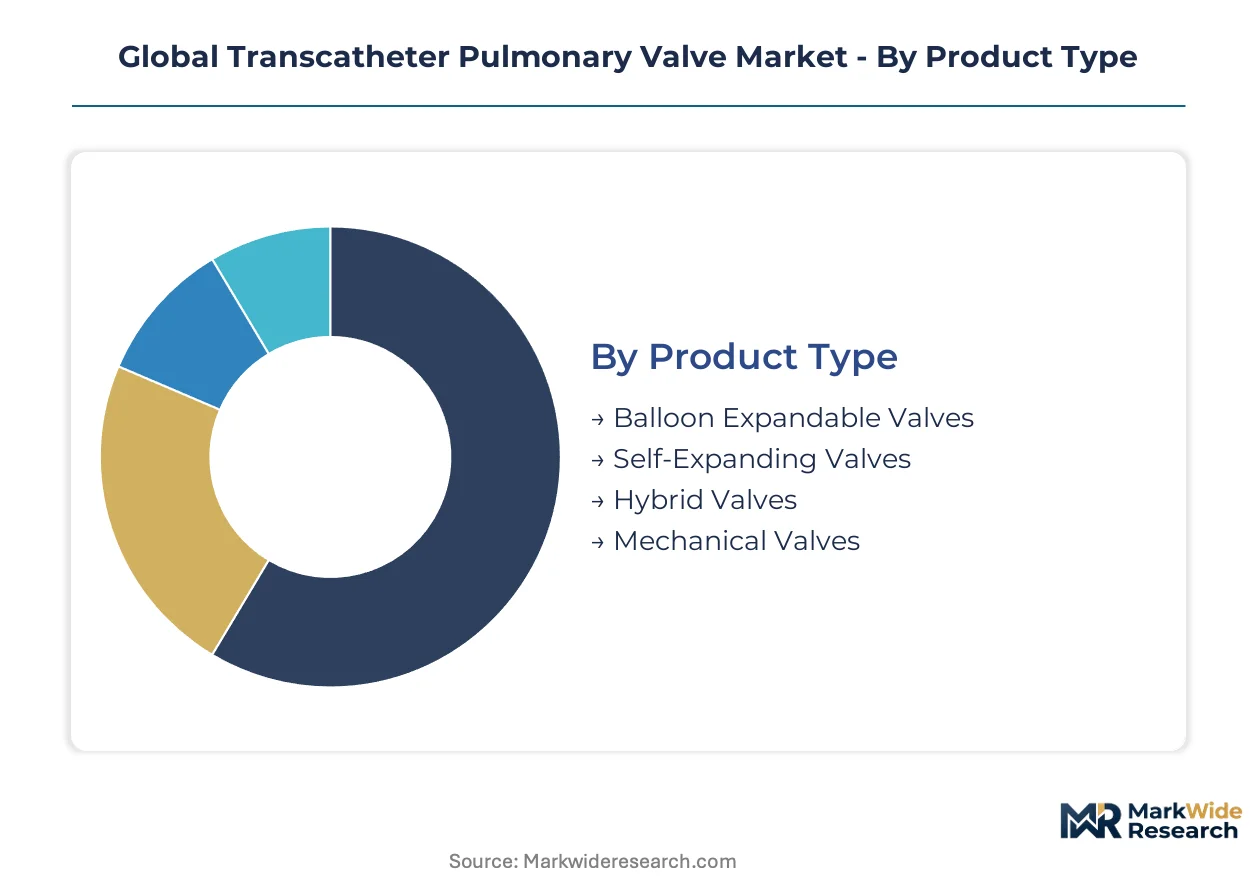
Transcatheter pulmonary valve manufacturers configure product portfolios across four intersecting dimensions that determine reimbursement pathways, operator training requirements, and patient eligibility criteria. Each segmentation axis carries distinct regulatory implications and competitive intensity profiles.
Product Type:
Radial force generation mechanisms differentiate valve platforms and dictate anatomical suitability for calcified conduits versus native outflow tracts.
- Balloon Expandable Valves:Bovine or porcine pericardial tissue mounted on cobalt-chromium or stainless steel frames delivers precise diameter control via balloon inflation. Demand concentrates in the United States where FDA premarket approval pathways favor controlled expansion in surgical conduit replacements.
- Self-Expanding Valves:Nitinol frames with shape-memory properties deploy without balloon assistance, conforming to irregular native anatomy. Germany's pediatric centers in Munich and Berlin are expanding adoption for Tetralogy of Fallot patients lacking prior conduit surgery, driving the steepest expansion trajectory in this category.
- Hybrid Valves:Surgical-percutaneous bridge designs accommodate complex anatomies through adjustable frame geometries.
- Mechanical Valves:Polymeric or carbon-based leaflets eliminate biological tissue sourcing constraints for extended durability applications.
Balloon expandable valves lead on scale; self-expanding valves lead on momentum.
Therapy Area:
Underlying pathophysiology determines valve sizing protocols, anticipated hemodynamic performance, and reintervention timelines.
- Pulmonary Stenosis:Obstructive lesions requiring high radial force frames to resist recoil against calcified native or conduit tissue. Japanese cardiac centers under PMDA sakigake designation prioritize stenosis indications for accelerated approval timelines.
- Pulmonary Regurgitation:Volume overload conditions favoring large effective orifice areas and low-profile frames to minimize right ventricular afterload. Catheterization laboratories in Boston and Cleveland report highest procedural volumes for isolated regurgitation repair.
- Tetralogy of Fallot:Complex congenital anatomy combining stenosis and regurgitation requiring individualized valve selection.
- Right Ventricular Outflow Tract Dysfunction:Heterogeneous presentations spanning conduit failure, homograft degeneration, and native valve deterioration.
Pulmonary regurgitation captures the largest addressable patient base; right ventricular outflow tract dysfunction applications are climbing the fastest as labeling expands.
End User:
Facility infrastructure and reimbursement models segment demand between surgical and interventional service lines.
- Cardiac Surgery Centers:Hybrid operating rooms with integrated imaging support complex cases requiring surgical standby. Germany's university hospitals in Heidelberg and Hamburg maintain highest European procedural volumes through combined surgical-interventional staffing models.
- Catheterization Laboratories:Standalone interventional suites optimized for same-day discharge protocols. United States outpatient cardiac catheterization facilities under CMS reimbursement frameworks are displacing inpatient surgical volume fastest.
- Specialized Cardiology Clinics:Focused congenital heart programs with dedicated nurse practitioner follow-up infrastructure.
- Pediatric Cardiology Units:Age-specific device sizing and growth-anticipating valve selection protocols.
Cardiac surgery centers lead on scale; catheterization laboratories lead on momentum.
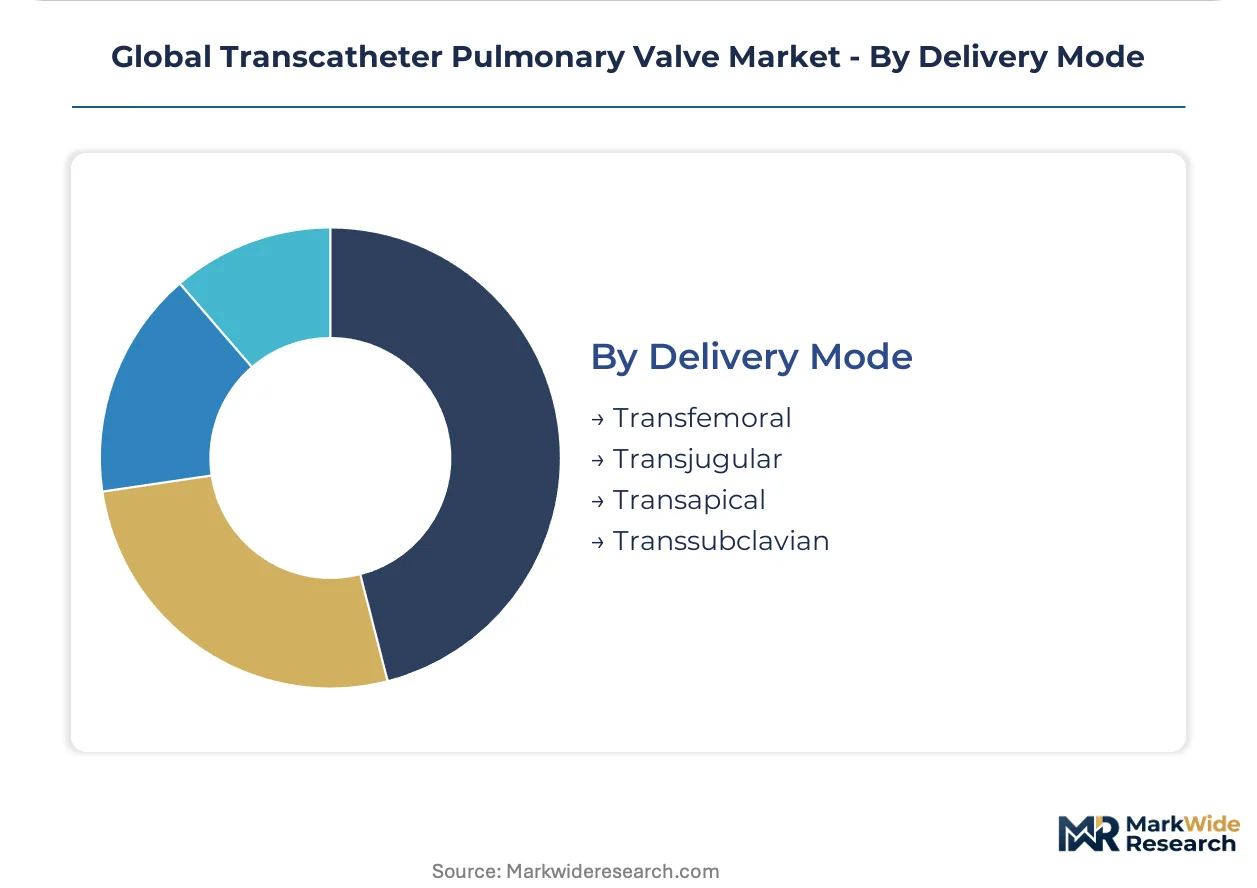
Delivery Mode:
Vascular access strategy determines sheath size requirements, fluoroscopy duration, and complication risk profiles.
- Transfemoral:Femoral vein access accommodating 18-26 French delivery systems represents the default approach for adult and adolescent patients. United States academic medical centers report transfemoral utilization exceeding alternative access routes by substantial margins.
- Transjugular:Internal jugular approach for patients with femoral vein occlusion or inferior vena cava interruption. Pediatric cardiology units in Tokyo and Osaka have pioneered transjugular workflows for small-body congenital patients.
- Transapical:Direct ventricular puncture reserved for conduit anatomy incompatible with peripheral vascular access.
- Transsubclavian:Subclavian vein utilization for specific conduit orientations or concomitant procedures.
Transfemoral access leads on scale; transjugular approaches are gaining share fastest in pediatric subpopulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric interventional cardiologists cluster in specialized cardiac centers across four countries where congenital heart surgery volumes and regulatory frameworks concentrate demand. These geographies anchor the procedural expertise and reimbursement infrastructure shaping market access patterns.
United States
FDA premarket approval pathways and breakthrough device designations accelerate commercialization timelines for novel valve platforms. CMS reimbursement frameworks favor same-day discharge protocols at outpatient cardiac catheterization facilities. The Boston-Cleveland corridor hosts the highest procedural volumes for isolated pulmonary regurgitation repair.
Germany
EU MDR conformity assessments and notified body capacity constraints extend CE marking timelines to 18-24 months. University hospitals in Heidelberg and Hamburg maintain combined surgical-interventional staffing models with highest European procedural volumes. Munich and Berlin pediatric centers are expanding self-expanding valve adoption for Tetralogy of Fallot patients lacking prior conduit surgery.
Japan
PMDA sakigake designation delivers six-month approval timelines and premium reimbursement positioning for pediatric orphan indications. Tokyo and Osaka pediatric cardiology units have pioneered transjugular workflows for small-body congenital patients. National health insurance coverage decisions concentrate purchasing authority at designated cardiac centers.
China
NMPA innovation pathway approvals and volume-based procurement reforms reshape pricing dynamics for imported valve systems. Shanghai and Beijing academic medical centers drive clinical trial enrollment for polymeric valve platforms. Domestic manufacturers are capturing share through localized production and provincial tender participation.
Global Transcatheter Pulmonary Valve Market Competitive Landscape
Top-tier vendors anchor integrated structural heart platforms, while mid-tier specialists compete on pediatric-specific labeling and regional regulatory expertise. The market exhibits moderate consolidation around three to four firms with congenital heart repair workflows. Strategic archetypes include diversified cardiovascular conglomerates, pure-play transcatheter valve engineers, and regional tissue-processing integrators. Dominant competitive moves encompass backward integration into bioprosthetic tissue supply and digital infrastructure investments for post-market surveillance compliance.
Among diversified cardiovascular conglomerates, Medtronic and Edwards Lifesciences Corporation occupy positions exemplifying platform breadth across structural heart segments. Boston Scientific Corporation represents the interventional portfolio extension archetype, competing across pediatric and adult congenital indications. These three firms anchor the premium tier through sustained regulatory capital deployment and integrated service line capture at academic medical centers.
| Leading Market Players |
|---|
| Medtronic |
| Edwards Lifesciences Corporation |
| Boston Scientific Corporation |
| Abbott |
| Artivion, Inc |
| JenaValve Technology, Inc |
| LivaNova PLC |
| Venus Medtech |
| Braile Biomedica |
| Others |
Supply & Pricing Matrix
Hospital procurement committee unbundling of valve hardware from procedural service contracts forces manufacturers to compete on standalone device pricing while absorbing catheterization laboratory staffing costs previously passed through bundled payments. This demand-side restructuring compresses margin pools for balloon-expandable platforms and accelerates price transparency across academic medical center purchasing committees.
Pricing Analysis
The bundled-versus-unbundled service split now dominates contract negotiations, with three-tier pricing structure across premium, standard, and economy levels stratifying by FDA breakthrough designation status and pediatric labeling breadth. Price differentiation hinges on CE marking tier under EU MDR and real-world evidence registry commitments. Cost compression in standard-tier balloon-expandable valves is intensifying because NMPA volume-based procurement in China exposes imported systems to domestic manufacturer undercutting. Pediatric cardiology units exhibit highest price sensitivity due to constrained procurement budgets, while hybrid operating room bundles at German university hospitals show lowest sensitivity given integrated surgical-interventional staffing models.
Supply Chain Analysis
Explanted valve return flows for post-market surveillance under EU MDR ten-year follow-up protocols create reverse-logistics infrastructure demands that mid-tier competitors struggle to fulfill. Geographic supply concentration centers on United States cobalt-chromium frame forging, Germany nitinol processing, and Japan polymeric leaflet pilot manufacturing. Raw material dependencies include bovine pericardial tissue from three specialized processors, cobalt-chromium alloys, and shape-memory nitinol wire. Single-source vulnerability in qualified tissue supply poses structural risk to batch release schedules. Distribution runs through GPO contracts at United States academic medical centers and direct hospital procurement in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transcatheter pulmonary valve market functions as a stable compounder anchored by recurring reintervention need across Tetralogy of Fallot survivor populations and congenital heart defect prevalence that generates predictable procedural volume expansion.
For Market Incumbents: Deepen backward integration into bioprosthetic tissue processing to offset single-source vulnerability from the three dominant tissue suppliers threatening production continuity. Fortify digital infrastructure for EU MDR post-market surveillance compliance, as active implant registry mandates disproportionately burden competitors lacking embedded electronic health record connectivity. Prioritize pediatric labeling expansions that extend addressable patient pools beyond adult congenital indications. For New Entrants and Emerging Players: Capture native right ventricular outflow tract applications where self-expanding frame demand climbs fastest and established players lack anatomically optimized platforms. Target Japan's PMDA sakigake designation pathway for six-month approval timelines and premium reimbursement positioning in pediatric orphan indications. Pursue polymeric valve materials to eliminate biological tissue sourcing dependencies and enable just-in-time manufacturing models. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier specialists possessing pediatric-specific labeling and integrated digital surveillance infrastructure that EU MDR conformity assessments now mandate. Long-term viability frames around ten-year durability data generation and real-world evidence registry maintenance capabilities. Watch FDA pediatric labeling expansion decisions as inflection indicators for addressable market step-function growth.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pediatric Labeling Expansion | Broadens addressable patient base to adolescent Tetralogy of Fallot survivors requiring repeat intervention. |
| EU MDR Post-Market Surveillance Infrastructure | Mandates ten-year implant registries that consolidate competitive position around digital health connectivity. |
| Polymeric Valve Material Development | Eliminates batch-to-batch biological variability and decouples manufacturing from pericardial tissue supply constraints. |
| Japan PMDA Sakigake Designation Pursuit | Delivers six-month approval timelines and premium reimbursement for pediatric orphan valve indications. |
| Remote Proctoring Network Deployment | Extends procedural capability to community cardiac centers lacking congenital interventional fellowship training density. |
Research Methodology
Coverage spans United States, Germany, Japan, and China, with primary inputs from each regional cluster combining structured interviews with pediatric interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers alongside secondary validation. Primary fieldwork drew from FDA premarket approval filings, PMDA sakigake designation records, EU MDR notified body assessment documentation, and NMPA innovation pathway approvals. Secondary sources encompassed CMS reimbursement databases, Japanese national health insurance coverage decisions, hospital procurement records, and congenital heart surgery volume registries. Bottom-up procedural volume modeling triangulated against top-down market sizing across manufacturer revenue disclosures.
Granularity-level framing applied product type segmentation at the valve-platform level, therapy area at pathophysiology indication, end user at facility infrastructure tier, and delivery mode at vascular access strategy across the projection horizon. CAGRs derived from logistic diffusion modeling of procedural adoption curves weighted by regulatory approval timeline assumptions and reimbursement framework evolution. Forecast inputs incorporated pediatric congenital heart defect prevalence trajectories, surgical-to-interventional procedural shift rates, and bioprosthetic tissue supply capacity constraints.
Regulatory approval delays, bioprosthetic tissue supply disruptions, and EU MDR notified body capacity bottlenecks are the dominant revision risks that could compress expansion trajectories. Forecasts reflect assumptions regarding pediatric labeling expansion timelines and real-world evidence registry compliance costs that may shift with regulatory interpretation evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Global Bone Screw System Market
Medical Devices
Knee Braces Market
Medical Devices
Capsulotomy Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market