
 Lacrimal Dilator Market | 2026-2036
Lacrimal Dilator Market Size, Share, and Industry Trends Forecast 2026-2036
Lacrimal Dilator Market Insights
A shift from single-source procurement to multi-source supply is repositioning how hospital systems and specialty eye centers contract for lacrimal dilators. FCI Ophthalmics leverages its specialized manufacturing footprint across European production sites to sustain consistent supply to ophthalmology departments. BVI Medical anchors its competitive stance through deep product specialization in balloon and silicone dilator formats. OASIS Medical differentiates by controlling distribution channels that reach outpatient clinics directly.
A lacrimal dilator is a slender, tapered instrument designed to progressively enlarge the nasolacrimal duct or punctal opening, typically manufactured from surgical-grade stainless steel, titanium, or biocompatible polymers with diameters ranging from 0.3 mm to 1.2 mm for calibrated mechanical dilation. Its primary purpose is to restore tear drainage patency in acquired or congenital nasolacrimal obstruction during procedures such as dacryocystorhinostomy or punctal stenosis repair. Metal dilators occupy the mature volume segment where standardized sizing and reusable sterilization protocols sustain lower per-procedure costs for high-volume hospitals. Balloon dilators represent the fastest-growing product category as controlled radial expansion technology displaces traditional bougienage in complex stenosis cases. Specialty eye centers concentrate margin pools around silicone dilators used in pediatric applications and revision surgeries where biocompatibility and reduced trauma justify premium positioning.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation govern material biocompatibility, sterility assurance, and clinical performance claims for lacrimal dilators entering their respective markets. ISO 13485 quality management standards and ophthalmic-specific ASTM specifications further constrain manufacturing processes and supplier qualification requirements. The convergence of automated dilatation systems with telemedicine-guided preoperative planning will reshape how regulators evaluate remote-supervised device use. Stakeholders must monitor how FDA digital health guidance and EU AI Act risk classifications apply to algorithm-assisted procedural planning tools.
Market Dynamics
Balloon dilatation technology is electrifying procedural protocols in dacryocystorhinostomy, compressing operative time and reducing trauma rates while specialty eye centers re-equip suites to accommodate controlled radial expansion systems.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated clearance pathways for balloon dilator iterations reduce time-to-market for manufacturers targeting United States hospital systems.
- Japan's Aging Demographics:METI-tracked surgical volumes in tertiary ophthalmology centers drive recurring instrument replacement cycles for metal and silicone formats.
- Biocompatible Polymer Advancement:Medical-grade polymer processing improvements enable thinner-walled balloon membranes with superior burst pressure ratings.
Market Restraints
- Titanium Feedstock Volatility:Surgical-grade titanium sponge pricing fluctuations squeeze margin structures for European reusable instrument manufacturers.
- Single-Source Balloon Catheter Dependence:German and United States producers rely on concentrated Midwest polymer extrusion facilities for compliant tubing supply.
- CE Marking Timeline Extension:EU MDR technical documentation requirements lengthen approval cycles for small-batch silicone dilator variants.
Strategic Opportunities
- Indian Outpatient Clinic Expansion:CDSCO-registered distributors can capture volume in tier-two cities where dacryocystorhinostomy capacity is scaling rapidly.
- Telemedicine-Assisted Preoperative Planning:Algorithm-guided stenosis assessment converges with disposable dilator kits for remote-supervised procedures.
- Pediatric Silicone Segment:Underpenetrated congenital nasolacrimal obstruction repair in Japanese university hospitals creates premium positioning potential.
Industry Challenges
- ISO 13485 Auditor Shortage:Qualified ophthalmic device quality management certification bodies face backlogs delaying supplier qualification timelines.
- Legacy Sterilization Infrastructure:United States hospital systems with fixed autoclave configurations resist transitioning to single-use balloon systems requiring different waste protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lacrimal Dilator Market |
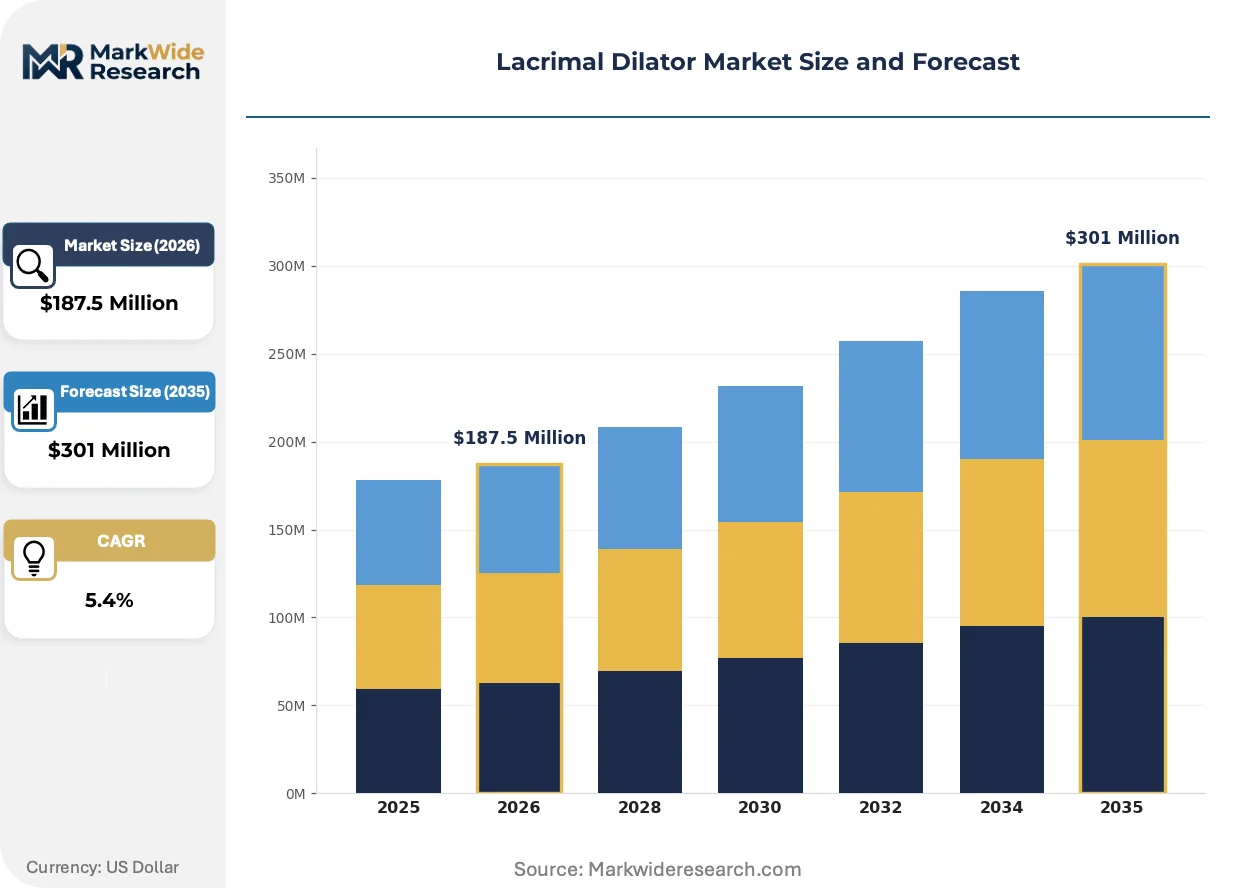
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $301 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Dilators, Silicone Dilators, Metal Dilators, Specialty Dilators Therapy Area: Ophthalmology, Eye Surgery, Allergic Conjunctivitis, Dacryocystitis End User: Hospitals, Outpatient Clinics, Specialty Eye Centers, Home Care Settings Delivery Mode: Surgical Procedures, Manual Dilatation, Automated Systems, Telemedicine |
| Companies Covered | FCI Ophthalmics, BVI Medical, OASIS Medical, Aurolab, Kaneka, Beaver-Visitec, Rumex International, Alcon Inc., Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lacrimal Dilator Market Trends and Innovations
Material science breakthroughs and regulatory recalibration are compressing product lifecycles while reshaping how surgical instruments traverse procurement channels.
Controlled radial expansion balloon systems are electrifying complex stenosis management by enabling precise, pressure-monitored duct dilation without mechanical bougienage trauma. Specialty eye centers in Germany and the United States are retrofitting procedure suites at accelerated pace to accommodate these systems. The technology is compressing average operative duration while elevating reimbursement complexity for mixed metal-and-balloon instrument trays.
EU MDR post-market surveillance requirements are intensifying clinical evidence obligations for reusable metal dilator manufacturers. European notified bodies now demand extended follow-up data on surface degradation and biocompatibility persistence. Small-cap Italian and French instrument specialists are consolidating quality management functions to absorb documentation burdens that larger competitors amortize across broader portfolios.
Direct-to-clinic distribution models are displacing traditional medical-surgical distributor intermediaries for high-volume silicone dilator consignment. OASIS Medical and comparable channel controllers are building captive logistics networks reaching outpatient surgery centers in Texas, California, and Florida. This disintermediation concentrates pricing leverage with manufacturers while fragmenting local service relationships that hospitals previously relied upon for instrument maintenance.
Lacrimal Dilator Market Segmentation
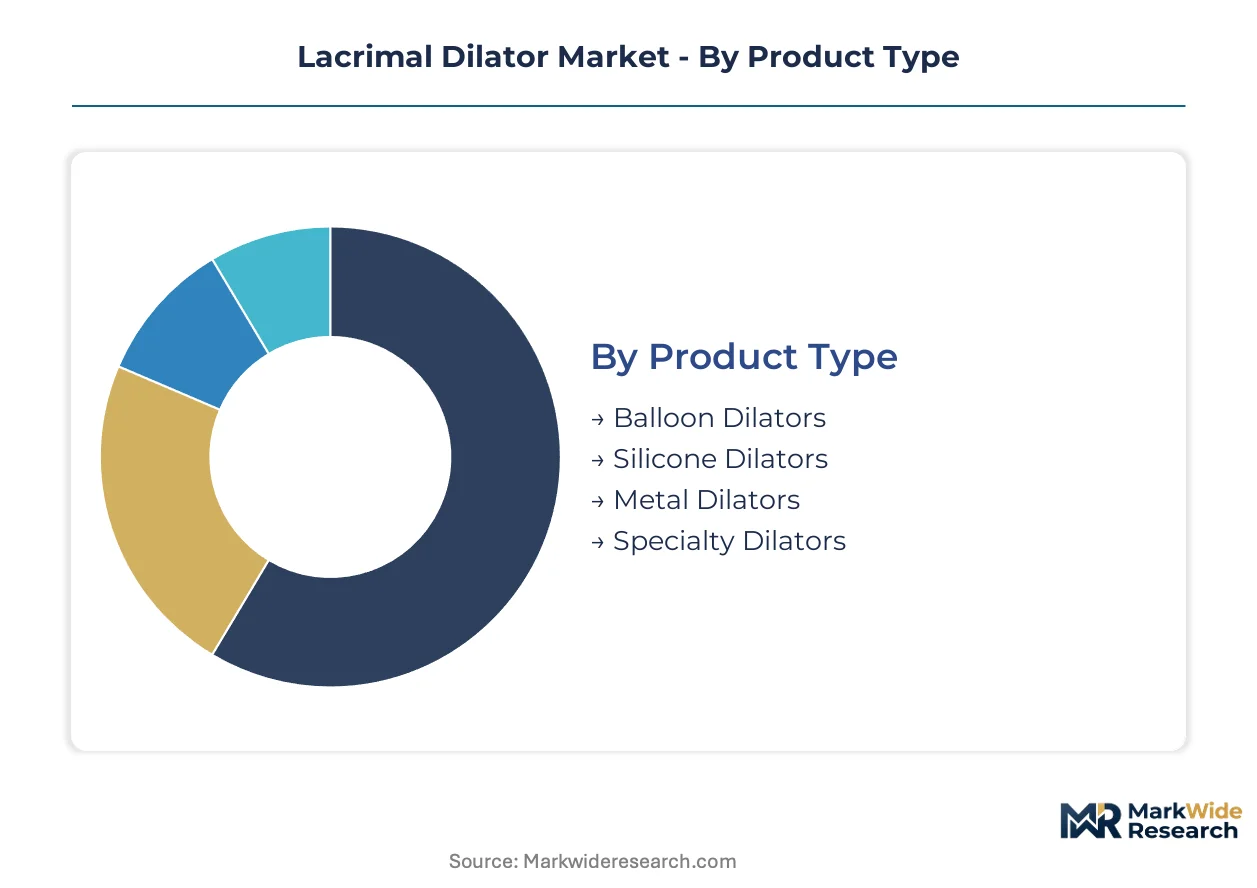
Segmentation in the lacrimal dilator market reveals how procedural complexity, reimbursement pathways, and sterilization infrastructure shape purchasing behavior across healthcare settings. Understanding these divisions exposes where margin pools concentrate and which technology transitions will disrupt incumbent supply relationships.
Product Type:
Cost tier separates buyers in this category, with capital-intensive hospitals favoring reusable formats while outpatient clinics absorb premium single-use pricing for operational simplicity.
- Balloon Dilators:Controlled radial expansion systems employ pressure-monitored polymer membranes for precise duct dilation without mechanical trauma. Demand concentrates in German and United States specialty eye centers where reduced operative time justifies higher per-procedure instrument costs against bundled reimbursement rates.
- Metal Dilators:Surgical-grade stainless steel and titanium instruments with calibrated taper diameters support repeated sterilization cycles in high-volume hospital settings. United States health systems with fixed autoclave infrastructure sustain demand despite longer procedure times, as capital avoidance outweighs efficiency gains from disposable alternatives.
- Silicone Dilators:Biocompatible polymer construction targets pediatric applications and revision surgeries where tissue trauma minimization commands premium positioning in Japanese university hospitals.
- Specialty Dilators:Hybrid designs and procedure-specific configurations serve niche anatomical variations in complex congenital cases.
Metal dilators lead volumes today; balloon dilators are gaining share fastest.
Therapy Area:
Application urgency determines procurement speed, with acute infection pathways demanding immediate instrument availability while elective procedures tolerate longer sourcing cycles.
- Ophthalmology:Comprehensive tear drainage disorder management spans diagnostic punctal probing through definitive surgical correction across tertiary referral networks.
- Eye Surgery:Dacryocystorhinostomy and related orbital procedures consume the highest instrument volumes in North American and Western European hospital systems.
- Dacryocystitis:Acute nasolacrimal duct infection requires urgent dilation intervention, driving emergency department stocking requirements and rapid sterilization turnaround protocols in United States urban medical centers.
- Allergic Conjunctivitis:Chronic inflammation with secondary punctal stenosis generates recurring dilation needs in allergy-specialty practices.
Eye surgery commands the largest addressable base; dacryocystitis creates the most time-sensitive procurement patterns.
End User:
Customer type dictates contract structure, with integrated delivery networks leveraging volume aggregation while independent specialists prioritize instrument flexibility.
- Specialty Eye Centers:Focused ophthalmology facilities generate concentrated procedural volumes that amortize capital equipment investments in balloon dilation systems, particularly across Texas and Florida metropolitan markets.
- Hospitals:Multi-service institutions balance reusable metal instrument depreciation against disposable supply chain complexity within centralized sterile processing departments.
- Outpatient Clinics:Ambulatory settings favor pre-sterilized single-use kits that eliminate reprocessing logistics and reduce regulatory documentation burdens.
- Home Care Settings:Minimal penetration limited to maintenance dilation in rare chronic cases under remote physician supervision.
Hospitals retain the installed base; specialty eye centers are expanding capacity most aggressively.
Delivery Mode:
Technology maturity separates adoption curves, with established manual techniques defending share against capital-intensive automated alternatives.
- Surgical Procedures:Operating room-based dacryocystorhinostomy under direct visualization remains the reimbursement-optimized standard in Medicare and commercial payer environments.
- Manual Dilatation:Bougienage and graduated mechanical dilation persist in resource-constrained settings and pediatric populations.
- Automated Systems:Pressure-feedback balloon inflation with real-time monitoring reduces operator variability and training requirements in German university hospital adoption.
- Telemedicine:Remote preoperative planning and postoperative surveillance creates adjunct demand for disposable dilator kits in geographically dispersed patient populations.
Surgical procedures anchor current practice; automated systems are climbing the fastest as training costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospital networks concentrate advanced balloon dilation adoption, while aging demographics across Japan and the United States sustain procedural volume expansion for metal and silicone formats.
United States
Medicare reimbursement pathways for dacryocystorhinostomy procedures drive hospital system procurement of reusable metal dilators alongside emerging balloon systems. FDA 510(k) clearance timelines for ophthalmic surgical instruments compress market entry windows for polymer-based innovations. Texas and Florida metropolitan specialty eye centers are retrofitting procedure suites to accommodate controlled radial expansion technology at accelerated pace.
Germany
EU MDR technical documentation requirements extend approval cycles for small-batch silicone dilator variants while sustaining demand for standardized stainless steel instruments. CE marking under tightened ophthalmic device regulations demands extended clinical follow-up data from reusable instrument manufacturers. Bavarian and North Rhine-Westphalian university hospitals anchor adoption of automated balloon inflation systems with real-time pressure monitoring.
Japan
METI-tracked surgical volumes in tertiary ophthalmology centers generate recurring instrument replacement cycles across metal and biocompatible polymer formats. PMDA regulatory frameworks govern material biocompatibility standards for pediatric silicone dilator applications. Tokyo and Osaka metropolitan hospital networks concentrate premium positioning for congenital nasolacrimal obstruction repair procedures.
India
CDSCO-registered distribution channels expand into tier-two cities where dacryocystorhinostomy capacity scales rapidly across outpatient clinic networks. Central Drugs Standard Control Organization import licensing requirements shape procurement timelines for European and North American instrument suppliers. Maharashtra and Gujarat ophthalmology clusters absorb volume growth in manual dilation instruments for resource-constrained surgical settings.
United Kingdom
NHS England procurement frameworks favor standardized metal dilator formats within centralized sterile processing departments of multi-service hospital trusts. MHRA post-Brexit regulatory alignment with EU MDR standards maintains continuity for CE-marked instrument recognition. London and Southeast England specialty eye centers concentrate private-pay balloon dilation adoption outside NHS reimbursement pathways.
Lacrimal Dilator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in biocompatible polymer processing and automated inflation systems. The vendor base stratifies across three functional tiers: diversified ophthalmic conglomerates with broad surgical portfolios, specialized instrument manufacturers with focused dacryology expertise, and regional fabricators serving price-sensitive procurement channels. Two dominant competitive moves are reshaping positioning: backward integration into polymer extrusion capabilities to secure compliant tubing supply, and captive distribution network construction to disintermediate traditional medical-surgical intermediaries.
Within the specialized instrument tier, FCI Ophthalmics, BVI Medical, and OASIS Medical exemplify contrasting geographic and channel strategies. FCI Ophthalmics anchors European manufacturing footprint advantages for consistent supply to ophthalmology departments. BVI Medical occupies a position emphasizing product specialization in balloon and silicone formats. OASIS Medical represents direct-to-clinic distribution control reaching outpatient surgery centers in high-growth United States metropolitan markets.
| Leading Market Players |
|---|
| FCI Ophthalmics |
| BVI Medical |
| OASIS Medical |
| Aurolab |
| Kaneka |
| Beaver-Visitec |
| Rumex International |
| Alcon Inc. |
| Bausch + Lomb |
| Others |
Pricing and Supply Chain Analysis
Specialty eye center procurement teams now mandate multi-source qualification for balloon catheter tubing, forcing polymer extrusion suppliers to absorb FDA biocompatibility testing costs that compress margins across German and United States manufacturing footprints.
Pricing Analysis
Input-cost pass-through from surgical-grade titanium sponge volatility anchors metal dilator pricing, with European reusable instrument manufacturers absorbing feedstock fluctuations rather than risking hospital contract loss. Pricing stratifies across premium silicone pediatric formats, standard stainless steel reusable sets, and economy polymer single-use alternatives. Cost compression in balloon membrane production intensifies as Midwest extrusion facilities consolidate, while outpatient clinics prove least price-sensitive due to operational simplicity premiums.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital systems and German university hospitals now mandate qualified secondary suppliers for all polymer tubing grades, fragmenting procurement leverage. Manufacturing concentrates in Germany, the United States, and Japan for precision metalwork; China and India dominate polymer component fabrication. Supply chain risk centers on single-source dependence for medical-grade silicone sheeting. Distribution runs through captive direct-to-clinic networks and traditional medical-surgical intermediaries in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU MDR documentation burdens delay European small-batch entrants while FDA 510(k) streamlining accelerates United States commercialization timelines for equivalent polymer innovations.
For Market Incumbents: Anticipate balloon dilator commoditization by securing backward integration into polymer extrusion capabilities before Midwest tubing supply tightens further. Cement hospital system relationships through reusable metal instrument service contracts that offset capital avoidance preferences. Priority lever rests on quality management consolidation to absorb EU MDR clinical evidence burdens that fragment smaller Italian and French competitors. For New Entrants and Emerging Players: Tier-two Indian outpatient clinics represent the most penetrable buyer archetype, with CDSCO registration pathways shorter than FDA or CE marking cycles for manual dilation formats. Capture volume through consignment stocking models that eliminate sterile processing infrastructure requirements. White-space targets include pediatric silicone dilators for Japanese university hospitals and telemedicine-guided disposable kits for remote-supervised procedures. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized instrument manufacturers possessing captive European manufacturing footprints and established ophthalmology department relationships. Five-to-ten year viability hinges on automated dilation system integration capabilities. Signal to monitor: FDA digital health guidance finalization affecting algorithm-assisted procedural planning tool valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Secures compliant tubing supply against Midwest concentration risk for balloon catheter manufacturers. |
| CE Marking Pathway Investment | Absorbs EU MDR technical documentation burdens that delay small-batch silicone dilator approvals. |
| Direct-to-Clinic Distribution Buildout | Disintermediates traditional medical-surgical distributors in Texas and Florida metropolitan markets. |
| Automated Balloon Inflation Development | Reduces operator variability in German university hospital adoption of pressure-feedback systems. |
| Pediatric Silicone Segment Expansion | Captures premium positioning in Japanese university hospitals for congenital obstruction repair. |
Research Methodology
Direct dialogue with ophthalmic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative findings, cross-referenced against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up and top-down triangulation validated volume estimates across product categories and geographies.
Bottom-up modeling anchored projections, with top-down macro checks against METI surgical volume tracking and tertiary ophthalmology center capacity expansion plans. Segmentation dimensions spanned product format, therapy area, end-user setting, and delivery mode. CAGRs derived from procedure volume elasticity to aging demographic penetration and technology substitution curves for balloon versus metal dilator adoption.
Underlying measurement precision varies by segment; metal dilator replacement cycles and established hospital procurement data carry tighter precision than emerging automated system forecasts. Projections reflect assumptions regarding FDA digital health guidance timing and EU MDR auditor availability. Deviation in titanium feedstock pricing or Midwest polymer extrusion capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Cranial Perforator Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Global Pulmonary Drug Delivery Systems Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Gastric Bands Market