
 Clinical Rollators Market | 2026-2036
Clinical Rollators Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Rollators Market Analysis
ISO 11199-2 certification for walking aids is redrawing competitive boundaries in the clinical rollators sector, forcing manufacturers to demonstrate sustained load-bearing performance and braking reliability under standardized test conditions. Invacare Corp. leverages extensive rehabilitation channel relationships across North America to sustain institutional placement rates. Compass Health Brands anchors its position through diversified homecare distribution, while DRIVE MEDICAL GMBH & CO. KG competes aggressively on European tender pricing for hospital systems.
Clinical rollators are wheeled ambulatory assistive devices engineered with aluminum or steel tubing frames, typically supporting users up to 150 kg, incorporating hand-operated brakes, height-adjustable handles, and optional seat platforms for intermittent rest during gait rehabilitation. Four-wheel configurations dominate hospital procurement due to superior stability on polished corridors, while carbon fiber variants command premium positioning in elderly care facilities where caregiver handling strain drives lightweight prioritization. Homecare channels favor foldable aluminum models that simplify transport and storage in residential environments.
FDA 510(k) clearance requirements govern US market entry for powered or novel braking rollator designs, while the EU Medical Device Regulation mandates notified body oversight for Class I devices with measuring function. Japan's Ministry of Health, Labour and Welfare applies PMDA-equivalent standards through the Pharmaceuticals and Medical Devices Agency for imported assistive devices. Stakeholders must monitor evolving reimbursement coding distinctions between standard walkers and rollators with seats, as these classifications determine patient out-of-pocket exposure and institutional purchasing volumes across Medicare, Medicaid, and comparable national health frameworks.
Market Dynamics
ISO 11199-2 certification requirements are compressing product development timelines and redistributing competitive advantage toward manufacturers with established testing infrastructure and rehabilitation channel relationships.
Growth Catalysts
- Statutory Long-Term Care Insurance:Germany's mandatory coverage for assistive devices eliminates patient cost barriers and sustains institutional procurement volumes through predictable reimbursement pathways.
- Post-Surgical Mobility Protocols:Rehabilitation centers are tightening ambulatory care standards, mandating four-wheel rollators with seat attachments for supervised gait training programs.
- Carbon Fiber Manufacturing:Advanced composite fabrication is enabling sub-6 kg frame weights that reduce caregiver handling strain in elderly care facilities.
Market Restraints
- Aluminum Price Volatility:Primary aluminum input costs fluctuate with energy pricing, squeezing margin structures for mid-tier manufacturers dependent on commodity-grade tubing.
- Notified Body Bottlenecks:EU MDR oversight requirements for Class I measuring-function devices extend clearance timelines by 8-14 months versus legacy Medical Device Directive pathways.
- Standard Walker Substitution:Basic folding walkers without wheels retain cost advantage in price-sensitive homecare segments where intermittent use patterns dominate.
Strategic Opportunities
- Japan's Super-Aged Society:METI procurement guidelines favor lightweight assistive devices, creating entry pathways for ISO-certified exporters addressing 29% population cohort over 65.
- Telehealth-Integrated Monitoring:Convergence of rollator-mounted sensors with remote patient monitoring platforms enables fall-risk analytics subscription revenue streams.
- Hospital-at-Home Expansion:CMS reimbursement expansion for acute care substitution is redirecting durable medical equipment procurement toward residential delivery channels.
Industry Challenges
- Biomechanical Engineer Scarcity:Specialized talent for anthropometric fitting and gait analysis remains concentrated in university rehabilitation science departments, constraining R&D throughput.
- ISO 11199 Testing Backlogs:Accredited laboratory capacity for sustained load-bearing and braking reliability validation is creating 4-6 month queue delays for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Rollators Market |
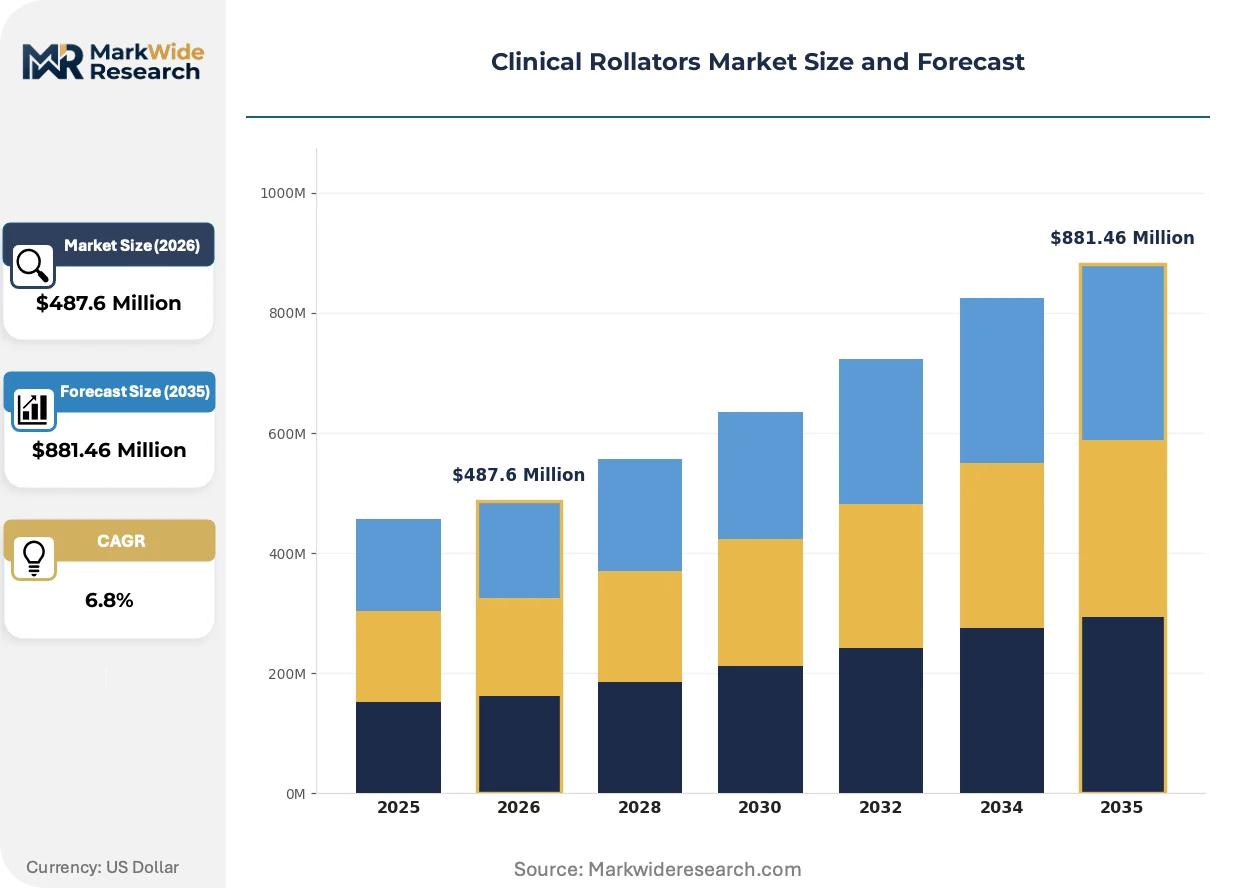
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheel, Four-Wheel, Anterior, Heavy-Duty Material: Aluminum, Steel, Plastic, Carbon Fiber End User: Hospitals, Homecare, Rehabilitation Centers, Elderly Care Facilities Feature: Foldable, Adjustable Height, Lightweight, Wheel Locks |
| Companies Covered | Compass Health Brands, Human Care HC AB, Invacare Corp., Cardinal Health Inc., DRIVE MEDICAL GMBH & CO. KG, Sunrise Medical LLC, GF Health Products Inc., Besco Medical Ltd., Medline Industries LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Rollators Market Emerging Trajectories
Carbon fiber composites and embedded sensor systems are redefining product architecture while regulatory harmonization efforts and procurement model evolution are restructuring commercial pathways across institutional and residential segments.
Carbon fiber layup construction is supplanting welded aluminum tubing in premium clinical rollator segments. Elderly care facilities in Scandinavia and Germany are adopting these sub-5 kg configurations to comply with manual handling injury prevention mandates. The technology is compressing traditional price-performance tradeoffs by delivering hospital-grade stability at weights previously achievable only in consumer-grade products.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to maintain post-market surveillance systems for Class I devices with measuring functions. This obligation is elevating compliance costs disproportionately for smaller European manufacturers serving regional hospital systems. German and French notified bodies are experiencing 40% application volume increases, extending review timelines and favoring enterprises with dedicated regulatory affairs functions.
Hospital procurement departments are consolidating durable medical equipment purchasing through group purchasing organizations and integrated delivery networks. Independent home medical equipment dealers are losing shelf space to direct manufacturer contracts with large health systems. The concentration is most visible in the United States, where three national GPOs now influence procurement decisions for over 60% of acute care beds.
Clinical Rollators Market Segmentation
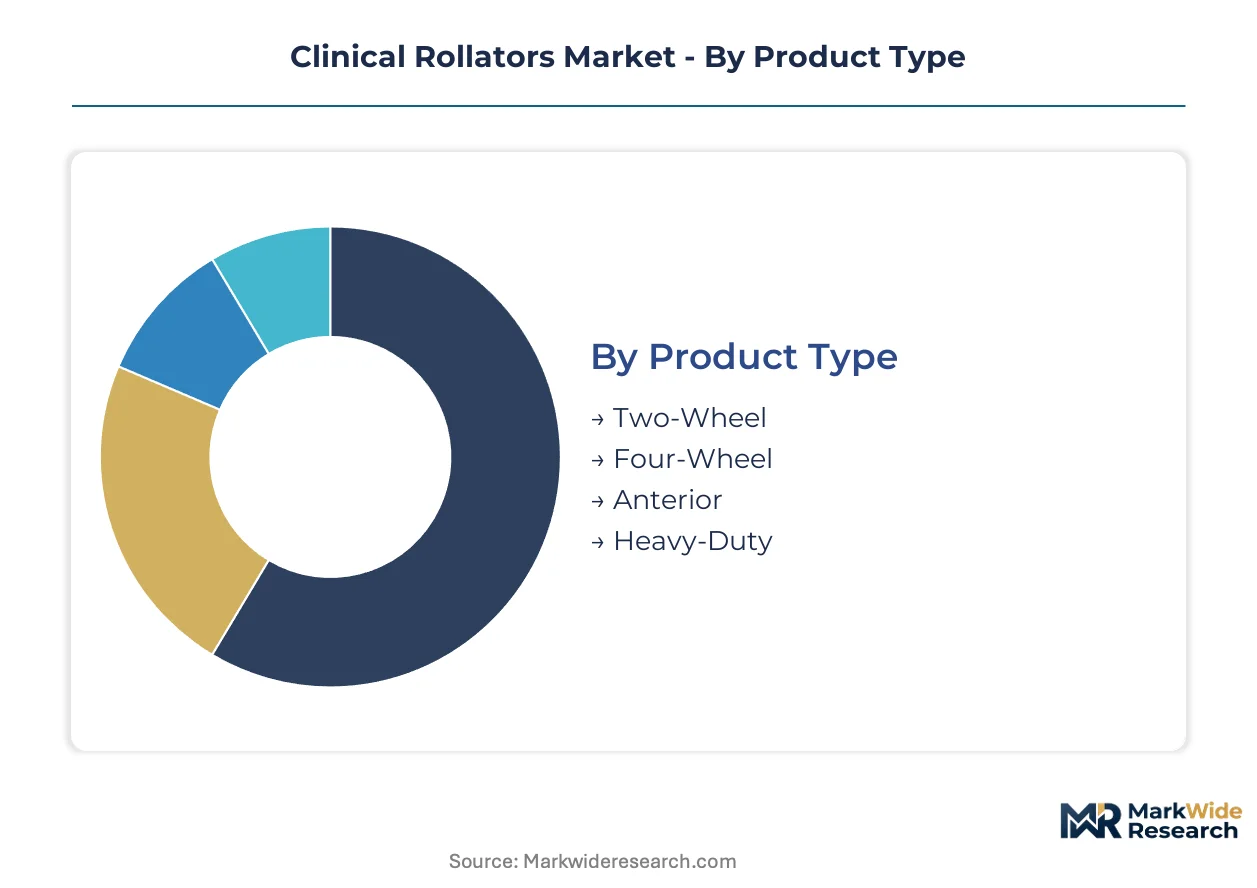
Clinical rollators segment across functional design, material engineering, care setting, and user-adjustable features. Each dimension carries distinct regulatory footprints and reimbursement coding implications that shape manufacturer R&D prioritization and channel economics.
Product Type:
FDA 510(k) clearance pathways diverge sharply between powered braking systems and purely mechanical designs, concentrating development resources toward configurations with established predicate devices.
- Four-Wheel:Configurations incorporate seat platforms and dual braking systems for supervised gait rehabilitation. German rehabilitation centers and Scandinavian elderly care facilities drive procurement volumes through statutory long-term care insurance coverage and manual handling injury prevention mandates.
- Heavy-Duty:Reinforced frames support users above 150 kg with wider wheelbases and enhanced stability geometry. Bariatric care units in US hospital systems and specialized German eldercare facilities generate demand as obesity prevalence rises in aging populations.
- Two-Wheel:Lighter frames suit patients with preserved upper body strength for lift-and-step gait patterns.
- Anterior:Forward-positioned wheels enable reciprocal stepping with trunk support for neurological rehabilitation.
Established volume favors Four-Wheel; emerging adoption favors Heavy-Duty.
Material:
Cost tier stratification separates premium composite offerings from commodity metal tubing, with ISO 11199-2 load-bearing certification requirements filtering supplier capabilities.
- Carbon Fiber:Advanced layup construction achieves sub-5 kg frame weights while maintaining hospital-grade stability ratings. Scandinavian and German facilities prioritize these configurations to comply with caregiver injury prevention regulations and reduce workers compensation exposure.
- Aluminum:Anodized 6061-T6 tubing dominates mid-tier procurement through favorable strength-to-weight ratios and established welding automation. Primary aluminum price volatility squeezes margin structures for manufacturers without long-term supply contracts or scrap recycling programs.
- Steel:Lower material costs attract price-sensitive homecare channels despite weight penalties.
- Plastic:Injection-molded components reduce secondary operations for seat platforms and handgrips.
Volume concentration sits with Aluminum; margin expansion concentrates in Carbon Fiber.
End User:
Procurement authority patterns split between institutional purchasing departments and individual patient acquisition through durable medical equipment suppliers.
- Hospitals:Group purchasing organizations consolidate acquisition decisions for acute care beds, favoring four-wheel configurations with seat attachments for post-surgical mobility protocols. US health systems and German hospital networks drive standardization toward ISO-certified models with predictable reimbursement coding.
- Homecare:Individual patients and family caregivers select foldable aluminum models through Medicare Part B suppliers and German statutory health insurance contracted dealers. CMS reimbursement expansion for hospital-at-home programs is redirecting procurement toward residential delivery channels.
- Rehabilitation Centers:Supervised gait training programs mandate specific braking and stability specifications.
- Elderly Care Facilities:Caregiver handling strain drives lightweight prioritization and injury prevention compliance.
Institutional procurement favors Hospitals; patient-directed acquisition favors Homecare.
Feature:
Functional differentiation determines reimbursement classification and out-of-pocket exposure across national health frameworks.
- Foldable:Collapsible frame designs enable transport and residential storage without disassembly. Homecare channels in the United States and Germany prioritize these configurations for intermittent use patterns and limited living space constraints.
- Lightweight:Sub-6 kg total weight reduces caregiver burden and expands patient self-propulsion capability. Japanese METI procurement guidelines explicitly favor lightweight assistive devices for super-aged society applications.
- Adjustable Height:Telescoping handle mechanisms accommodate anthropometric variation across patient populations.
- Wheel Locks:Parking brake systems satisfy institutional safety protocols for seated rest periods.
Universal demand concentrates in Foldable; premium positioning clusters around Lightweight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory long-term care insurance creates a policy template that neighboring economies are adapting. Reimbursement certainty drives procurement volumes while ISO certification requirements filter market entry across developed healthcare systems.
United States
Hospital-at-home expansion and CMS reimbursement redirection sustain institutional procurement volumes. FDA 510(k) clearance governs powered braking rollator designs, extending development timelines for novel configurations. The Midwest manufacturing corridor around Chicago anchors durable medical equipment distribution networks serving Medicare Part B suppliers.
Germany
Statutory long-term care insurance eliminates patient cost barriers for assistive devices. EU MDR notified body oversight applies to Class I measuring-function rollators, compressing clearance timelines for unprepared manufacturers. The Ruhr industrial cluster hosts rehabilitation equipment fabricators supplying statutory health insurance contracted dealers.
Japan
METI procurement guidelines explicitly favor lightweight assistive devices for super-aged society applications. PMDA-equivalent standards through the Pharmaceuticals and Medical Devices Agency regulate imported devices. The Kansai region around Osaka concentrates elderly care facility procurement decisions for carbon fiber rollator adoption.
United Kingdom
NHS procurement consolidation through integrated care systems redirects rollator purchasing toward standardized frameworks. MHRA oversight applies post-Brexit, maintaining alignment with EU MDR technical documentation requirements. The Midlands manufacturing belt hosts aluminum tubing suppliers serving rehabilitation equipment assemblers.
France
ANSM oversight and national health insurance reimbursement coding determine patient out-of-pocket exposure for seated rollators versus standard walkers. CSRD reporting obligations extend to medical device distributors above threshold revenues. The Lyon biomedical cluster anchors rehabilitation science research influencing anthropometric fitting protocols.
Clinical Rollators Market Vendor Landscape
Player mix skews toward diversified health conglomerates with rehabilitation channel relationships and specialized European fabricators with ISO certification infrastructure. The vendor base concentrates around three strategic archetypes: North American institutional suppliers leveraging GPO relationships, German-engineered premium manufacturers competing on tender pricing, and diversified medical device conglomerates spanning homecare distribution. Competitive moves center on M&A for rehabilitation channel access and backward integration into aluminum tubing supply.
Among diversified health conglomerates, Cardinal Health Inc. and Medline Industries LP occupy positions anchored by institutional purchasing relationships and national distribution footprints. Invacare Corp. exemplifies the rehabilitation-focused archetype with established North American channel presence. DRIVE MEDICAL GMBH & CO. KG represents European engineering-driven competition with aggressive positioning on hospital system tenders.
| Leading Market Players |
|---|
| Compass Health Brands |
| Human Care HC AB |
| Invacare Corp. |
| Cardinal Health Inc. |
| DRIVE MEDICAL GMBH & CO. KG |
| Sunrise Medical LLC |
| GF Health Products Inc. |
| Besco Medical Ltd. |
| Medline Industries LP |
| Others |
Supply Flow & Price Mechanics
ISO 11199-2 certification gates both supplier qualification and price differentiation simultaneously, compressing mid-tier manufacturers between premium carbon fiber positioning and commodity aluminum competition while extending development timelines that reshape procurement economics across institutional buyers.
Pricing Analysis
Cost-plus contracts with primary aluminum indexation dominate mid-tier manufacturer agreements, exposing margin structures to energy price volatility. Three-tier pricing structure across premium carbon fiber, standard aluminum, and economy steel configurations separates ISO-certified hospital-grade models from homecare commodity offerings. Pricing pressure stems from notified body bottlenecks extending clearance timelines and squeezing working capital for unprepared entrants. Homecare channels exhibit highest price sensitivity due to patient out-of-pocket exposure, while German statutory insurance coverage insulates institutional procurement.
Supply Chain Analysis
Germany and China anchor aluminum tubing fabrication and carbon fiber layup manufacturing respectively, with the Ruhr industrial cluster hosting rehabilitation equipment assemblers and Guangdong province supplying injection-molded seat components. Primary aluminum draws from smelters in Iceland and Norway, while carbon fiber precursors rest on Japanese PAN supply. Single-source vulnerability concentrates in accredited ISO 11199 testing laboratories creating validation queue delays. Distribution runs through group purchasing organizations in the United States and statutory health insurance contracted dealer networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber manufacturing convergence with embedded sensor systems signals high-growth disruption as telehealth-integrated rollators redefine reimbursement economics and care delivery models.
For Market Incumbents: Fortify rehabilitation channel control through exclusive GPO contracts and backward integration into aluminum tubing supply to defend against carbon fiber substitution threats. Accelerate ISO 11199-2 certification pipelines to exploit testing laboratory capacity constraints that disadvantage smaller competitors. Prioritize sensor platform development for remote patient monitoring subscription revenue streams. For New Entrants and Emerging Players: Lead with lightweight carbon fiber configurations targeting Japanese METI procurement guidelines and Scandinavian caregiver injury prevention mandates as the most penetrable white-space segments. Exploit hospital-at-home program expansion in the United States where CMS reimbursement redirection creates direct-to-patient delivery channel openings. Position through durable medical equipment dealers losing shelf space to GPO consolidation. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by elevating compliance costs disproportionately for smaller European manufacturers lacking dedicated regulatory affairs functions. Five-to-ten year viability favors diversified health conglomerates with rehabilitation channel relationships and ISO-certified fabrication infrastructure over pure-play commodity assemblers. Monitor notified body application volume trends as inflection indicator for clearance timeline compression and competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11199-2 Certification Acceleration | Testing laboratory queue delays favor manufacturers with established validation infrastructure and predicate device portfolios. |
| Carbon Fiber Manufacturing Scale-Up | Sub-5 kg frame weights unlock Scandinavian and German elderly care facility procurement under manual handling injury prevention mandates. |
| Telehealth Sensor Platform Development | Fall-risk analytics subscription revenue streams reposition rollators from capital equipment to recurring service models. |
| Hospital System GPO Consolidation | Direct manufacturer contracts with three national US GPOs now influence procurement decisions for over sixty percent of acute care beds. |
| Japanese PMDA-Equivalent Compliance Pathway | METI procurement guidelines for lightweight assistive devices create structured entry for ISO-certified exporters addressing super-aged society demand. |
Methodological Framework
Operator-level perspectives from rehabilitation equipment procurement managers, biomedical engineers, GPO contracts specialists, and statutory health insurance reimbursement officers anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, EU MDR notified body registers, CMS Medicare durable medical equipment claims databases, and German statutory long-term care insurance utilization records. Bottom-up segment sizing and top-down macroeconomic triangulation cross-verified volume estimates.
Sensitivity analysis framed analytical approach across the projection horizon, modeling product type, material engineering, care setting, and reimbursement coding dimensions. CAGRs derived from segment-level growth rate synthesis and macroeconomic elasticity coefficients. Forecast inputs incorporated aluminum price volatility scenarios and notified body capacity expansion assumptions.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways, EU MDR Class I oversight, and German statutory long-term care insurance coverage; material policy shifts in reimbursement coding or certification requirements would require re-modeling. Recalibration cycles align with material shifts in raw material input costs, regulatory timeline changes, and hospital-at-home program expansion velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Needle Destroyer Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Band Ligators Market