
 South Africa Artificial Organs and Bionic Implants Market | 2026-2036
South Africa Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Artificial Organs and Bionic Implants Market Analytics
South Africa's national health insurance roadmap is shifting procurement priorities toward domestically registered implantable devices with established reimbursement pathways. Medtronic leverages its cardiac rhythm portfolio to anchor hospital supply agreements across Gauteng and Western Cape provinces. Cochlear Ltd specializes in auditory implant systems for pediatric patients through academic hospital networks. Berlin Heart sustains its position in ventricular assist devices via partnerships with cardiothoracic referral centers.
Artificial organs and bionic implants comprise electromechanical or biological substitute systems designed to replace or augment native physiological functions, typically incorporating biocompatible alloys, polymers, or bioceramic composites manufactured through precision machining or additive fabrication processes. These devices restore motor, sensory, or organ-level performance in patients with congenital defects, trauma, or degenerative conditions. The cardiovascular application category leads current volume, driven by pacemaker and heart valve demand among aging populations with ischemic disease profiles. Robotics technology represents the fastest-expanding segment, as powered exoskeletons and myoelectric prosthetics gain traction in rehabilitation centers. The orthopedic application category maintains mature growth patterns, with margin pools concentrating in revision joint replacements and custom limb prosthetics.
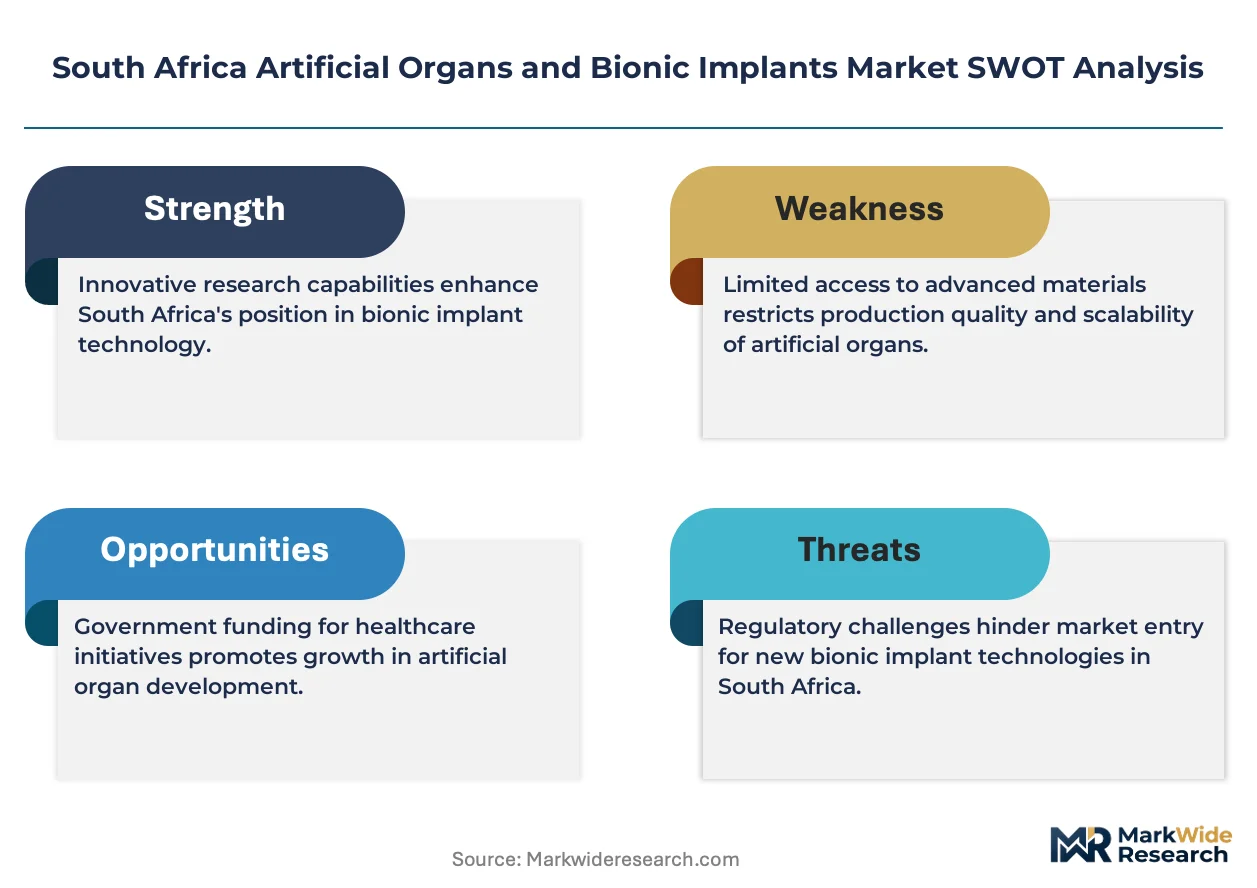
South Africa's Health Products Regulatory Authority enforces medical device registration aligned with ISO 13485 quality management and biocompatibility testing protocols, while the South African Bureau of Standards certifies structural integrity for load-bearing implants. These frameworks extend product development timelines but elevate barrier thresholds against unregistered imports. Stakeholders must monitor alignment between national health insurance reimbursement schedules and regulatory approval pathways to secure sustainable market access.
Market Dynamics
South Africa's national health insurance procurement reforms are redistributing purchasing authority from provincial hospitals to centralized tender boards, compressing vendor negotiation cycles and privileging suppliers with established reimbursement codes.
Growth Catalysts
- NHI Procurement Centralization:Consolidated tender boards under the national health insurance framework are streamlining multi-year supply agreements for cardiac assist devices, reducing vendor acquisition friction.
- ISO 13485 Alignment:The Health Products Regulatory Authority's harmonization with international quality management standards is accelerating registration pathways for biocompatible implantable alloys and polymers.
- Gauteng Surgical Clustering:Concentration of cardiothoracic and orthopedic referral centers in Johannesburg and Pretoria is generating procedure volume density that justifies dedicated device inventory and technical support infrastructure.
Market Restraints
- Biocompatibility Testing Costs:Extended ISO 10993 cytotoxicity and sensitization protocols for novel polymer composites are elevating pre-market validation expenditures for domestic manufacturers.
- Import Dependency for Precision Components:Additive fabrication systems and bioceramic feedstocks concentrate supply among German and Swiss equipment vendors, exposing procurement to currency volatility.
- Substitution by Conservative Management:Pharmaceutical regimens for congestive heart failure are delaying ventricular assist device implantation in cost-constrained public sector cases.
Strategic Opportunities
- Western Cape Expansion:Cape Town's academic medical centers are establishing pediatric cochlear implant programs with dedicated auditory rehabilitation pathways, replicating Gauteng's volume model.
- Myoelectric-Robotics Convergence:Integration of pattern-recognition software with powered upper-limb prosthetics is opening rehabilitation center contracts previously served by passive mechanical devices.
- Provincial Manufacturing Incentives:Department of Trade, Industry and Competition production-linked incentives for medical device assembly are reducing landed cost disadvantages against imported finished goods.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Cardiovascular perfusionists and implantable device specialists are concentrating in Gauteng and Western Cape urban centers, constraining procedure expansion in KwaZulu-Natal and Eastern Cape.
- Reimbursement Code Lag:Novel robotic exoskeleton systems face delays in securing national health insurance tariff classifications, compressing commercialization timelines for rehabilitation technology vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Artificial Organs and Bionic Implants Market |
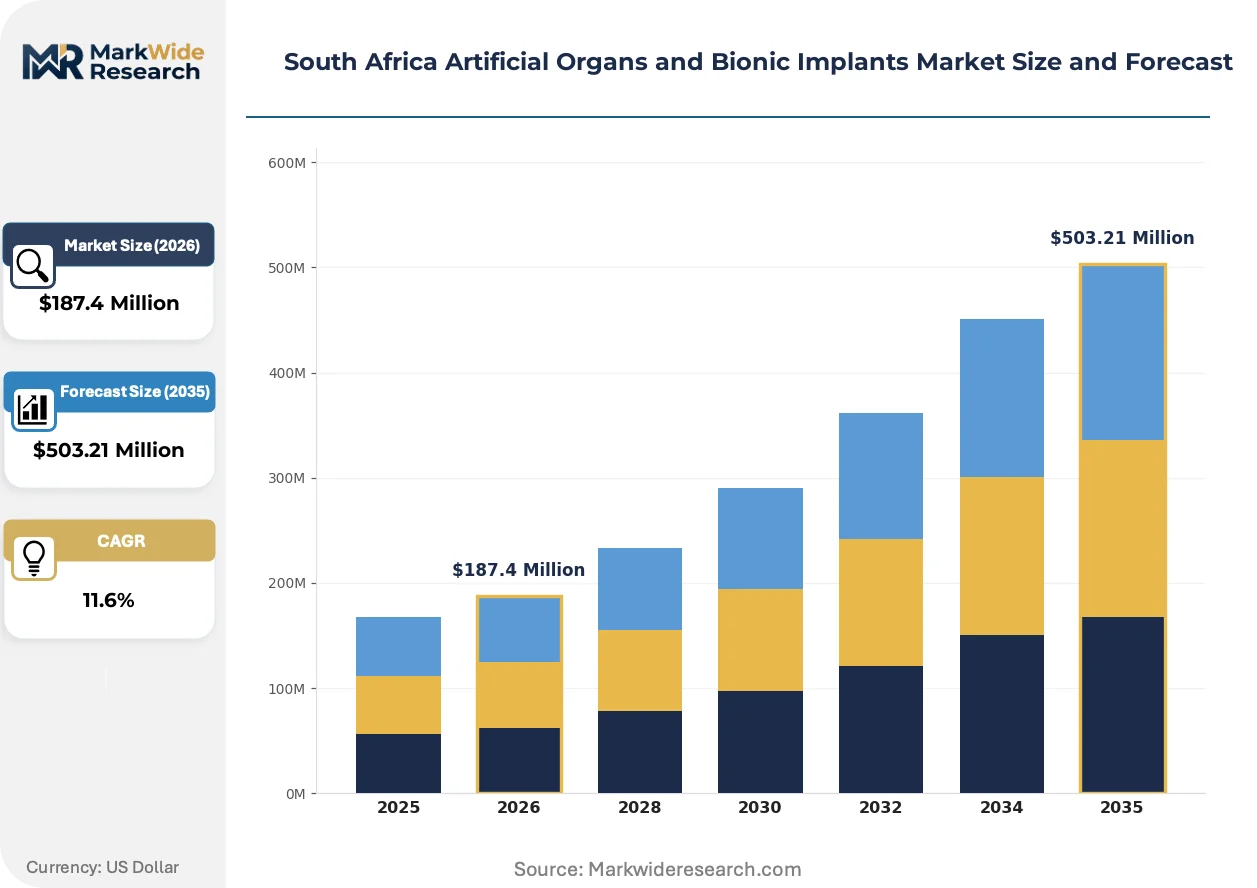
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Valves, Artificial Limbs, Cochlear Implants, Pacemakers Technology: Bioceramics, 3D Printing, Bioelectronics, Robotics End User: Hospitals, Specialty Clinics, Rehabilitation Centers, Research Institutions Application: Cardiovascular, Orthopedic, Neurological, Assistive Devices |
| Companies Covered | Abbott, Berlin Heart, Cochlear Ltd, Ossur, Sonova, Abiomed Inc., Medtronic, Zimmer Biomet, Ekso Bionics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Artificial Organs and Bionic Implants Market Evolving Landscape
Additive manufacturing of patient-specific orthopedic implants is compressing lead times for revision joint replacements, while regulatory data requirements for biocompatibility are expanding documentation burdens across the product lifecycle.
Titanium lattice structures produced through selective laser melting are replacing solid-cast femoral stems in complex revision arthroplasty cases. Academic orthopedic units in Johannesburg and Pretoria are absorbing these geometries at accelerating rates, displacing standard modular components in high-complexity procedures and compressing revision surgery intervals.
The Health Products Regulatory Authority's tightened biocompatibility surveillance protocols are extending post-market clinical follow-up obligations for permanent implants. Manufacturers must now submit annual adverse event summaries for cardiac rhythm devices, elevating compliance infrastructure costs and favoring established suppliers with dedicated regulatory affairs capacity.
Hospital procurement committees are unbundling device supply from technical service contracts, separating capital equipment acquisition from maintenance and training obligations. This disintermediation is compressing vendor margins while creating openings for independent clinical engineering firms in Gauteng's tertiary hospital networks.
South Africa Artificial Organs and Bionic Implants Market Segmentation
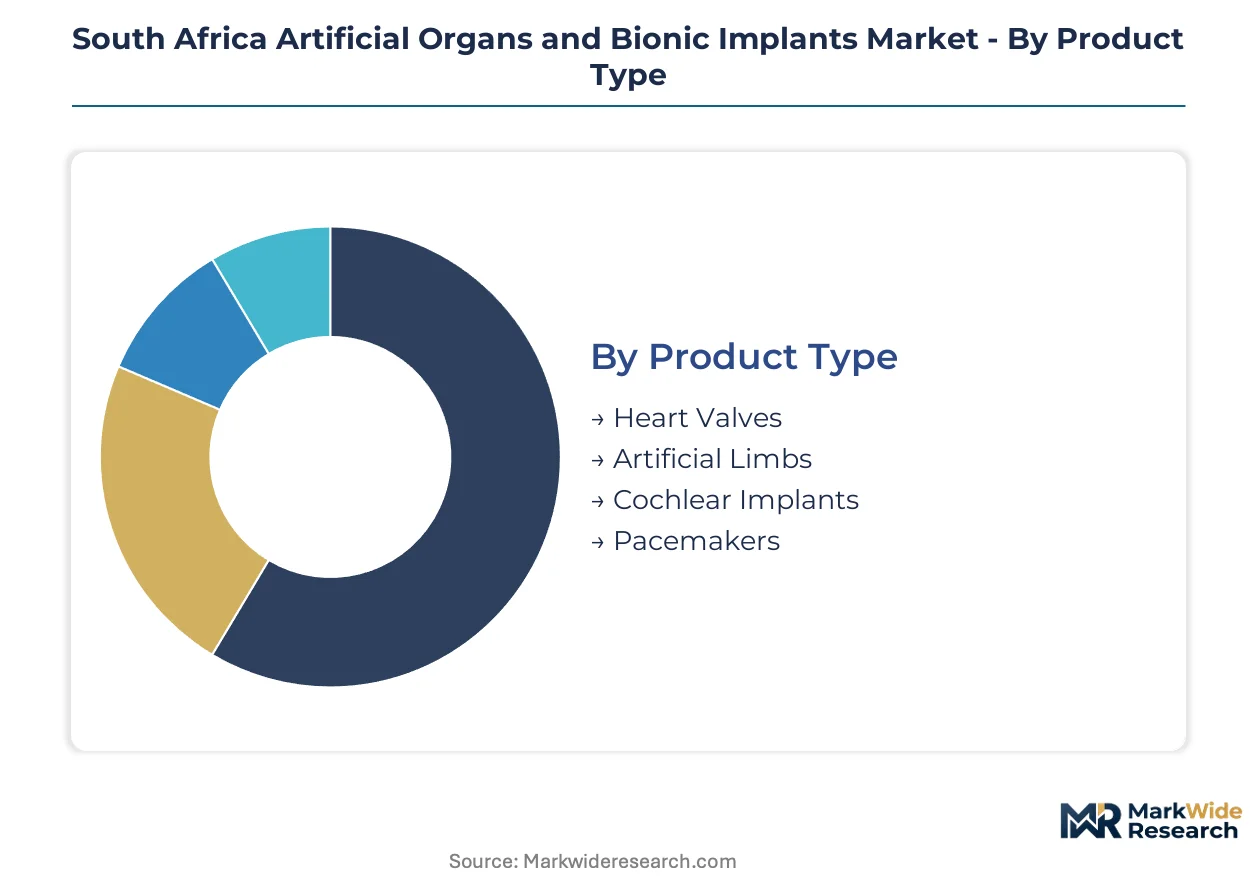
Segmentation of South Africa's artificial organs and bionic implants market reveals distinct procurement patterns across public hospital networks, private surgical centers, and academic research facilities. Each category captures different technology readiness levels and reimbursement pathway maturity.
Product Type:
Hospital procurement committees distinguish implantable devices by surgical complexity and long-term maintenance requirements.
- Heart Valves:Mechanical and bioprosthetic valve assemblies address rheumatic heart disease prevalence in Gauteng and Western Cape cardiothoracic centers. Transcatheter delivery systems are displacing open surgical replacement in tertiary referral hospitals with hybrid operating suites.
- Artificial Limbs:Modular prosthetic systems incorporating carbon fiber sockets and silicone liners serve traumatic amputation cases from mining and road traffic incidents. Above-knee configurations dominate public sector tender volumes due to diabetes-related limb loss patterns.
- Cochlear Implants:Multi-channel electrode arrays restore auditory function in pediatric congenital deafness cases through academic hospital networks in Johannesburg and Cape Town.
- Pacemakers:Dual-chamber pulse generators manage bradyarrhythmias in aging populations with ischemic cardiomyopathy profiles.
Pacemakers lead volumes today; cochlear implants are gaining share fastest.
Technology:
Manufacturing method determines regulatory pathway duration and production cost structure for South African market entrants.
- Bioceramics:Hydroxyapatite-coated titanium substrates promote osseointegration in load-bearing orthopedic applications. Alumina-zirconia composites from German feedstock suppliers dominate hip bearing surfaces in Pretoria arthroplasty units.
- 3D Printing:Selective laser melting of titanium lattice structures enables patient-specific acetabular cups and mandibular reconstruction plates. Johannesburg academic hospitals are absorbing these geometries at accelerating rates for complex revision cases.
- Bioelectronics:Implantable pulse generators and neural interface assemblies incorporate hermetic titanium enclosures with platinum-iridium electrodes.
- Robotics:Powered exoskeletons and myoelectric hand systems integrate pattern-recognition software for upper-limb rehabilitation.
Bioceramics anchor current revenue; robotics is climbing the fastest.
End User:
Facility type dictates device specification complexity and technical support service level requirements.
- Hospitals:Tertiary academic centers in Gauteng and Western Cape perform the majority of cardiac rhythm device and joint replacement procedures. Centralized tender boards under national health insurance reforms are consolidating procurement authority from provincial facilities.
- Rehabilitation Centers:Specialized facilities in Pretoria and Cape Town deliver prosthetic fitting and gait training services for traumatic amputation patients.
- Specialty Clinics:Private ENT practices in Johannesburg's northern suburbs concentrate pediatric cochlear implant candidacy assessments.
- Research Institutions:University-affiliated biomedical engineering units evaluate novel biomaterial formulations and additive manufacturing parameters.
Hospitals dominate installed base; rehabilitation centers are expanding most quickly.
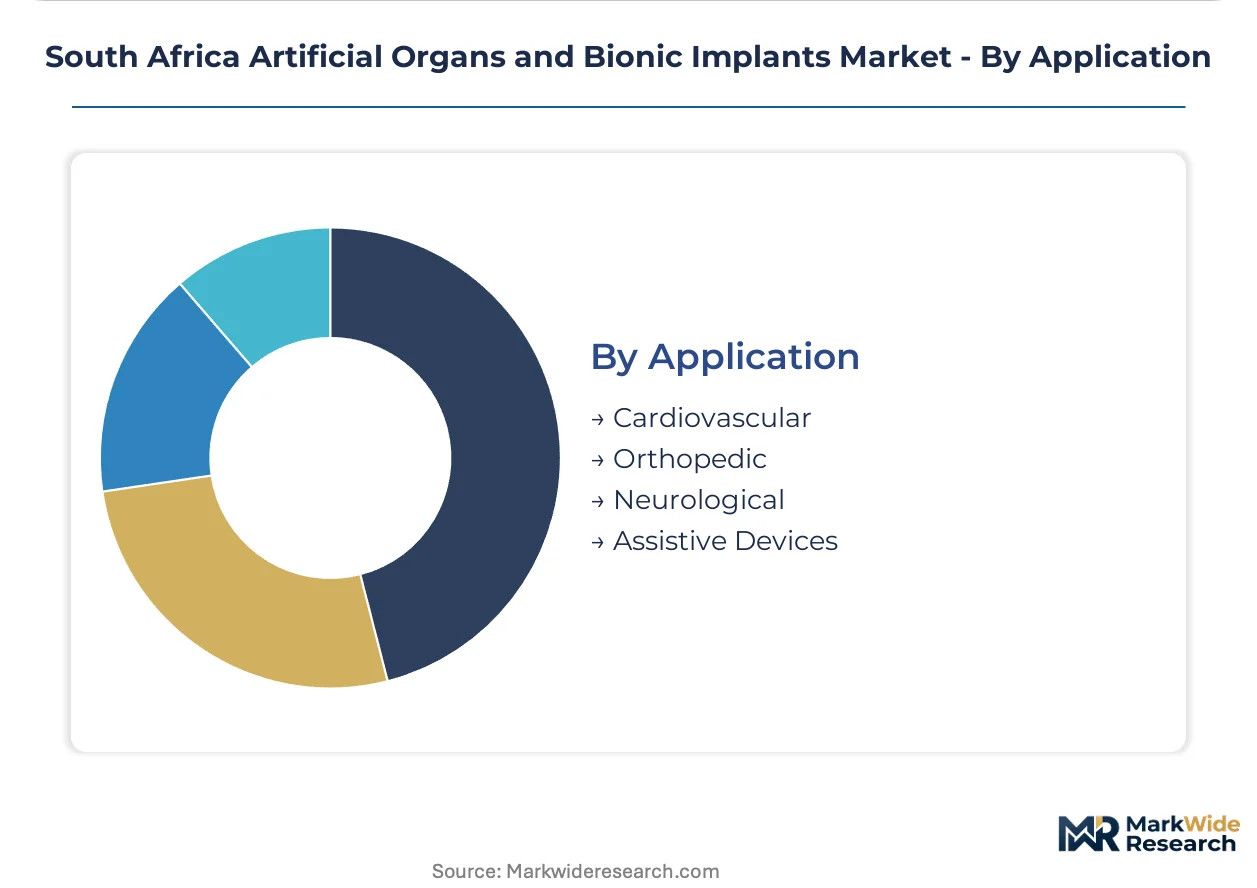
Application:
Clinical indication determines reimbursement code availability and procedure volume concentration across South Africa's provinces.
- Cardiovascular:Pacemaker implantation and heart valve replacement address ischemic disease burden in aging urban populations. Cardiac assist device procurement is rising under national health reforms targeting public hospital infrastructure.
- Orthopedic:Primary and revision joint arthroplasty serves osteoarthritis and trauma sequelae cases. Titanium lattice femoral stems from selective laser melting are displacing standard modular components in complex revision procedures.
- Neurological:Cochlear implantation and deep brain stimulation target congenital and degenerative conditions.
- Assistive Devices:Powered and passive prosthetic limbs restore function for traumatic and dysvascular amputation patients.
Cardiovascular leads procedure counts today; assistive devices show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular perfusionists and implantable device specialists cluster in Gauteng and Western Cape urban centers, constraining procedure expansion in KwaZulu-Natal and Eastern Cape provinces. This workforce concentration shapes procurement patterns and hospital infrastructure investment across South Africa's provincial health systems.
Gauteng
Johannesburg and Pretoria host the country's largest cardiothoracic and orthopedic surgical centers, generating procedure volume density that justifies dedicated device inventory. The Health Products Regulatory Authority enforces ISO 13485-aligned registration pathways for biocompatible implants. Academic hospitals in Johannesburg absorb titanium lattice structures from selective laser melting at accelerating rates for complex revision arthroplasty.
Western Cape
Cape Town's academic medical centers are establishing pediatric cochlear implant programs with dedicated auditory rehabilitation pathways. The South African Bureau of Standards certifies structural integrity for load-bearing implants used in regional facilities. Private ENT practices in the northern suburbs concentrate pediatric implant candidacy assessments, replicating Gauteng's volume model.
KwaZulu-Natal
Durban's tertiary hospitals face biomedical engineering talent scarcity that limits cardiac assist device program expansion. National health insurance procurement reforms redistribute purchasing authority to centralized tender boards, compressing vendor negotiation cycles. Provincial facilities rely on referral pathways to Gauteng for complex implantable device procedures.
Eastern Cape
Port Elizabeth and East London surgical units experience delayed ventricular assist device implantation due to pharmaceutical regimen substitution for congestive heart failure. The Department of Trade, Industry and Competition production-linked incentives for medical device assembly are reducing landed cost disadvantages. Rehabilitation centers in the region serve traumatic amputation cases from industrial and road traffic incidents.
South Africa Artificial Organs and Bionic Implants Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Africa's artificial organs and bionic implants sector. The market structure consolidates around established multinational suppliers with dedicated regulatory affairs capacity and hospital supply agreements. Three archetypes dominate: diversified cardiovascular device conglomerates, specialized auditory implant manufacturers, and orthopedic revision specialists. Competitive moves center on securing national health insurance reimbursement codes and anchoring multi-year technical service contracts with Gauteng's tertiary hospital networks.
Within the diversified cardiovascular tier, Medtronic leverages its cardiac rhythm portfolio to anchor hospital supply agreements across Gauteng and Western Cape provinces. Cochlear Ltd occupies a specialized position in auditory implant systems for pediatric patients through academic hospital networks. Berlin Heart exemplifies the cardiac assist device archetype via partnerships with cardiothoracic referral centers. These three companies represent distinct strategic positions: broad portfolio leverage, pediatric specialization depth, and critical care device integration respectively.
| Leading Market Players |
|---|
| Abbott |
| Berlin Heart |
| Cochlear Ltd |
| Ossur |
| Sonova |
| Abiomed Inc. |
| Medtronic |
| Zimmer Biomet |
| Ekso Bionics |
| Others |
Value Network & Pricing Analysis
Biocompatibility certification tiers bifurcate procurement economics across South Africa's artificial organs and bionic implants sector, with ISO 13485-registered devices commanding premium positioning while unregistered imports face compressed margins and exclusion from national health insurance reimbursement pathways. This tier divergence manifests in Gauteng's tertiary hospitals maintaining dual vendor rosters—established suppliers with dedicated regulatory affairs capacity versus emerging entrants navigating extended validation timelines—and concentrates supply chain leverage among German and Swiss feedstock specialists serving the premium tier.
Pricing Analysis
The bundled-vs-unbundled service split is reshaping vendor economics as hospital procurement committees separate device acquisition from technical support contracts. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility certification depth and after-sales service bundling. Cost compression in the standard tier is intensifying because provincial tender boards are consolidating multi-year supply agreements under national health insurance reforms. Public sector procurement committees exhibit highest price sensitivity, while private academic centers prioritize technical service integration over unit cost.
Supply Chain Analysis
Selective laser melting equipment and bioceramic feedstocks rest on German and Swiss specialty manufacturing, with titanium powder supply anchored in Ukrainian and Russian extraction networks prior to recent disruptions. Platinum-iridium electrode assemblies draw from South African mining operations, while hermetic titanium enclosures source from Japanese precision metalworking. Single-source vulnerability concentrates in additive fabrication system maintenance contracts, exposing Gauteng hospitals to extended downtime risk. Distribution runs through Johannesburg-based medical device distributors holding Health Products Regulatory Authority import licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's artificial organs and bionic implants market functions as a regulatory compounder, where the Health Products Regulatory Authority's ISO 13485 alignment is accelerating registration pathways and consolidating procurement authority around compliant suppliers.
For Market Incumbents: Anticipate margin compression from unbundled service contracts by deepening technical training infrastructure and securing exclusive biomedical engineering placement agreements with Gauteng academic hospitals. Consolidate position through backward integration into additive fabrication feedstock supply, countering currency volatility exposure from German and Swiss equipment vendors. For New Entrants and Emerging Players: Enter via Western Cape pediatric cochlear implant programs, where Cape Town's academic medical centers are establishing dedicated auditory rehabilitation pathways with less entrenched vendor relationships than Gauteng's cardiothoracic centers. Target myoelectric-robotics convergence applications in Pretoria rehabilitation facilities, leveraging pattern-recognition software partnerships to displace passive mechanical device incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory affairs capacity scarcity constrains market access for mid-tier manufacturers lacking dedicated ISO 13485 compliance infrastructure. Long-term viability favors acquirers of South African medical device assembly operations benefiting from Department of Trade, Industry and Competition production-linked incentives. Watch national health insurance reimbursement code expansion for robotic exoskeleton systems as the inflection signal for rehabilitation technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Health Products Regulatory Authority registration unlocks national health insurance procurement access for cardiac rhythm devices. |
| Hospital System Partnership | Multi-year technical service agreements with Gauteng tertiary centers secure device placement against unbundled procurement trends. |
| Backward Integration into Feedstock | In-house titanium powder sourcing reduces currency exposure from German selective laser melting equipment vendors. |
| Reimbursement Strategy | National health insurance tariff classification for robotic exoskeletons compresses commercialization timelines for rehabilitation entrants. |
| Software Companion Development | Pattern-recognition integration with myoelectric prosthetics opens rehabilitation center contracts previously served by passive devices. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cardiothoracic surgeons, hospital purchasing committee chairs, biomedical engineering directors, and Health Products Regulatory Authority registration specialists with secondary validation against hospital procurement databases, GPO contracts, and ISO 13485 certification records. Bottom-up procedure volume estimates from Gauteng and Western Cape academic centers were triangulated against top-down national health insurance expenditure projections.
Segment-weighting approaches distributed value across product type, technology, end user, and application dimensions, with cardiovascular, orthopedic, neurological, and assistive device categories modeled separately across the projection horizon. CAGRs were derived from procedure volume growth trajectories and reimbursement pathway maturity curves, incorporating additive manufacturing adoption rates and biocompatibility testing timeline assumptions specific to South Africa's regulatory environment.
Inputs from hospital procurement databases and regulatory filing records were available through the study window; gaps in provincial-level procedure reporting from KwaZulu-Natal and Eastern Cape introduce uncertainty bands around geographic distribution estimates. Forecasts reflect documented assumptions regarding national health insurance implementation pace and biomedical engineering workforce expansion. A small set of triggers—reimbursement code finalization for robotic systems, additive fabrication feedstock tariff adjustments, and Health Products Regulatory Authority inspection capacity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Photopheresis Products Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Oral Appliance Market
Medical Devices
Soft Tissue Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Portable OT Light Market