
 Brazil Cardiac Pacemakers Market | 2026-2036
Brazil Cardiac Pacemakers Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Cardiac Pacemakers Market Insights
ANVISA's Good Manufacturing Practice certification cycle is collapsing from twenty-four months to under fifteen for established importers, tightening the field of qualified suppliers. Medtronic plc leverages its São Paulo distribution infrastructure to sustain same-day device availability for tier-one hospitals. Abbott Laboratories anchors its position through dedicated electrophysiology training centers in Rio de Janeiro and Belo Horizonte. BIOTRONIK SE & Co.KG differentiates via local technical service teams that reduce replacement lead times.
A cardiac pacemaker is an implantable pulse generator connected to leads that deliver electrical stimuli to myocardial tissue, typically operating at 2.5–3.0 volts with lithium-iodine batteries lasting seven to twelve years, designed to correct bradycardia and heart block. Dual chamber systems command premium positioning due to synchronized atrioventricular pacing benefits, while leadless technology represents the fastest-growing product category as infection risk reduction drives cardiologist preference. MRI-compatible devices now dominate hospital procurement specifications, with conventional systems retreating to price-sensitive surgical centers and home care channels where reimbursement constraints limit technology upgrades.
ANVISA's medical device vigilance requirements and the Brazilian Health Regulatory Agency's post-market surveillance protocols compel manufacturers to maintain local adverse-event reporting capabilities, raising operational barriers for smaller foreign entrants. The Brazilian Society of Cardiology's clinical guidelines and SUS reimbursement classifications further stratify which device tiers reach public versus private patients. Stakeholders must monitor ANVISA's alignment with International Medical Device Regulators Forum standards, as harmonization would accelerate approval of next-generation biostable and wireless platforms.
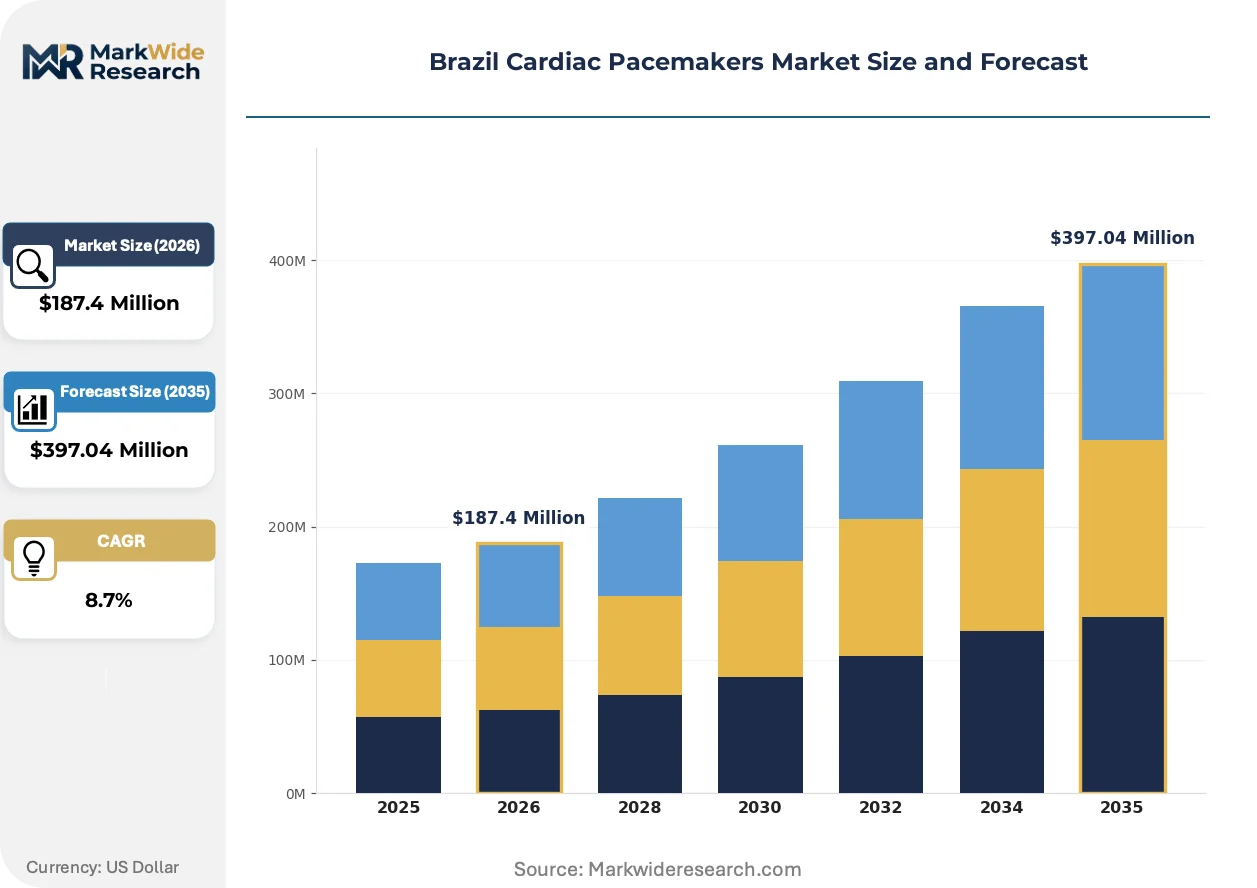
Market Dynamics
Leadless pacemaker technology is compressing conventional transvenous system demand as infection risk reduction becomes the dominant procurement criterion across Brazilian cardiology networks.
Growth Catalysts
- SUS Realignment:Brazil's public health system is expanding electrophysiology coverage for dual-chamber devices in Minas Gerais and São Paulo state hospitals, pulling volume from private channels into reimbursed procedures.
- ANVISA Streamlining:The regulator's compressed fifteen-month Good Manufacturing Practice cycle for established importers accelerates MRI-compatible platform introductions versus legacy twenty-four-month pathways.
- Southeastern Cluster Density:Cardiology clinic concentration in Rio de Janeiro, Belo Horizonte, and São Paulo generates patient referral volumes that sustain high-throughput implantation programs.
Market Restraints
- Lithium-Iodine Battery Supply:Single-source dependency on specialized cell manufacturers concentrates input risk for pulse generator production.
- ANVISA Vigilance Burden:Post-market surveillance protocols compel local adverse-event reporting infrastructure that raises fixed costs for foreign entrants below scale thresholds.
- Leadless Device Cost Premium:Retrieval complexity and specialized delivery systems price these systems above SUS reimbursement ceilings, limiting public-sector penetration.
Strategic Opportunities
- Northeastern Underpenetration:Bahia, Pernambuco, and Ceará states show cardiology specialist density gaps of forty percent versus southeastern benchmarks, creating whitespace for training-partnership models.
- Biostable Lead Convergence:Integration of steroid-eluting electrodes with wireless telemetry architectures enables next-generation remote monitoring platforms.
- Home Care Channel Expansion:Post-implant remote monitoring reimbursement is shifting device follow-up from hospital outpatient departments to telemedicine-enabled home settings.
Industry Challenges
- Electrophysiologist Training Pipeline:Brazilian Society of Cardiology certification programs produce fewer than eighty new implant specialists annually against rising arrhythmia caseloads.
- Legacy System Integration:Hospital IT infrastructure fragmentation complicates wireless pacemaker data transmission into existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Cardiac Pacemakers Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Dual Chamber, Biventricular, Wireless End User: Hospitals, Surgical Centers, Cardiology Clinics, Home Care Technology: MRI-Compatible, Leadless, Conventional, Biostable Distribution Channel: Direct Sales, Distributors, Online Sales, Other |
| Companies Covered | Medtronic plc, Abbott Laboratories, BIOTRONIK SE & Co.KG, Boston Scientific Corporation, LivaNova plc, Osypka Medical GmbH, MEDICO S.p.A., MicroPort Scientific, Ivanovo plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Cardiac Pacemakers Market Trends and Innovations
Device miniaturization and battery chemistry advances are redefining implantable pulse generator specifications, while regulatory harmonization pressures reshape competitive entry pathways.
Leadless pacemaker systems are supplanting transvenous devices in premium private hospital segments. These capsule-shaped implants eliminate lead-related complications entirely. Hospital procurement committees in São Paulo and Rio de Janeiro are now specifying leadless-first protocols for eligible bradycardia patients. The technology is compressing conventional dual-chamber system margins as manufacturers reallocate R&D toward retrieval and longevity improvements.
ANVISA's alignment with International Medical Device Regulators Forum standards is accelerating technical documentation reviews for MRI-conditional platforms. The regulator's adoption of predicate-device referencing reduces redundant clinical testing for iterative battery and telemetry upgrades. Brazilian private insurers are responding by narrowing coverage differentials between conventional and MRI-compatible systems, eroding the price premium that sustained older technology tiers.
Cardiologist preference is rotating toward devices with embedded remote monitoring capabilities that reduce in-person follow-up frequency. Hospital outpatient departments are unbundling device interrogation from implantation reimbursement, creating standalone service lines. This shift concentrates in southeastern Brazil's integrated delivery networks, where capitated contracts reward complication prevention over procedure volume.
Brazil Cardiac Pacemakers Market Segmentation
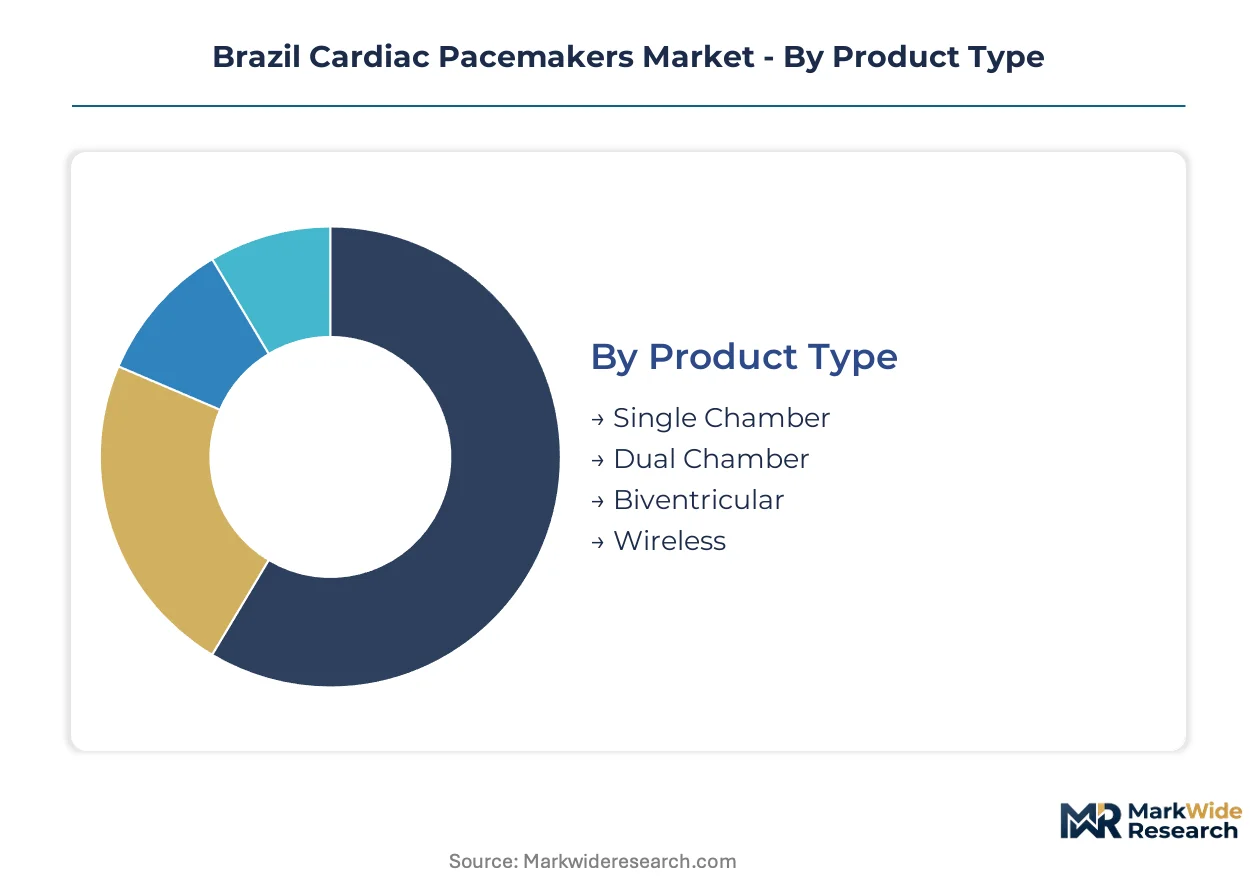
Segmentation reveals how leadless and MRI-compatible platforms are displacing conventional systems across Brazilian cardiology networks. Procurement specifications now diverge sharply between SUS-funded public hospitals and premium private facilities.
Product Type:
Dual chamber systems face the most acute substitution pressure as leadless technology captures eligible bradycardia cases with lower infection profiles.
- Single Chamber:Implanted in the right atrium or ventricle with a single lead delivering 2.5–3.0 volt pulses. Demand concentrates in surgical centers across Minas Gerais where SUS reimbursement ceilings constrain device selection.
- Dual Chamber:Synchronized atrioventricular pacing maintains premium positioning in São Paulo private hospitals despite leadless encroachment. Cardiologists specify these systems for patients requiring rate-responsive atrial support.
- Biventricular:Cardiac resynchronization therapy devices for heart failure with reduced ejection fraction.
- Wireless:Leadless capsule implants eliminating transvenous lead complications entirely.
Dual chamber retains volume leadership; wireless holds the steepest expansion curve.
End User:
Cost tier stratification separates high-complexity implantation sites from routine follow-up venues.
- Hospitals:Tertiary facilities in Rio de Janeiro and São Paulo perform complex dual-chamber and biventricular implants with electrophysiology lab infrastructure. ANVISA's vigilance requirements compel these sites to maintain adverse-event reporting systems.
- Surgical Centers:Ambulatory settings in Belo Horizonte concentrate single-chamber procedures under SUS reimbursement protocols.
- Cardiology Clinics:Private practice networks in southeastern Brazil handle device interrogation and remote monitoring follow-up.
- Home Care:Telemedicine-enabled post-implant monitoring shifts patient touchpoints from hospital outpatient departments.
Hospitals dominate implant volume; home care channels are expanding most quickly.
Technology:
Application requirements now mandate MRI compatibility for new hospital procurements.
- MRI-Compatible:Conditional systems with shielded circuitry and revised lead designs. São Paulo hospital procurement committees specify MRI-conditional devices exclusively, eroding coverage differentials from private insurers.
- Leadless:Capsule-shaped implants delivered via femoral catheter eliminating lead-related endocarditis risk. Premium private facilities in Rio de Janeiro specify leadless-first protocols for eligible patients.
- Conventional:Non-conditional systems retreating to price-sensitive surgical centers where reimbursement constraints limit technology upgrades.
- Biostable:Steroid-eluting electrodes with wireless telemetry architectures for next-generation remote monitoring.
MRI-Compatible holds current procurement dominance; leadless platforms gain share fastest.
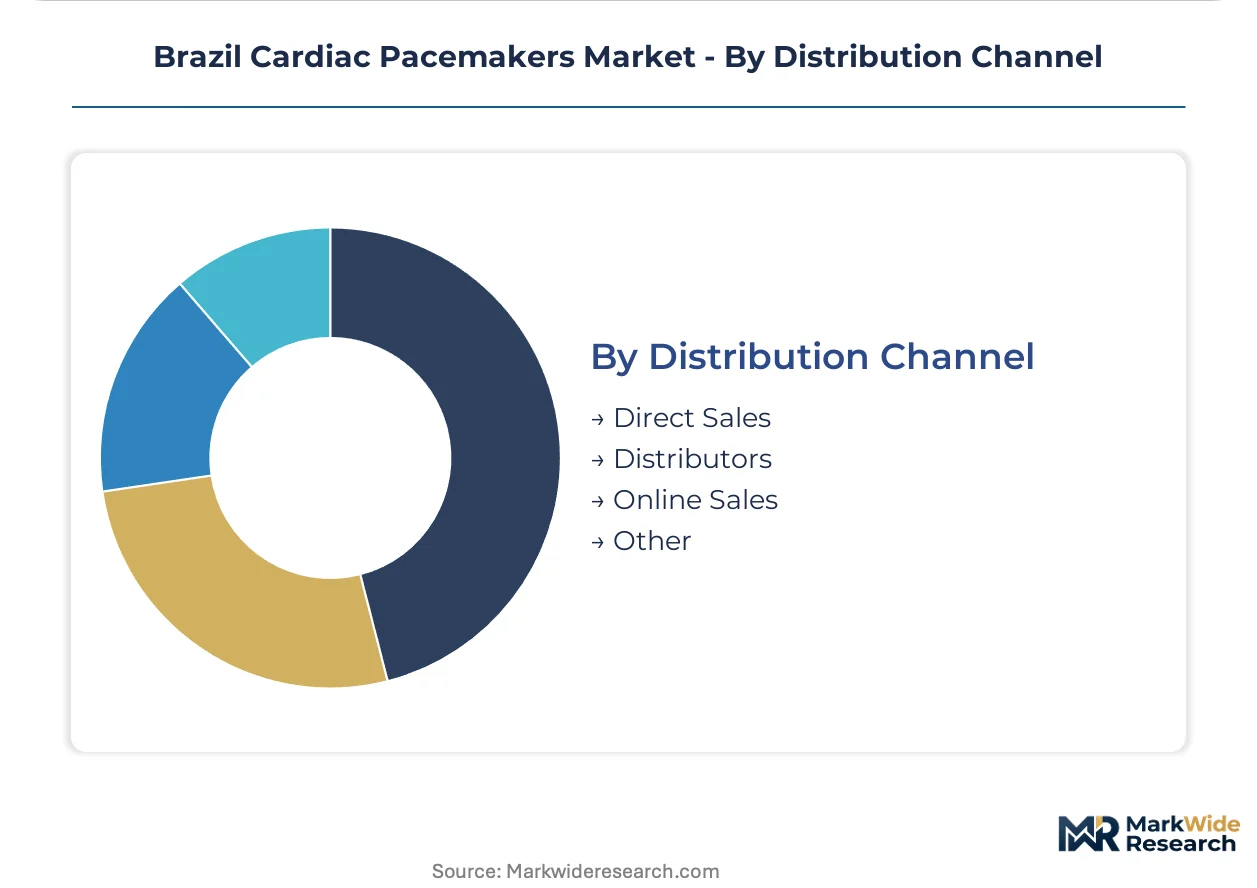
Distribution Channel:
Customer type concentration favors direct relationships with high-volume implantation centers.
- Direct Sales:Manufacturer field representatives maintain same-day device availability for tier-one hospitals in São Paulo through localized inventory.
- Distributors:Regional wholesalers service cardiology clinics and surgical centers across Minas Gerais and Rio de Janeiro with technical support teams.
- Online Sales:Emerging procurement pathway for consumables and replacement accessories in remote monitoring programs.
- Other:Group purchasing organizations and hospital consortium arrangements.
Direct sales commands premium system volume; distributor networks penetrate tier-two facilities most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-volume implantation programs concentrate in Brazil's southeastern corridor, where private hospital networks and SUS-funded tertiary facilities generate divergent procurement specifications for cardiac rhythm management devices.
São Paulo
Private hospital procurement committees in São Paulo specify MRI-conditional and leadless-first protocols exclusively, driven by capitated contracts that reward complication prevention. ANVISA's compressed fifteen-month Good Manufacturing Practice certification cycle accelerates device introductions for established importers. The metropolitan region's integrated delivery networks sustain same-day device availability through localized manufacturer inventory.
Minas Gerais
State hospital networks in Minas Gerais expand electrophysiology departments under SUS reimbursement realignments, pulling dual-chamber device volume from private channels. ANVISA's vigilance requirements compel these facilities to maintain adverse-event reporting infrastructure. Belo Horizonte's surgical centers concentrate single-chamber procedures where reimbursement ceilings constrain technology selection.
Rio de Janeiro
Premium private facilities in Rio de Janeiro anchor dedicated electrophysiology training centers that shape cardiologist preference toward remote monitoring capabilities. The Brazilian Society of Cardiology's certification programs produce implant specialists who drive leadless adoption. Hospital outpatient departments here unbundle device interrogation from implantation reimbursement.
Bahia
Cardiology specialist density gaps of forty percent versus southeastern benchmarks create whitespace for training-partnership models in Salvador and surrounding municipalities. SUS coverage expansion targets underpenetrated arrhythmia caseloads. Telemedicine-enabled home care channels emerge as post-implant monitoring shifts from hospital settings.
Rio Grande do Sul
Porto Alegre's hospital networks balance public and private patient flows with tiered device procurement strategies. Regional distributors service cardiology clinics with technical support teams that reduce replacement lead times. Post-market surveillance protocols raise fixed costs for foreign entrants below scale thresholds.
Brazil Cardiac Pacemakers Market Competitive Landscape
Player mix skews toward multinational device manufacturers with established Brazilian distribution infrastructure. The field tightens as ANVISA's fifteen-month Good Manufacturing Practice cycle filters smaller foreign entrants. Three archetypes dominate: integrated multinationals with same-day logistics capability, training-centric specialists with electrophysiology education platforms, and regional service-focused operators with localized technical teams. Competitive moves center on electrophysiologist training partnerships and remote monitoring platform integration.
Among multinational anchors, Medtronic plc and Abbott Laboratories exemplify divergent positioning strategies within the Brazilian market. Medtronic plc leverages São Paulo-based distribution infrastructure to sustain same-day device availability for tier-one hospitals. Abbott Laboratories anchors its presence through dedicated electrophysiology training centers in Rio de Janeiro and Belo Horizonte. BIOTRONIK SE & Co.KG occupies a service-differentiated position via local technical teams that compress replacement lead times.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| BIOTRONIK SE & Co.KG |
| Boston Scientific Corporation |
| LivaNova plc |
| Osypka Medical GmbH |
| MEDICO S.p.A. |
| MicroPort Scientific |
| Ivanovo plc |
| Others |
Pricing and Supply Chain Analysis
Lithium-iodine battery chemistry substitution for older silver-oxide cells is simultaneously relocating pulse generator manufacturing toward specialized cell producers in Japan and South Korea while compressing margin structures for Brazilian importers facing single-source input dependencies. This input shift concentrates pricing power with battery manufacturers and forces device assemblers to absorb volatility through long-term offtake commitments rather than spot procurement.
Pricing Analysis
Cost-plus contracts with lithium-iodine cell indexation dominate procurement between Brazilian distributors and East Asian battery suppliers. Three-tier pricing structure across MRI-conditional, leadless, and conventional systems separates premium private hospitals from SUS-funded facilities and surgical centers. Price erosion runs through the conventional device tier as ANVISA streamlining accelerates MRI-compatible platform introductions. SUS reimbursement ceilings render public-sector procurement the most price-sensitive segment, while São Paulo private hospitals absorb leadless premiums through capitated complication-prevention contracts.
Supply Chain Analysis
Just-in-time inventory strategies dominate São Paulo tier-one hospitals where Medtronic and Abbott maintain localized stockpiles, whereas Minas Gerais state hospitals prefer strategic stockpiling against ANVISA vigilance disruption risks. Pulse generator assembly draws from lithium-iodine cell manufacturers in Japan and South Korea, lead fabrication in Germany, and semiconductor components from Taiwan. Single-source vulnerability concentrates in specialized battery cell supply. Distribution runs through manufacturer field representatives for high-volume centers and regional wholesalers for tier-two clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's cardiac pacemaker market rewards electrophysiologist training infrastructure and ANVISA certification velocity more than manufacturing scale, creating asymmetric returns for players that front-load capability investment ahead of caseload expansion.
For Market Incumbents: Shield installed base relationships by embedding remote monitoring platforms into hospital IT architectures before SUS reimbursement shifts fully unbundle device interrogation from implantation payments. Deepen backward integration into lithium-iodine cell supply through long-term offtake agreements with Japanese manufacturers to neutralize single-source risk. Prioritize ANVISA Good Manufacturing Practice recertification velocity to maintain fifteen-month approval advantages over emerging entrants. For New Entrants and Emerging Players: Anchor in Bahia and Pernambuco cardiology networks where specialist density gaps of forty percent versus southeastern benchmarks create whitespace for training-partnership models with the Brazilian Society of Cardiology. Target SUS-funded electrophysiology department expansions in Minas Gerais state hospitals where dual-chamber volume is migrating from private channels. Lead with distributor relationships that bundle technical service teams with device supply to compress replacement lead times. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors electrophysiology training-centric specialists over pure manufacturing scale. Viability over the coming decade hinges on capturing cardiologist preference formation before leadless and biostable platforms mature. Acquisition candidates should demonstrate ANVISA certification track records and established distributor technical service capabilities. Watch for ANVISA alignment with International Medical Device Regulators Forum standards as the inflection signal that would accelerate next-generation platform approvals and reshape competitive entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Good Manufacturing Practice Recertification | Fifteen-month certification cycles filter smaller foreign entrants and protect established importer margins. |
| Electrophysiologist Training Center Partnership | Rio de Janeiro and Belo Horizonte facilities shape cardiologist preference toward remote monitoring capabilities. |
| Leadless Pacemaker Retrieval Capability Investment | Specialized delivery and extraction systems differentiate premium private hospital positioning. |
| Lithium-Iodine Battery Long-Term Supply Agreement | Japanese and South Korean cell manufacturer commitments neutralize single-source input risk. |
| Telemedicine-Enabled Home Care Channel Development | Post-implant remote monitoring reimbursement shifts patient touchpoints from hospital outpatient departments. |
Research Methodology
A spread of perspectives from electrophysiology department heads, hospital purchasing committee members, ANVISA regulatory affairs specialists, biomedical engineers, and GPO contracts managers converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from ANVISA medical device registration databases, Brazilian Society of Cardiology clinical guideline publications, SUS reimbursement classification records, and hospital procurement system data. Bottom-up implant volume estimates triangulated against top-down market size reconstructions.
Segmentation dimensions modeled include product type, end-user facility tier, technology platform, and distribution channel across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for ANVISA regulatory velocity and SUS reimbursement realignment trajectories. Forecast inputs incorporated electrophysiologist training pipeline constraints, lithium-iodine battery longevity improvements, and MRI-conditional platform penetration rates.
Material uncertainties — ANVISA regulatory harmonization timing, SUS reimbursement ceiling adjustments, and electrophysiologist certification program expansion — sit outside the modeled envelope. Forecasts reflect assumptions about continued southeastern Brazil demand concentration and leadless device cost trajectory moderation. Revision becomes warranted when ANVISA approval timelines for next-generation biostable platforms deviate substantially from predicate-device referencing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Root Canal Irrigators Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Morcellators Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Surgical AR Systems Market