
 Computer Assisted Surgical (CAS) Systems Market | 2026-2036
Computer Assisted Surgical (CAS) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Assisted Surgical (CAS) Systems Market Insights
Ambulatory surgical centers is rotating toward higher CAS system utilization as hospital networks decentralize orthopedic and general surgery volumes. Intuitive Surgical, Inc. dominates the robotic surgery systems segment through its installed base and training ecosystem. Stryker Corporation competes in navigation and robotics through its Mako platform and orthopedic specialization. Medtronic plc extends its presence across imaging software and spine navigation through sustained R&D allocation.
Computer assisted surgical systems integrate robotic manipulators, optical tracking arrays, and preoperative planning software to enhance instrument precision during minimally invasive procedures. These systems typically achieve sub-millimeter registration accuracy through infrared stereoscopic cameras paired with patient-specific anatomical models derived from CT or MRI datasets. Robotic surgery systems command the largest revenue share due to capital intensity and recurring instrument revenue. Navigation systems represent the fastest-growing product category as spine and cranial applications expand beyond early-adopter academic centers. Machine learning integration across surgical planning tools is creating new margin pools through predictive analytics and automated segmentation workflows.
FDA 510(k) and de novo pathways govern U.S. market entry for CAS devices, while EU MDR and CE marking requirements impose stricter clinical evidence standards on software-as-a-medical-device components. Japan's PMDA and METI coordinate reimbursement approvals that determine commercial viability for robotic platforms in tertiary hospitals. Stakeholders must monitor evolving software validation requirements and reimbursement parity between inpatient and outpatient settings.
Market Dynamics
Machine learning integration into surgical planning modules is compressing development cycles and forcing incumbent vendors to reconfigure software validation pipelines around FDA 510(k) and EU MDR requirements.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Hospital networks in the United States are decentralizing orthopedic and general surgery volumes toward outpatient facilities, creating concentrated demand for compact navigation systems.
- EU MDR Software Classification:Stricter clinical evidence standards for software-as-a-medical-device components are accelerating investment in automated segmentation workflows and predictive analytics modules.
- Japan Reimbursement Coordination:PMDA and METI joint approvals for robotic platforms in tertiary hospitals are unlocking capital expenditure cycles for integrated surgical systems.
Market Restraints
- Capital Intensity Barrier:Robotic surgery platforms require substantial upfront investment in infrastructure, training ecosystems, and dedicated operating room configurations that constrain mid-tier hospital adoption.
- Optical Component Supply Concentration:Infrared stereoscopic camera arrays and precision tracking sensors concentrate manufacturing in specialized German and Japanese component suppliers, creating input vulnerability.
- FDA Validation Timeline Friction:Premarket clearance pathways for navigation modules with iterative software updates impose documentation burdens that extend time-to-revenue for planning tool vendors.
Strategic Opportunities
- Cranial Navigation Underpenetration:Neurosurgical applications of optical tracking systems remain concentrated in academic medical centers in Germany, leaving community hospital networks in Japan and the United States as expansion targets.
- Cloud-Native Planning Convergence:Integration of preoperative CT/MRI segmentation with remote surgical consultation platforms is creating new service revenue pools beyond hardware sales.
- IRA Hospital Infrastructure Incentives:United States federal funding for rural healthcare modernization is channeling capital toward minimally invasive surgical capability upgrades in underserved counties.
Industry Challenges
- Mechatronics Talent Scarcity:Vendors face acute shortages of engineers capable of integrating robotic manipulators with real-time optical feedback loops and patient-specific anatomical modeling.
- Legacy PACS Integration Complexity:Surgical planning software must interface with heterogeneous hospital imaging archives, forcing costly customization for each institutional IT environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Assisted Surgical (CAS) Systems Market |
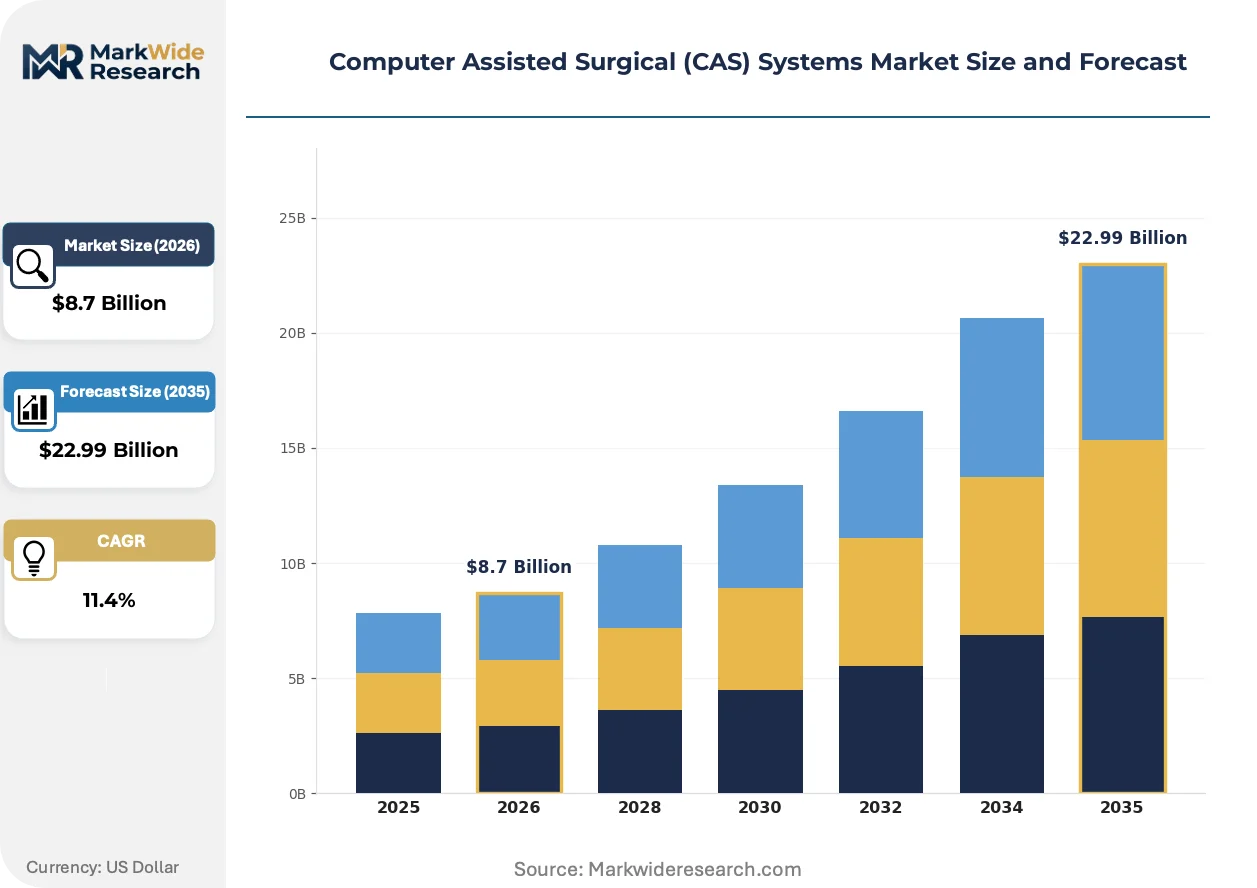
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgery Systems, Imaging Software, Navigation Systems, Surgical Planning Tools End User: Hospitals, Surgical Centers, Academic Institutions, Clinics Technology: Digital Imaging, Augmented Reality, Robotics, Machine Learning Application: Orthopedic Surgery, Neurosurgery, Cardiothoracic Surgery, General Surgery |
| Companies Covered | Intuitive Surgical, Inc., Stryker Corporation, Medtronic plc, Zimmer Biomet, Mazor Robotics, Brainlab AG, Accuray Incorporated, Smith & Nephew, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Assisted Surgical (CAS) Systems Market Trends and Innovations
Autonomous segmentation algorithms and edge-computing architectures are redistributing computational workloads from centralized servers to operating room environments, altering hardware specifications and validation requirements simultaneously.
Deep learning-based anatomical landmark detection is displacing manual registration protocols in spine navigation workflows. Academic medical centers in Germany and Japan are deploying these tools for scoliosis correction and degenerative disc procedures. The technology is compressing operative setup time and reducing reliance on specialized radiological technicians for intraoperative image interpretation.
EU MDR Annex VIII reclassification of surgical planning software is forcing vendors to generate clinical performance data for algorithms previously cleared under lighter documentation standards. The regulation is extending development timelines for European market entry. Spine navigation modules with machine learning components are experiencing the most significant compliance cost inflation as notified bodies apply novel scrutiny to training dataset provenance.
Hospital procurement departments are unbundling after-sales service contracts from initial capital purchases, compressing vendor margin structures and shifting negotiation leverage toward multi-year consumable supply agreements. Ambulatory surgical centers in the United States are driving this pattern most aggressively, using volume commitments to secure per-procedure pricing for robotic instrument sterilization and maintenance. The model is displacing traditional upfront-plus-annual-fee structures in outpatient settings.
Computer Assisted Surgical (CAS) Systems Market Segmentation
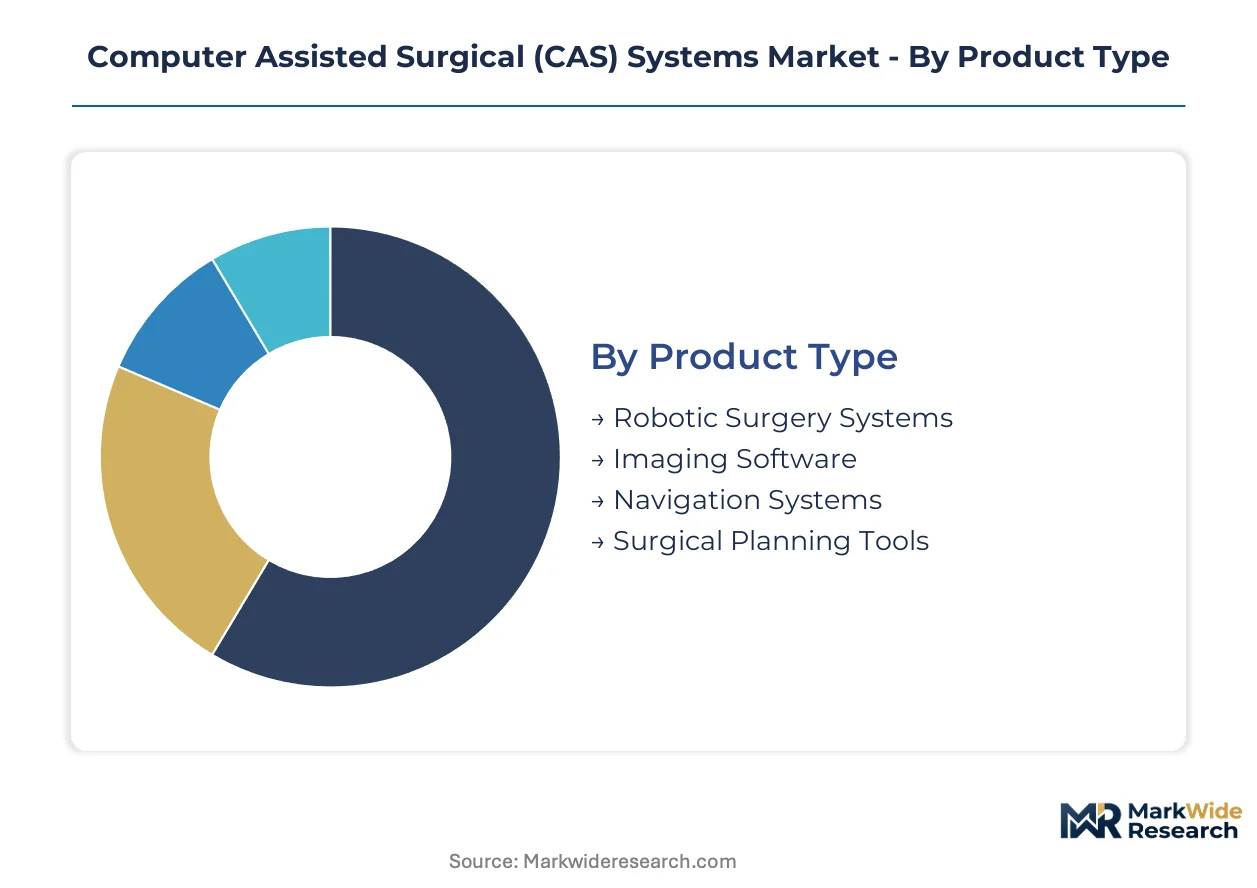
Segmentation in computer assisted surgical systems reveals how capital intensity, reimbursement pathways, and procedural complexity concentrate demand across distinct buyer and technology configurations. Understanding these divides clarifies where vendors must configure software validation pipelines and service delivery models.
Product Type:
Robotic surgery systems concentrate manufacturing in the United States and Japan, while navigation and planning tools flow from German and Swiss component clusters. Imaging software development spans distributed engineering centers across North America and Europe.
- Robotic Surgery Systems:Capital-intensive platforms integrating manipulator arms, optical tracking arrays, and sterile instrument interfaces. Demand clusters in United States tertiary hospitals where reimbursement parity for minimally invasive procedures justifies infrastructure investment and dedicated operating room configurations.
- Navigation Systems:Optical tracking and registration hardware achieving sub-millimeter accuracy through infrared stereoscopic camera arrays. Spine and cranial applications in German academic medical centers are expanding toward community hospital networks in Japan and the United States as procedural volumes decentralize.
- Imaging Software:CT and MRI segmentation tools for preoperative anatomical modeling, developed across distributed North American and European engineering centers.
- Surgical Planning Tools:Preoperative workflow modules requiring integration with heterogeneous hospital PACS archives, forcing costly institutional customization.
Robotic surgery systems hold the largest share; momentum sits with navigation systems.
End User:
Capital availability and reimbursement frameworks create sharp tiering across buyer categories, with ambulatory facilities capturing fastest volume expansion.
- Hospitals:Tertiary centers with dedicated robotic surgery programs, concentrated infrastructure investment, and training ecosystems. United States academic medical centers anchor installed base expansion through fellowship pipelines and outcome data collection.
- Surgical Centers:Outpatient facilities driving fastest CAS system utilization as hospital networks decentralize orthopedic and general surgery volumes. United States ambulatory networks use volume commitments to secure per-procedure pricing for instrument sterilization and maintenance.
- Academic Institutions:Research-focused centers validating machine learning algorithms and training datasets for regulatory submission to FDA and EU notified bodies.
- Clinics:Limited-adoption settings constrained by capital intensity and optical component supply concentration in specialized German and Japanese suppliers.
Hospitals dominate current procurement; surgical centers are climbing the fastest.
Technology:
Regulatory classification intensity varies sharply, with machine learning components facing escalated EU MDR scrutiny and FDA software validation documentation burdens.
- Digital Imaging:Established CT and MRI processing backbone with mature regulatory pathways. PACS integration complexity remains the primary deployment friction across institutional IT environments.
- Robotics:Capital-intensive mechatronics requiring scarce engineering talent capable of integrating manipulators with real-time optical feedback loops.
- Augmented Reality:Emerging visualization overlay technology for intraoperative guidance, still concentrated in early-adopter academic centers.
- Machine Learning:Automated segmentation and anatomical landmark detection algorithms experiencing steepest expansion trajectory. EU MDR Annex VIII reclassification forces clinical performance data generation for training dataset provenance, extending European market entry timelines.
Digital imaging commands current revenue; machine learning shows steepest expansion trajectory.
Application:
Procedural reimbursement rates and clinical evidence requirements determine adoption sequencing across surgical specialties.
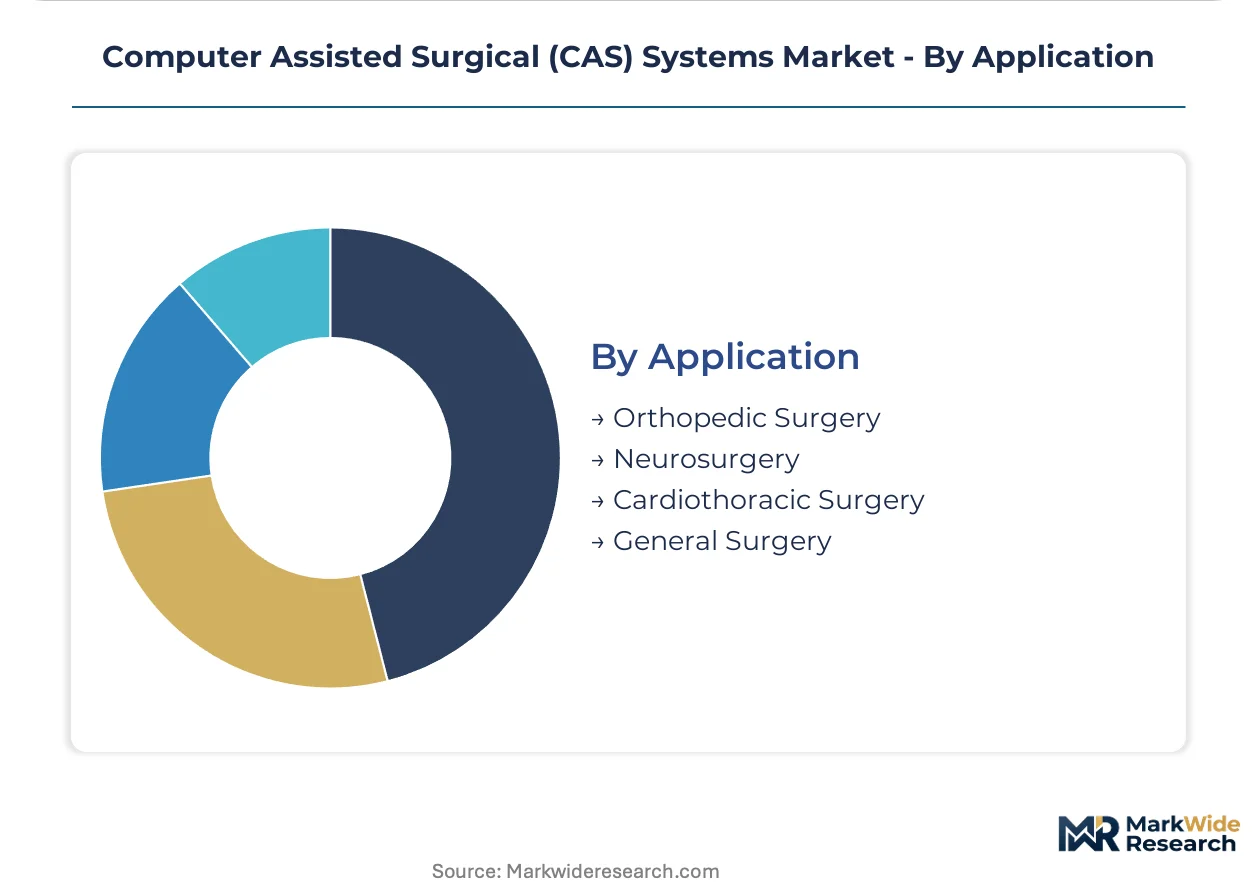
- Orthopedic Surgery:Primary volume driver through knee and hip arthroplasty applications. Stryker's Mako platform and competing systems concentrate in United States hospital networks with bundled payment contracts.
- Neurosurgery:Cranial navigation remains underpenetrated outside German academic centers, leaving community hospital networks in Japan and the United States as expansion targets for optical tracking deployment.
- Cardiothoracic Surgery:Specialized robotic applications with concentrated demand in tertiary centers with established minimally invasive cardiac programs.
- General Surgery:Broad procedural category spanning hernia repair to colorectal applications, with adoption constrained by capital intensity barriers in mid-tier facilities.
Orthopedic surgery holds the largest share; neurosurgery presents the most significant underpenetration opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized component manufacturing clusters in Germany and Japan concentrate optical tracking array production, while tertiary hospital infrastructure investment drives demand concentration in the United States. Regulatory approval timelines and reimbursement frameworks create divergent commercialization pathways across major markets.
United States
Hospital networks decentralize orthopedic and general surgery volumes toward ambulatory surgical centers, creating concentrated demand for compact navigation systems. FDA 510(k) and de novo pathways govern premarket clearance for CAS devices with iterative software updates. The Greater Boston and San Francisco Bay Area clusters anchor machine learning algorithm development for surgical planning tools.
Germany
Academic medical centers in Munich and Heidelberg validate spine and cranial navigation applications with sub-millimeter registration accuracy. EU MDR Annex VIII reclassification imposes stricter clinical evidence standards on software-as-a-medical-device components. The Baden-Württemberg precision engineering corridor supplies infrared stereoscopic camera arrays to global system integrators.
Japan
Tertiary hospitals in Tokyo and Osaka drive capital expenditure cycles for integrated robotic surgical systems. PMDA and METI coordinate joint reimbursement approvals that determine commercial viability for robotic platforms. The Nagoya manufacturing belt produces precision tracking sensors for optical navigation hardware.
United Kingdom
NHS bundled payment contracts concentrate orthopedic robotic system adoption in London and Manchester teaching hospitals. MHRA post-Brexit regulatory alignment with EU MDR extends software validation documentation requirements. The Oxford-Cambridge corridor hosts imaging software engineering centers serving European markets.
China
Domestic hospital procurement prioritizes cost-competitive navigation systems for tier-two and tier-three facilities in Shanghai and Beijing. NMPA medical device registration pathways accelerate for locally manufactured robotic platforms. The Yangtze River Delta cluster assembles optical tracking components for regional system vendors.
Computer Assisted Surgical (CAS) Systems Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates and specialized robotics developers. The vendor base stratifies across three tiers: capital-intensive platform integrators with installed base moats, navigation hardware specialists with optical tracking expertise, and software vendors with regulatory-cleared segmentation algorithms. Strategic moves center on unbundling service contracts from capital sales and securing multi-year consumable supply agreements with ambulatory networks.
Among diversified medical technology conglomerates, Intuitive Surgical, Inc. and Stryker Corporation occupy positions defined by installed base scale and orthopedic specialization respectively. Medtronic plc anchors the imaging software and spine navigation vector through sustained R&D allocation. These three entities exemplify how platform breadth and regulatory clearance depth determine competitive positioning in capital-intensive surgical technology markets.
| Leading Market Players |
|---|
| Intuitive Surgical, Inc. |
| Stryker Corporation |
| Medtronic plc |
| Zimmer Biomet |
| Mazor Robotics |
| Brainlab AG |
| Accuray Incorporated |
| Smith & Nephew |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance tiers and EU MDR Annex VIII software classifications simultaneously gate supplier qualification and stratify price levels across robotic surgery platforms, navigation hardware, and surgical planning modules. Ambulatory surgical centers exploit volume leverage to compress service bundling while specialized component manufacturers in Germany and Japan retain pricing power over infrared tracking arrays.
Pricing Analysis
FDA 510(k) and de novo pathways dictate the pricing tier structure across robotic surgery systems, navigation hardware, and software modules. Three-tier pricing separates premium integrated platforms from standard navigation configurations from economy planning tools, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in outpatient settings is intensifying because ambulatory surgical centers unbundle service contracts and demand per-procedure instrument pricing. Surgical centers exhibit highest price sensitivity; tertiary academic hospitals with bundled payment contracts show lowest.
Supply Chain Analysis
Extended lead times for precision infrared stereoscopic camera arrays signal inventory vulnerability across system integrators. Manufacturing concentrates in Germany, Japan, and the United States, with the Baden-Württemberg engineering corridor and Nagoya manufacturing belt anchoring optical component production. Supply rests on germanium lenses, precision-machined aluminum housings, and CMOS sensor arrays. Single-source vulnerability runs through specialized German tracking sensor suppliers. Distribution feeds from component manufacturers to system integrators through long-term supply agreements with hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CAS systems market sits in a cyclical recovery phase as hospital capital expenditure cycles rebound from pandemic-deferred infrastructure investment and ambulatory surgical center expansion accelerates procedural volume decentralization.
For Market Incumbents: Fortify installed base moats through captive supply of precision optical tracking components and exclusive training ecosystem lock-in. Machine learning algorithm vendors with cleared segmentation workflows threaten margin pools in surgical planning software. Vertical integration into infrared stereoscopic camera manufacturing reduces exposure to German component supplier concentration.
For New Entrants and Emerging Players: FDA breakthrough device designation offers a certification fast-track for autonomous segmentation algorithms targeting cranial navigation underpenetration. Community hospital networks in Japan and the United States represent the most penetrable expansion corridor for compact navigation systems. Cloud-native planning platform partnerships with ambulatory networks provide a capital-light go-to-market angle.
For Investors and Strategic Acquirers: EU MDR Annex VIII reclassification reshapes the acquisition landscape toward software vendors with validated clinical performance datasets and notified body relationships. Long-term viability centers on regulatory clearance depth rather than hardware scale. Watch FDA 510(k) clearance velocity for machine learning-integrated modules as the inflection signal for planning software consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for navigation modules with iterative software updates. |
| CE Marking Pathway | Unlocks EU market access under MDR Annex VIII software-as-a-medical-device standards. |
| Hospital System Partnership | Secures multi-year consumable supply agreements with ambulatory surgical networks. |
| Software Companion Development | Creates recurring revenue streams through predictive analytics and automated segmentation. |
| Reimbursement Strategy | Aligns PMDA-METI coordination in Japan with outpatient procedural parity expansion. |
Research Methodology
Operator-level perspectives from robotic surgery program directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up installed base modeling and top-down capital expenditure triangulation cross-checked volume estimates.
Sensitivity analysis tested forecast robustness across alternative reimbursement scenarios and regulatory timeline assumptions over the projection horizon. Segmentation dimensions spanned product type, end-user facility tier, technology maturity, and application specialty. CAGRs derived from iterative convergence of historical capital expenditure patterns and forward procurement pipeline indicators. Machine learning integration intensity and ambulatory surgical center expansion velocity served as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance velocity or EU MDR implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding reimbursement parity evolution and optical component supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laparoscopic Devices Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Global Concussion Market
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market