
 High Speed Fiber Optic Sensor Market | 2026-2036
High Speed Fiber Optic Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Fiber Optic Sensor Market Analysis
REACH compliance is decoupling European market access from legacy manufacturing cost structures. Honeywell International Inc. leverages its aerospace certification depth to sustain premium positioning across structural health monitoring contracts. Yokogawa Electric Corporation anchors its competitive stance through dominant channel control in Japanese power generation installations. Luna Innovations Incorporated specializes in Brillouin scattering interrogator platforms that differentiate its offering in distributed temperature sensing.
High speed fiber optic sensors employ silica or polymer waveguides with response times below one millisecond to transduce strain, temperature, or pressure into optical signals for industrial telemetry. These devices enable real-time monitoring in environments where electromagnetic interference corrupts conventional electronic sensors. Distributed sensors lead installed base volume across pipeline and perimeter security networks, while non-intrusive sensors represent the fastest-expanding category as automotive battery pack manufacturers adopt embedded thermal monitoring. Point sensors command concentrated margin pools in aerospace landing gear and turbine blade applications where single-channel precision justifies unit premiums.
FDA device classification rules shape product validation pathways for biomedical fiber optic pressure sensors, while FAA airworthiness directives mandate continuous structural monitoring on next-generation commercial aircraft platforms. OSHA process safety management requirements drive oil and gas operators toward intrinsically safe optical sensing architectures in hazardous area classifications. Stakeholders must weigh certification timeline exposure against technology refresh cycles when allocating R&D across interrogator hardware and fiber coating innovations.
Market Dynamics
Aerospace manufacturers are mandating continuous structural monitoring on next-generation aircraft, forcing sensor suppliers to align certification timelines with FAA airworthiness directives while interrogator hardware refresh cycles compress from five years to three.
Growth Catalysts
- FAA Airworthiness Directives:Commercial aviation mandates for real-time structural health monitoring are pulling distributed fiber optic sensing into landing gear and turbine blade applications.
- Germany's Industrial Automation Corridor:Munich and Stuttgart manufacturing clusters are embedding high-speed optical sensors into precision tooling for sub-millisecond feedback loops.
- Silica Waveguide Advances:Improved coating chemistries are extending sensor lifespans in high-radiation environments, opening nuclear decommissioning contracts.
Market Restraints
- Specialized Fiber Supply Concentration:Photonic crystal fiber production concentrates in Japanese and German specialty glasshouses, creating single-source vulnerability for Brillouin scattering platforms.
- REACH Compliance Cost Escalation:ECHA substance restrictions on legacy coating materials are forcing reformulation investments that disproportionately burden mid-tier interrogator manufacturers.
- Electronic Sensor Substitution:MEMS pressure transducers with improved EMI shielding are reclaiming share in non-hazardous automotive applications below 150°C.
Strategic Opportunities
- EU AI Act Disclosure Requirements:Embedded sensing systems in industrial automation must document algorithmic performance, creating certified sensor bundling opportunities for compliant hardware vendors.
- Automotive Battery Pack Thermal Monitoring:Non-intrusive fiber optic temperature mapping is displacing thermocouple arrays in lithium-ion module assemblies as cell energy densities climb.
- Pipeline Perimeter Security:Distributed acoustic sensing networks are expanding beyond oil and gas into critical infrastructure protection for data center fiber backbones.
Industry Challenges
- Interrogator Firmware Talent Scarcity:DSP algorithm development for sub-millisecond signal processing requires rare expertise in optical physics and embedded systems co-design.
- Multi-Agency Certification Overlap:Biomedical pressure sensors face parallel FDA device classification and ISO 13485 quality system audits that extend validation timelines.
- Legacy SCADA Integration Friction:Oil and gas operators struggle to map optical sensor outputs into decades-old DCS architectures without full control system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Fiber Optic Sensor Market |
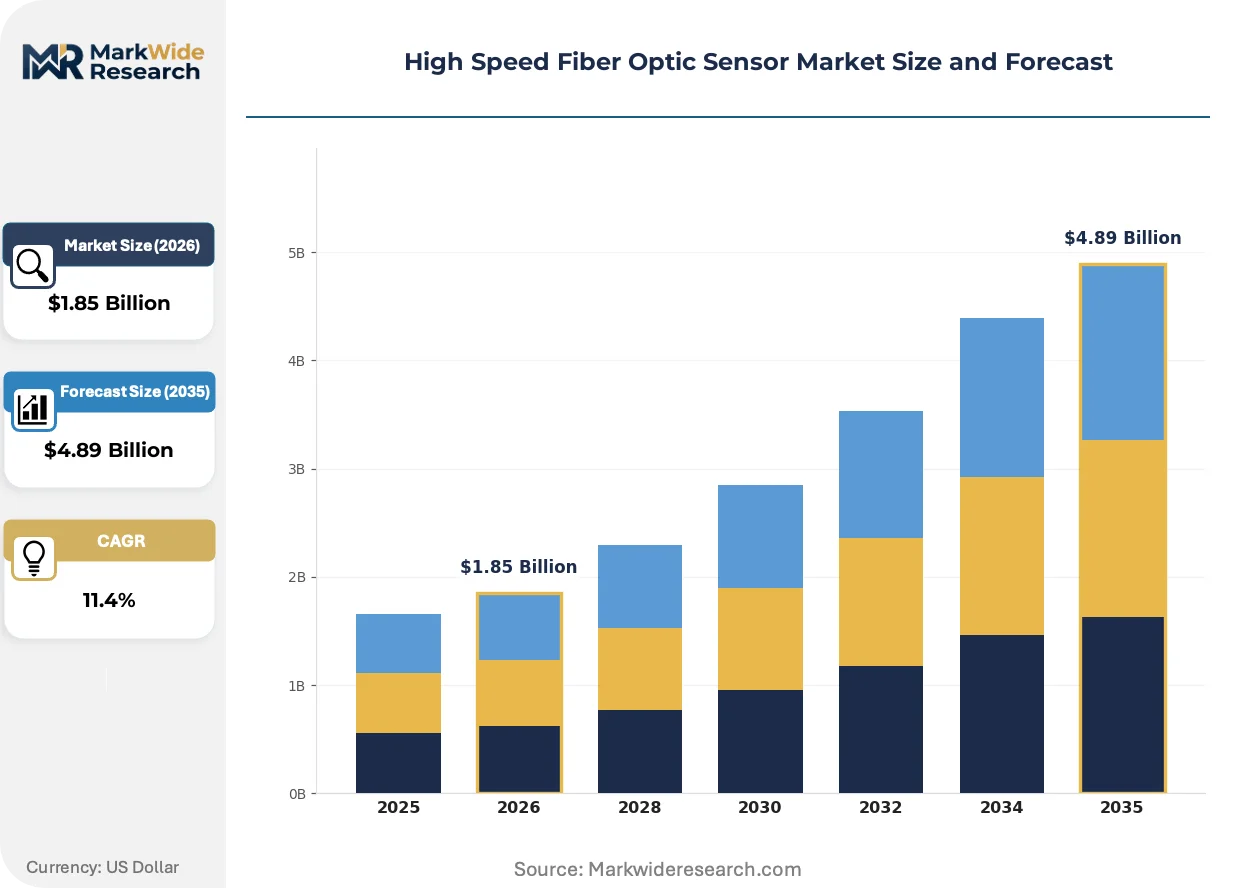
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusive Sensors, Non-Intrusive Sensors, Distributed Sensors, Point Sensors Application: Structural Health Monitoring, Temperature Sensing, Pressure Measurement, Vibration Monitoring End User: Aerospace, Oil & Gas, Automotive, Power Generation Technology: Time-Domain Reflectometry, Frequency-Domain Reflectometry, Phase-Shift Method, Brillouin Scattering |
| Companies Covered | Rockwell Automation, Micron Optics, STMicroelectronics, ON Semiconductor, Halliburton, Honeywell International Inc., SLB, Yokogawa Electric Corporation, Luna Innovations Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Fiber Optic Sensor Market Emerging Trajectories
Photonic integration is collapsing interrogator footprints while regulatory disclosure mandates are rewriting procurement specifications. Three developments are restructuring competitive advantage.
Silicon photonic chip-based interrogators are consolidating discrete optical benches into single-package solutions. Aerospace tier-1 suppliers are qualifying these platforms for weight-critical unmanned aerial vehicle programs. The consolidation is compressing bill-of-material costs and locking in early movers with airframe OEMs.
The EU AI Act's performance disclosure requirements for embedded sensing systems are forcing algorithm documentation into hardware procurement contracts. Industrial automation buyers in Germany now require traceability matrices linking sensor outputs to decision logic. Machine tool OEMs are responding by pre-certifying integrated sensing modules rather than selling discrete components.
Service unbundling is fragmenting long-term interrogator contracts. Japanese power generators are separating hardware procurement from calibration and fiber replacement services, compressing initial sale values while extending vendor relationship horizons. This shift is most visible in METI-regulated thermal plant upgrades where asset owners internalize predictive maintenance capabilities.
High Speed Fiber Optic Sensor Market Segmentation
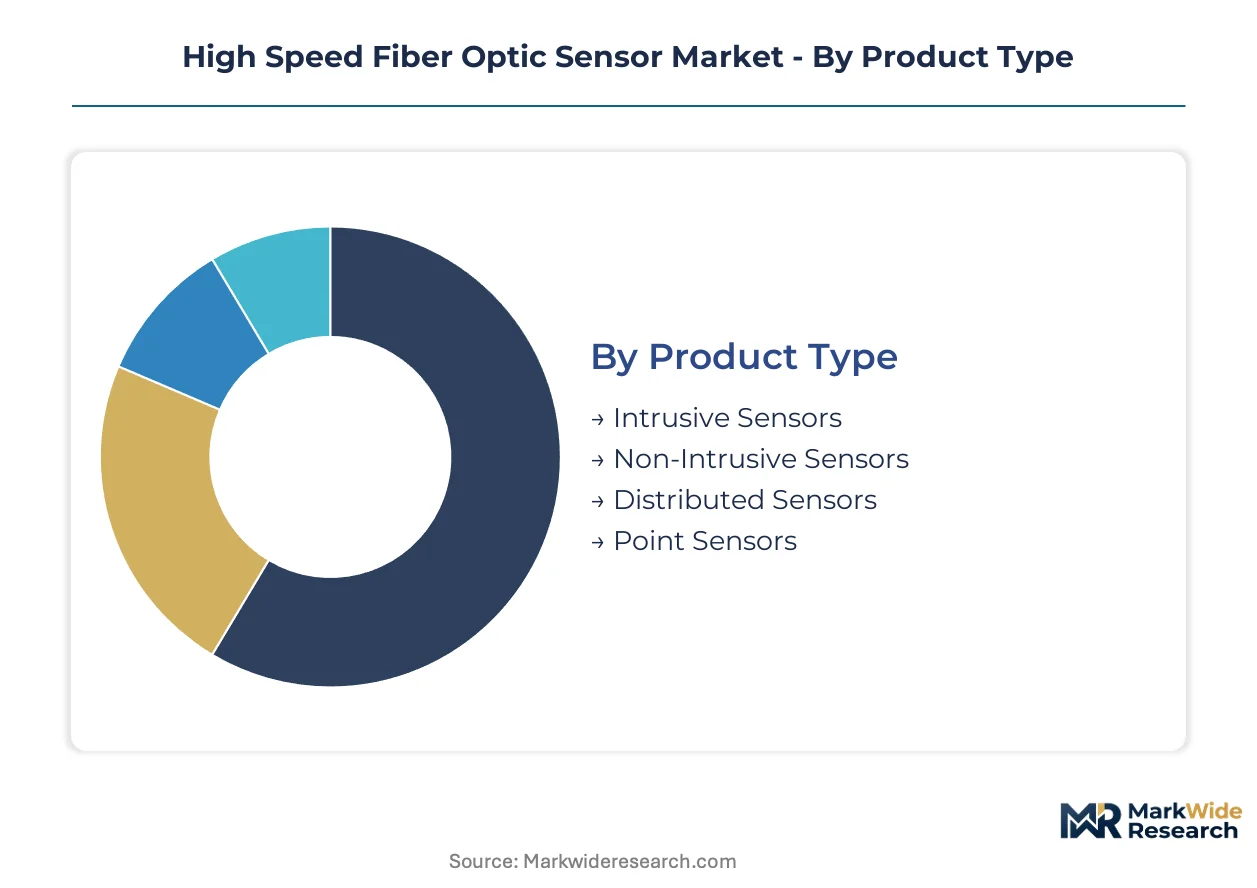
Segmentation in high speed fiber optic sensors reveals how interrogator hardware, sensing architecture, and end-use certification requirements create distinct competitive arenas. Vendors must align R&D allocation with the technical and regulatory intensity of each category.
Product Type:
Standardization dominates intrusive and point sensor designs, while distributed and non-intrusive platforms demand extensive customization for deployment-specific fiber routing and coating chemistries.
- Distributed Sensors:Continuous fiber runs measuring strain or temperature along kilometers of waveguide without discrete sensing points. Pipeline operators in Germany deploy these for perimeter security and leak detection, though photonic crystal fiber supply concentration in Japanese and German specialty glasshouses creates procurement vulnerability.
- Point Sensors:Discrete measurement nodes delivering single-channel precision for critical component monitoring. Aerospace landing gear and turbine blade applications command concentrated margin pools where FAA airworthiness directives justify unit premiums.
- Non-Intrusive Sensors:External mounting eliminates process penetration for hazardous environment compatibility. Automotive battery pack manufacturers embed thermal monitoring arrays as lithium-ion cell energy densities climb.
- Intrusive Sensors:Direct media contact designs for high-fidelity pressure and temperature measurement in process vessels. Oil and gas operators favor these for subsea wellhead monitoring where EMI immunity outweighs installation complexity.
Most installed capacity flows through Distributed Sensors. Expansion is steepest in Non-Intrusive Sensors.
Application:
Application segmentation tracks how end-use performance thresholds split procurement between off-the-shelf interrogator platforms and engineered sensing networks.
- Structural Health Monitoring:Real-time strain and deformation tracking in aircraft, bridges, and wind turbines. FAA mandates for next-generation commercial aircraft platforms are pulling distributed fiber optic sensing into landing gear assemblies.
- Temperature Sensing:Thermal profile mapping for process control and safety systems. Power generation utilities in Japan deploy Brillouin scattering interrogators for transformer and cable monitoring under METI efficiency regulations.
- Pressure Measurement:High-speed transduction for hydraulic and pneumatic systems. FDA device classification rules shape validation pathways for biomedical fiber optic pressure sensors.
- Vibration Monitoring:Dynamic mechanical analysis for rotating machinery and seismic detection. Industrial automation corridors around Munich and Stuttgart embed optical sensors for sub-millisecond feedback loops in precision tooling.
Structural Health Monitoring absorbs the largest share of interrogator hardware investment. Temperature Sensing is climbing the fastest as power grid modernization accelerates.
End User:
End user segmentation exposes how regulatory exposure and asset criticality determine sensor specification tiers and vendor qualification depth.
- Aerospace:Airframe and propulsion system monitoring with multi-agency certification requirements. Tier-1 suppliers qualify silicon photonic chip-based interrogators for weight-critical unmanned aerial vehicle programs.
- Oil & Gas:Pipeline integrity and reservoir monitoring in hazardous area classifications. OSHA process safety management requirements drive operators toward intrinsically safe optical sensing architectures.
- Power Generation:Thermal plant and grid infrastructure monitoring. Japanese generators separate hardware procurement from calibration services, compressing initial sale values while extending vendor relationships.
- Automotive:Battery thermal management and structural validation for electric vehicle platforms. Non-intrusive fiber optic temperature mapping displaces thermocouple arrays in lithium-ion module assemblies.
Aerospace commands the highest specification premiums. Automotive is gaining share fastest as battery energy densities drive embedded thermal monitoring adoption.
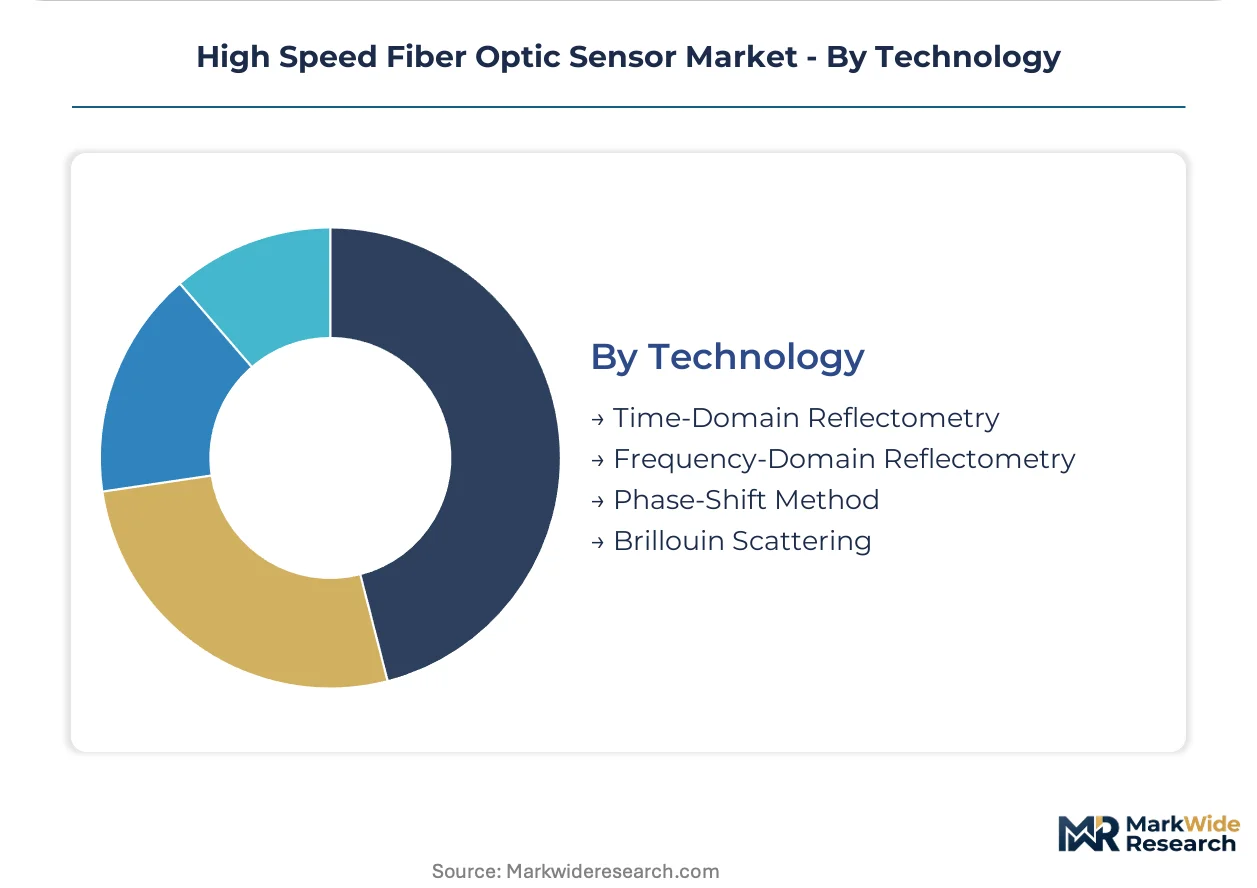
Technology:
Technology segmentation maps interrogator signal processing methods to measurement range, resolution, and environmental tolerance trade-offs.
- Brillouin Scattering:Distributed strain and temperature measurement through acoustic phonon interaction with optical pulses. Specialized platforms differentiate offerings in long-range pipeline and power cable monitoring.
- Time-Domain Reflectometry:Pulse-echo ranging for fault location and distributed sensing with straightforward implementation. Standard interrogator designs serve cost-sensitive industrial automation deployments.
- Frequency-Domain Reflectometry:Modulated continuous-wave techniques for enhanced spatial resolution. Emerging adoption in precision structural health monitoring where measurement granularity justifies complexity.
- Phase-Shift Method:Interferometric approaches for ultra-high sensitivity displacement and vibration detection. Laboratory and seismic applications leverage these platforms where picometer resolution is essential.
Time-Domain Reflectometry carries the broadest installed base. Brillouin Scattering shows the steepest expansion trajectory as distributed sensing networks extend beyond oil and gas into data center and critical infrastructure protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized photonics engineers cluster in Germany's precision manufacturing belt, Japan's industrial electronics corridors, and the US aerospace engineering hubs. This talent distribution shapes where interrogator hardware development and fiber coating innovation concentrate.
United States
FAA airworthiness directives for next-generation commercial aircraft are pulling distributed fiber optic sensing into landing gear and turbine blade applications. OSHA process safety management requirements drive oil and gas operators toward intrinsically safe optical sensing architectures in hazardous area classifications. Houston's energy corridor and Seattle's aerospace engineering cluster host the densest concentrations of fiber sensor system integrators.
Germany
REACH compliance is decoupling European market access from legacy manufacturing cost structures and forcing coating material reformulation investments. The EU AI Act and CSRD tighten performance disclosure requirements for embedded sensing systems in industrial automation. Munich and Stuttgart manufacturing clusters embed high-speed optical sensors into precision tooling for sub-millisecond feedback loops.
Japan
METI-regulated thermal plant upgrades drive Brillouin scattering interrogator deployment for transformer and cable monitoring under efficiency regulations. Photonic crystal fiber production concentrates in Japanese specialty glasshouses, creating single-source vulnerability for distributed sensing platforms. Nagoya's industrial belt and Tokyo's precision electronics corridor anchor domestic interrogator manufacturing.
China
Dual carbon goals accelerate power grid modernization and distributed temperature sensing deployment across transmission infrastructure. GB standards and MIIT regulations shape domestic product certification pathways for industrial optical sensors. The Yangtze River Delta manufacturing belt concentrates fiber coating and interrogator assembly capacity.
United Kingdom
Offshore wind farm construction drives structural health monitoring demand for turbine blade strain sensing in North Sea installations. The country's national aerospace regulator aligns with EASA frameworks for fiber optic sensing certification on commercial aircraft platforms. Cambridge's photonics cluster and Scotland's offshore engineering corridor host specialized sensor development facilities.
High Speed Fiber Optic Sensor Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive aerospace and energy customer relationships. Tier-1 airframe suppliers and oilfield service operators qualify vendors through multi-year certification cycles that freeze out new entrants. Three archetypes dominate: integrated automation giants with broad sensing portfolios, specialized fiber interrogator developers with proprietary signal processing IP, and energy-sector service providers with hazardous-area deployment expertise. Competitive moves center on silicon photonic chip integration for weight-critical applications and service unbundling that separates hardware procurement from calibration contracts.
Within the diversified industrial tier, Honeywell International Inc. and Rockwell Automation occupy positions shaped by deep aerospace certification depth and broad factory automation footprints respectively. Yokogawa Electric Corporation and Luna Innovations Incorporated exemplify specialization archetypes, with the former anchoring channel control in Japanese power generation and the latter representing Brillouin scattering platform expertise. STMicroelectronics sits within the semiconductor-integrated tier, leveraging silicon photonic fabrication capabilities.
| Leading Market Players |
|---|
| Rockwell Automation |
| Micron Optics |
| STMicroelectronics |
| ON Semiconductor |
| Halliburton |
| Honeywell International Inc. |
| SLB |
| Yokogawa Electric Corporation |
| Luna Innovations Incorporated |
| Others |
Supply Flow & Price Mechanics
Family-owned specialty glasshouses in Japan and Germany anchor photonic crystal fiber production, translating concentrated upstream ownership into disciplined pricing power for Brillouin scattering interrogators while contract structures fragment toward unbundled service models.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware procurement from calibration and fiber replacement contracts, with Japanese power generators driving this shift under METI regulations. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth—FAA airworthiness tiering commands unit premiums in aerospace landing gear, while automotive battery pack manufacturers squeeze mid-tier suppliers on volume scale. Cost compression in standard interrogator tiers is intensifying because REACH compliance forces coating reformulation investments. Automotive OEMs exhibit highest price sensitivity as thermocouple substitution threat constrains optical sensor premiums, whereas aerospace tier-1 suppliers absorb least sensitivity given airframe qualification lock-in.
Supply Chain Analysis
Domestic-content mandates reshaping sourcing in China's Yangtze River Delta manufacturing belt are pressuring foreign interrogator assemblers to localize fiber coating operations. Photonic crystal fiber draws from Japanese and German specialty glasshouses, silica waveguide inputs rest on refined quartz sand processing, and silicon photonic chips hinge on semiconductor foundry capacity. Single-source vulnerability concentrates in photonic crystal fiber supply, where Japanese glasshouse concentration creates procurement chokepoints. Distribution runs through direct OEM qualification channels for aerospace and energy sectors, with industrial automation corridors favoring systems integrator intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA airworthiness directives for structural health monitoring establish this market as a stable compounder, with regulatory mandates locking in interrogator refresh cycles that outpace typical industrial sensor replacement rates.
For Market Incumbents: Cement silicon photonic chip integration partnerships with aerospace OEMs before qualification windows close, while capturing calibration service contracts that extend vendor relationships beyond hardware depreciation. MEMS pressure transducers with improved EMI shielding threaten non-hazardous automotive share below 150°C. Channel control in Japanese power generation and German industrial automation corridors remains the critical defensive lever. For New Entrants and Emerging Players: Silicon photonic interrogator platforms offer a technology-first wedge into unmanned aerial vehicle programs where weight-critical specifications favor consolidated optical benches. Automotive battery pack thermal monitoring represents the most penetrable white-space as lithium-ion energy densities climb, with non-intrusive fiber routing displacing legacy thermocouple arrays. A go-to-market angle through METI-regulated Japanese thermal plant upgrades bypasses entrenched European supplier relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized fiber interrogator developers with proprietary Brillouin scattering IP but limited channel reach. Long-term viability over a five-to-ten year window hinges on regulatory mandate durability rather than technology substitution risk. Acquisition target archetype: mid-tier interrogator manufacturers with FAA certification progress but stranded without silicon photonic roadmaps. Watch FAA airworthiness directive expansion into unmanned platforms as the inflection signal for distributed sensing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonic Chip Integration | Consolidates optical benches for weight-critical UAV qualification under FAA directives. |
| Service Unbundling | Separates hardware procurement from calibration contracts in METI-regulated Japanese power upgrades. |
| REACH Compliance Reformulation | Extends coating lifespan for nuclear decommissioning contracts in high-radiation environments. |
| EU AI Act Pre-Certification | Bundles algorithmic traceability into machine tool OEM sensing modules for German automation. |
| Automotive Battery Pack Embedding | Displaces thermocouple arrays in lithium-ion modules as cell energy densities climb. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aerospace certification engineers, power plant maintenance directors, automotive battery thermal management leads, and industrial automation systems integrators with secondary validation against FAA airworthiness filings, METI efficiency regulation updates, ECHA substance restriction databases, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up interrogator shipment estimates and top-down end-use demand projections were cross-referenced for triangulation.
Comparable-period anchoring tied projection models to historical certification cycle data and technology refresh patterns across the analysis window. Segmentation dimensions included sensing architecture type, signal processing technology, end-use certification tier, and regional regulatory cluster. CAGRs were derived from installed base growth rates weighted by replacement cycle compression. Industry-specific inputs incorporated photonic crystal fiber supply constraints and silicon photonic foundry capacity expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FAA mandate expansion timing, REACH substance restriction scope creep, and MEMS sensor EMI shielding breakthroughs. Forecasts reflect documented assumptions regarding certification timeline exposure and technology refresh synchronization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Silicon Focus Ring Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Digital Cinema Lens Market
Optical Components
Silicon Photonics Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Optical Sensor Market
Optical Components
Co-Packaged Optics Market
Optical Components
Optical Transmitter Market
Optical Components
Fogless Mirror Market
Optical Components
Ring Panel Filters Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
CVD Sic Ring Market