
 Silicon Focus Ring Market | 2026-2036
Silicon Focus Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Focus Ring Market Insights
Extreme ultraviolet lithography migration is reconfiguring silicon focus ring specifications across leading foundries. Silfex Inc. leverages vertical integration from raw polysilicon to finished rings, sustaining cost advantages in high-purity grades. Hana Materials Inc. anchors South Korean supply chains through proximity to domestic etch equipment OEMs. CoorsTek competes via ceramic-to-silicon hybrid architectures for plasma-facing components.
A silicon focus ring is a high-purity monocrystalline or polycrystalline silicon component, typically 99.999% plus purity, machined to sub-micron tolerances for plasma etch and deposition chambers; it functions as an electrostatic confinement boundary that shapes plasma density distribution and protects chamber walls from ion bombardment. Customized focus rings command premium positioning as 3nm logic and advanced memory nodes require application-specific edge profiles and thermal expansion matching. Precision manufacturing technology dominates value capture, while coating technologies represent the fastest-growing segment as atomic layer deposition barriers extend ring lifetimes in fluorocarbon-rich chemistries.
Japan's METI enforces JIS standards for semiconductor materials traceability, while South Korea's K-Battery and K-Semiconductor Acts mandate domestic sourcing quotas for critical chamber components. The US CHIPS Act and NIST measurement protocols create parallel compliance pathways for suppliers serving Intel and GlobalFoundries fabs. Stakeholders must monitor which regulatory jurisdiction's certification requirements their end customers prioritize when selecting manufacturing locations and qualification strategies.
Market Dynamics
Extreme ultraviolet lithography node migration is compressing tolerance specifications for plasma-facing components while fragmenting supplier qualification pathways across major semiconductor manufacturing clusters.
Growth Catalysts
- MIIT semiconductor self-sufficiency directives:China's domestic sourcing mandates for critical chamber components accelerate localized silicon focus ring procurement from qualified suppliers.
- Fluorocarbon-rich etch chemistries:Advanced memory and logic nodes require atomic layer deposition barrier coatings that extend ring lifetimes and reduce chamber downtime.
- Pyeongtaek-Yongin corridor concentration:Samsung and SK Hynix foundry clusters in South Korea generate concentrated demand for high-purity monocrystalline rings with application-specific edge profiles.
Market Restraints
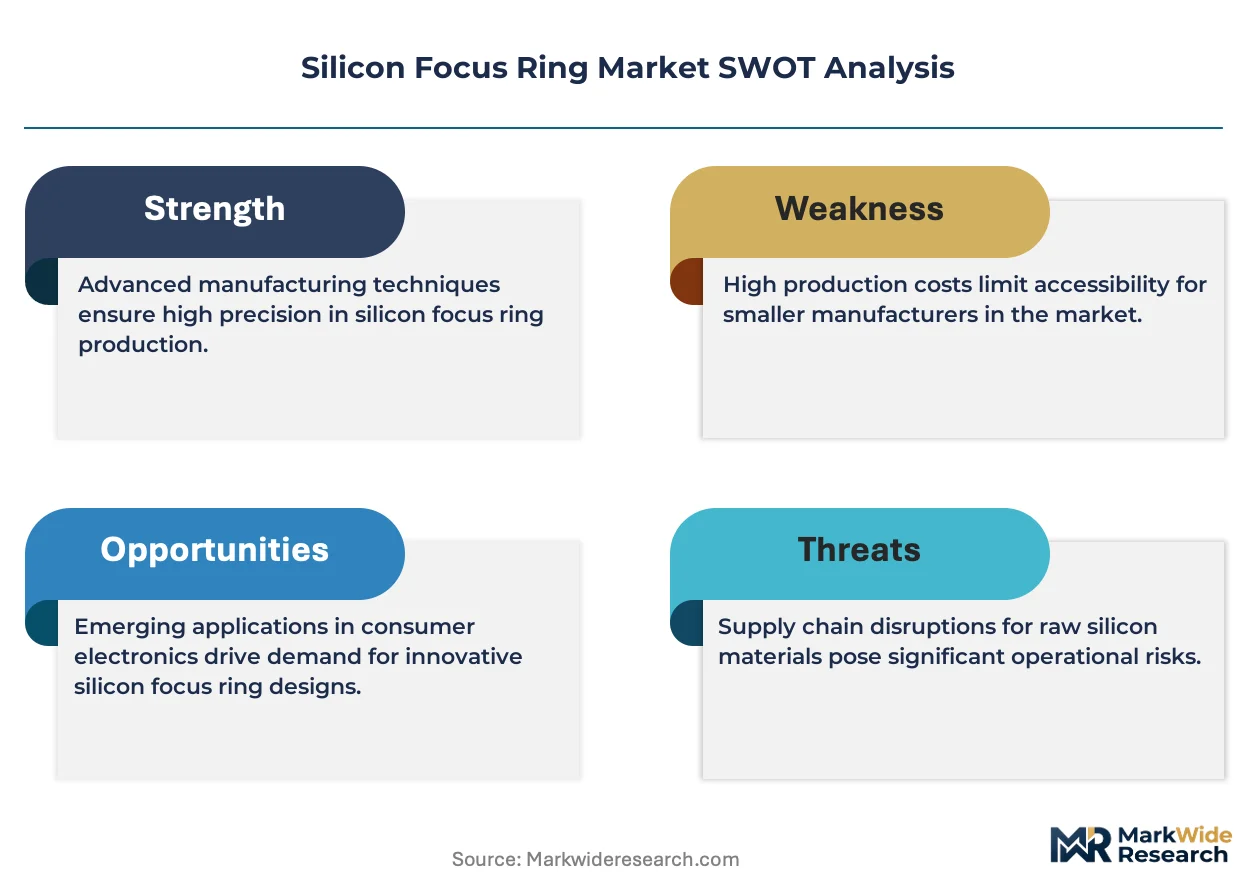
- Polysilicon feedstock volatility:Semiconductor-grade polysilicon pricing fluctuations compress margins for non-vertically integrated ring fabricators.
- East Asian supply concentration:Overreliance on Japanese and South Korean raw material suppliers creates geopolitical exposure for European and North American equipment OEMs.
- JIS traceability compliance costs:METI-enforced material provenance documentation adds qualification overhead for new market entrants.
Strategic Opportunities
- India's PLI scheme for semiconductors:Central government production-linked incentives for domestic fab construction create virgin demand for qualified chamber component suppliers.
- Ceramic-to-silicon hybrid architectures:Composite plasma-facing components combining silicon precision with ceramic thermal properties open etch equipment retrofit markets.
- Direct OEM contracting models:Bypassing traditional distributor channels allows ring fabricators to capture qualification data and accelerate design iteration cycles.
Industry Challenges
- Sub-micron machining talent scarcity:Precision grinding and chemical mechanical polishing expertise concentrates among veteran technicians in Japan and Germany.
- Dual certification timelines:Simultaneous NIST measurement protocol and K-Battery Act compliance extends product qualification cycles for suppliers serving multiple jurisdictions.
- Legacy equipment integration friction:New ring designs must maintain backward compatibility with installed base etch chambers running 200mm and 300mm wafer formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Focus Ring Market |
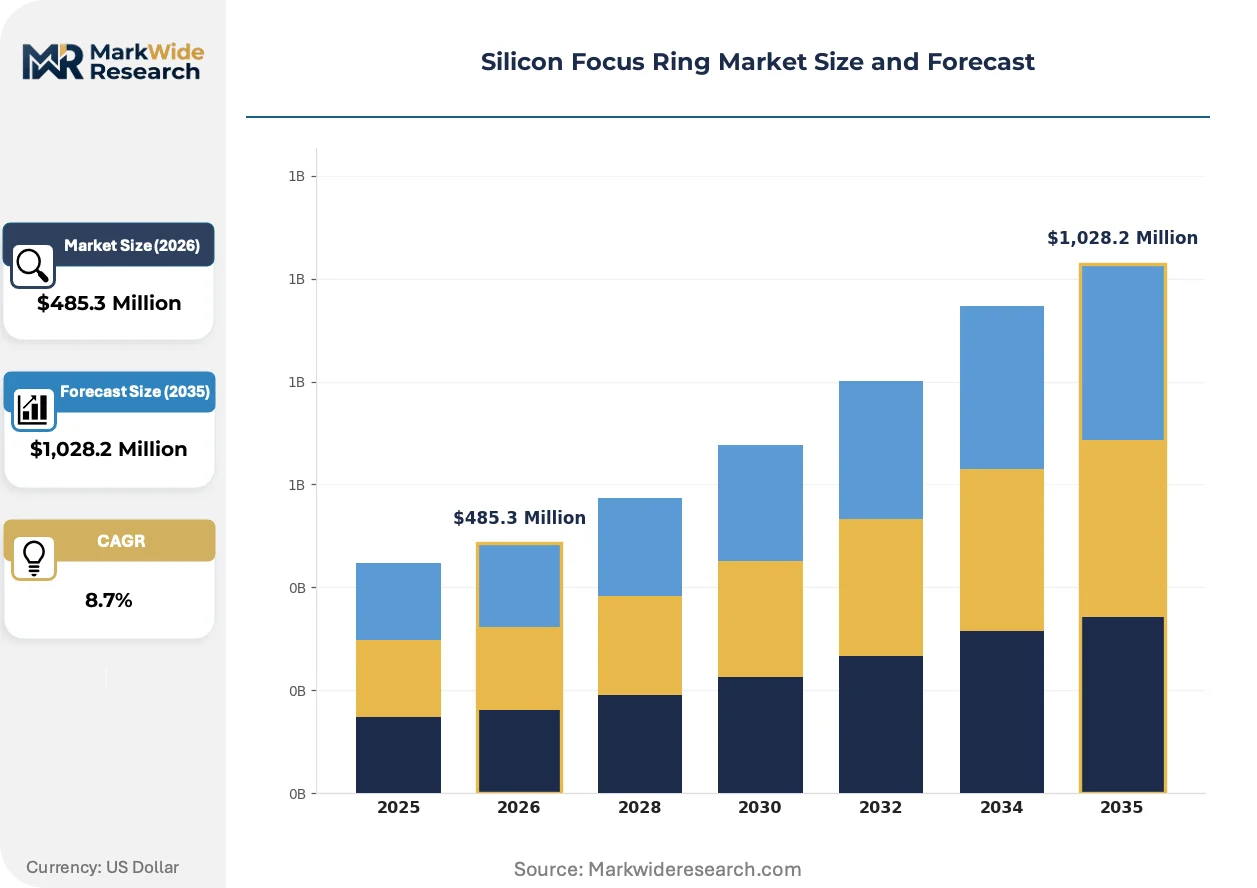
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Focus Rings, Customized Focus Rings, Dual Focus Rings, Optoelectronic Focus Rings End User: Semiconductor Manufacturers, Optical Component Developers, Research Institutions, Laser System Integrators Application: Fiber Optics, Laser Systems, Photo Detectors, Imaging Systems Technology: Precision Manufacturing, Coating Technologies, Simulation Software, Testing Equipment |
| Companies Covered | Silfex Inc., Hana Materials Inc., CoorsTek, Mitsubishi Materials, Worldex Industry & Trading Co., Ltd., Tokai Carbon, Kallex, Daewon, Greene Tweed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Focus Ring Market Trends and Innovations
Plasma uniformity control specifications are tightening faster than conventional machining capabilities, forcing material science and process engineering convergence in component design.
Atomic layer deposition barrier coatings on silicon focus rings are rendering obsolete uncoated monocrystalline rings in fluorocarbon etch applications. Leading foundries in South Korea and Taiwan now specify coated rings for 3nm logic node production. The technology is compressing replacement cycle economics and shifting value capture toward surface engineering specialists.
Japan's METI JIS standards for semiconductor materials traceability now require batch-level provenance documentation from polysilicon source to finished ring. Equipment OEMs serving Japanese fabs must audit supplier records against these protocols. European and North American fabricators are establishing parallel documentation systems to maintain access to METI-regulated procurement channels.
Consolidated procurement through etch equipment OEMs is displacing independent ring sourcing by individual fabs. Applied Materials and Lam Research now specify qualified supplier lists for chamber components bundled with equipment sales. South Korean memory manufacturers have been quickest to adopt this bundled sourcing model, reducing direct supplier relationships.
Silicon Focus Ring Market Segmentation
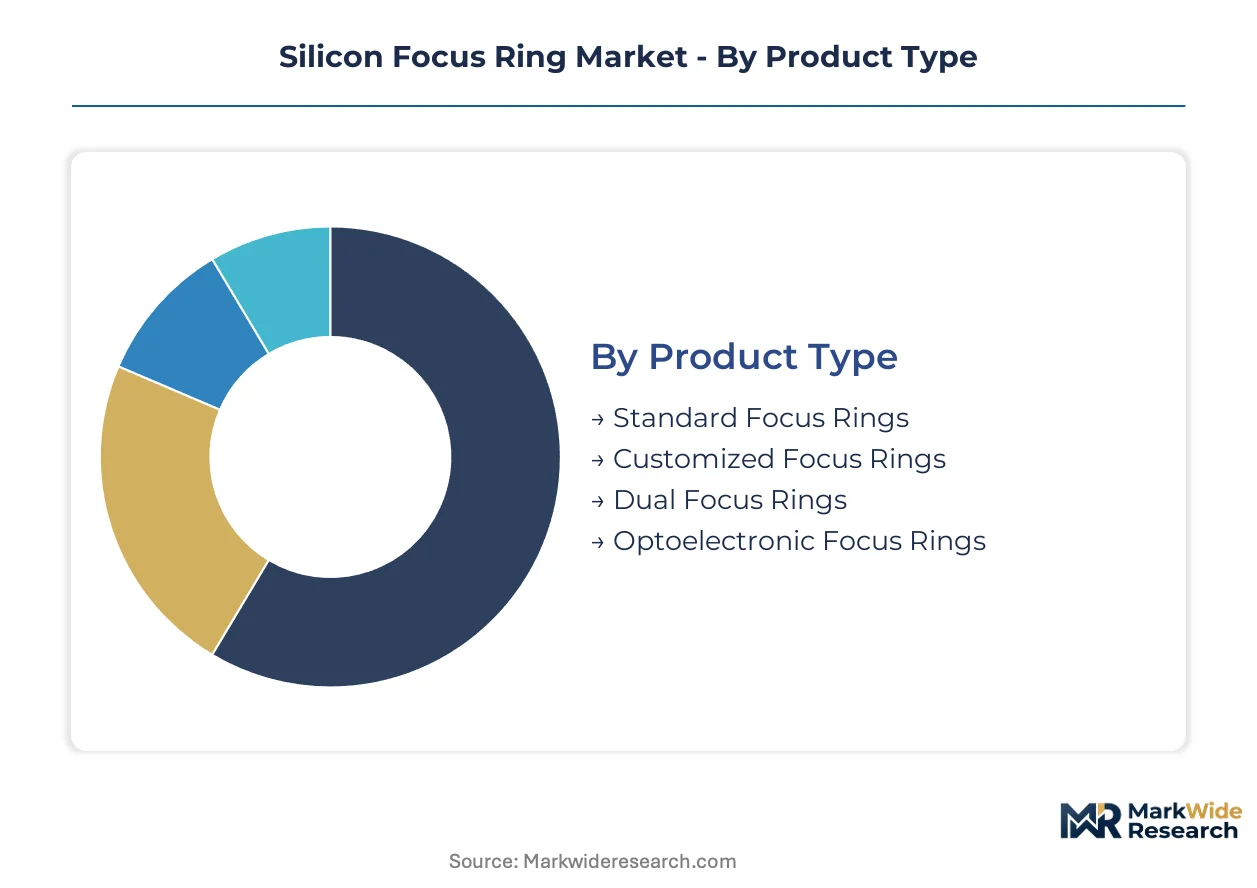
Silicon focus ring procurement patterns diverge sharply across product tiers and end-use applications. Precision requirements from EUV lithography nodes and fluorocarbon etch chemistries are fragmenting demand specifications across semiconductor manufacturing clusters.
Product Type:
Cost tier differentiation separates commodity replacement rings from application-specific engineered components.
- Customized Focus Rings:Application-specific edge profiles and thermal expansion coefficients match 3nm logic node requirements. Samsung and SK Hynix foundries in South Korea's Pyeongtaek-Yongin corridor specify these for advanced memory and logic production.
- Standard Focus Rings:Generic monocrystalline silicon rings serve legacy 200mm and 300mm etch chambers with established plasma uniformity profiles. Maintenance procurement from mature fabs in Japan and Germany sustains volume.
- Dual Focus Rings:Stacked architectures enable rapid chemistry switching in multi-process chambers.
- Optoelectronic Focus Rings:Specialized surface finishes support photonics and optical sensor fabrication.
Customized Focus Rings holds installed capacity. Dual Focus Rings is rotating up the share rankings.
End User:
Customer type determines qualification pathways and contracting structures across the value chain.
- Semiconductor Manufacturers:Foundries and IDMs drive specifications through direct OEM partnerships with Applied Materials and Lam Research. China's MIIT self-sufficiency directives accelerate localized procurement from qualified domestic suppliers.
- Research Institutions:National laboratories and university cleanrooms purchase low volumes with extreme customization requirements.
- Optical Component Developers:Photonics specialists source rings for telecom and datacom laser packaging.
- Laser System Integrators:Industrial and medical laser builders integrate rings into resonator cavity designs.
Semiconductor Manufacturers command specification authority. Research Institutions is climbing the fastest as EUV research programs expand.
Application:
Volume concentration tracks the migration of data infrastructure and precision optics manufacturing.
- Fiber Optics:Telecommunications backbone expansion and hyperscale datacenter interconnects drive demand for low-insertion-loss components. Corning and Fujikura supply chains in the US and Japan specify tight concentricity tolerances.
- Laser Systems:Industrial cutting, medical surgery, and LiDAR applications require thermal stability under high-power operation.
- Photo Detectors:Automotive ADAS and consumer electronics imaging modules use rings for sensor packaging alignment.
- Imaging Systems:Semiconductor inspection and metrology equipment incorporate rings in optical column assemblies.
Fiber Optics anchors current volume. Photo Detectors is gaining share fastest from automotive sensor proliferation.
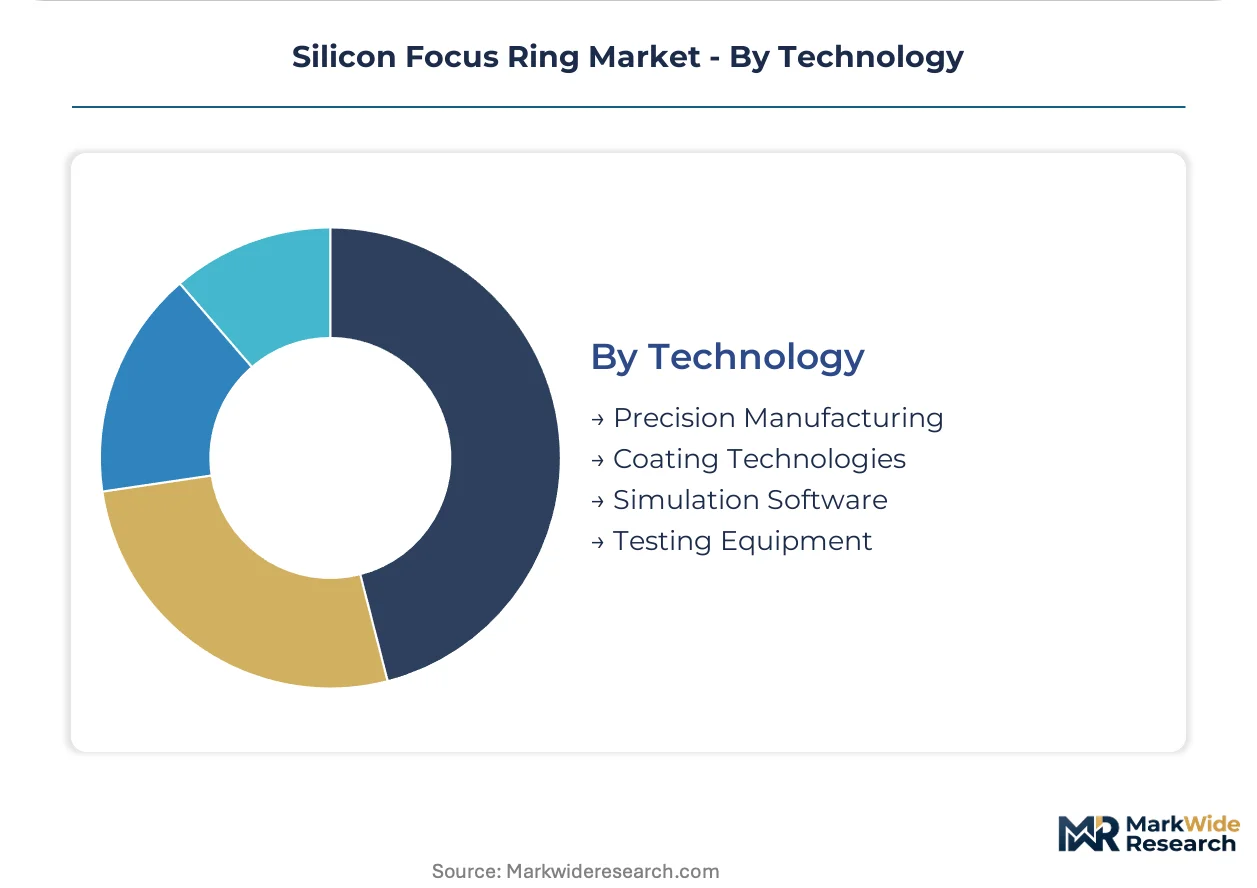
Technology:
Margin capture shifts upstream from fabrication toward surface engineering and predictive tooling.
- Coating Technologies:Atomic layer deposition barriers extend ring lifetimes in fluorocarbon-rich etch chemistries. South Korean foundries now mandate coated rings for 3nm production, compressing replacement economics.
- Precision Manufacturing:Sub-micron grinding and chemical mechanical polishing expertise concentrates among veteran technicians in Japan and Germany.
- Simulation Software:Plasma modeling tools reduce physical prototyping cycles for new ring geometries.
- Testing Equipment:Non-destructive characterization systems verify purity and dimensional compliance.
Precision Manufacturing retains the deepest capability moats. Coating Technologies is expanding most quickly as surface engineering displaces bulk material value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese polysilicon refiners and South Korean ring fabricators dominate export flows to foundry clusters in Taiwan and the United States, creating a tightly coupled East Asian supply corridor for EUV-grade chamber components.
United States
Intel and GlobalFoundries fabs in Arizona and New York drive procurement of coated monocrystalline rings for advanced logic production. NIST measurement protocols govern qualification pathways for domestic suppliers. The CHIPS Act funding concentration in Phoenix and Albany is accelerating local supply chain development for plasma-facing components.
China
Domestic foundry construction by SMIC and Hua Hong Semiconductor is generating demand for high-purity silicon rings in Shanghai and Beijing. MIIT semiconductor self-sufficiency directives mandate localized sourcing quotas for critical chamber components. The Yangtze River Delta cluster around Wuxi and Suzhou is emerging as a qualification hub for domestic ring fabricators.
South Korea
Samsung and SK Hynix memory foundries in Pyeongtaek and Yongin specify application-specific edge profiles for 3nm production. The K-Semiconductor Act enforces domestic procurement quotas for strategic chamber components. The Gyeonggi Province corridor concentrates etch equipment OEM partnerships and ring qualification facilities.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor demand for ultra-high-purity polysilicon feedstock and finished rings. METI-enforced JIS standards require batch-level provenance documentation from source to finished component. The Kyushu and Nagoya industrial zones host precision grinding expertise for sub-micron tolerance machining.
Germany
Infineon and Bosch semiconductor operations in Saxony and Bavaria sustain demand for legacy 300mm etch chamber maintenance rings. REACH compliance and CE marking requirements structure import qualification for Asian suppliers. The Dresden silicon cluster maintains specialized chemical mechanical polishing capabilities for European equipment OEMs.
Silicon Focus Ring Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated polysilicon-to-ring fabricators and specialized precision machining houses dependent on external feedstock. Three archetypes dominate: upstream-integrated material suppliers, proximity-focused regional fabricators, and surface engineering specialists. Capacity expansion in South Korea and strategic partnerships with etch equipment OEMs represent the primary competitive vectors.
Among North American suppliers, Silfex Inc. exemplifies the upstream-integrated archetype through captive polysilicon refining. Hana Materials Inc. and CoorsTek occupy differentiated positions within the precision fabrication tier, with the former representing proximity-based supply chain anchoring and the latter exemplifying hybrid material architecture development.
| Leading Market Players |
|---|
| Silfex Inc. |
| Hana Materials Inc. |
| CoorsTek |
| Mitsubishi Materials |
| Worldex Industry & Trading Co., Ltd. |
| Tokai Carbon |
| Kallex |
| Daewon |
| Greene Tweed |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Pyeongtaek maritime corridor carries semiconductor-grade polysilicon and finished focus rings between Chinese refiners and South Korean foundry clusters, with freight cost volatility amplifying margin compression for non-integrated fabricators while reinforcing price premiums for vertically controlled supply chains serving EUV-grade specifications.
Pricing Analysis
The 3nm-to-5nm node pricing gap separates application-specific customized rings from legacy standard replacements, with coating technology premiums widening as atomic layer deposition barriers become mandatory for fluorocarbon etch chemistries. Pricing stratifies across EUV-certified, trailing-node qualified, and maintenance-tier segments, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard rings intensifies because Chinese domestic sourcing mandates expand qualified supplier pools. Memory manufacturers in South Korea exhibit lowest price sensitivity due to chamber downtime costs, while mature fab operators in Europe prioritize unit economics.
Supply Chain Analysis
Tariff exposure between Japan and South Korea dominates supply chain risk planning for equipment OEMs sourcing ultra-high-purity polysilicon feedstock. Manufacturing concentrates in Japan, South Korea, and the United States, with production anchored in polysilicon refining capability, precision grinding expertise, and surface engineering infrastructure. The supply chain draws from semiconductor-grade polysilicon, chemical mechanical polishing consumables, and atomic layer deposition precursor chemicals. Single-source vulnerability persists for sub-micron machining talent concentrated in Kyushu and Dresden. Distribution runs through etch equipment OEM qualified supplier lists rather than direct fab procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicon focus ring market is approaching a platform-economics inflection as etch equipment OEM bundling consolidates procurement channels and interoperability standards around chamber component specifications.
For Market Incumbents: Harden qualification data advantages by capturing plasma modeling telemetry from installed base equipment, creating feedback loops that accelerate design iteration beyond what unintegrated competitors can match. Deepen backward integration into polysilicon refining to defend margin position against feedstock volatility. METI JIS traceability requirements raise compliance barriers that favor incumbents with established documentation systems.
For New Entrants and Emerging Players: Build out coating technology capabilities as the most penetrable segment, since surface engineering expertise concentrates among fewer specialists than precision fabrication and commands expanding share of ring economics. Target India's PLI scheme beneficiary fabs as virgin demand with less entrenched supplier relationships. Pursue direct OEM contracting models to bypass distributor channels and capture qualification data.
For Investors and Strategic Acquirers: The K-Semiconductor Act and CHIPS Act implementation reshape the acquisition landscape by creating geographically bounded demand pools that favor regional supply chain anchoring. Five-to-ten year viability hinges on exposure to EUV node migration rather than legacy maintenance markets. Prioritize surface engineering specialists with atomic layer deposition capabilities as acquisition targets. Monitor MIIT domestic sourcing quota enforcement intensity as the signal indicating Chinese market access conditions for foreign suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | Silfex Inc.'s captive feedstock supply insulates margins from spot price volatility. |
| Atomic Layer Deposition Coating Scale-Up | South Korean foundry mandates for 3nm production expand addressable market for barrier specialists. |
| Direct OEM Contracting Model | Applied Materials and Lam Research bundling displaces independent fab procurement channels. |
| India PLI Scheme Market Entry | Central government incentives for domestic fab construction create first-mover qualification opportunities. |
| Hybrid Ceramic-Silicon Architecture Development | CoorsTek's composite designs open retrofit markets for thermal performance upgrades. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with semiconductor manufacturing stakeholders and secondary validation against trade and regulatory records. Interview sources included etch equipment OEM procurement directors, foundry chamber engineering leads, polysilicon refinery technical managers, and precision machining house operations heads. Secondary sources comprised MIIT policy directives, METI JIS standard documentation, K-Semiconductor Act implementation guidance, SEC filings from listed equipment manufacturers, and customs data tracking polysilicon and finished ring trade flows. Bottom-up fabrication capacity modeling and top-down foundry capex allocation analysis were triangulated against each other.
Forecast inputs considered technology node migration timelines, fluorocarbon chemistry adoption curves, and regional sourcing mandate enforcement intensity across the projection horizon. Segmentation dimensions modeled include product type tier, end-user procurement structure, application technology requirements, and surface engineering technology adoption. CAGRs were derived from installed base replacement cycles, new fab equipment procurement patterns, and coating technology penetration assumptions. Industry-specific inputs incorporated EUV lithography node ramp schedules and atomic layer deposition barrier qualification protocols.
Practitioners should monitor MIIT quota enforcement, METI traceability audit frequency, and K-Semiconductor Act domestic content threshold adjustments for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Optical Component Tester Market
Optical Components
Laser Photomask Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Fogless Mirror Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
CMP Polishing Machine Market
Optical Components
Prism Coupler Market
Optical Components
Co-Packaged Optics Market
Optical Components
North America Tunable Laser Market
Optical Components
Bio-Optics Market
Optical Components
Microchannel Plates Market
Optical Components
Optical Film Market
Optical Components
Quartz Glass Substrate Market
Optical Components
Optical Waveguide Market