
 Optical Transmitter Market | 2026-2036
Optical Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Transmitter Market Analytics
Platform licensing revenue is tilting toward silicon photonics foundry partnerships as module vendors seek to defray capex burdens. Broadcom leverages its vertical integration in indium phosphide lasers to sustain margin capture across the 800G generation. Coherent Corp. anchors its position through backward integration into lithium niobate modulator crystals. Eoptolink Technology specializes in cost-optimized QSFP-DD designs for Chinese data center operators.
An optical transmitter converts electrical signals into modulated light for fiber-optic communication, typically operating at wavelengths of 1310 nm or 1550 nm with output powers between 0 dBm and 10 dBm depending on link budget requirements. The device serves as the critical electro-optical interface in telecom networks, cloud data centers, and broadcast distribution systems. Coherent transmitter modules command premium positioning due to digital signal processor complexity and forward error correction overhead. Wavelength division multiplexing technology dominates long-haul and metro deployments where spectrum efficiency determines fiber economics. Data center end users are shifting procurement toward pluggable coherent optics to displace discrete transponder shelves.
FCC Part 68 registration requirements govern optical transmitter connection to US public networks, while the EU RoHS directive restricts hazardous substances in module assemblies sold across Europe. China's MIIT enforces GB standards for optical interface interoperability in domestic 5G backhaul builds. The EU AI Act and CSRD reporting obligations will soon extend supply chain due diligence to optical component sourcing. Stakeholders must monitor open standards body convergence between OIF and IEEE as interoperability definitions determine qualification timelines and customer lock-in dynamics.
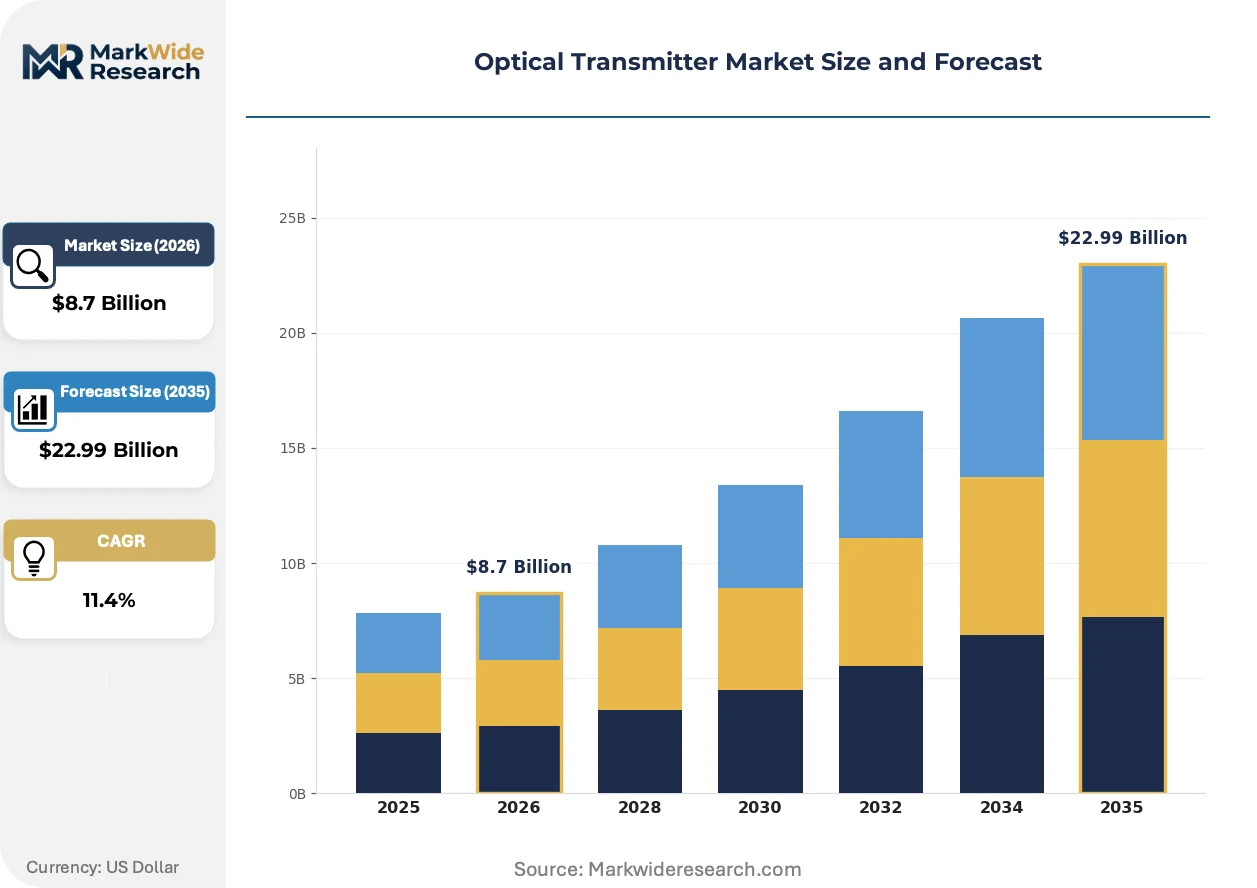
Market Dynamics
OpenZR+ interoperability standards and silicon photonics integration are compressing qualification timelines while reshaping supplier selection criteria across data center interconnect builds. Module vendors must now demonstrate foundry partnerships alongside optical performance metrics to secure hyperscale procurement contracts.
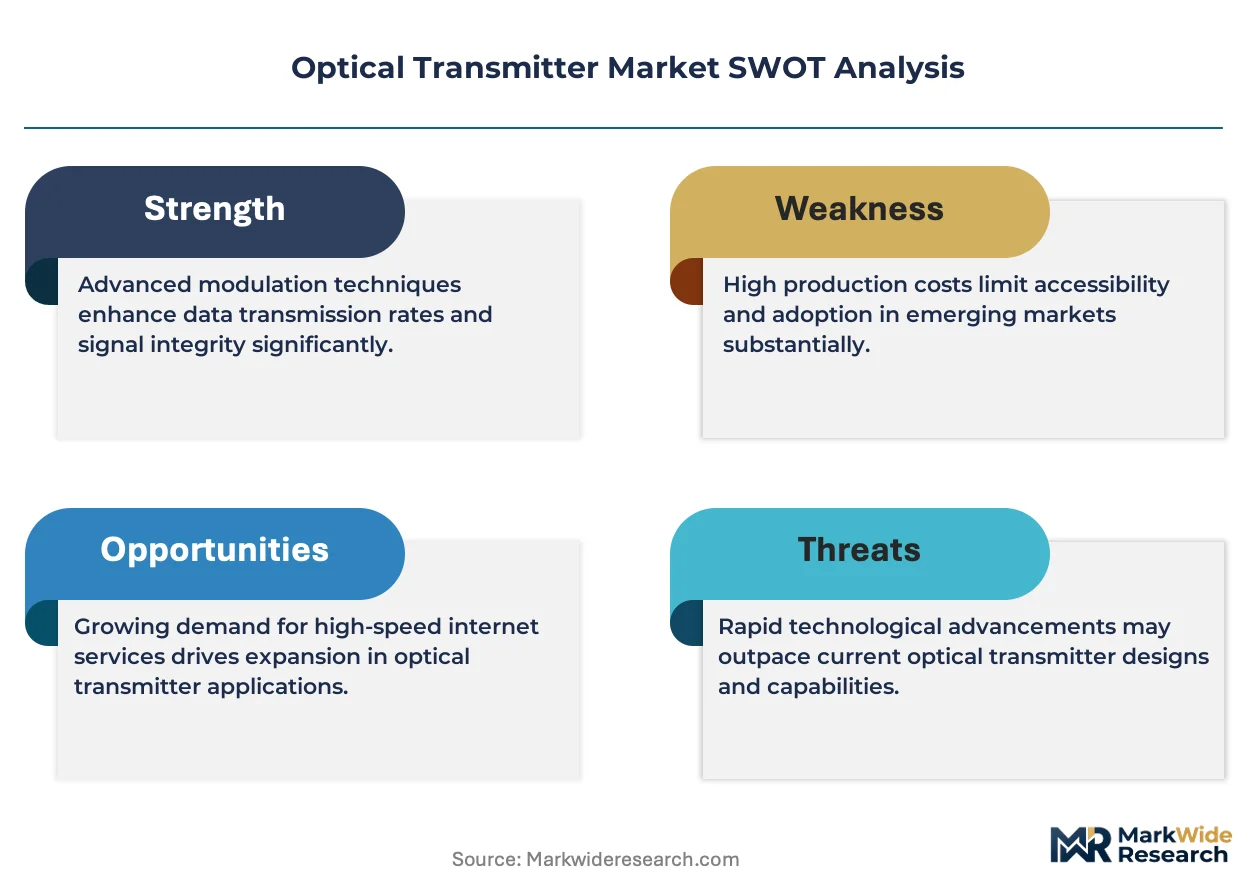
Growth Catalysts
- 400G/800G Infrastructure Deployment:Hyperscale cloud operators in the United States, China, and Germany are accelerating fiber capacity expansion to support AI training clusters and real-time inference workloads.
- EU CSRD Reporting Obligations:Supply chain due diligence requirements are mandating traceability in optical component sourcing, favoring vendors with documented ESG compliance across module assemblies.
- Silicon Photonics Integration:CMOS-compatible manufacturing processes are reducing per-channel costs while enabling co-packaged optics architectures in next-generation switches.
Market Restraints
- Indium Phosphide Supply Concentration:High-performance laser diode production concentrates among a limited set of compound semiconductor foundries, creating input cost volatility for coherent transmitter modules.
- FCC Part 68 Registration Friction:Connection approval requirements for US public networks extend product launch timelines and create compliance overhead for foreign module vendors.
- Discrete Transponder Shelf Displacement Lag:Legacy chassis-based systems persist in carrier networks where operational inertia and sunk infrastructure costs slow pluggable coherent adoption.
Strategic Opportunities
- Chinese Domestic 5G Backhaul:MIIT-enforced GB standards for optical interface interoperability are creating qualified supplier slots for module vendors with local manufacturing footprints.
- Co-packaged Optics Convergence:Integration of silicon photonics with switch ASICs is opening architecture decisions at hyperscale operators previously captive to pluggable module form factors.
- EU AI Act Compliance Positioning:High-reliability optical links for AI infrastructure are attracting premium positioning where supply chain documentation meets emerging algorithmic system requirements.
Industry Challenges
- Coherent DSP Talent Scarcity:Digital signal processor design expertise for 800G generation modules concentrates among a narrow pool of specialists, constraining vendor R&D scaling.
- OIF-IEEE Standardization Divergence:Competing interoperability definitions between standards bodies are fragmenting qualification test suites and extending customer validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Transmitter Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Modulator, Integrated Modulator, Coherent Transmitter, Directly Modulated Laser Technology: Wavelength Division Multiplexing, Frequency Division Multiplexing, Time Division Multiplexing, Analog Transmission End User: Telecommunications, Data Centers, Broadcasting, Enterprise Networks Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Broadcom Inc., Hisense Broadband Inc., Coherent Corp., Source Photonics Inc., Eoptolink Technology Inc., Accelink Technology Co. Ltd., Cisco Systems Inc., Lumentum Holdings Inc., InnoLight Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Transmitter Market Evolving Landscape
Silicon photonics manufacturing is compressing cost structures while coherent DSP complexity is extending performance differentiation. Module form factors and integration architectures are simultaneously evolving.
Pluggable coherent optics using QSFP-DD and OSFP form factors is rendering obsolete discrete transponder shelves in metro and data center interconnect applications. Hyperscale operators are standardizing on these modules for 400G and 800G links. The shift is collapsing traditional optical transport equipment margins while reallocating value capture toward DSP and silicon photonics suppliers.
China's MIIT enforcement of GB standards for optical interface interoperability is mandating domestic certification for 5G backhaul module procurement. Foreign vendors must establish local testing partnerships and manufacturing presence to maintain qualified supplier status. The regulation is segmenting supply bases between domestic Chinese builds and international deployments.
Hyperscale operators are consolidating optical module procurement through direct foundry partnerships rather than traditional component distributors. Cloud providers in the United States and Germany are negotiating silicon photonics wafer supply agreements that bypass conventional channel structures. The disintermediation is compressing distributor margins while extending vendor working capital requirements.
Optical Transmitter Market Segmentation
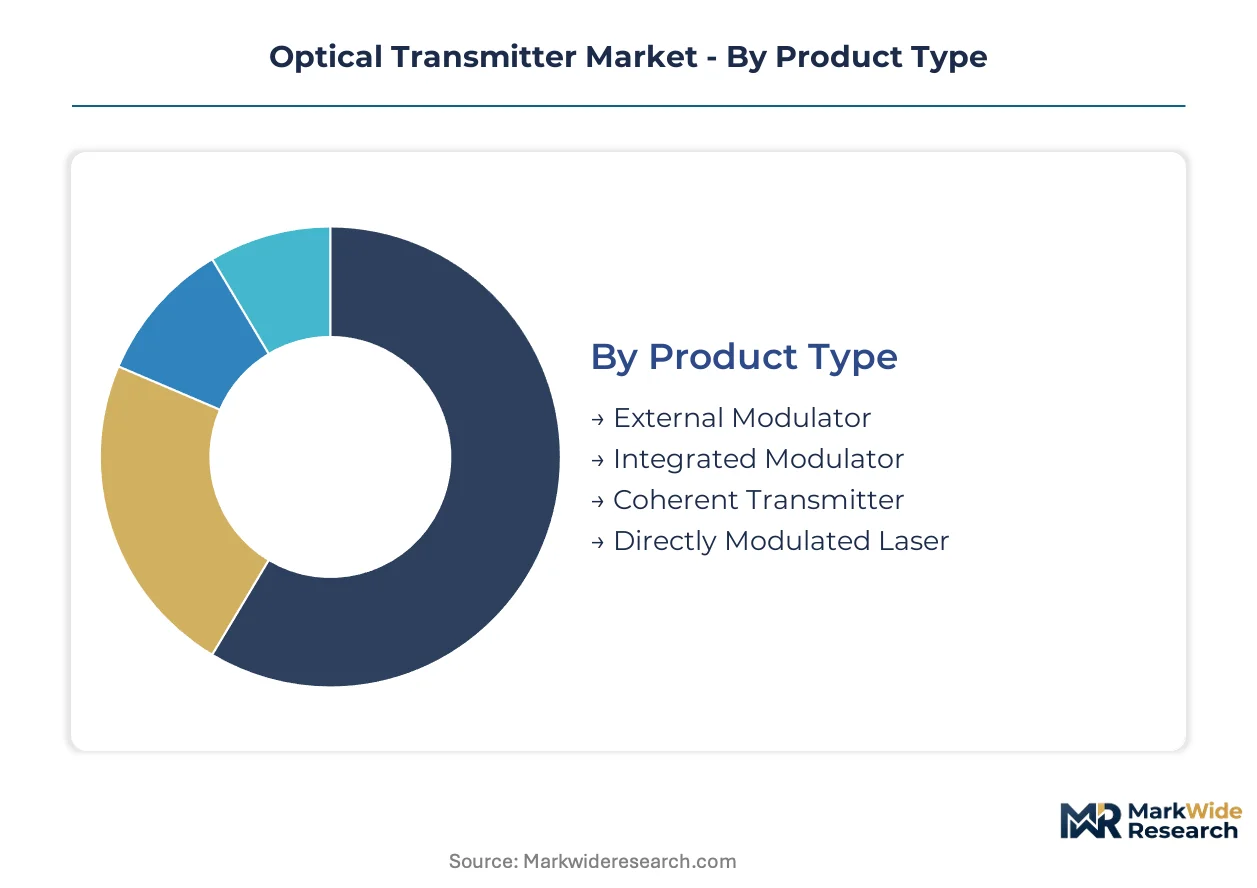
Optical transmitter procurement patterns diverge sharply across product architectures and deployment contexts. Understanding these segment boundaries clarifies where silicon photonics integration is compressing margins versus where coherent DSP complexity sustains premium positioning.
Product Type:
Mature discrete designs coexist with emerging integrated architectures as data center operators recalibrate form factor preferences.
- Coherent Transmitter:Digital signal processor-enabled modules with forward error correction overhead dominate 400G/800G data center interconnect builds. Hyperscale operators in the United States and Germany are standardizing procurement on these units for AI training cluster backhaul.
- Integrated Modulator:Silicon photonics-based designs merge modulator and laser functions on single chips, reducing per-channel costs for Chinese data center operators seeking QSFP-DD form factor density.
- External Modulator:Lithium niobate crystal-based devices serve legacy long-haul networks where established link budgets resist architecture migration.
- Directly Modulated Laser:Simplified electro-optical conversion meets cost-sensitive enterprise access links with relaxed performance requirements.
Coherent transmitter modules handle the majority of throughput; integrated modulator designs are gaining share fastest in hyperscale procurement.
Technology:
Cost tier stratification separates spectrum-efficient core network technologies from simpler access-layer alternatives.
- Wavelength Division Multiplexing:Multiple optical carriers on single fiber cores maximize spectrum efficiency in metro and long-haul deployments. FCC Part 68 registration requirements govern these connections to US public networks, extending qualification timelines.
- Time Division Multiplexing:Sequential channel aggregation suits enterprise network backhaul where fiber scarcity is less acute than in carrier infrastructure.
- Frequency Division Multiplexing:Radio-frequency overlay techniques persist in hybrid fiber-coaxial broadcast distribution systems.
- Analog Transmission:Continuous-wave modulation serves specialized broadcast and sensing applications outside digital communication mainstream.
Wavelength division multiplexing carries the bulk of installed capacity; time division multiplexing is expanding most quickly in enterprise edge builds.
End User:
Customer type determines performance specifications and procurement channel structures across the value chain.
- Data Centers:Hyperscale cloud operators in China, Germany, and the United States are displacing discrete transponder shelves with pluggable coherent optics. Direct foundry partnerships are consolidating procurement away from traditional distributors.
- Telecommunications:Carrier networks exhibit operational inertia where sunk chassis investments slow pluggable module adoption despite total cost advantages.
- Enterprise Networks:Mid-scale organizations prioritize interoperability certification over bleeding-edge data rates, creating stable demand for established form factors.
- Broadcasting:Real-time video distribution maintains specialized requirements for analog transmission compatibility and signal latency consistency.
Data center procurement commands the dominant revenue share; telecommunications is climbing fastest as carrier pluggable migration accelerates.
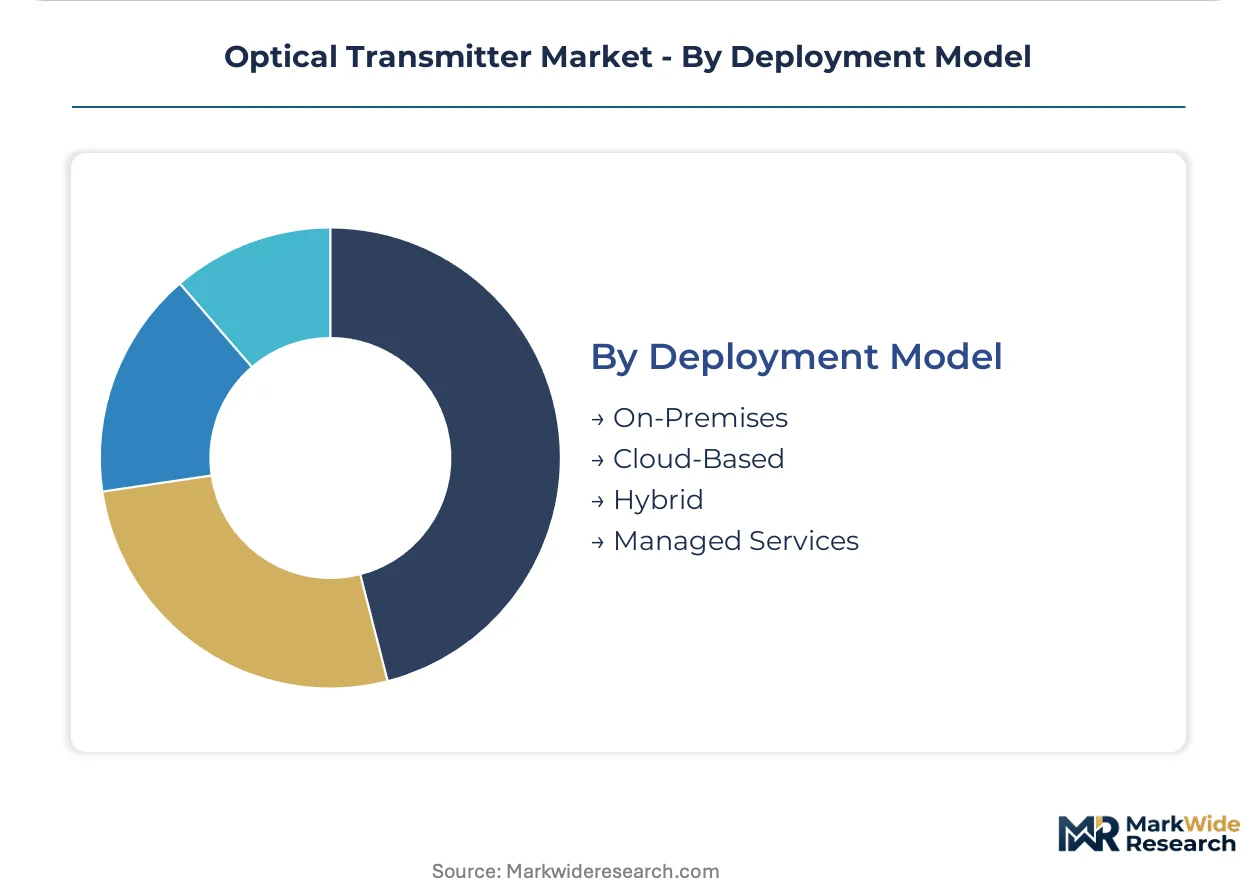
Deployment Model:
Supply concentration varies across ownership structures, with cloud-based models concentrating purchasing power among fewer decision-makers.
- Cloud-Based:Hyperscale operators negotiate silicon photonics wafer supply agreements that bypass conventional channel structures, compressing distributor margins while extending vendor working capital requirements.
- On-Premises:Enterprise-owned infrastructure maintains fragmented procurement through systems integrators and value-added resellers.
- Hybrid:Split workload architectures create dual qualification requirements for modules serving both private data center and public cloud interconnects.
- Managed Services:Outsourced network operations transfer transmitter procurement decisions to telecommunications carriers and specialized optical network operators.
Cloud-based deployment handles the majority of volume growth; hybrid models are expanding most quickly as enterprises navigate workload migration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in Germany demonstrate the lowest price elasticity, absorbing premium coherent modules for AI training clusters, while Chinese data center buyers prioritize cost-optimized QSFP-DD designs. The United States sits between these extremes, balancing performance requirements with procurement consolidation through direct foundry partnerships.
United States
Microsoft, Amazon, and Google are deploying 400G/800G pluggable coherent optics across their domestic AI infrastructure. FCC Part 68 registration requirements govern optical transmitter connections to public networks, extending qualification timelines for foreign module vendors. Northern Virginia's data center corridor concentrates procurement volume where hyperscale operators negotiate silicon photonics wafer supply agreements bypassing traditional distributors.
China
Domestic cloud providers Alibaba, Tencent, and Baidu are accelerating fiber capacity expansion for real-time inference workloads. MIIT enforces GB standards for optical interface interoperability in 5G backhaul builds, mandating domestic certification for module procurement. Shenzhen and Wuhan host manufacturing clusters where Eoptolink Technology and Accelink Technology optimize cost structures for local data center operators.
Germany
Deutsche Telekom and regional cloud operators are standardizing on coherent transmitter modules for AI training cluster backhaul with minimal price sensitivity. EU CSRD reporting obligations mandate supply chain due diligence in optical component sourcing, favoring vendors with documented ESG compliance. Frankfurt's financial data center hub drives premium module demand where latency consistency commands technical specification priority.
Japan
NTT and KDDI are migrating metro networks toward pluggable coherent optics while maintaining legacy chassis investments in rural segments. METI industrial policy supports domestic silicon photonics foundry development to reduce dependence on foreign compound semiconductor supply. Tokyo-Osaka corridor data centers concentrate procurement for financial services and manufacturing IoT applications.
South Korea
Samsung and Naver are deploying high-speed coherent modules for domestic AI infrastructure and cloud gaming latency requirements. MFDS-equivalent telecommunications certification processes align with international standards while maintaining domestic testing protocols. Pangyo Techno Valley and Seoul metropolitan area data centers concentrate demand for 800G generation optical interconnects.
Optical Transmitter Market Competitive Landscape
Compound semiconductor specialists and CMOS-integrated platform vendors split the market along technology architecture lines. The vendor base concentrates among fifteen to twenty qualified suppliers, with tiering determined by foundry access and DSP design capability. Three archetypes dominate: vertically integrated indium phosphide laser manufacturers, silicon photonics foundry partners, and cost-optimized QSFP-DD module assemblers. Competitive moves center on backward integration into lithium niobate modulator crystals and strategic partnerships with hyperscale cloud operators for direct wafer supply agreements.
Within the premium coherent module tier, Broadcom Inc. and Coherent Corp. occupy positions sustained by captive laser and modulator supply chains. Among China-based module assemblers, Eoptolink Technology Inc. and Accelink Technology Co. Ltd. exemplify the cost-optimization archetype serving domestic data center procurement. InnoLight Technology Co. Ltd. represents the hybrid model bridging silicon photonics integration with hyperscale direct partnerships.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Hisense Broadband Inc. |
| Coherent Corp. |
| Source Photonics Inc. |
| Eoptolink Technology Inc. |
| Accelink Technology Co. Ltd. |
| Cisco Systems Inc. |
| Lumentum Holdings Inc. |
| InnoLight Technology Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Trans-Pacific fiber-optic cable routes from Shanghai to Los Angeles carry the heaviest module traffic, with freight cost volatility amplifying price spreads between indium phosphide-based coherent transmitters and silicon photonics alternatives. Supply concentration in Chinese foundries and Japanese compound semiconductor facilities feeds downstream pricing power differentials that hyperscale buyers navigate through direct wafer agreements.
Pricing Analysis
Platform licensing and extended service contracts generate the majority of lifetime value in coherent module procurement. Three-tier pricing structure across premium coherent DSP modules, standard silicon photonics designs, and economy direct-modulation lasers dominates transactional flows. Cost compression in the standard tier is intensifying because Chinese module assemblers are scaling QSFP-DD production for domestic data center builds. Enterprise network buyers exhibit the highest price sensitivity, while German AI training cluster operators absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for module vendors serving hyperscale procurement. Manufacturing concentrates in China, Japan, and the United States, with indium phosphide laser diodes, lithium niobate modulator crystals, and silicon photonics wafers serving as critical input dependencies. Single-source vulnerability in compound semiconductor foundries threatens input cost stability. Distribution runs through direct foundry partnerships at hyperscale operators, bypassing traditional component distributors and compressing channel margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OpenZR+ interoperability standards and silicon photonics integration constitute a regulatory-technological inflection that will displace legacy discrete transponder architectures. Market participants must recalibrate positioning around DSP design capability and foundry access rather than module assembly scale.
For Market Incumbents: Build captive laser supply moats through backward integration into indium phosphide manufacturing or exclusive foundry partnerships. Secure qualified supplier status under China's MIIT GB standards by establishing local testing and production footprints. Defend against pluggable coherent displacement by accelerating chassis-based system retirement programs for carrier network customers. For New Entrants and Emerging Players: Mid-market telecommunications carriers in Southeast Asia represent the most penetrable entry point where operational inertia has slowed pluggable coherent adoption. Cost-optimized QSFP-DD designs for Chinese domestic 5G backhaul procurement offer a second white-space target. Pursue go-to-market positioning through silicon photonics foundry partnerships that bypass traditional distributor channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors DSP design specialists with coherent 800G generation expertise over pure-play module assemblers. Long-term viability hinges on architectural control points shifting toward silicon photonics integration and co-packaged optics convergence. Watch hyperscale direct procurement consolidation as the signal indicating permanent channel structure change.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Secures wafer supply for 800G coherent modules at hyperscale operators in the United States and Germany. |
| MIIT GB Standards Certification | Unlocks qualified supplier slots for China's domestic 5G backhaul and data center interconnect builds. |
| Co-packaged Optics Integration | Positions vendors for next-generation switch architectures displacing pluggable module form factors. |
| Lithium Niobate Backward Integration | Captures modulator crystal supply chain value in premium coherent transmitter tier. |
| EU CSRD Compliance Documentation | Meets emerging supply chain due diligence requirements for optical component sourcing across European deployments. |
Research Methodology
A spread of perspectives from optical module procurement executives at hyperscale operators, coherent DSP design engineers, compound semiconductor foundry managers, and telecommunications carrier network planners converged on the working assumptions. Primary interview insights combined with secondary validation from FCC Part 68 registration databases, MIIT GB standards filings, EU CSRD regulatory disclosures, and hyperscaler capital expenditure reports. Bottom-up module shipment tracking and top-down optical transport equipment revenue analysis provided triangulation anchors.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework. Segmentation dimensions modeled include product architecture type, technology generation, end-user deployment context, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and hyperscale capacity expansion trajectories. Forecast inputs incorporated silicon photonics yield improvements and coherent DSP power efficiency roadmaps without assuming specific technology transition dates.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or fiber-optic cable deployment rates would shift the trajectory. Forecasts reflect documented assumptions regarding OpenZR+ standards adoption timing and pluggable coherent displacement velocity in carrier networks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Optical Film Market
Optical Components
Optical Cross Connect Market
Optical Components
Optical Film Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Microchannel Plates Market
Optical Components
Co-Packaged Optics Market
Optical Components
Photosensitive Glass Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Package Shell for Optical Communication Modules Market
Optical Components
Acousto Optic Devices Market