
 Moisture Detection Stickers Market | 2026-2036
Moisture Detection Stickers Market Size, Share, and Industry Trends Forecast 2026-2036
Moisture Detection Stickers Market Outlook
Specialty packaging distributors is rewriting how moisture detection stickers reach end users in regulated industries. AMETEK MOCON Inc. leverages its permeation testing heritage to anchor high-barrier packaging validation programs for pharmaceutical clients. Labthink Instruments Co., Ltd. competes on instrumentation-to-consumable bundling, while Desiccare Inc. specializes in desiccant-integrated indicator systems for military and aerospace logistics.
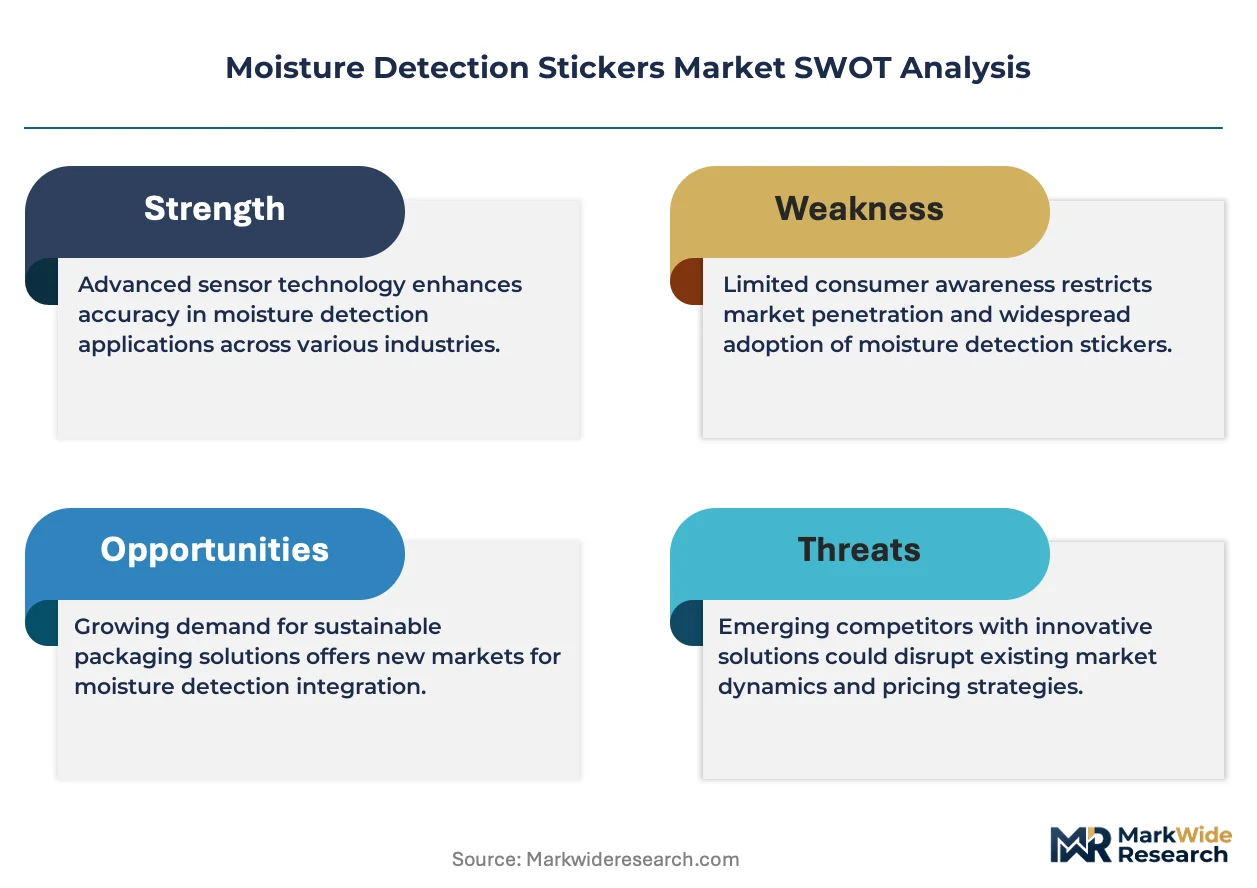
Moisture detection stickers are thin-film humidity indicators, typically cobalt chloride or copper chloride impregnated substrates, that undergo visible color transitions at defined relative humidity thresholds to signal moisture ingress in sealed environments. Printed stickers dominate unit volumes across food and pharmaceutical packaging lines where single-use cost minimization governs procurement, though smart tags embedding RFID and capacitive sensors capture the fastest value growth as real-time supply chain visibility becomes mandatory. Flexible sensors occupy a narrower niche in wearable textile applications where wash-cycle durability determines specification compliance.
FDA 21 CFR Part 11 and EU MDR traceability mandates push manufacturers toward electronic record-compatible indicator formats, while REACH restrictions on cobalt compounds force reformulation toward halogen-free colorimetric chemistries. Japan's METI circular economy guidelines add material recovery requirements for adhesive label backings in cross-border electronics shipments. Stakeholders must decide whether to absorb smart tag premium costs or risk disqualification from regulated tenders as digital chain-of-custody rules harden across major import jurisdictions.
Market Dynamics
Serialized moisture tracking requirements from pharmaceutical cold chain packaging are forcing converters to abandon passive cobalt chloride indicators in favor of smart, data-logging formats that satisfy digital chain-of-custody mandates.
Growth Catalysts
- EU MDR traceability mandates:Medical device sterilization kits exported from Germany must now carry humidity-logging labels with electronic record compatibility, accelerating smart sticker adoption across Bavarian packaging clusters.
- Pharmaceutical serialization:Biologics and vaccine shippers require real-time moisture ingress data to protect high-value payloads, creating sustained pull for integrated sensor-label systems.
- Halogen-free chemistry advances:REACH restrictions on cobalt compounds are driving R&D investment into copper chloride and organic dye alternatives that maintain colorimetric precision without hazardous substance classification.
Market Restraints
- Raw material concentration:Specialty adhesive substrates for humidity-sensitive coatings depend on a narrow supplier base concentrated in East Asian chemical processing zones, exposing converters to input volatility.
- Smart tag cost premiums:RFID and capacitive sensor integration adds unit costs that disqualify sticker suppliers from commodity food packaging tenders where single-use minimization governs procurement.
- Technical durability limits:Flexible humidity sensors for textile applications face wash-cycle performance degradation that narrows addressable markets to disposable wearable segments.
Strategic Opportunities
- Underpenetrated aerospace logistics:Military and defense contractors in the United States seek desiccant-integrated indicator systems for extended-duration equipment storage, representing a high-margin specialty channel.
- Japan's circular economy compliance:METI guidelines for adhesive label backing recovery in cross-border electronics shipments create first-mover advantage for suppliers with recyclable substrate formats.
- Capacitive-RFID convergence:Hybrid smart tags combining passive humidity sensing with active wireless transmission enable real-time supply chain visibility without separate data logger hardware.
Industry Challenges
- Calibration technician scarcity:Smart indicator production requires specialized workforce competencies in thin-film sensor calibration and RFID antenna patterning that outpace vocational training pipeline output.
- FDA 21 CFR Part 11 validation timelines:Electronic record-compatible indicator formats require extensive software validation documentation that extends product commercialization cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moisture Detection Stickers Market |
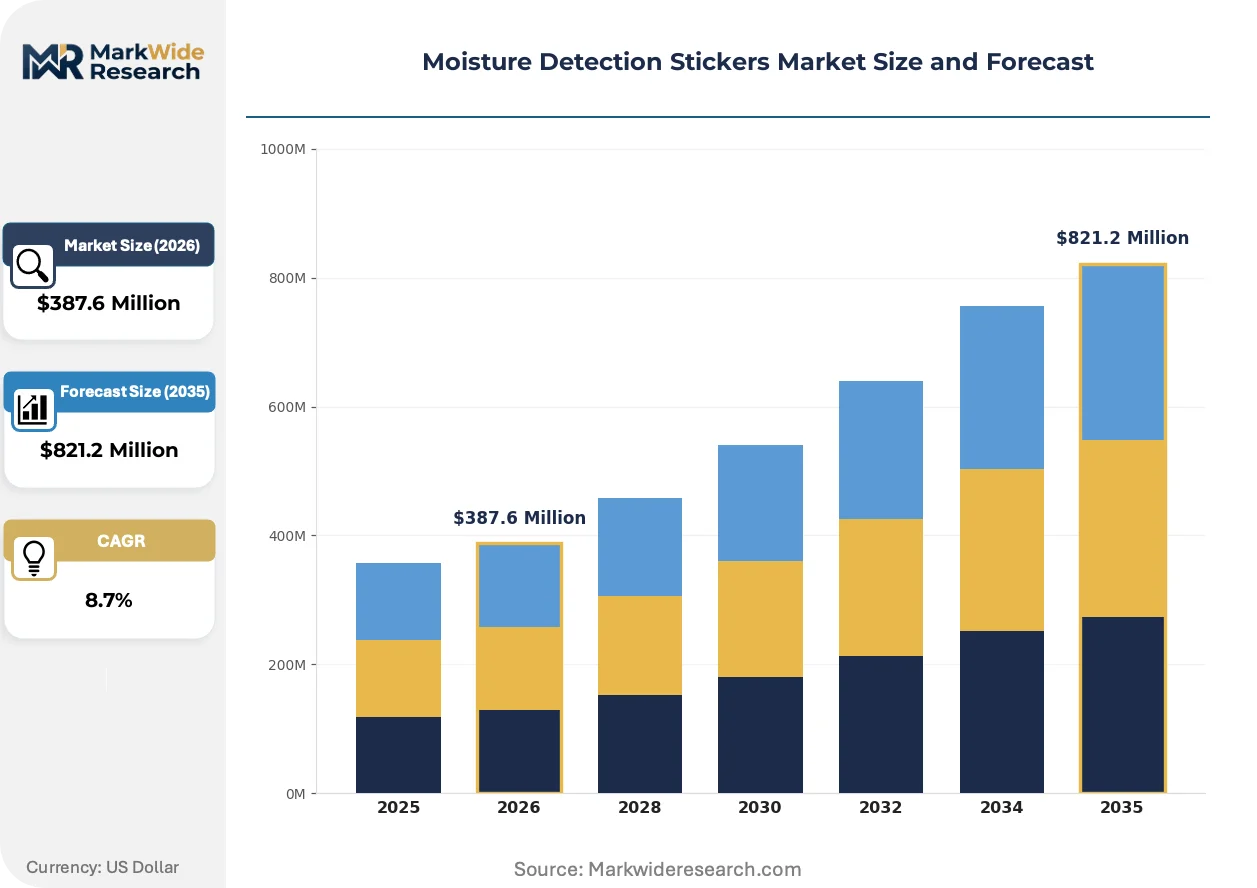
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printed Stickers, Flexible Sensors, Adhesive Labels, Smart Tags Application: Packaging, Clothing, Electronics, Building Materials End User: Manufacturers, Retailers, Consumers, Logistics Providers Technology: Colorimetric, Optical, Capacitive, RFID |
| Companies Covered | AMETEK MOCON Inc., Labthink Instruments Co., Ltd., Desiccare Inc., TexTest AG, 3M, Avery Dennison Corporation, Brady Corporation, Multisorb Technologies Inc., TQC Sheen BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moisture Detection Stickers Market Strategic Shifts
Digital traceability mandates are compressing the viable product lifecycle for purely colorimetric indicators while opening premium positioning for connected sensing formats that automate compliance documentation.
Printed capacitive humidity sensors are collapsing the cost barrier between passive visual indicators and active electronic monitoring. Pharmaceutical contract packagers in Germany and Switzerland are piloting these formats for high-value biologics shipments. The technology is collapsing the traditional tiered market structure by enabling mid-cost real-time monitoring at price points competitive with conventional data loggers.
REACH authorization requirements for cobalt dichloride are accelerating reformulation investment across European converter operations. ECHA substance restrictions now classify common humidity indicator chemistries as substances of very high concern, forcing migration to copper-based and halogen-free organic alternatives. German medical device packaging clusters are absorbing reformulation costs to maintain CE-marked export eligibility.
Consolidated buying by pharmaceutical 3PLs is compressing supplier margins while elevating technical service requirements. Large cold chain logistics providers now mandate API-accessible humidity data streams for vendor qualification, displacing spot-buy relationships with multi-year performance contracts. This pattern is most visible in United States and German pharmaceutical distribution networks where serialization mandates have centralized procurement authority.
Moisture Detection Stickers Market Segmentation
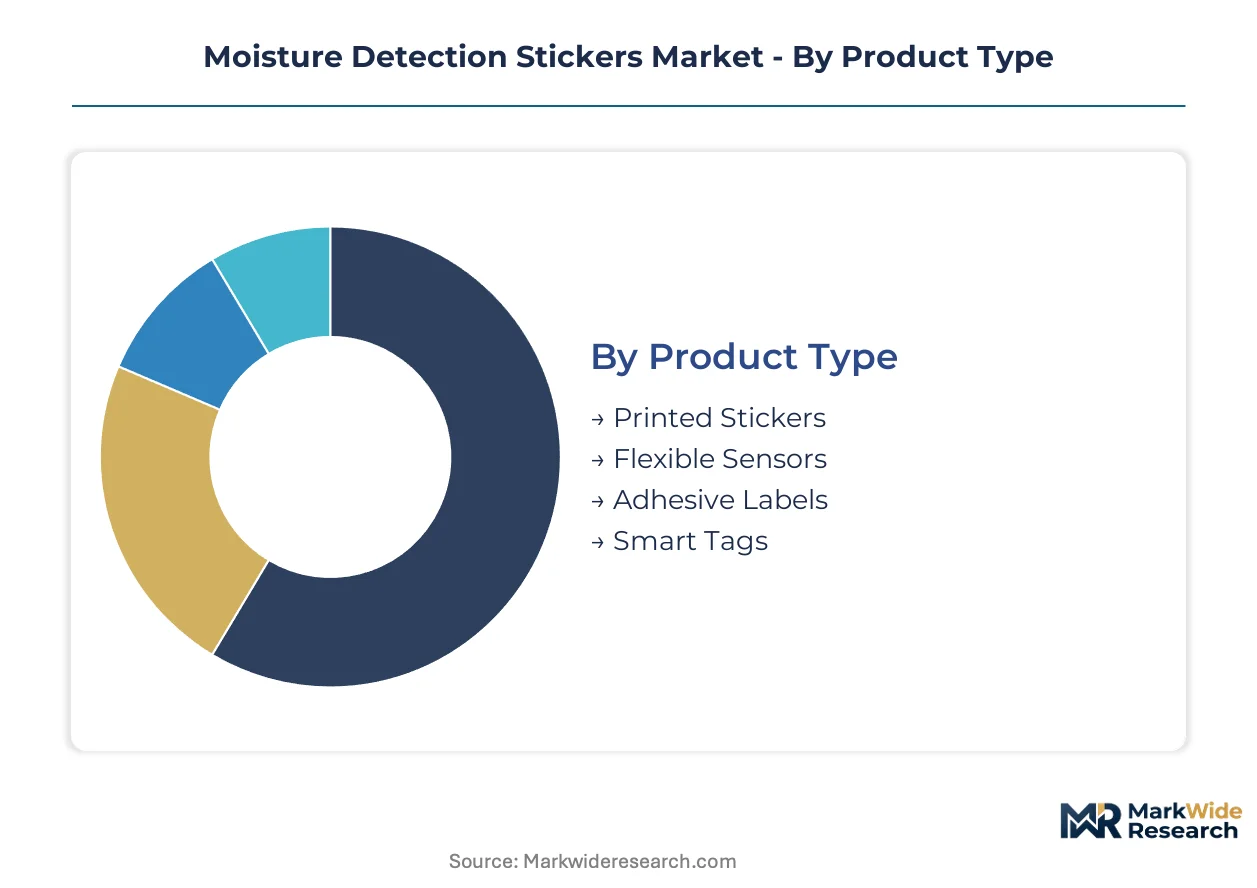
Moisture detection stickers serve divergent technical requirements across pharmaceutical serialization, military logistics, and consumer electronics protection. Segmentation reveals how cobalt chloride colorimetry competes with capacitive-RFID hybrids for procurement budgets governed by either cost minimization or digital traceability mandates.
Product Type:
Use cases span from single-use visual confirmation to continuous wireless monitoring in cold chain biologics.
- Printed Stickers:Cobalt chloride or copper chloride impregnated paper substrates deliver irreversible color transitions at defined relative humidity thresholds. Food packaging lines in Germany and pharmaceutical sterilization kit exporters in Bavaria specify these for cost-sensitive high-volume applications where visual pass-fail inspection suffices.
- Smart Tags:Hybrid formats embed capacitive sensors with RFID antennas for real-time data transmission to supply chain management platforms. Vaccine shippers and biologics 3PLs in the United States mandate these for electronic record compatibility under FDA 21 CFR Part 11, absorbing premium unit costs to maintain tender eligibility.
- Flexible Sensors:Thin-film polymer substrates with printed conductive traces enable conformal mounting on curved surfaces. Textile manufacturers pilot these for disposable wearable applications.
- Adhesive Labels:Pressure-sensitive backings with integrated desiccant pockets serve military aerospace contractors for extended-duration equipment storage.
Established volume favors printed stickers; emerging adoption favors smart tags.
Application:
Regulatory intensity varies sharply across segments, with pharmaceutical and defense procurement imposing validation documentation that commodity channels avoid.
- Packaging:Pharmaceutical cold chain serialization drives specification toward humidity-logging labels with API-accessible data streams. EU MDR traceability mandates force converters to abandon passive indicators for electronic record-compatible formats in medical device sterilization kits exported from Germany.
- Electronics:Cross-border shipments into Japan face METI circular economy guidelines requiring recoverable adhesive label backings. Manufacturers specify halogen-free colorimetric chemistries to preempt REACH authorization complications.
- Clothing:Wash-cycle durability constraints limit flexible humidity sensors to disposable wearable segments rather than reusable apparel.
- Building Materials:Construction moisture detection employs basic colorimetric strips for concrete curing monitoring and HVAC duct inspection.
Packaging commands the highest technical service requirements; electronics faces the steepest material compliance transition.
End User:
Procurement authority concentrates in logistics providers and manufacturers with centralized serialization mandates, fragmenting across spot-buy retailers and individual consumers.
- Logistics Providers:Large pharmaceutical 3PLs in the United States and Germany now mandate multi-year performance contracts with embedded humidity data APIs, displacing transactional supplier relationships.
- Manufacturers:Medical device and electronics OEMs specify integrated indicator systems during packaging design phase, locking in converter partnerships early.
- Retailers:Specialty packaging distributors stock printed stickers for small-batch food and consumer goods producers without internal validation capabilities.
- Consumers:Individual purchasers drive minimal volume through e-commerce channels for household storage and hobbyist electronics protection.
Logistics providers extract the steepest service terms; manufacturers offer the longest contract visibility.
Technology:
Chemistry reformulation and wireless integration are collapsing the traditional cost hierarchy between passive and active monitoring.
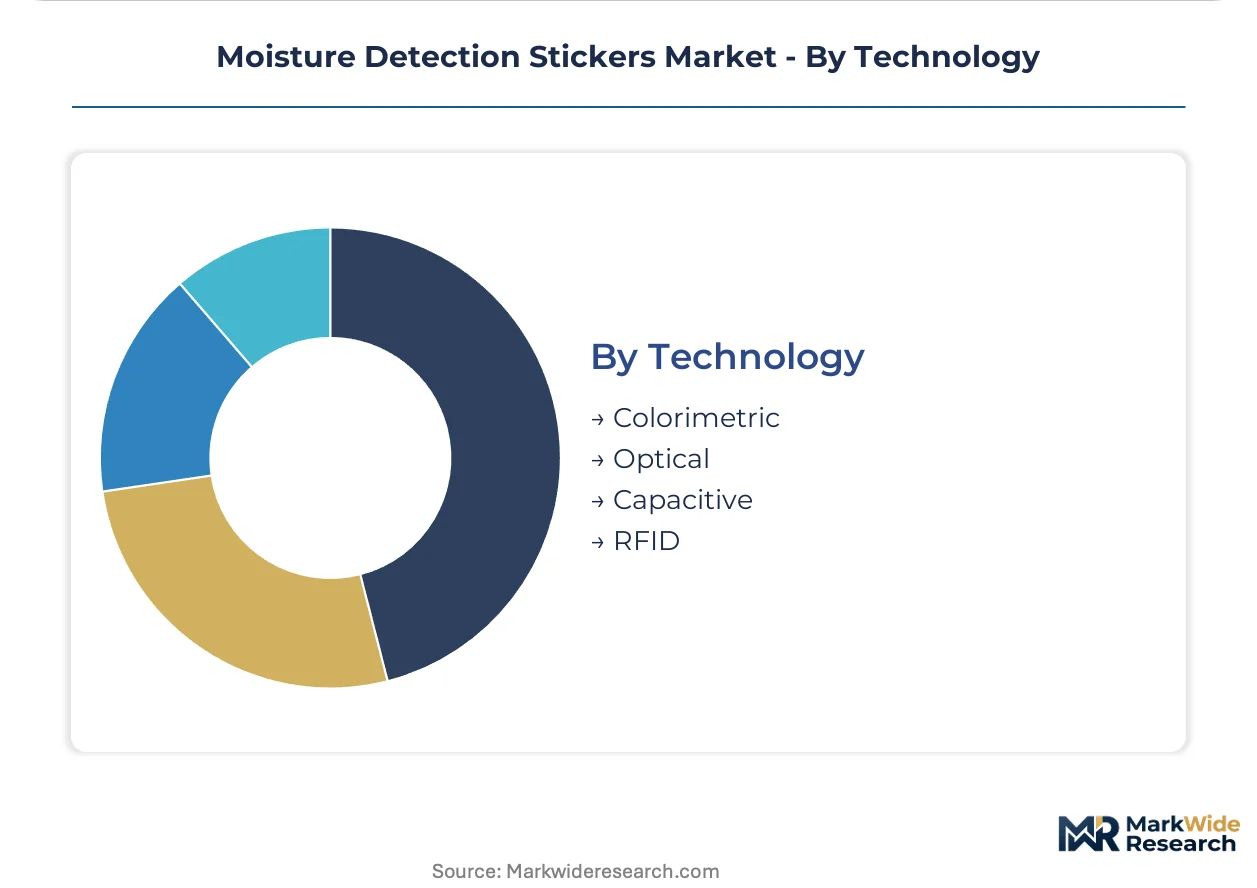
- Colorimetric:Copper chloride and organic dye alternatives displace cobalt formulations under ECHA substance restrictions. German converters absorb reformulation costs to maintain CE-marked export eligibility.
- Capacitive:Printed humidity sensors with polymer dielectric layers enable mid-cost real-time monitoring competitive with conventional data loggers. Swiss and German pharmaceutical contract packagers pilot these for high-value biologics.
- RFID:Passive UHF tags with integrated sensor front-ends eliminate separate data logger hardware for serialized cold chain tracking.
- Optical:Fluorescent indicator systems respond to moisture ingress with quantifiable spectral shifts for laboratory calibration applications.
Colorimetric retains the widest installed base; capacitive-RFID convergence gains share fastest in regulated pharmaceutical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's dominance in pharmaceutical cold chain logistics, with direct rail links to Bavarian medical device clusters and Rhine-Ruhr chemical processing zones. This infrastructure underwrites the country's position as the primary sourcing hub for serialized humidity-logging labels serving EU sterilization kit exports.
Germany
EU MDR traceability mandates force Bavarian packaging converters to abandon passive cobalt chloride indicators for electronic record-compatible formats. ECHA substance restrictions on cobalt compounds accelerate reformulation toward copper-based alternatives. Medical device sterilization kit exporters in the Munich-Stuttgart corridor absorb these compliance costs to maintain CE-marked access across European markets.
United States
FDA 21 CFR Part 11 validation requirements drive pharmaceutical 3PLs toward API-accessible humidity data streams for serialized cold chain tracking. Military and defense contractors seek desiccant-integrated indicator systems for extended-duration aerospace equipment storage. The Boston-Cambridge biotech corridor and New Jersey pharmaceutical distribution hubs concentrate demand for smart tag integration.
Japan
METI circular economy guidelines mandate recoverable adhesive label backings for cross-border electronics shipments entering domestic ports. Manufacturers specify halogen-free colorimetric chemistries to preempt REACH authorization complications in re-export markets. The Kanto industrial belt around Tokyo anchors production of recyclable substrate formats serving regional electronics OEMs.
Switzerland
Swissmedic serialization rules for high-value biologics shipments push contract packagers toward capacitive-RFID hybrid formats. Swiss pharmaceutical clusters in Basel and the greater Zurich region pilot printed humidity sensors at price points competitive with conventional data loggers. These facilities serve as technical validation gateways for formats later deployed across German and Austrian distribution networks.
China
NMPA traceability requirements for imported pharmaceuticals create compliance pull for electronic record-compatible indicator systems at domestic cold chain hubs. GB standards for packaging materials drive reformulation investment in copper chloride and organic dye alternatives. The Yangtze River Delta manufacturing zone concentrates specialty adhesive substrate production for humidity-sensitive coatings serving regional converter operations.
Moisture Detection Stickers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate chemistry and sensor calibration. The vendor base stratifies across three tiers: multinational diversified materials conglomerates with captive label divisions, mid-cap instrumentation-to-consumable bundlers, and niche desiccant-integrated system specialists. Consolidation pressure concentrates in the middle tier as pharmaceutical 3PL procurement centralization favors multi-year performance contracts over spot-buy relationships. Strategic moves center on backward integration into specialty adhesive substrates and technology licensing partnerships for capacitive-RFID convergence.
Among instrumentation heritage specialists, AMETEK MOCON Inc. and Labthink Instruments Co., Ltd. occupy positions bridging permeation testing equipment into consumable validation programs. Desiccare Inc. exemplifies the desiccant-integrated indicator archetype serving military and aerospace logistics channels. These three companies represent distinct competitive vectors: permeation testing lineage, instrumentation-to-consumable bundling, and specialty integrated systems for extended-duration storage applications.
| Leading Market Players |
|---|
| AMETEK MOCON Inc. |
| Labthink Instruments Co., Ltd. |
| Desiccare Inc. |
| TexTest AG |
| 3M |
| Avery Dennison Corporation |
| Brady Corporation |
| Multisorb Technologies Inc. |
| TQC Sheen BV |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in East Asian specialty adhesive substrate production is pressuring converters toward volume-commitment contracts that lock in pricing floors while securing cobalt-free chemistry feedstock access for EU MDR compliance.
Pricing Analysis
Volume-discount tiering separates pharmaceutical serialization contracts from commodity food packaging spot buys. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and API-accessible data integration. Pricing pressure stems from consolidated pharmaceutical 3PL procurement centralization. Food packaging lines exhibit highest price sensitivity; biologics shippers absorb premium smart tag costs for FDA 21 CFR Part 11 eligibility.
Supply Chain Analysis
Export-control regimes on capacitive sensor fabrication equipment limit technology transfer to Chinese converter operations. Specialty adhesive substrates draw from Germany, Japan, and South Korea; cobalt chloride alternatives source from Chinese and Indian chemical processors. Single-source vulnerability concentrates in halogen-free organic dye formulations. Distribution runs through pharmaceutical 3PL networks and military aerospace contractors rather than spot-buy retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EU MDR, and METI jurisdictions is fragmenting procurement specifications into incompatible technical standards, creating niche openings for specialized compliance-focused suppliers.
For Market Incumbents: Pre-empt cobalt compound substitution by securing copper chloride and organic dye supply agreements before ECHA authorization deadlines tighten. Backward integration into specialty adhesive substrate production defends margin position against East Asian input volatility. Certification investment for FDA 21 CFR Part 11 software validation extends commercialization timelines but locks out commodity competitors.
For New Entrants and Emerging Players: Mid-market capacitive-RFID hybrid formats for Swiss and German pharmaceutical contract packagers represent the most penetrable entry point. Military aerospace desiccant-integrated systems offer second white-space target with lower regulatory validation barriers. Go-to-market through specialty packaging distributors bypasses direct 3PL procurement consolidation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among instrumentation-to-consumable bundlers with captive validation service relationships. Long-term viability favors targets with FDA and EU MDR electronic record compatibility already deployed. Watch for ECHA substance restriction enforcement acceleration as inflection signal for reformulation cost absorption winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Adhesive Substrates | Captive cobalt-free chemistry supply secures EU MDR compliance cost control. |
| Capacitive-RFID Hybrid Product Launch | Printed sensor convergence collapses price barrier against conventional data loggers. |
| Regulatory Certification Pathway Investment | FDA 21 CFR Part 11 validation documentation extends competitive moat duration. |
| Long-term Supply Agreement with Pharmaceutical 3PLs | Multi-year performance contracts displace spot-buy relationships in cold chain. |
| Joint Venture for Halogen-free Chemistry Scale-up | Copper chloride and organic dye partnerships preempt REACH authorization disruption. |
Study Parameters
Desk research of ECHA substance restriction filings, FDA 510(k) and 21 CFR Part 11 guidance documents, and METI circular economy guidelines preceded structured interviews with pharmaceutical packaging converters, cold chain logistics procurement directors, and specialty adhesive substrate chemists. Secondary validation drew from customs trade data, SEC filings of diversified materials conglomerates, and Swissmedic serialization rulemakings. Bottom-up unit economics triangulated against top-down market sizing across product type and application segments.
Assumptions held regulatory enforcement timelines and cobalt compound authorization schedules fixed while varying pharmaceutical serialization adoption rates and smart tag cost decline curves across the analysis window. Segmentation dimensions modeled included product format, application vertical, end-user procurement archetype, and chemistry technology platform. CAGRs derived from installed base replacement cycles and penetration rate assumptions for electronic record-compatible formats. Industry-specific inputs included EU MDR sterilization kit export volumes and FDA biologics cold chain shipment data.
Practitioners should monitor ECHA authorization enforcement acceleration and pharmaceutical 3PL procurement centralization pace for early signals of competitive displacement. Forecasts reflect assumptions about regulatory compliance cost absorption capacity and smart tag price convergence timelines. Material shifts in REACH substance restriction scope or FDA validation requirement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
Spark Detector Market