
 CVD Sic Ring Market | 2026-2036
CVD Sic Ring Market Size, Share, and Industry Trends Forecast 2026-2036
CVD Sic Ring Market Insights
The gap between single-crystal and polycrystalline tiers is repositioning procurement strategies across the CVD SiC ring supply base. Tokai Carbon leverages its synthetic graphite heritage to anchor high-purity precursor supply for semiconductor OEMs. Morgan Technical Ceramics competes through specialized CVD reactor expertise in aerospace-qualified ring geometries. CoorsTek sustains broad manufacturing scale across both optical and electronics end uses.
A CVD SiC ring denotes a chemically vapor-deposited silicon carbide structural component, typically achieving purity above 99.9995% with density approaching 3.21 g/cm³, engineered to withstand thermal cycling above 1600°C in plasma etch and epitaxy chambers. Single crystal rings command premium positioning in EUV lithography wafer handling where defect tolerance approaches zero. Polycrystalline variants occupy faster-growing volume pools in mature node semiconductor etch tools. Composite formulations differentiate through tailored thermal expansion matching to specific chamber architectures.
Japan's METI and PMDA frameworks govern material certification for semiconductor equipment imports, while China's MIIT and GB standards enforce dual carbon-aligned manufacturing disclosures on domestic CVD SiC suppliers. REACH and RoHS in Europe restrict fluorinated precursor chemistries, reshaping qualified supplier lists for rings bound for ASML ecosystem partners. Stakeholders must monitor how divergent carbon accounting rules across these jurisdictions fragment qualification timelines and alter total cost of ownership calculations.
Market Dynamics
The migration of semiconductor manufacturing toward sub-3nm EUV nodes is concentrating procurement power among foundries capable of qualifying ultra-high-purity single-crystal CVD SiC rings, compressing supplier timelines and tightening material traceability requirements across East Asian fabrication clusters.
Growth Catalysts
- EUV Lithography Scaling:Wafer handling rings for ASML's next-generation scanners require zero-defect single-crystal SiC, pulling demand from Taiwan Semiconductor Manufacturing and Samsung Foundry expansion programs.
- Japan's METI Semiconductor Revival Framework:Domestic content mandates for critical equipment materials are redirecting procurement toward certified Japanese CVD SiC suppliers with PMDA-tracked quality systems.
- Plasma Etch Chamber Retrofits:Polycrystalline ring replacements in mature-node tools are accelerating as 200mm fab utilization rates climb across automotive and industrial chip segments.
Market Restraints
- Precursor Supply Concentration:Methyltrichlorosilane and high-purity graphite feedstock for CVD reactors originates from a limited supplier base in Japan and Germany, exposing ring manufacturers to input volatility.
- Single-Crystal Technical Ceiling:Defect-free boule growth beyond 150mm diameter remains unachievable at commercial scale, constraining ring geometries for next-generation 450mm wafer handling systems.
- REACH Fluorinated Chemistry Restrictions:ECHA classification of certain CVD process byproducts as substances of very high concern is extending qualification timelines for European-bound ring shipments by 8-14 months.
Strategic Opportunities
- India's Semiconductor PLI Scheme:Domestic fab construction at Dholera and Assam creates first-mover advantage for CVD SiC ring suppliers establishing local precursor synthesis and deposition capabilities.
- SiC-Metal Matrix Composite Formulations:Tailored thermal expansion coefficients through aluminum-silicon carbide hybrid rings are opening retrofit opportunities in legacy plasma etch chambers with mismatched chamber materials.
- Carbon Accounting Differentiation:China's MIIT dual carbon disclosure requirements for domestic suppliers create competitive wedge for foreign producers with verified low-carbon CVD reactor energy sourcing.
Industry Challenges
- Plasma Etch Process Engineering Talent:The intersection of ceramic materials science and semiconductor chamber physics commands premium compensation, constraining supplier technical service expansion.
- ASML Ecosystem Certification Timelines:Qualification for EUV scanner wafer handling components requires 18-36 months of thermal cycling validation, locking working capital and technical resources.
- Legacy Tool Integration Complexity:Polycrystalline ring geometries must interface with 15-20 year old chamber designs from Applied Materials and Lam Research without triggering particle generation from thermal mismatch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CVD Sic Ring Market |
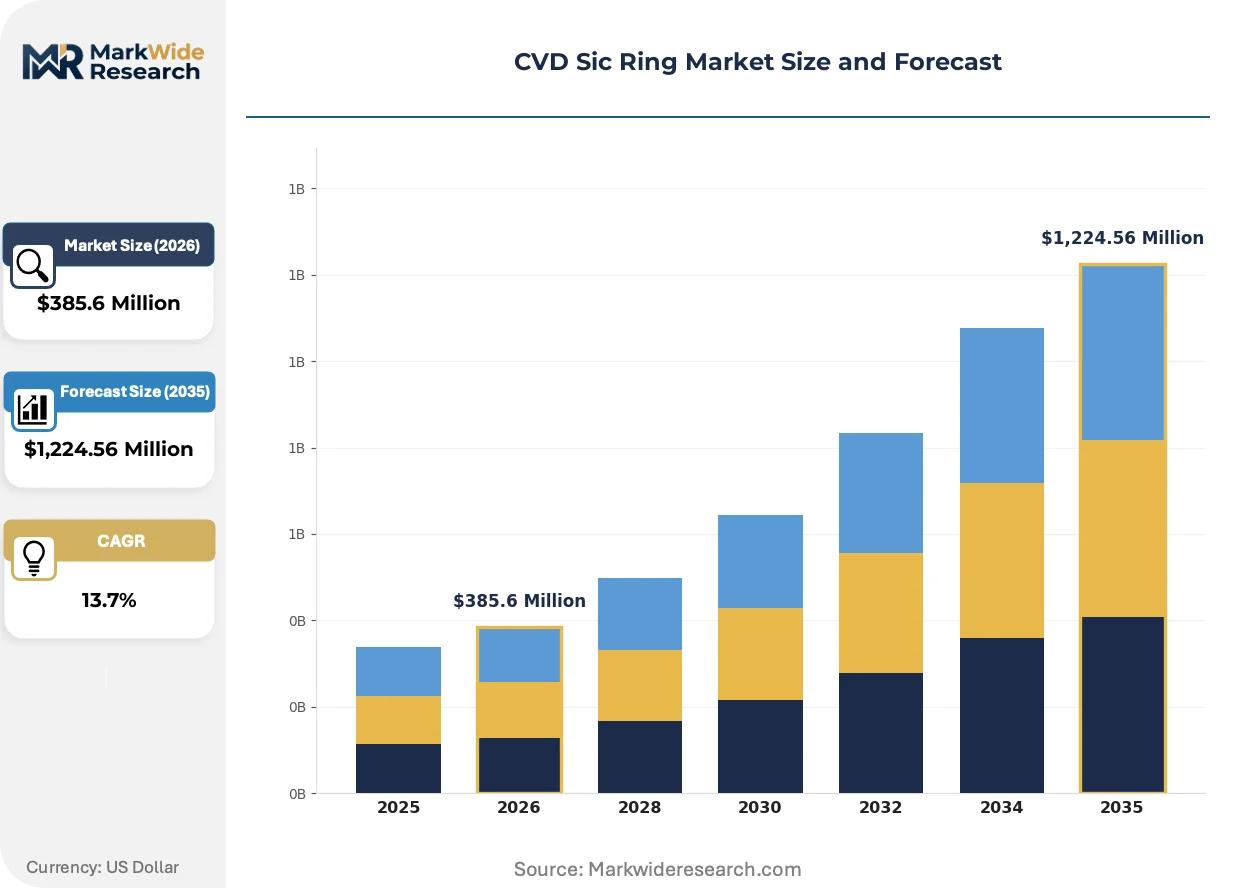
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,224.56 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Polycrystalline, Composite, Others Application: Semiconductors, Optical Devices, Aerospace, Automotive End User: Manufacturers, Research Institutions, Aerospace Companies, Electronic Firms Material: Silicon Carbide, Graphene, Diamond, Others |
| Companies Covered | Tokai Carbon, Ferrotec Material Technologies, Morgan Technical Ceramics, CoorsTek, Top Seiko, Max Luck Technology, Kallex, Worldex, SKC Solmics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CVD Sic Ring Market Trends and Innovations
Process control technologies and regulatory disclosure frameworks are compressing supplier qualification windows while fragmenting procurement authority between central engineering and regional sustainability compliance functions.
Atomic layer deposition surface finishing is converging with conventional CVD SiC ring substrates to eliminate subsurface porosity that traps fluorinated etch byproducts. Samsung Foundry and Intel's process engineering teams are piloting these hybrid rings in 3nm high-aspect-ratio etch chambers. The structural consequence is converging with premium pricing tiers as single-crystal-equivalent performance becomes achievable at polycrystalline cost structures.
China's MIIT GB standards for carbon footprint disclosure in semiconductor materials are forcing CVD reactor operators to document energy sourcing and precursor supply chain emissions. Domestic suppliers without verified low-carbon electricity contracts face exclusion from state-backed fab procurement pools. Polycrystalline ring producers in Jiangsu and Zhejiang provinces are most affected, accelerating migration to grid-connected renewable power purchase agreements.
Foundry technical buyers are consolidating ring procurement under centralized advanced materials groups rather than distributed chamber engineering teams. This displaces incumbent regional distributors in Taiwan and South Korea with direct supplier relationships and long-term supply agreements indexed to purity certification tiers. The shift is most visible in Hsinchu Science Park and Pyeongtaek semiconductor clusters where TSMC and Samsung have established dedicated CVD ceramic sourcing desks.
CVD Sic Ring Market Segmentation
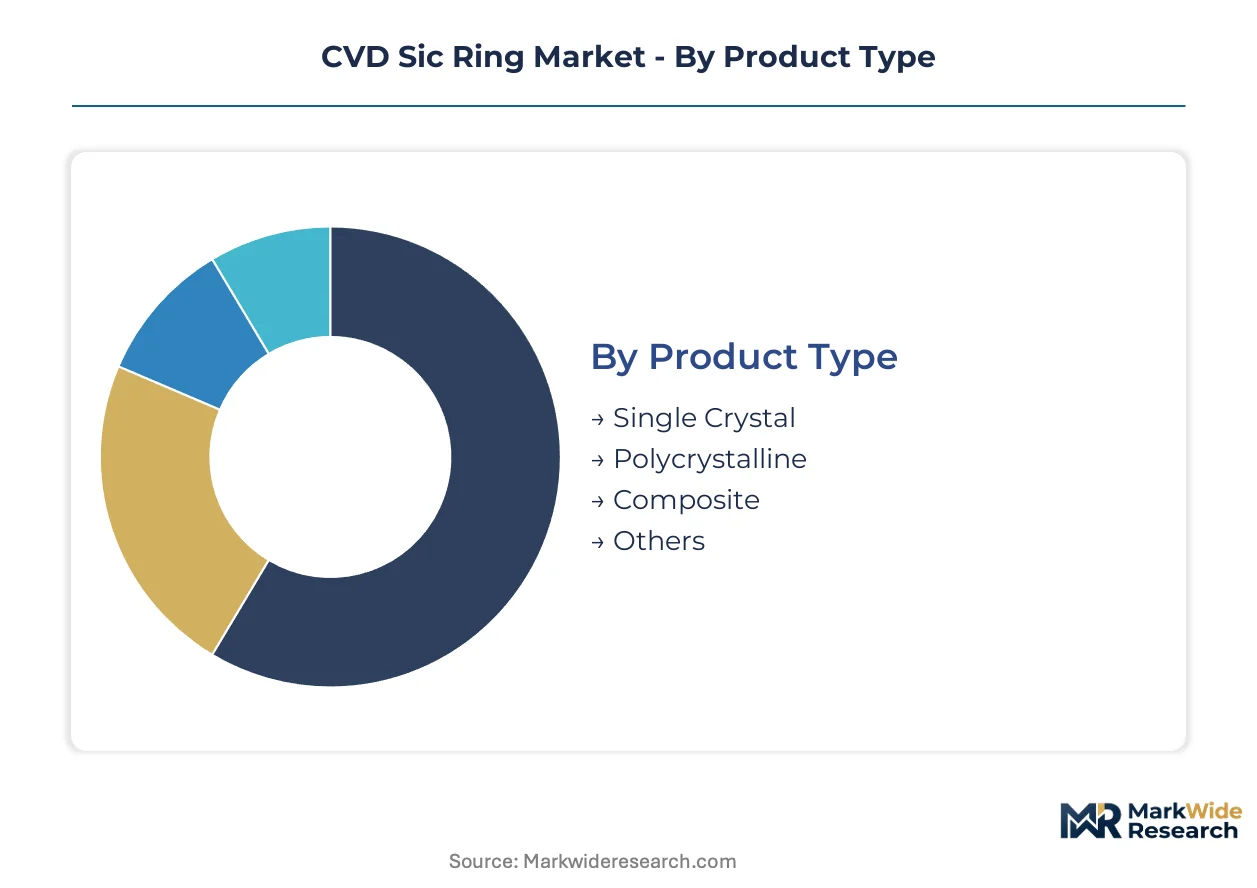
Ring geometry and purity specifications fragment procurement authority across semiconductor fabs, optical foundries, and aerospace integrators. Each segment tier commands distinct qualification timelines, precursor sourcing requirements, and thermal cycling validation protocols that reshape supplier competitive positioning.
Product Type:
Supply concentration in methyltrichlorosilane refining and CVD reactor capacity locks tiered availability across purity grades.
- Single Crystal:Defect-free boules grown above 99.9995% purity serve EUV lithography wafer handling where thermal expansion tolerance approaches zero. Taiwan Semiconductor Manufacturing and Samsung Foundry concentrate procurement for sub-3nm node expansion, compressing supplier qualification windows to 18-36 months.
- Polycrystalline:Grain-boundary structures achieve 99.995% purity at 40-60% lower unit cost, dominating plasma etch chamber retrofits in mature-node 200mm fabs. Automotive chip demand from Bosch and Infineon is pulling volume through Jiangsu and Zhejiang deposition facilities.
- Composite:SiC-aluminum matrix hybrids tailor thermal expansion coefficients to legacy chamber architectures from Applied Materials and Lam Research.
- Others:Experimental graded-density rings for specialized epitaxy applications remain confined to R&D procurement channels.
Polycrystalline rings absorb the bulk of installed capacity; single crystal variants are expanding most quickly.
Application:
End-use diversification spreads technical risk across cyclical semiconductor capital expenditure and long-cycle aerospace programs.
- Semiconductors:Plasma etch and epitaxy chambers consume 70-plus percent of ring volume, with EUV scanner wafer handling commanding premium pricing. ASML's ecosystem qualification requirements filter supplier access to Taiwan, South Korea, and Intel's Arizona and Oregon fabs.
- Optical Devices:Mirror substrates for space-based telescopes and laser systems require isotropic thermal properties. NASA and ESA procurement specifications favor polycrystalline grades with verified cryogenic performance.
- Aerospace:Re-entry vehicle nose caps and hypersonic leading edges exploit SiC's oxidation resistance above 1600°C. Lockheed Martin and Raytheon programs source through Morgan Technical Ceramics' aerospace-qualified reactor lines.
- Automotive:EV power module test fixtures and battery thermal management prototypes represent emerging demand from Tesla and BYD engineering centers.
Semiconductor applications anchor supplier revenue stability; optical devices are climbing the fastest as space economy capital deployment accelerates.
End User:
Procurement sophistication diverges sharply between volume manufacturers and specification-driven research institutions.
- Manufacturers:Foundries and OEMs impose statistical process control requirements that favor suppliers with ISO 9001 and IATF 16949 certification. Direct long-term agreements are displacing regional distributors in Hsinchu and Pyeongtaek clusters.
- Research Institutions:National laboratories and university consortia prioritize geometric flexibility and rapid prototyping over purity certification. Oak Ridge and Fraunhofer programs source small-batch rings through specialized ceramic job shops.
- Aerospace Companies:Defense primes require AS9100 traceability and ITAR compliance that domesticates supply chains within NATO-aligned deposition facilities.
- Electronic Firms:LED and compound semiconductor device makers source polycrystalline rings for MOCVD reactor retrofits, with Chinese domestic fab construction driving regional procurement consolidation.
Manufacturers lock in the majority of multi-year supply agreements; research institutions are gaining share fastest as government-funded advanced materials programs expand.
Material:
Precursor chemistry availability and deposition kinetics constrain viable substrate alternatives to silicon carbide derivatives.
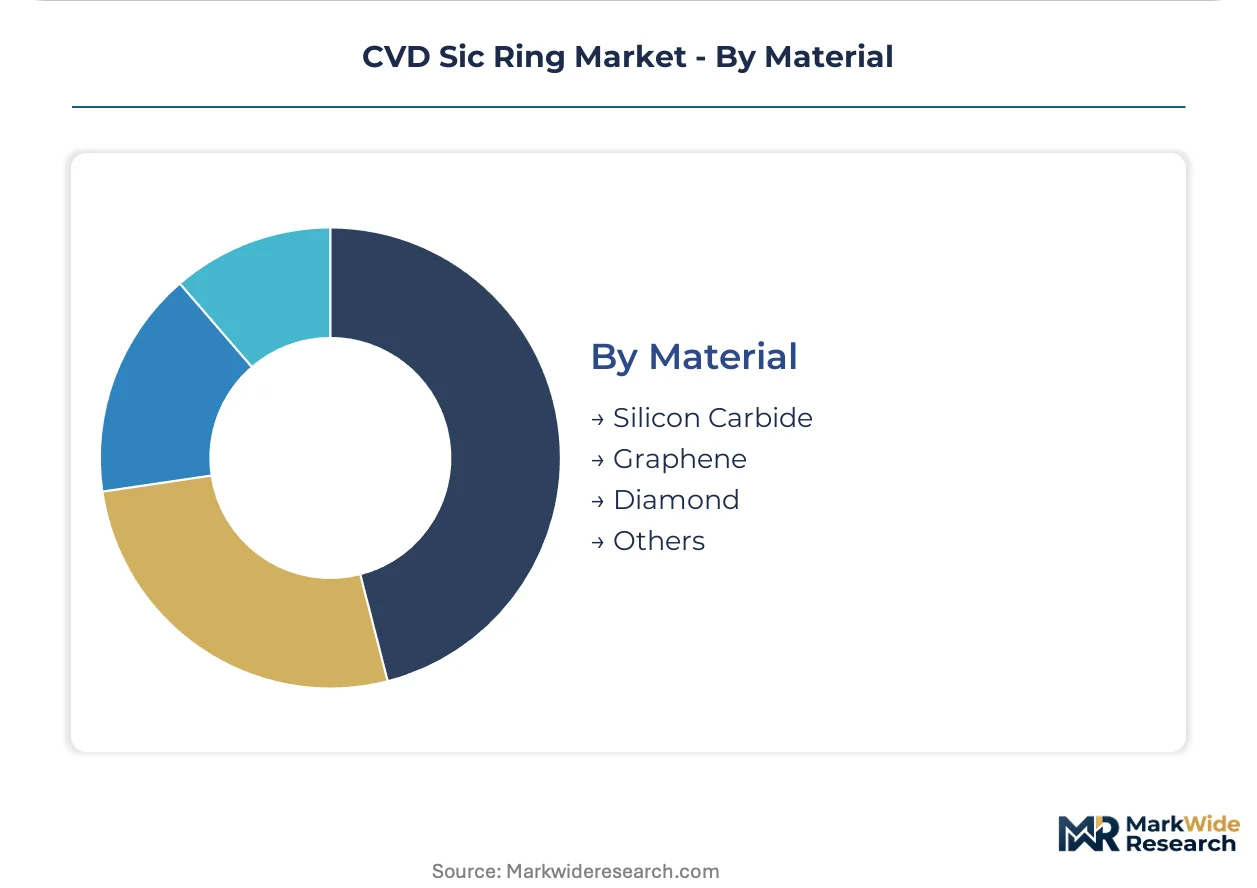
- Silicon Carbide:Dominant chemistry achieving theoretical density near 3.21 g/cm³ through halide CVD processes. Japan's Tokai Carbon and Germany's SGL Carbon anchor high-purity graphite precursor supply.
- Graphene:Monolayer coatings on SiC substrates reduce surface roughness for atomic layer deposition compatibility. Samsung Foundry pilots hybrid rings in 3nm high-aspect-ratio etch chambers.
- Diamond:CVD diamond coatings for extreme wear applications in abrasive slurry processing remain niche due to deposition rate limitations.
- Others:Boron carbide and aluminum nitride experimental formulations occupy pre-commercial evaluation at DOE and EU Horizon programs.
Silicon carbide claims overwhelming installed base dominance; graphene-enhanced variants are expanding most quickly as surface engineering converges with conventional CVD substrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park concentrates the most intensive procurement activity for CVD SiC rings, with Taiwan Semiconductor Manufacturing and United Microelectronics Corporation driving qualification timelines for sub-3nm EUV wafer handling components. Foundry expansion programs across East Asian fabrication clusters are reshaping supplier geographic priorities.
Taiwan
TSMC's Fab 18 and Fab 20 expansions in Tainan and Taichung are pulling single-crystal ring volumes for ASML EUV scanner integration. The National Development Council's chip industry stimulus allocates capital equipment subsidies contingent on domestic content thresholds. Kaohsiung's emerging semiconductor materials park is attracting CVD precursor suppliers seeking proximity to southern Taiwan fabrication corridors.
South Korea
Samsung Foundry's Pyeongtaek complex and SK Hynix's Yongin cluster are qualifying ultra-high-purity rings for 3nm GAA transistor production. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative funnels tax credits toward materials localization. Seongnam's Pangyo technology hub houses process engineering teams conducting thermal cycling validation for next-generation chamber architectures.
China
SMIC's Beijing and Shanghai fabs are expanding polycrystalline ring procurement for mature-node etch tool retrofits. MIIT's dual carbon disclosure mandates require Jiangsu and Zhejiang deposition facilities to document renewable energy sourcing for state-backed procurement eligibility. Hefei's memory manufacturing corridor is emerging as a secondary demand center for 200mm fab equipment materials.
Japan
Tokai Carbon's synthetic graphite heritage anchors precursor supply for domestic and export CVD reactor operations. METI's semiconductor equipment materials revival framework imposes PMDA-tracked quality systems on certified suppliers. Kyushu's silicon carbide substrate cluster in Kumamoto is extending into ring finishing capabilities for proximity to Sony and Toshiba device fabs.
United States
Intel's Arizona and Oregon fabs are qualifying single-crystal rings for EUV wafer handling in advanced packaging integration. The CHIPS and Science Act's domestic content requirements are redirecting procurement toward North American deposition facilities with ITAR-compliant traceability. Albany's NY CREATES complex hosts process development partnerships evaluating next-generation ring geometries.
CVD Sic Ring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity certification tiers, with single-crystal qualification status separating pricing power from volume-driven polycrystalline competition. The supplier base concentrates around three strategic archetypes: synthetic graphite heritage players leveraging upstream precursor control, aerospace-qualified ceramic specialists with thermal cycling validation infrastructure, and broad-scale manufacturers spanning optical and electronics end uses. Dominant competitive moves include backward integration into methyltrichlorosilane refining and geographic co-location with East Asian foundry clusters.
Within the heritage materials tier, Tokai Carbon exemplifies upstream-anchored positioning through its synthetic graphite precursor lineage. Morgan Technical Ceramics and CoorsTek occupy scale-driven positions across diversified end-use portfolios. Ferrotec Material Technologies represents the specialized reactor equipment vector, while SKC Solmics anchors Korean domestic supply capabilities. These named entities illustrate how supplier archetypes map to distinct qualification pathways and foundry procurement relationships.
| Leading Market Players |
|---|
| Tokai Carbon |
| Ferrotec Material Technologies |
| Morgan Technical Ceramics |
| CoorsTek |
| Top Seiko |
| Max Luck Technology |
| Kallex |
| Worldex |
| SKC Solmics |
| Others |
Pricing and Supply Chain Analysis
Methyltrichlorosilane feedstock costs cascade through CVD reactor operations into three distinct pricing tiers for semiconductor OEMs, with Japan and Germany precursor concentration amplifying volatility at the premium single-crystal segment.
Pricing Analysis
Yield-guaranteed throughput pricing anchors single-crystal ring contracts to wafer-per-hour performance metrics rather than unit costs. Three-tier pricing structure across premium, standard, and economy levels separates ASML-qualified single-crystal suppliers from polycrystalline volume producers and unqualified job shops. Cost compression in polycrystalline tiers is intensifying because Chinese domestic fab construction is pulling volume through Jiangsu deposition facilities. Foundry procurement desks at TSMC and Samsung exhibit lowest price sensitivity for EUV-qualified rings, while mature-node 200mm fab operators negotiate hardest on polycrystalline replacement cycles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Taiwan Semiconductor Manufacturing and Samsung Foundry, displacing regional distributors in Hsinchu and Pyeongtaek. Methyltrichlorosilane refining concentrates in Japan and Germany; high-purity graphite feedstock draws from Tokai Carbon's synthetic graphite heritage and SGL Carbon's European reactor lines. Single-source vulnerability in precursor supply exposes ring manufacturers to input disruption when METI or ECHA tighten chemical handling disclosures. Distribution runs through long-term offtake agreements indexed to purity certification tiers rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-crystal boule growth capacity constraints prop pricing power for qualified suppliers, as defect-free 150mm diameter achievement remains locked in technical development timelines.
For Market Incumbents: Hedge precursor supply exposure through captive methyltrichlorosilane refining investments or binding offtake agreements with Tokai Carbon and SGL Carbon. Secure ASML ecosystem qualification status before Samsung Foundry and Intel complete their 18-36 month validation windows, locking out second-tier competitors. Prioritize reactor capacity additions in Kaohsiung materials parks to satisfy TSMC's domestic content thresholds. For New Entrants and Emerging Players: The price-point gap between ASML-qualified single-crystal rings and unqualified polycrystalline alternatives creates entry space for mid-tier purity grades targeting Indian Semiconductor PLI scheme fabs at Dholera. Target polycrystalline ring retrofits in 200mm automotive chip fabs where Bosch and Infineon procurement teams prioritize delivery security over EUV-grade certification. Lead with carbon-accounting transparency to exploit MIIT dual carbon disclosure requirements excluding high-emission Chinese domestic suppliers. For Investors and Strategic Acquirers: SKC Solmics achieving PMDA-tracked quality certification is the leading indicator that Korean domestic supply capabilities are maturing toward premium-tier pricing capture. Acquisition target archetype: specialized CVD reactor operators with aerospace-qualified thermal cycling validation infrastructure but lacking semiconductor foundry relationships. Watch for Intel Arizona and Oregon fab qualification completions as inflection signals for North American supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Tokai Carbon's synthetic graphite heritage demonstrates upstream control over methyltrichlorosilane supply security. |
| ASML Ecosystem Qualification | TSMC and Samsung Foundry procurement desks filter supplier access through 18-36 month thermal cycling validation protocols. |
| Geographic Co-location with Foundry Clusters | Kaohsiung materials park proximity to southern Taiwan fabrication corridors satisfies National Development Council domestic content thresholds. |
| Carbon Accounting Certification | MIIT dual carbon disclosure requirements create competitive exclusion for Jiangsu deposition facilities without renewable power purchase agreements. |
| Composite Formulation Development | SiC-aluminum matrix hybrids from Morgan Technical Ceramics unlock retrofit opportunities in legacy Applied Materials chamber architectures. |
Research Methodology
Multi-period observation of ASML scanner installation rates, foundry capex disclosures, and CVD reactor capacity utilization anchored the trend analysis, supplemented by interviews with semiconductor process engineering directors, ceramic materials procurement leads at TSMC and Samsung, CVD reactor equipment specialists, and METI certification auditors. Secondary validation drew from SEC 10-K filings, MIIT GB standard publications, ECHA SVHC regulatory updates, and Japan PMDA quality system registrations. Bottom-up ring volume estimates from individual foundry expansion programs triangulated against top-down semiconductor capital equipment spending forecasts.
Input-output matrix framing mapped methyltrichlorosilane precursor availability through CVD reactor throughput assumptions into ring volume and value projections across the analysis window. Segmentation dimensions modeled include purity grade tier, ring geometry specification, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to qualified supplier capacity expansion timelines and foundry node migration patterns. Industry-specific forecast inputs incorporated EUV lithography scanner deployment schedules and plasma etch chamber retrofit cycles.
Inputs from foundry procurement desks and CVD equipment operators were available through the study window; gaps in Chinese domestic supplier carbon disclosure verification introduce uncertainty bands around MIIT compliance-driven demand shifts. Forecasts reflect assumptions on single-crystal boule diameter achievement timelines and REACH fluorinated chemistry restriction enforcement intensity. Periodic stress-testing of base assumptions against actual qualification completion rates and precursor supply disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Prism Coupler Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Silicon Focus Ring Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Ring Panel Filters Market
Optical Components
Faraday Rotator Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Optical Cross Connect Market
Optical Components
Optical Lens Edger Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Optical Component Tester Market
Optical Components
North America Photonic Sensors Market
Optical Components
Fiber Optic Plates (FOP) Market